
 Vitamin B Complex Market | 2026-2036
Vitamin B Complex Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin B Complex Market Analytics
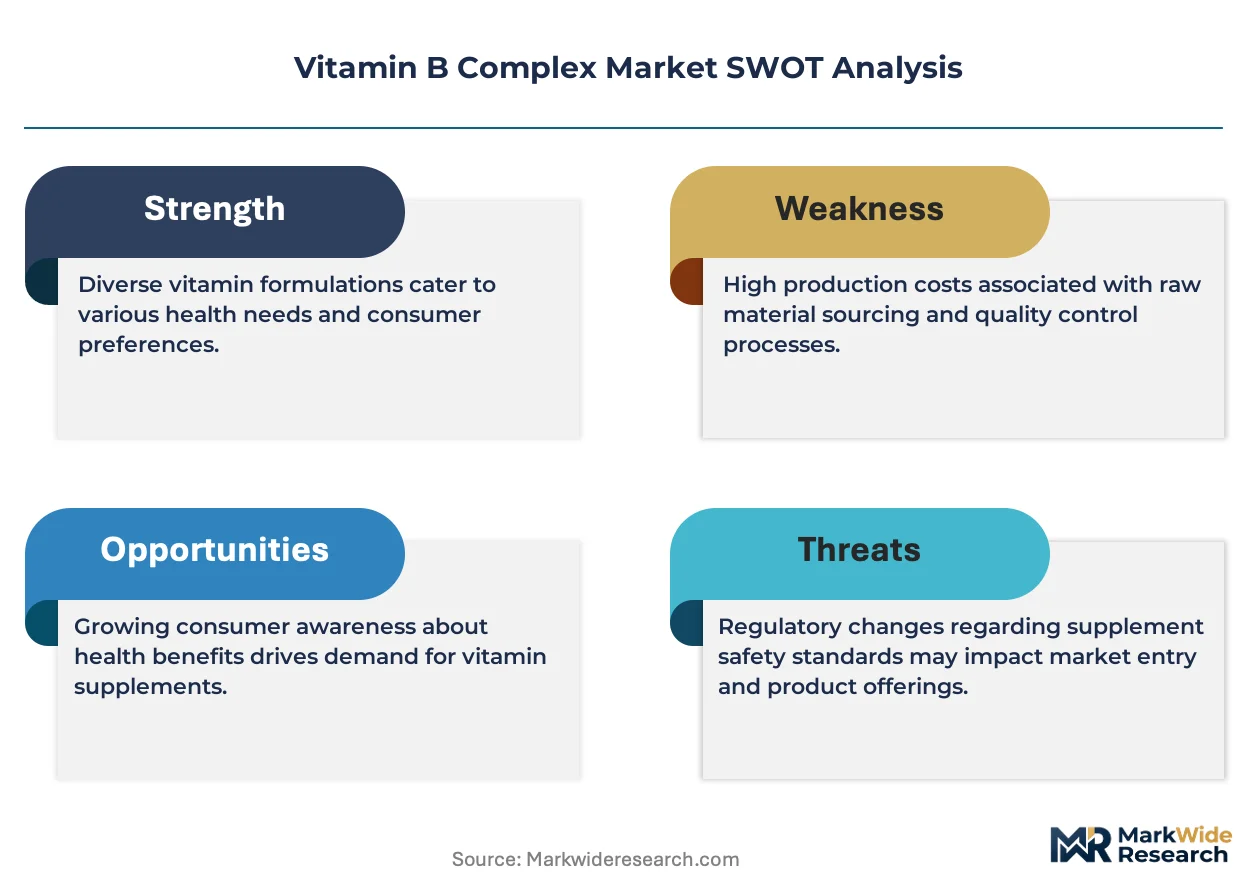
The EU Nutrition and Health Claims Regulation is expanding compliance burdens for B-complex supplement manufacturers entering European markets. DSM leverages its synthetic biology capabilities to secure cost-advantaged positions in fermented B-vitamin production. BASF anchors its competitive stance through backward integration into petrochemical precursors for thiamine and riboflavin synthesis. GSK competes primarily through pharmacy-channel dominance and clinician-trusted branding in therapeutic-dose segments.
Vitamin B Complex denotes a group of eight water-soluble vitamins—thiamine (B1), riboflavin (B2), niacin (B3), pantothenic acid (B5), pyridoxine (B6), biotin (B7), folate (B9), and cobalamin (B12)—typically manufactured through chemical synthesis or microbial fermentation and formulated at doses ranging from 1 mg to 100 mg per unit depending on target application. These compounds serve essential coenzyme functions in cellular energy metabolism, neurological maintenance, and erythropoiesis, with primary commercial demand flowing from dietary supplementation, food fortification, and clinical nutrition. Tablets occupy the largest share of product-type volume due to manufacturing scalability and consumer familiarity, while liquid formats attract pediatric and geriatric populations with swallowing difficulties. Online stores represent the fastest-expanding distribution channel, though drugstores retain margin concentration through pharmacist-assisted purchasing and insurance-adjacent reimbursement pathways.
The FDA's Current Good Manufacturing Practice regulations and the EPA's environmental discharge standards for fermentation facilities jointly shape production economics and facility siting decisions for B-complex manufacturers. India's CDSCO and BIS impose parallel purity and labeling requirements that govern export eligibility for contract manufacturers supplying multinational brands. Stakeholders must monitor evolving bioequivalence standards for generic B-vitamin entrants and the sustainability credentials of fermentation-based supply chains as procurement criteria harden across institutional buyers.
Market Dynamics
The Vitamin B Complex market faces structural pressure from the EU's Nutrition and Health Claims Regulation, which demands clinical substantiation for efficacy statements and is forcing manufacturers to reformulate labeling and marketing strategies across European distribution channels.
Growth Catalysts
- Preventive health consciousness:Dietary supplement users are expanding as consumers prioritize metabolic wellness and neurological maintenance without clinical intervention.
- EFSA substantiation pathways:The European Food Safety Authority's Article 13 health claims process, despite its rigor, creates competitive moats for firms that secure approved B-vitamin efficacy language.
- Fermentation technology maturation:Microbial production methods for cobalamin and riboflavin are achieving cost parity with petrochemical synthesis while delivering sustainability credentials.
Market Restraints
- Petrochemical feedstock volatility:Thiamine and riboflavin synthesis depends on acetonitrile and petrochemical precursors subject to energy-price fluctuations.
- Chinese supply concentration:A significant share of bulk B-vitamin active pharmaceutical ingredients originates from Zhejiang and Shandong provinces, creating single-geography exposure.
- Bioequivalence standard elevation:The FDA's tightening dissolution and purity requirements for generic B-complex entrants extend regulatory timelines and compliance costs.
Strategic Opportunities
- Pediatric liquid formulations:Swallowing difficulties in aging populations and children create unmet demand for non-tablet delivery systems with precise dosing.
- Indian export manufacturing:CDSCO-registered contract manufacturers in Hyderabad and Ahmedabad can supply multinational brands seeking geographic diversification of production.
- Direct-to-consumer channel expansion:Online subscription models bypass pharmacy margin extraction while capturing recurring revenue from wellness-focused cohorts.
Industry Challenges
- Fermentation scale-up expertise:Microbial B12 production requires specialized bioprocess engineers scarce outside established biotechnology clusters.
- Cross-jurisdictional label harmonization:Divergent FDA, EFSA, and BIS daily-value reference standards force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin B Complex Market |
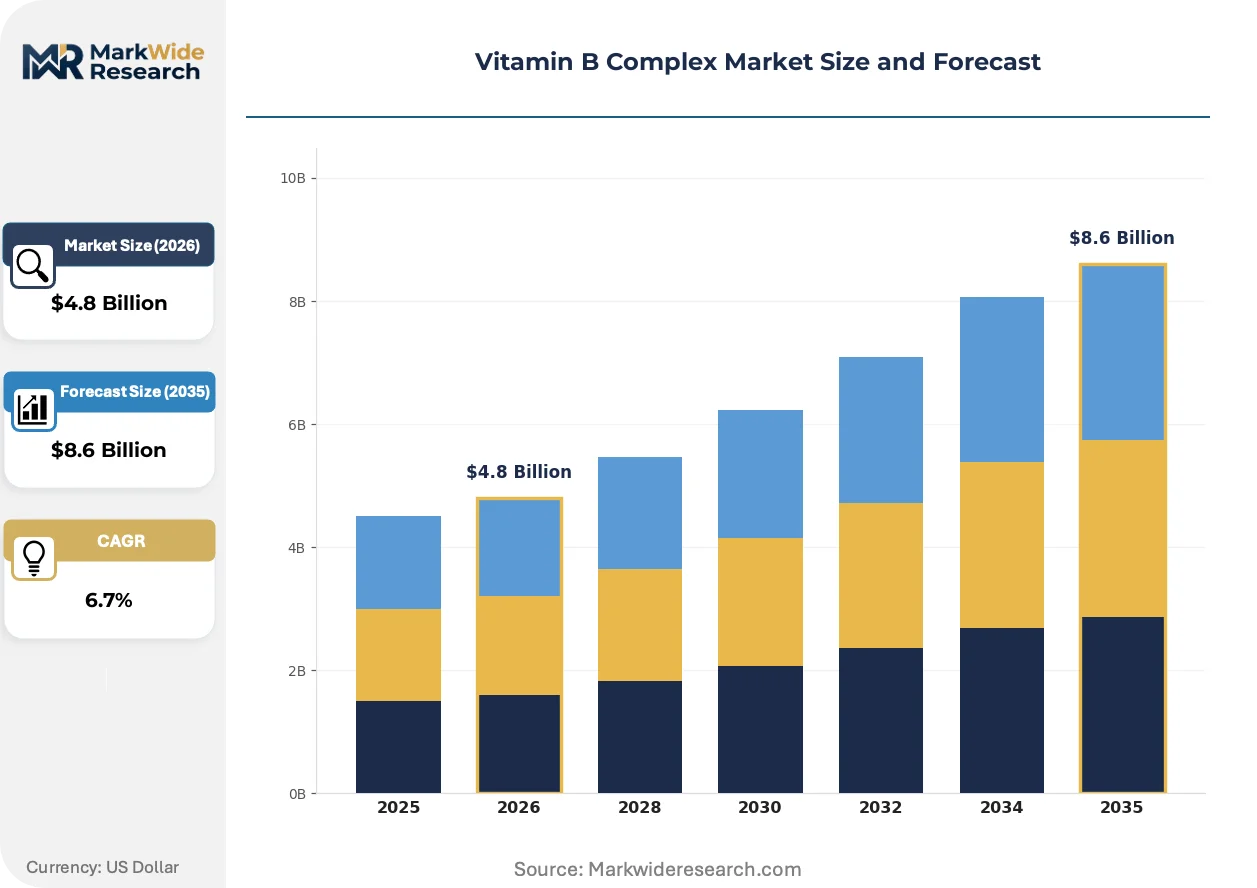
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Liquids End User: Health Enthusiasts, Athletes, Dietary Supplement Users, Patients Distribution Channel: Online Stores, Drugstores, Supermarkets, Health Food Shops Packaging Type: Bottles, Blister Packs, Sachets, Jars |
| Companies Covered | Nature's Bounty, GNC Holdings Inc, Amway (Nutrilite), DSM, Nestlé Health Science, Nature Made, GSK, BASF, Pfizer (Caltrate), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin B Complex Market Evolving Landscape
Synthetic biology and precision fermentation are rewriting production economics for cobalamin and riboflavin, while regulatory substantiation requirements and channel fragmentation are reshaping how manufacturers reach end-users.
Precision fermentation platforms are integrating CRISPR-engineered microbial strains to produce bioactive B-vitamin forms with higher purity than chemical synthesis. Contract manufacturers in Denmark and the Netherlands are adopting these systems to serve European brands seeking EFSA-aligned sustainability claims. This technology is integrating carbon-negative production credentials into procurement criteria for institutional buyers and pharmacy chains.
The EU's Corporate Sustainability Reporting Directive now mandates disclosure of fermentation facility emissions and water usage for B-vitamin suppliers above threshold revenue. This compels manufacturers to retrofit existing plants or relocate to jurisdictions with renewable energy access. Smaller supplement brands without compliance infrastructure are outsourcing formulation to full-service contract manufacturers with embedded CSRD reporting capabilities.
Subscription-based replenishment models are displacing pharmacy counter purchases among millennial and Generation X supplement users. Direct-to-consumer brands capture recurring revenue through personalized dosing algorithms and bundled micronutrient protocols. This shift concentrates most visibly in the United States, where telehealth-integrated wellness platforms prescribe therapeutic-dose B-complex regimens with home delivery fulfillment.
Vitamin B Complex Market Segmentation
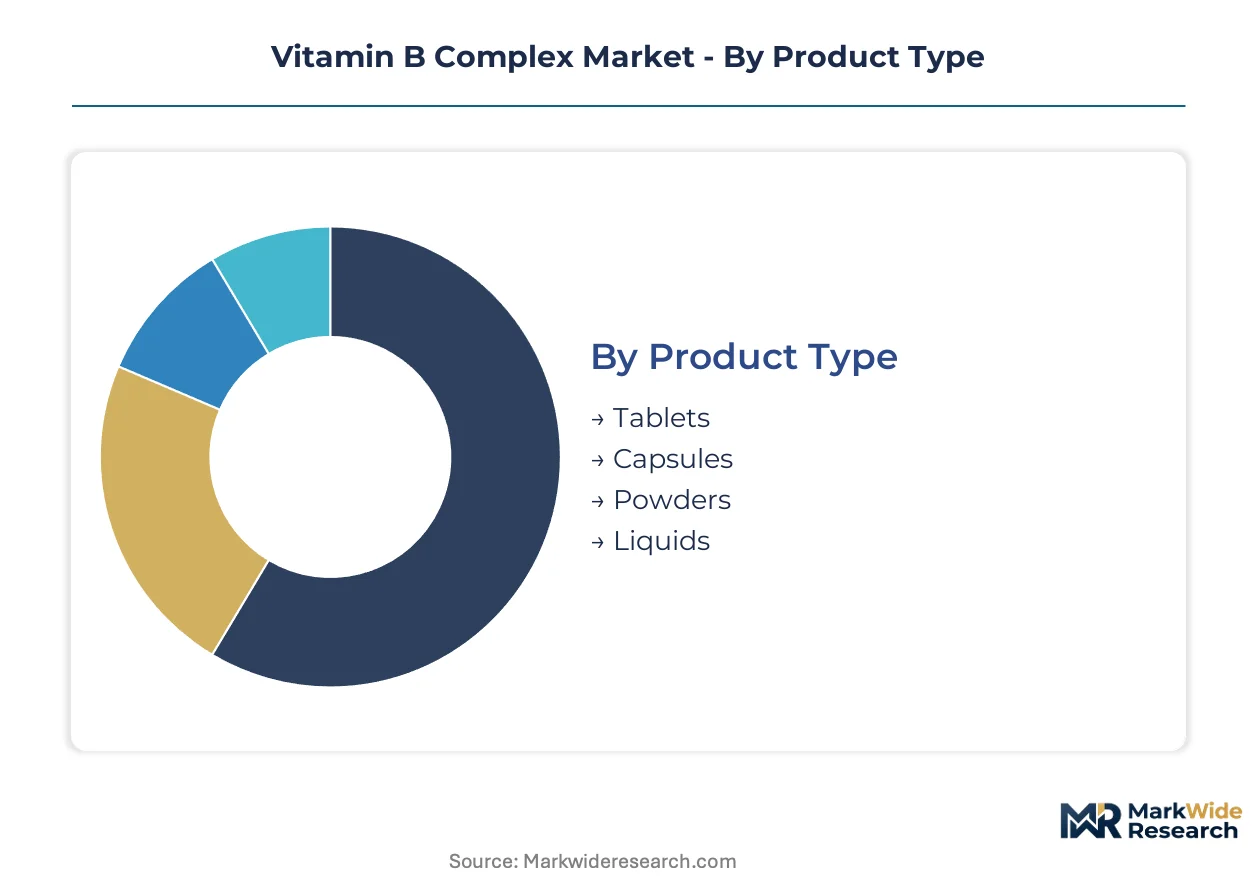
Vitamin B Complex manufacturers configure production lines around format-specific tooling and stability requirements. Segmentation choices directly determine capital allocation, shelf-life engineering, and channel access strategies across therapeutic and wellness applications.
Product Type:
Tablet and capsule formats demand the heaviest upfront investment in compression machinery, coating systems, and dissolution-testing infrastructure. Liquid production requires aseptic filling lines and cold-chain logistics that scale differently.
- Tablets:Compressed formulations with binders and disintegrants enable precise dosing from 1 mg to 100 mg active per unit. Demand concentrates in United States pharmacy chains and direct-to-consumer wellness brands where manufacturing scalability and consumer familiarity drive volume. FDA Current Good Manufacturing Practice regulations govern dissolution profiles and hardness specifications.
- Liquids:Aqueous or oil-based suspensions with preservatives and flavor masking serve pediatric and geriatric populations with swallowing difficulties. Expansion concentrates in telehealth-integrated subscription platforms and European pharmacy channels where EFSA substantiation requirements favor bioavailability claims.
- Capsules:Gelatin or HPMC shells encase powders or granules for modified-release profiles and odor masking.
- Powders:Bulk active blends for food fortification and custom compounding applications.
Most installed capacity flows through Tablets. Expansion is steepest in Liquids.
End User:
Patient segments command premium pricing through clinical reimbursement pathways, while wellness cohorts scale through subscription economics with lower per-unit margins.
- Dietary Supplement Users:Preventive-health consumers pursuing metabolic wellness and neurological maintenance without clinical intervention. Demand concentrates in United States direct-to-consumer channels and European markets where EFSA Article 13 health claims create competitive moats for substantiated efficacy language.
- Patients:Therapeutic-dose regimens prescribed for deficiency states, neuropathy, and pernicious anemia requiring clinician oversight. Demand anchors in pharmacy chains with pharmacist-assisted purchasing and insurance-adjacent reimbursement pathways, particularly in Germany and France where ANSM and BfArM govern prescription boundaries.
- Health Enthusiasts:Wellness-focused consumers bundling B-complex into broader micronutrient protocols.
- Athletes:Performance-oriented users targeting energy metabolism support for training and recovery.
Patient segments extract the highest per-unit margins. Dietary Supplement Users are gaining share fastest.
Distribution Channel:
Channel selection determines working capital intensity, with online models converting inventory risk into logistics complexity and subscription technology investment.
- Online Stores:Direct-to-consumer platforms and marketplace listings with personalized dosing algorithms and bundled protocols. Demand concentrates in United States millennial and Generation X cohorts where telehealth-integrated wellness platforms prescribe therapeutic-dose regimens with home delivery fulfillment.
- Drugstores:Pharmacy counters with pharmacist-assisted purchasing and insurance reimbursement pathways. Demand anchors in Germany, France, and Japan where METI and PMDA regulations maintain professional gatekeeping for therapeutic-dose segments.
- Supermarkets:Mass-market retail with impulse-purchase placement and price-competitive positioning.
- Health Food Shops:Specialty retail with educated staff and premium-brand curation for wellness-focused consumers.
Drugstores retain the highest margin concentration. Online Stores are climbing the fastest.
Packaging Type:
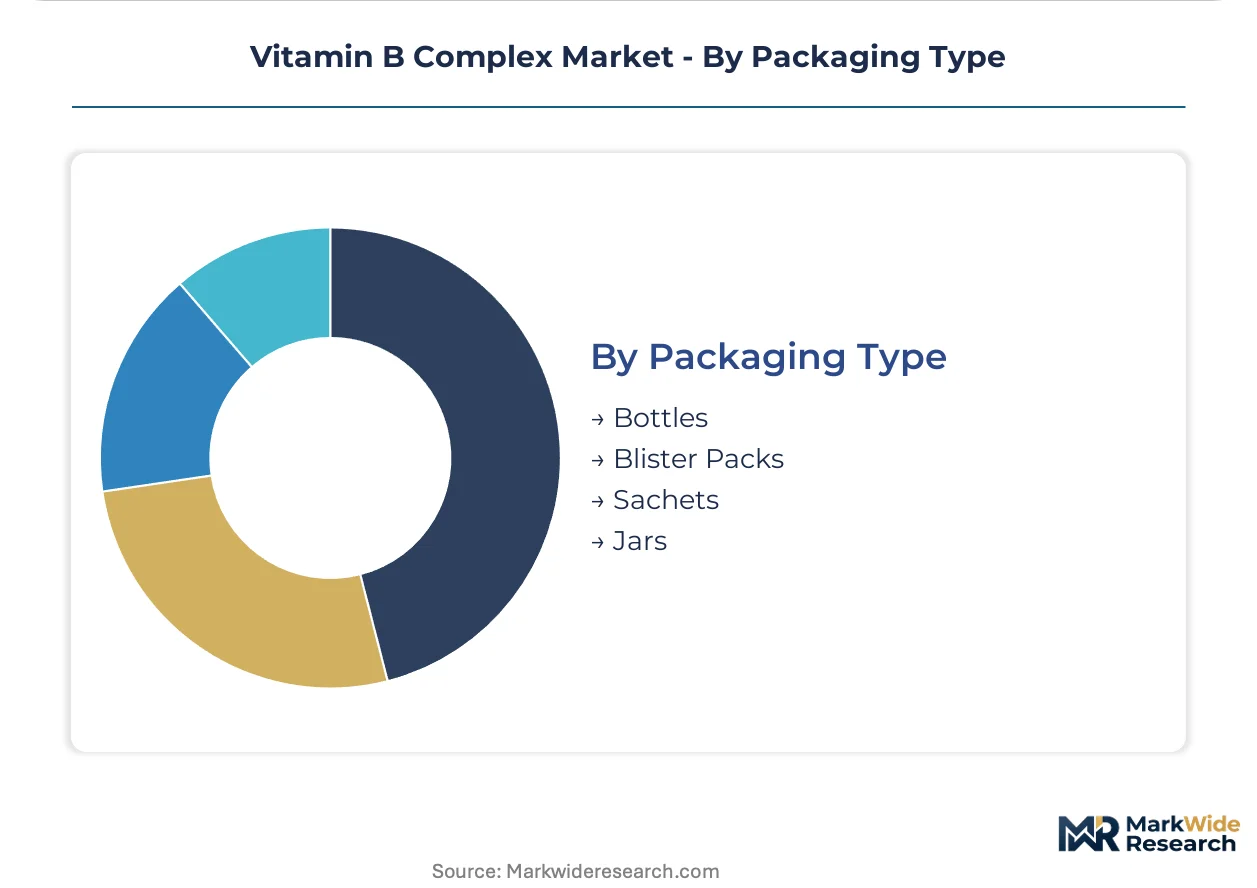
Packaging economics hinge on moisture protection, child-resistance compliance, and sustainability credentials that vary sharply by geography.
- Bottles:HDPE or PET containers with desiccant inserts for moisture-sensitive B-vitamin stability. Demand concentrates in United States mass-market and pharmacy channels where FDA child-resistant packaging requirements govern closure specifications.
- Blister Packs:Thermoformed PVC or aluminum lidding for unit-dose protection and adherence tracking. Demand concentrates in European markets where EU Packaging and Packaging Waste Directive drives aluminum recyclability claims and pharmacy-dispensed therapeutic regimens.
- Sachets:Flexible film single-serve packets for powders and liquids with portion control.
- Jars:Wide-mouth containers for bulk powder formats and food fortification applications.
Bottles carry the highest unit volumes. Blister Packs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Vitamin B Complex industry traces its modern commercial origins to Swiss pharmaceutical innovation in the early twentieth century, when isolation techniques for thiamine and riboflavin established the foundation for today's multi-billion dollar market. Production networks now span fermentation facilities in Asia, petrochemical synthesis corridors in Europe, and direct-to-consumer formulation centers in North America.
United States
Direct-to-consumer wellness brands and pharmacy chains drive the majority of volume demand. FDA Current Good Manufacturing Practice regulations govern dissolution profiles and facility inspections. Formulation hubs cluster in New Jersey and California, where contract manufacturers serve subscription-based replenishment platforms with telehealth integration.
Germany
Pharmacy-channel dominance and clinician-trusted branding anchor therapeutic-dose segments. BfArM governs prescription boundaries for high-potency B12 formulations. Industrial fermentation expertise concentrates in Bavaria and North Rhine-Westphalia, where biotechnology clusters supply bioactive vitamin forms to European brands.
China
Bulk active pharmaceutical ingredient production dominates global supply, with significant concentration in Zhejiang and Shandong provinces. NMPA purity standards and environmental discharge requirements from MEE shape facility siting decisions. Fermentation scale-up capabilities in Jiangsu province serve both domestic nutraceutical brands and multinational procurement.
India
CDSCO-registered contract manufacturers in Hyderabad and Ahmedabad supply multinational brands seeking geographic diversification of production. FSSAI labeling requirements and BIS purity standards govern export eligibility. The country's fermentation infrastructure is expanding to capture contract manufacturing volumes shifting from Chinese supply concentration.
Netherlands
Precision fermentation platforms integrate CRISPR-engineered microbial strains for cobalamin and riboflavin production. EFSA Article 13 health claims processes create competitive moats for substantiated efficacy language. Bioprocess engineering clusters in the Randstad region serve European brands with CSRD-aligned sustainability reporting.
Vitamin B Complex Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with backward integration into petrochemical precursors and fermentation biotechnology. The vendor base spans three tiers: multinational life-science conglomerates controlling raw material supply, specialized nutraceutical formulators with pharmacy-channel relationships, and direct-to-consumer wellness brands with subscription economics. Dominant competitive moves include capacity expansion in microbial fermentation and strategic partnerships with telehealth platforms for distribution access.
Within the conglomerate tier, DSM and BASF occupy positions anchored in synthetic biology capabilities and petrochemical integration respectively. Among pharmacy-channel specialists, GSK exemplifies clinician-trusted branding in therapeutic-dose segments. Nature's Bounty and GNC Holdings represent the direct-to-consumer archetype with mass-market retail and subscription platform presence. These entities collectively illustrate the strategic segmentation between upstream supply control and downstream brand access.
| Leading Market Players |
|---|
| Nature's Bounty |
| GNC Holdings Inc |
| Amway (Nutrilite) |
| DSM |
| Nestlé Health Science |
| Nature Made |
| GSK |
| BASF |
| Pfizer (Caltrate) |
| Others |
Value Network & Pricing Analysis
Petrochemical precursor costs for thiamine and riboflavin synthesis cascade through three distinct pricing tiers, with acetonitrile price volatility transmitted from Zhejiang fermentation facilities to United States pharmacy chains and European direct-to-consumer brands. Energy-intensive microbial B12 production in Danish biotechnology clusters commands premium positioning against chemically synthesized alternatives, while contract manufacturers in Hyderabad and Ahmedabad compete on cost for generic tablet formulations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated bioactive forms from conventional chemical synthesis and private-label generics. Price differentiation centers on fermentation-derived purity grades and CSRD-aligned sustainability credentials demanded by institutional procurement. Pricing pressure stems from Chinese API oversupply in bulk B-vitamin categories. Dietary supplement users exhibit highest price sensitivity; therapeutic-dose pharmacy segments show lowest.
Supply Chain Analysis
Direct-to-consumer channels handle subscription-model demand from millennial wellness cohorts, while pharmacy chains manage insurance-adjacent therapeutic regimens. Raw material supply concentrates in China, India, and the Netherlands, with Zhejiang province dominating bulk API output and Dutch biotechnology clusters supplying precision-fermented bioactive forms. Critical dependencies include acetonitrile for chemical synthesis, corn-derived fermentation feedstocks, and pharmaceutical-grade gelatin for capsule shells. Single-source vulnerability from Chinese supply concentration threatens geographic diversification efforts. Distribution runs through online subscription platforms, pharmacy counters, and health food specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vitamin B Complex market represents a late-cycle quality story as preventive health consciousness shifts demand toward EFSA-substantiated, fermentation-derived formulations with documented bioavailability profiles.
For Market Incumbents: Deepen backward integration into petrochemical precursors or precision fermentation capacity to defend margin position against Chinese API price competition. Prioritize CDSCO-registered manufacturing partnerships in Hyderabad and Ahmedabad to diversify geographic supply exposure. Secure EFSA Article 13 health claims for proprietary bioactive forms to lock in premium pricing tiers. For New Entrants and Emerging Players: The EU's Corporate Sustainability Reporting Directive in Europe opens a window for contract manufacturers with embedded emissions disclosure capabilities to capture brand outsourcing demand. Target pediatric liquid formulations as the most penetrable white space, where swallowing difficulties create unmet need. Pursue telehealth-integrated subscription distribution to bypass pharmacy margin extraction. For Investors and Strategic Acquirers: Roll-up economics work for CDSCO-registered Indian contract manufacturers because multinational brands are actively diversifying production away from Chinese supply concentration. Five-to-ten year viability hinges on fermentation scale-up expertise scarcity. Monitor EFSA substantiation approval velocity as the inflection signal for premium-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-engineered microbial strains achieve cost parity with petrochemical synthesis for cobalamin production. |
| EFSA Health Claims Substantiation | Article 13 approvals create competitive moats for European brands against generic competitors. |
| Indian Contract Manufacturing Expansion | CDSCO-registered facilities in Hyderabad capture volumes shifting from Chinese API concentration. |
| Direct-to-Consumer Channel Buildout | Telehealth-integrated subscription models bypass pharmacy margin extraction in United States wellness segments. |
| CSRD-Aligned Sustainability Reporting | Embedded emissions disclosure capabilities attract institutional procurement from European pharmacy chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with nutraceutical formulators, fermentation facility engineers, pharmacy procurement managers, and regulatory affairs specialists with secondary validation from FDA Current Good Manufacturing Practice filings, EFSA Article 13 health claims registers, CDSCO manufacturing registration databases, and customs trade data. Bottom-up capacity assessments and top-down demand modeling provided triangulation across the analysis window.
Comparable-period anchoring linked historical fermentation capacity utilization and pharmacy channel volume data to projection assumptions across the modeling period. Segmentation dimensions included product format, end-user category, distribution channel, and geographic regulatory cluster. CAGRs were derived from normalized growth trajectory analysis. Forecast inputs incorporated petrochemical feedstock price indices and EFSA substantiation approval timelines.
Revisions become necessary when Chinese environmental discharge enforcement tightens, EU health claims substantiation standards shift, or fermentation technology achieves breakthrough cost reductions. Forecasts reflect documented assumptions about regulatory stability and feedstock price bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
North America Feed Vitamins Market