
 Nutraceutical Excipients Market | 2026-2036
Nutraceutical Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Excipients Market Intelligence
Modular dosage formats are hardening as the dominant configuration pattern, with manufacturers unbundling traditional tablet-capsule bundles into single-serve sachets and stick packs that demand tailored excipient performance. BASF SE leverages its polymer expertise to supply specialized coating systems for these flexible formats. Kerry Group anchors its position through integrated taste-masked excipient platforms that reduce the need for separate flavoring steps. Roquette Frères differentiates via plant-derived binder technologies that align with clean-label positioning across European and North American customers.
Nutraceutical excipients are inactive substances formulated alongside bioactive compounds to ensure stability, manufacturability, and controlled release in dietary supplement and functional food products; their composition spans cellulose derivatives, starches, lipids, and synthetic polymers selected for specific dissolution profiles and compressibility indices. The primary commercial purpose centers on enabling high-speed production of uniform dosage forms while protecting sensitive actives from degradation during shelf life and gastric transit. Fillers and binders occupy the largest volume share as tablet and capsule production remains the backbone of dietary supplement manufacturing. Coatings represent the fastest-expanding margin pool as delayed-release and enteric applications gain traction among probiotic and enzyme formulations. Functional foods and beverages as an application category are pulling excipient innovation toward heat-stable and pH-tolerant variants.
FDA dietary supplement regulations, EFSA novel food assessments, and FSSAI excipient quality standards collectively shape product registration pathways and manufacturing compliance burdens across major supply destinations. These frameworks elevate demand for pharmacopeia-grade materials with documented safety profiles and batch-to-batch consistency. Stakeholders must monitor evolving clean-label definitions and regional purity thresholds as procurement criteria harden beyond basic technical performance.
Market Dynamics
Modular dosage formats are fragmenting traditional tablet-capsule supply chains into single-serve sachet and stick-pack configurations that demand excipient performance tailored to flexible packaging stresses rather than standard compression indices.
Growth Catalysts
- FDA Labeling Modernization:Updated dietary supplement labeling requirements are pushing manufacturers toward excipients with cleaner technical profiles and documented safety dossiers that streamline compliance pathways.
- Sports Nutrition Formats:Specialized binders and coatings are proliferating across protein bar and ready-to-drink applications as brands differentiate delivery formats in crowded retail sets.
- Functional Food Heat Stability:Heat-stable and pH-tolerant excipient variants are capturing pull from beverage manufacturers expanding into fortified and fermented product lines.
Market Restraints
- Pharmacopeia-Grade Input Costs:Cellulose derivatives and modified starches with USP-NF certification command 15-40% premiums over technical grades, compressing margin pools for mid-tier contract manufacturers.
- European Supply Concentration:Plant-derived binder technologies from Roquette Frères and specialty coating systems from BASF SE create dependency risk for North American formulators seeking clean-label positioning.
- EFSA Novel Food Assessments:Extended safety evaluation timelines for new excipient compositions delay product launches by 18-36 months, freezing innovation capital in regulatory queues.
Strategic Opportunities
- India FSSAI Quality Standards:Rising domestic excipient quality mandates are creating first-mover advantage for suppliers establishing pharmacopeia-grade manufacturing within the subcontinent.
- Probiotic Enteric Coatings:Delayed-release applications for enzyme and live culture formulations represent an underpenetrated margin pool as gastric survival rates become a purchase criterion.
- Gummy Manufacturing Scale-Up:United States contract manufacturers are expanding capacity for functional confectionery formats that require specialized moisture-barrier excipients distinct from traditional tablet binders.
Industry Challenges
- Clean-Label Definition Fluidity:Absence of harmonized standards across FDA, EFSA, and FSSAI jurisdictions forces suppliers to maintain multiple product grades, fragmenting batch economics.
- High-Speed Line Integration:Excipient performance must compressibility-match legacy equipment while enabling throughput rates above 500,000 units per hour, constraining formulation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Excipients Market |
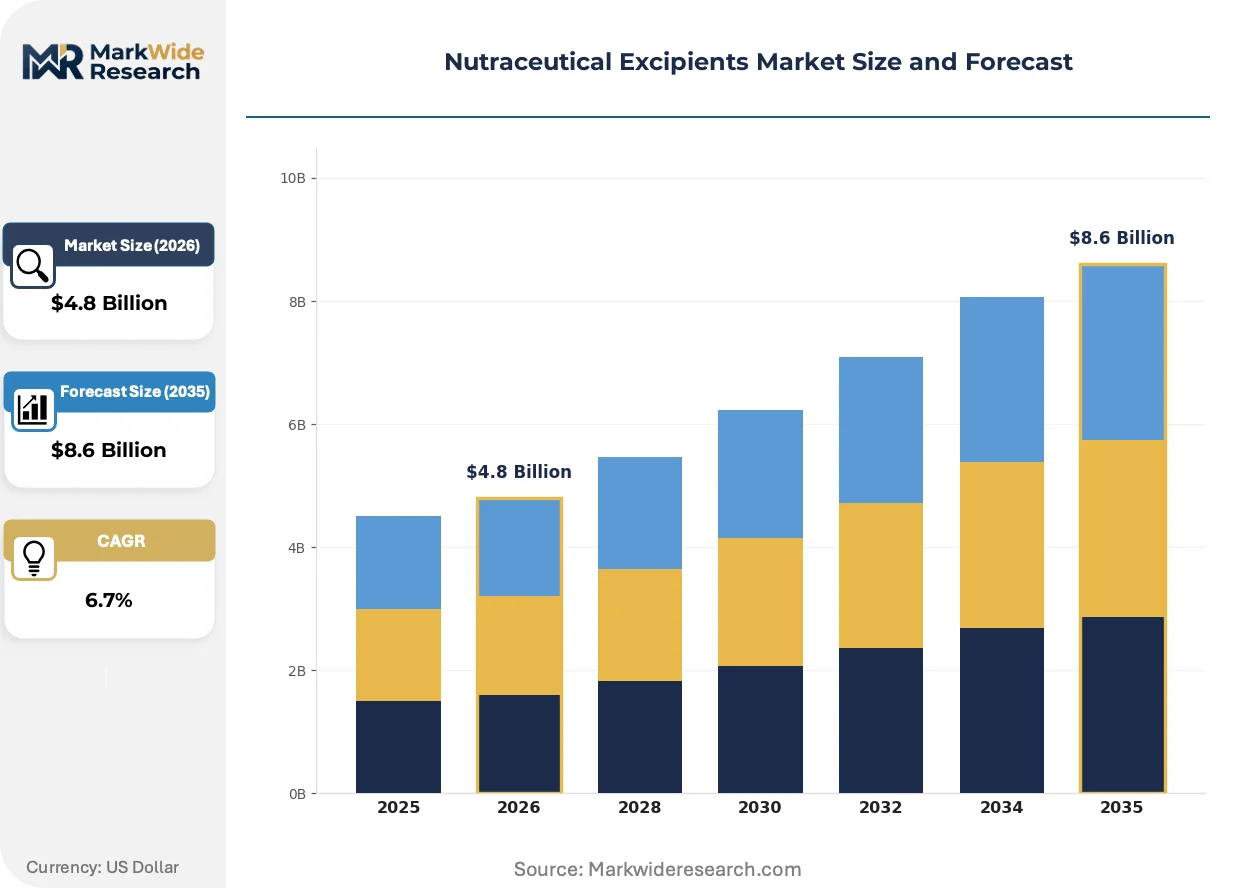
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillers, Binders, Disintegrants, Coatings, Lubricants, Glidants Application: Tablets, Capsules, Powders, Beverages, Bars, Functional Foods End User: Dietary Supplement Manufacturers, Functional Food Producers, Sports Nutrition Companies, Pharmaceutical Firms Form: Dry Powders, Granules, Liquids, Semi-solids, Pellets |
| Companies Covered | DuPont Nutrition & Biosciences, BASF SE, Evonik Industries, Kerry Group, Roquette Frères, Ingredion Incorporated, Ashland Global Holdings, FMC Corporation, International Flavors & Fragrances Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Excipients Market Strategic Shifts & Innovations
Excipient innovation is pivoting from universal performance specifications toward segment-specific functional profiles that align with clean-label positioning, regulatory dossier requirements, and novel delivery format stresses.
Modified-release polymer systems are electrifying probiotic and enzyme formulation stability. Sports nutrition brands are adopting these coatings at accelerated pace to differentiate gastric survival claims. The technology is compressing traditional barrier-coating suppliers into specialized performance tiers or commodity margins.
REACH registration requirements for synthetic polymers are tightening documentary burdens on European excipient importers. Manufacturers are responding by accelerating plant-derived binder substitution programs. Probiotic and enzyme segments face the steepest compliance cost escalation as enteric coating portfolios reconfigure.
Brand procurement teams are consolidating supplier relationships around integrated taste-masked platforms that eliminate separate flavoring process steps. Kerry Group's bundled offerings are displacing point-solution purchasing in North American sports nutrition. This consolidation is most visible among mid-scale contract manufacturers seeking to reduce formulation complexity and audit overhead.
Nutraceutical Excipients Market Segmentation
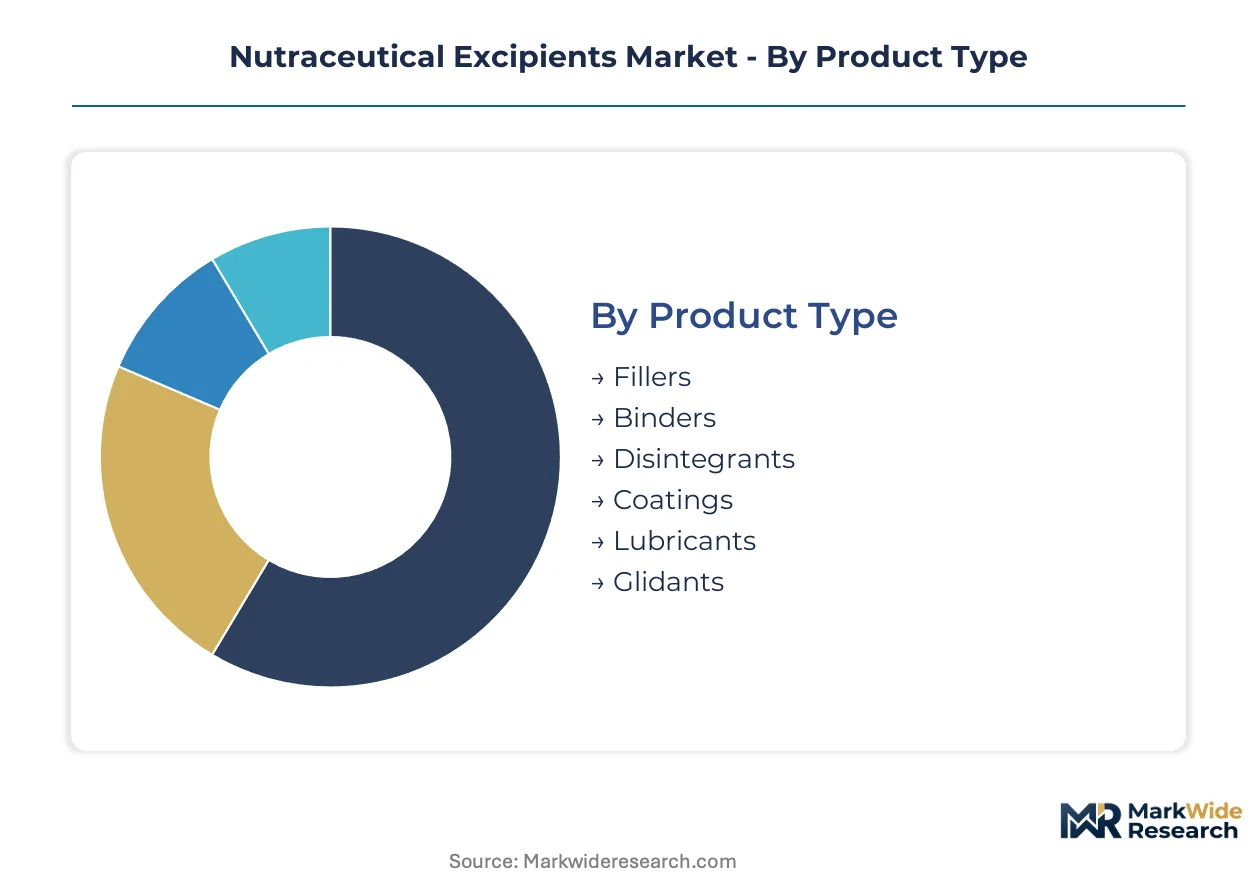
Excipient selection in nutraceuticals hinges on matching functional performance to specific manufacturing stresses and regulatory dossier requirements across delivery formats. Segmentation reveals where procurement budgets concentrate and which technical specifications command premium positioning.
Product Type:
Formulation engineers prioritize dissolution profiles and compressibility indices when allocating procurement spend across functional categories.
- Fillers:Cellulose derivatives and modified starches provide bulk density and flow properties for high-speed tablet production. Demand concentrates among United States contract manufacturers scaling gummy and functional food capacity where filler load affects final texture.
- Coatings:Polymer systems enable delayed-release and enteric protection for probiotic and enzyme formulations. Sports nutrition brands in North America and Europe are adopting these systems fastest to differentiate gastric survival claims on retail packaging.
- Binders:Plant-derived and synthetic polymers ensure tablet integrity during compression and shelf life.
- Disintegrants:Superdisintegrants like croscarmellose sodium accelerate dissolution in gastric media.
- Lubricants:Magnesium stearate and vegetable-based alternatives prevent tooling adhesion during high-speed tableting.
- Glidants:Colloidal silicon dioxide improves powder flow for capsule filling operations.
Fillers lead on scale; coatings lead on momentum.
Application:
Delivery format selection determines which excipient performance attributes become non-negotiable in supplier qualification.
- Tablets:Compression-grade excipients must achieve hardness above 4 kp while maintaining friability below 1% for high-speed packaging lines. United States dietary supplement manufacturers remain the dominant volume purchasers as tablet-capsule bundles persist in mass-market channels.
- Functional Foods:Heat-stable and pH-tolerant variants are capturing pull from beverage manufacturers expanding into fortified and fermented product lines across North American and European retail sets.
- Capsules:Gelatin and HPMC shells require compatible filler systems for powder or granule encapsulation.
- Powders:Instant dispersibility and moisture resistance define excipient specifications for stick-pack and sachet formats.
- Beverages:Solubility and suspension stability requirements differ markedly from solid dosage demands.
- Bars:Protein bar applications require specialized binders that maintain structural integrity through temperature fluctuations.
Tablets dominate current procurement volumes; functional foods are expanding most quickly.
End User:
Customer type shapes excipient technical requirements through divergent regulatory exposure and clean-label positioning intensity.
- Dietary Supplement Manufacturers:These buyers prioritize pharmacopeia-grade materials with USP-NF certification to satisfy FDA labeling modernization requirements. Procurement teams are consolidating supplier relationships around integrated platforms that reduce formulation complexity.
- Sports Nutrition Companies:Specialized binders and coatings are proliferating across protein bar and ready-to-drink applications as brands differentiate delivery formats. This segment is gaining share fastest as athletic lifestyle positioning expands beyond core demographics.
- Functional Food Producers:Heat stability requirements for UHT processing and baking applications create distinct excipient specifications from supplement manufacturing.
- Pharmaceutical Firms:cGMP compliance and ICH Q3D elemental impurity guidelines impose stricter quality thresholds than nutraceutical-grade applications.
Dietary supplement manufacturers lead on scale; sports nutrition companies lead on momentum.
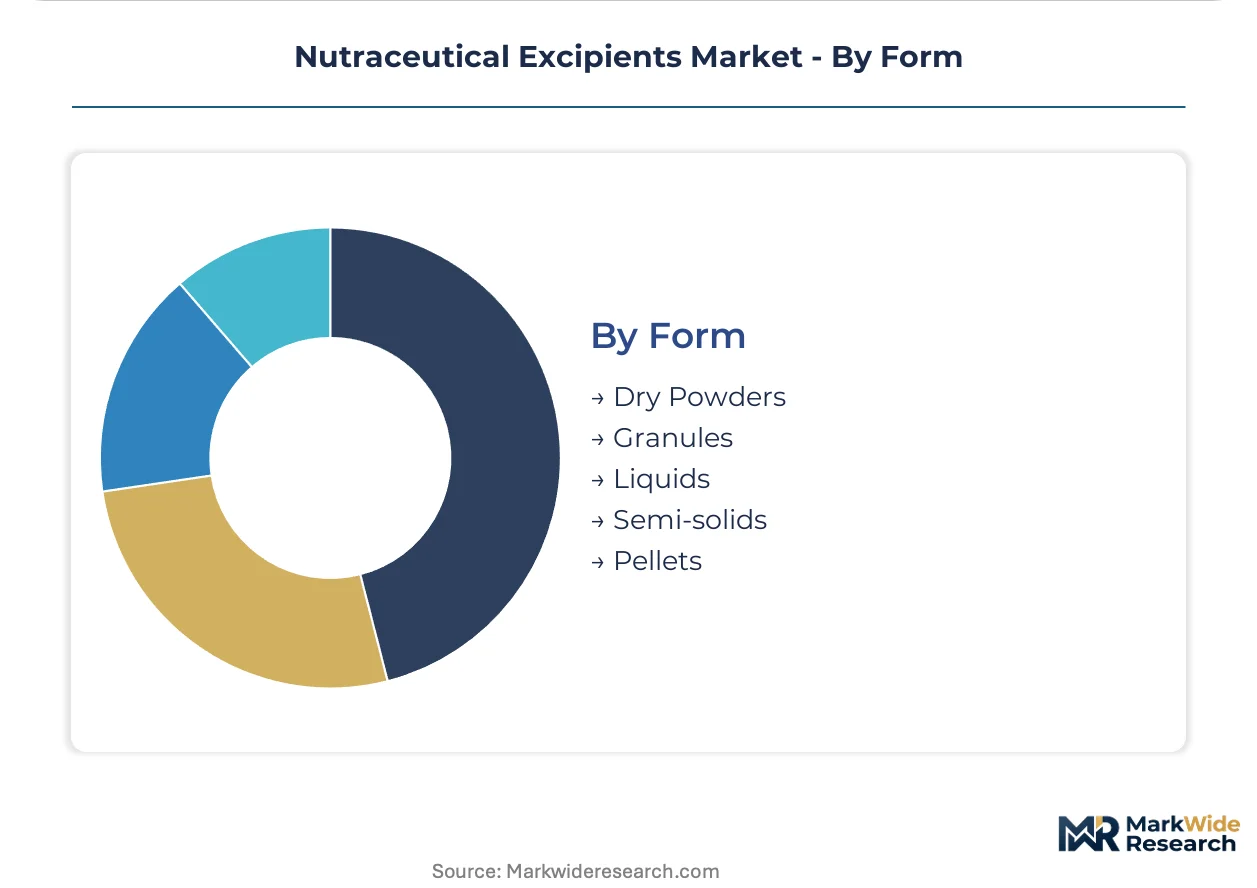
Form:
Physical state determines handling characteristics, storage requirements, and compatibility with active pharmaceutical ingredients.
- Dry Powders:Free-flowing particulate systems remain the default configuration for tablet compression and capsule filling operations. United States and European contract manufacturers specify powder grades with tight particle size distributions to ensure content uniformity.
- Liquids:Solution and suspension excipients serve beverage and liquid supplement applications where solid-state processing is impractical. Demand is climbing the fastest as functional beverage lines expand beyond traditional supplement channels.
- Granules:Agglomerated particles improve flow properties and reduce dust generation during high-speed manufacturing.
- Semi-solids:Gel and paste excipients find application in chewable and gummy manufacturing where moisture control is critical.
- Pellets:Spherical granules enable multiparticulate dosage forms and controlled-release matrix systems.
Dry powders dominate manufacturing inputs; liquids are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nutraceutical excipients industry traces its commercial scale to post-war pharmaceutical manufacturing clusters in Germany and the United States, where cellulose derivative processing first achieved industrial throughput. Modern demand geography reflects this lineage while shifting toward Asia-Pacific contract manufacturing centers.
United States
Dietary supplement contract manufacturers in New Jersey and California are scaling gummy and functional food capacity, pulling specialized moisture-barrier excipients. FDA labeling modernization elevates procurement of USP-NF certified materials. The New York-New Jersey pharma corridor anchors East Coast excipient distribution networks serving mid-Atlantic formulation houses.
Germany
Specialty polymer coating systems command premium positioning among European probiotic formulators seeking gastric survival differentiation. REACH registration burdens on synthetic polymers accelerate plant-derived binder substitution programs. The Rhine-Ruhr industrial basin concentrates toll manufacturing capacity for enteric coating applications.
India
Domestic dietary supplement brands are expanding manufacturing capacity in Maharashtra and Gujarat, driving pharmacopeia-grade excipient demand. FSSAI quality standard tightening creates first-mover advantage for suppliers establishing USP-NF manufacturing within the subcontinent. Hyderabad's life sciences cluster incubates regional excipient distribution infrastructure.
China
Functional beverage manufacturers in Guangdong and Zhejiang provinces require heat-stable excipient variants for UHT processing lines. NMPA excipient quality guidelines align with ICH Q3D elemental impurity standards, elevating import substitution priorities. The Yangtze River Delta hosts contract manufacturing scale-up for export-oriented supplement brands.
Japan
Aging-population supplement brands in Tokyo and Osaka prioritize dissolution-optimized excipients for geriatric dosage formats. PMDA consultation procedures for novel excipient compositions extend development timelines, freezing innovation capital. The Kansai region maintains specialty lipid excipient production for traditional medicine applications.
Nutraceutical Excipients Market Key Industry Players
The competitive structure tilts toward integrated chemical conglomerates with polymer expertise crossing into food-grade applications. Three to five global suppliers control premium coating and modified-release technology tiers, while regional specialists capture standard-grade filler and binder volumes. The dominant archetypes comprise diversified chemical majors, integrated taste-and-texture platforms, and plant-derived specialists. Competitive moves concentrate on backward integration into pharmacopeia-grade raw material sourcing and geographic licensing partnerships to bypass REACH and FSSAI registration bottlenecks.
Within the diversified chemical major tier, BASF SE and Evonik Industries exemplify polymer-to-pharma technology transfer capabilities. Kerry Group anchors the integrated platform archetype through bundled taste-masked excipient systems. Roquette Frères occupies the plant-derived specialist position leveraging European agricultural supply chains. These three represent distinct strategic postures rather than direct segment overlap, with each archetype commanding different procurement relationships and margin structures.
| Leading Market Players |
|---|
| DuPont Nutrition & Biosciences |
| BASF SE |
| Evonik Industries |
| Kerry Group |
| Roquette Frères |
| Ingredion Incorporated |
| Ashland Global Holdings |
| FMC Corporation |
| International Flavors & Fragrances Inc |
| Others |
Cost & Logistics Intelligence
Cellulose derivative feedstock indices cascade through nutraceutical excipient supply chains into three distinct procurement tiers, with USP-NF certified grades commanding substantial premiums over technical grades and compressing margin pools for mid-tier contract manufacturers facing FDA labeling modernization compliance burdens.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs excipient procurement, with pharmacopeia-grade certification and documented safety dossiers driving price differentiation between tiers. Cost compression in standard-grade cellulose derivatives is intensifying because REACH registration burdens on synthetic polymers accelerate plant-derived substitution programs. Sports nutrition companies demonstrate the lowest price sensitivity as gastric survival claims justify premium coating investments, while functional food producers in developing markets exhibit highest sensitivity to input cost fluctuations.
Supply Chain Analysis
Specialty polymer supply rests on German and United States chemical conglomerates with polymer-to-pharma technology transfer capabilities, while plant-derived binder feedstock draws from European agricultural processing clusters. Modified starches and cellulose derivatives constitute critical raw material dependencies alongside lipid excipients for traditional medicine applications. Single-source vulnerability concentrates in enteric coating technology tiers controlled by three to five global suppliers. Distribution runs through regional toll manufacturing hubs anchored by the New York-New Jersey pharma corridor and the Rhine-Ruhr industrial basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA dietary supplement labeling modernization elevates procurement of pharmacopeia-grade materials and reshapes supplier consolidation patterns across North American contract manufacturing.
For Market Incumbents: Deploy backward integration into pharmacopeia-grade raw material sourcing to defend against emerging plant-derived specialists capturing clean-label positioning. BASF SE and Kerry Group exemplify this lever through captive polymer expertise and integrated taste-masked platforms respectively. Capacity addition in India creates defensive moats against FSSAI quality standard tightening that rewards first-mover suppliers establishing USP-NF manufacturing within the subcontinent. For New Entrants and Emerging Players: Begin with probiotic enteric coatings as the most penetrable margin pool where gastric survival rates increasingly drive purchase criteria among sports nutrition brands. Functional gummy manufacturing in the United States offers secondary white-space as contract manufacturers scale capacity for moisture-barrier excipients distinct from traditional tablet binders. A regulatory dossier service bundling strategy reduces audit overhead for mid-scale formulators seeking to consolidate supplier relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with plant-derived specialists leveraging European agricultural supply chains as REACH compliance costs reconfigure synthetic polymer portfolios. Five-to-ten year viability favors excipient suppliers with demonstrated pharmacopeia-grade manufacturing capabilities across multiple regulatory jurisdictions. Watch FSSAI enforcement intensity as the signal indicating when Indian domestic demand justifies regional manufacturing footprint expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pharmacopeia-Grade Raw Materials | Captures margin premiums from USP-NF certification requirements elevating procurement standards. |
| Geographic Licensing Partnerships | Bypasses REACH and FSSAI registration bottlenecks for European and Indian market access. |
| Integrated Taste-Masked Platform Development | Eliminates separate flavoring steps for Kerry Group-style bundled excipient offerings. |
| Plant-Derived Binder Substitution Programs | Aligns with clean-label positioning as Roquette Frères demonstrates across European supply chains. |
| Probiotic Enteric Coating Specialization | Differentiates gastric survival claims for sports nutrition brands seeking retail packaging advantages. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation engineers at dietary supplement manufacturers, procurement leads at sports nutrition companies, regulatory affairs directors navigating FDA labeling modernization, and plant managers at contract manufacturing facilities with secondary validation against USP-NF certification databases, FDA dietary supplement filings, EFSA novel food assessment records, and customs trade data for cellulose derivative imports. Bottom-up excipient demand modeling triangulated against top-down market sizing across delivery format categories.
Historical reference periods anchored the forecast window to pre-pandemic baseline through current regulatory transition phases, with segmentation dimensions spanning product type, application, end user, form, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating probiotic and enzyme formulation growth, functional food heat stability requirements, and gummy manufacturing capacity expansion. Forecast inputs included FSSAI quality standard implementation timelines and REACH registration burden escalation for synthetic polymers.
Caveats apply where EFSA novel food assessment timeline extensions or FSSAI enforcement intensity shifts could materially shift the outlook for excipient innovation capital deployment. Forecasts reflect assumptions regarding clean-label definition harmonization across FDA, EFSA, and FSSAI jurisdictions. A small set of named triggers including regulatory dossier requirement changes and plant-derived binder technology maturation warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Carob Bean Gum Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market