
 North America Feed Vitamins Market | 2026-2036
North America Feed Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Vitamins Market Analytics
Subscription-based premix formulation services is expanding how vitamin suppliers monetize feed additive relationships beyond commodity sales. DSM Nutritional Products AG leverages its Swiss parent company's biotechnology pipeline to sustain R&D intensity in next-generation vitamin metabolites. Cargill Inc. anchors its position through backward integration into grain origination and captive premix manufacturing networks across the Corn Belt. BASF SE differentiates via chemical synthesis expertise that spans pharmaceutical and animal nutrition applications.
Feed vitamins comprise water-soluble and fat-soluble organic compounds supplemented in livestock diets to prevent deficiency disorders, optimize metabolic function, and support immune competence; typical inclusion rates range from grams to milligrams per ton of finished feed depending on species requirements and basal ingredient composition. Vitamin E maintains structural dominance in ruminant applications due to its antioxidant role in preventing nutritional muscular dystrophy, while Vitamin D3 exhibits accelerated demand in poultry operations responding to cage-free housing mandates that reduce natural light exposure. Powder formulations occupy the largest volume share owing to blending compatibility with mash feeds, though liquid micro-encapsulation variants command premium positioning in automated dosing systems.
The FDA's Center for Veterinary Medicine enforces current Good Manufacturing Practice requirements for medicated feed mills, while the USDA's Agricultural Marketing Service oversees quality verification programs that indirectly elevate vitamin specification standards. The Canadian Food Inspection Agency maintains parallel oversight through its Feed Program, creating cross-border compliance symmetry that simplifies supplier certification burdens. Stakeholders must monitor evolving state-level phosphorus and nitrogen regulations, as these nutrient management constraints increasingly trigger reformulation decisions that cascade into vitamin premix redesign requirements.
Market Dynamics
Midwestern concentrated animal feeding operations are consolidating vitamin procurement through multi-year supply agreements, compressing spot market liquidity and forcing premix suppliers to restructure pricing architectures around volume-commitment tiers.
Growth Catalysts
- Cage-free housing mandates:State-level poultry welfare regulations in California and Massachusetts eliminate natural light exposure, necessitating elevated Vitamin D3 supplementation rates in layer operations.
- FSMA compliance infrastructure:The FDA's updated animal food safety rules under the Food Safety Modernization Act require hazard analysis and preventive controls, elevating demand for certified premix manufacturing capacity.
- Feed conversion optimization:Poultry integrators across the southeastern United States are expanding vitamin premix programs to improve metabolic efficiency and reduce feed cost per unit of gain.
Market Restraints
- Feed-grade vitamin input volatility:Chemical synthesis of Vitamin A and E precursors depends on petrochemical derivatives and acetate intermediates subject to energy price swings.
- Chinese supply concentration:Bulk vitamin manufacturing capacity clusters in Shandong and Zhejiang provinces, creating geographic single-source risk for North American formulators.
- Substitution pressure from direct-fed microbials:Enzyme and probiotic additives compete for inclusion space in premium ration formulations targeting gut health outcomes.
Strategic Opportunities
- Canadian prairie expansion:Alberta and Saskatchewan cattle feeding operations remain underpenetrated for custom vitamin premix services relative to US Corn Belt intensity.
- Subscription formulation services:Premix suppliers can monetize ongoing nutritional advisory relationships beyond commodity vitamin sales through recurring revenue structures.
- Micro-encapsulation technology convergence:Combination of lipid coating and spray-drying processes enables heat-stable vitamin variants for pelleted feed applications.
Industry Challenges
- Qualified nutritionist scarcity:Feed formulation roles require dual competency in animal science and regulatory compliance, tightening talent pipelines for premix technical service teams.
- Cross-border certification complexity:Parallel FDA and Canadian Food Inspection Agency feed safety programs create duplicative audit burdens for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Vitamins Market |
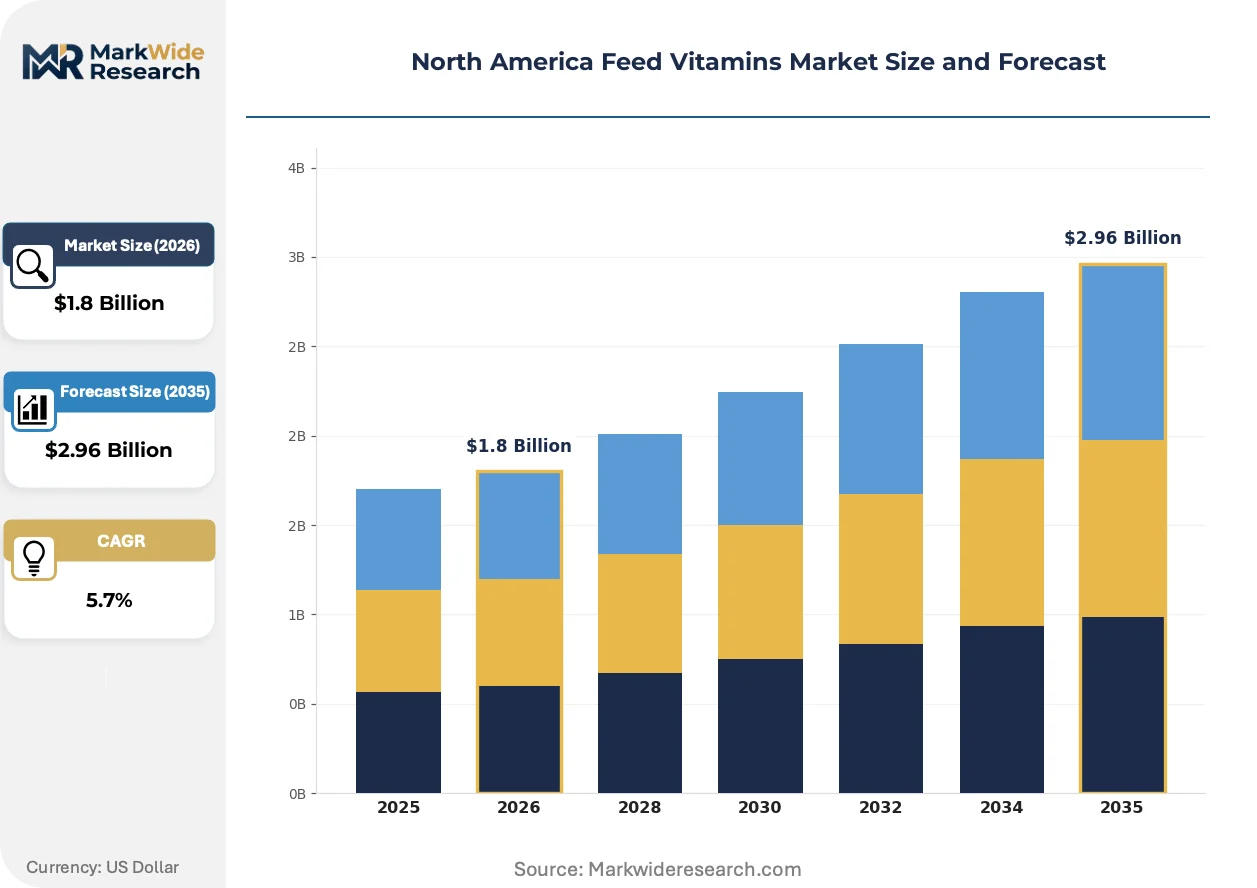
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin A, Vitamin D, Vitamin E, Vitamin K Formulation: Powder, Liquid, Granules, Tablets End User: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | Adisseo, Archer Daniels Midland Co., BASF SE, Brenntag SE, Cargill Inc., DSM Nutritional Products AG, Evonik Industries, Lonza Group Ltd., Nutreco N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Vitamins Market Evolving Landscape
Near-infrared spectroscopy and automated dosing systems are compressing formulation cycle times while elevating precision requirements for vitamin micro-encapsulation technologies. These shifts favor suppliers with captive R&D infrastructure over commodity traders.
Robotic sampling and analysis equipment is automating quality verification in high-volume premix facilities. Large integrators in Iowa and Nebraska deploy these systems to reduce batch-to-batch vitamin variance below 2%. The technology is automating compliance documentation for FSMA hazard analysis records.
The EPA's emerging nutrient discharge regulations for concentrated animal feeding operations are triggering reformulation cascades. Phosphorus and nitrogen management constraints in the Chesapeake Bay watershed and California Central Valley force ration redesigns that redistribute vitamin premix specifications. Poultry operations in these watersheds face the steepest premix adjustment requirements.
Consolidated procurement desks at major protein companies are compressing supplier rosters and unbundling technical advisory from product supply. Midwestern pork and beef processors now demand standalone formulation consulting before awarding vitamin contracts. This behavior concentrates purchasing power among fewer buyers while fragmenting service delivery models.
North America Feed Vitamins Market Segmentation
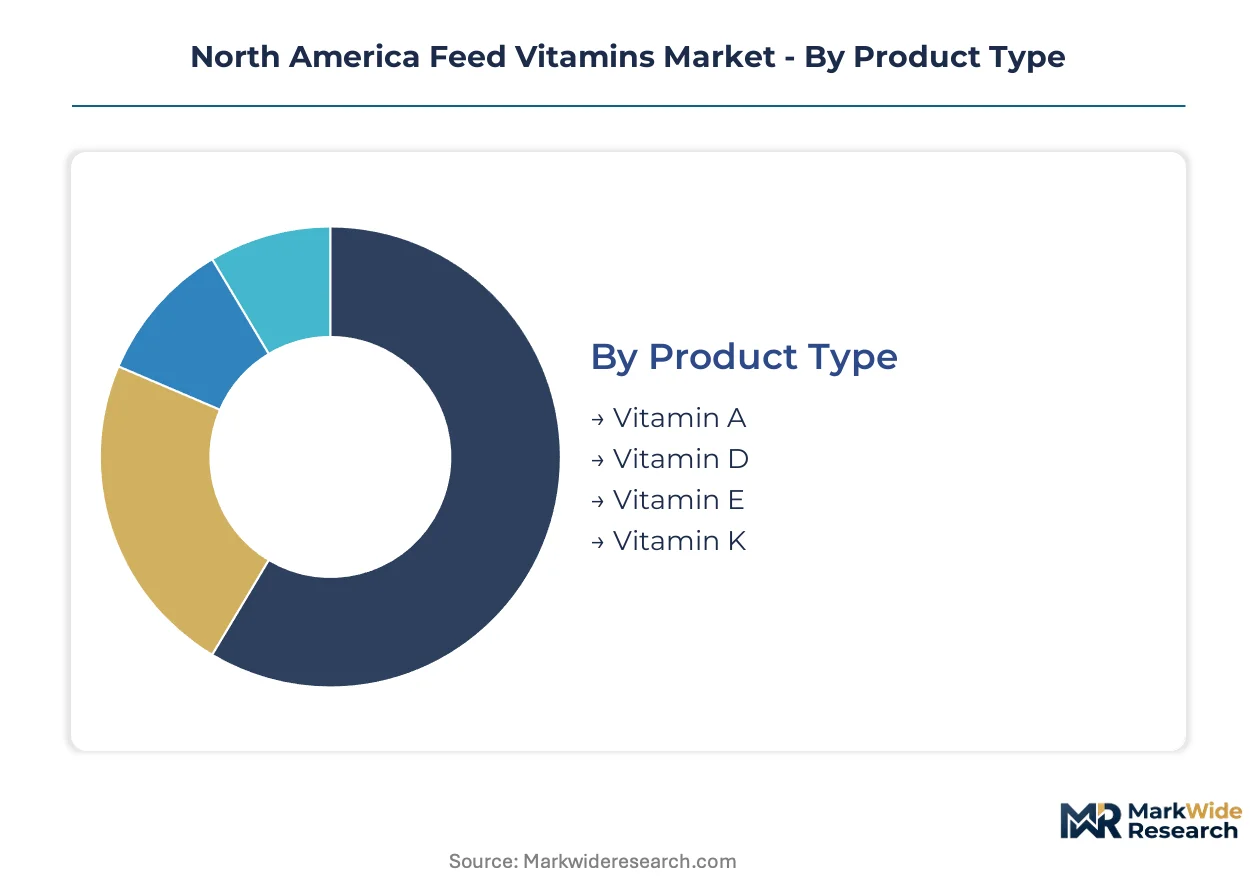
Feed vitamin suppliers structure product portfolios around species-specific metabolic requirements, manufacturing process compatibility, and procurement channel economics. Segmentation discipline separates commodity volume plays from premium formulation services across North American livestock operations.
Product Type:
Species deficiency risks and regulatory thresholds differentiate buyer priorities across the four core vitamin categories.
- Vitamin E:Alpha-tocopherol acetate formulations dominate ruminant applications through antioxidant protection against nutritional muscular dystrophy. Midwestern cattle feedlots in Iowa and Nebraska maintain specification contracts for high-potency Vitamin E premixes to meet USDA quality verification standards.
- Vitamin D:Cholecalciferol (D3) exhibits accelerated demand in layer operations responding to California and Massachusetts cage-free housing mandates that eliminate natural light exposure. Southeastern poultry integrators are expanding D3 supplementation rates to maintain eggshell quality and bone density in enclosed housing systems.
- Vitamin A:Retinol palmitate and acetate esters support vision, epithelial integrity, and immune function across all livestock species; stability challenges in pelleted feeds drive demand for micro-encapsulated variants.
- Vitamin K:Menadione derivatives address coagulation disorders in swine and poultry; inclusion rates remain lowest among fat-soluble vitamins due to gut microbial synthesis in ruminants.
Volume sits with Vitamin E; growth tilts toward Vitamin D.
Formulation:
Processing temperature tolerance and dosing automation requirements shape formulation selection in mill operations.
- Powder:Standardized particle sizes enable homogeneous blending with mash feeds and mineral premixes. Powder variants occupy the largest volume share across Corn Belt feed mills due to compatibility with existing batching infrastructure and lower unit costs.
- Liquid:Micro-encapsulation and lipid carrier systems command premium positioning in automated dosing systems. Large integrators in the southeastern United States deploy liquid injection equipment to reduce batch-to-batch variance below 2%.
- Granules:Agglomerated forms improve flowability and reduce dust exposure during handling; heat-stable coatings suit pelleting applications where conditioning temperatures exceed 85°C.
- Tablets:Compressed bolus formats serve niche ruminant applications requiring slow-release nutrient delivery over extended periods.
Share concentrates in powder; automation pressures are elevating liquid uptake fastest.
End User:
Feed conversion economics and regulatory compliance burdens vary sharply across livestock species.
- Poultry:Broiler and layer operations drive the steepest premix specification adjustments due to cage-free mandates and feed conversion optimization programs. Integrators across Georgia, Alabama, and Arkansas are consolidating vitamin procurement through multi-year supply agreements.
- Ruminants:Beef feedlots and dairy operations in the U.S. Midwest maintain large-scale contracts for Vitamin E and B-complex premixes. The EPA's emerging nutrient discharge regulations in the Chesapeake Bay watershed are triggering ration redesigns that cascade into vitamin premix adjustments.
- Swine:Sow and finishing operations in the Corn Belt require balanced B-vitamin supplementation to optimize litter performance and growth rates; porcine epidemic diarrhea recovery protocols have elevated biosecurity requirements for premix sourcing.
- Aquaculture:Salmonid and shrimp operations in British Columbia and the U.S. Gulf Coast represent a nascent but specification-intensive segment requiring water-stable vitamin C derivatives.
Contract value peaks in poultry; aquaculture presents the steepest expansion trajectory.
Distribution Channel:
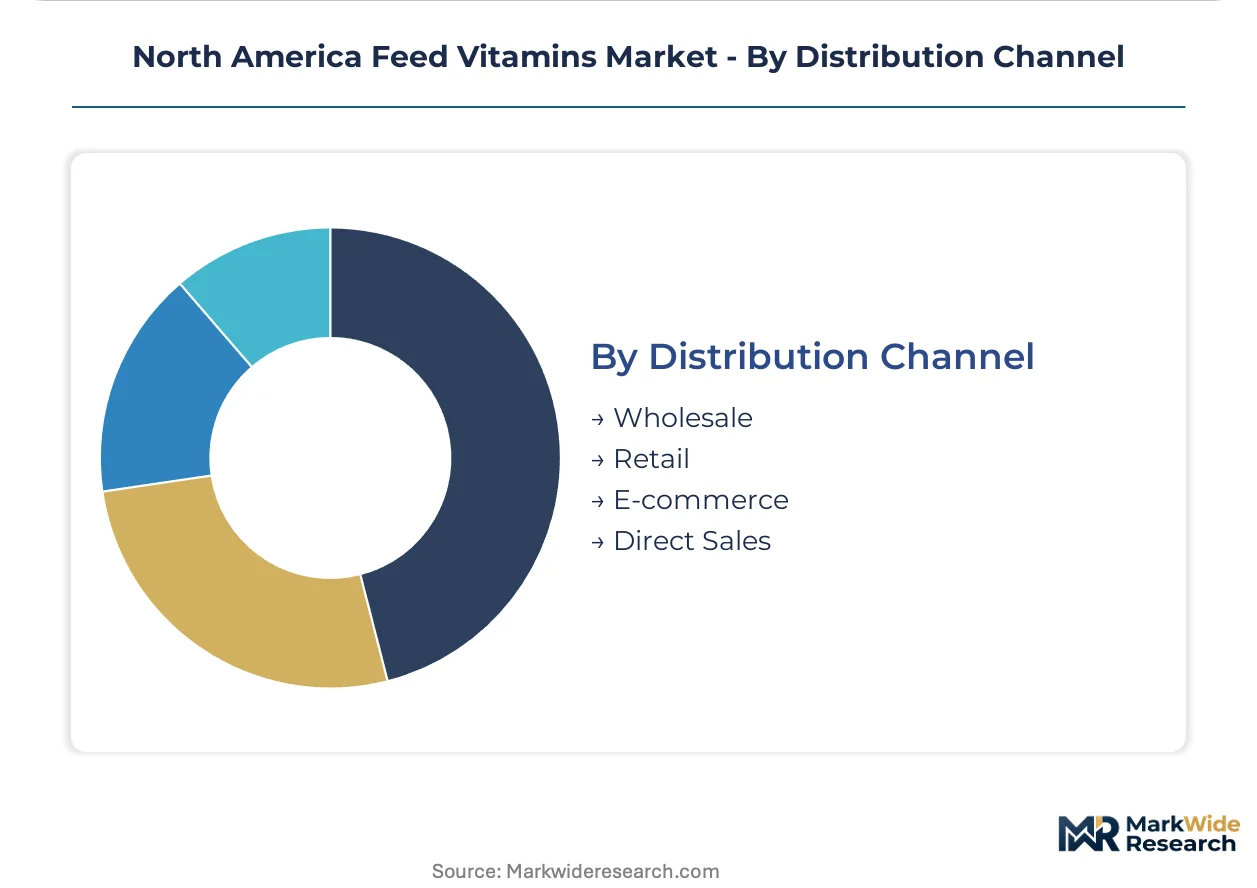
Procurement scale and technical service requirements determine channel selection across buyer tiers.
- Wholesale:Regional feed distributors aggregate demand from mid-sized independent mills across the U.S. Midwest and Canadian prairies. Wholesale channels maintain inventory positions for standard vitamin premix specifications with 2-4 week lead times.
- Direct Sales:Major protein companies negotiate standalone formulation consulting and supply contracts with integrated premix manufacturers. Cargill Inc. and DSM Nutritional Products AG deploy captive technical service teams for direct accounts exceeding 10,000-ton annual premix volumes.
- Retail:Farm supply cooperatives and local distributors serve smaller livestock operations with bagged premix and vitamin supplement products.
- E-commerce:Digital procurement platforms are emerging for specialty vitamin formulations and emergency replenishment orders, though feed-grade bulk transactions remain concentrated in established channels.
Volume flows through wholesale; advisory bundling is concentrating direct sales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States production capacity outstrips domestic consumption across several vitamin categories, while Canadian and Mexican markets rely on cross-border supply chains for premix formulations. This production-consumption divide shapes procurement patterns and regulatory harmonization priorities across the continent.
United States
Midwestern concentrated animal feeding operations in Iowa and Nebraska drive bulk vitamin procurement through multi-year supply agreements. The FDA's Food Safety Modernization Act mandates hazard analysis and preventive controls for medicated feed mills, elevating certification requirements for premix manufacturers. Poultry integrators across Georgia, Alabama, and Arkansas are expanding vitamin D3 supplementation programs to meet cage-free housing mandates in California and Massachusetts.
Canada
Alberta and Saskatchewan cattle feeding operations remain underpenetrated for custom vitamin premix services relative to U.S. Corn Belt intensity. The Canadian Food Inspection Agency's Feed Program maintains parallel oversight to FDA requirements, creating cross-border compliance symmetry. British Columbia salmonid aquaculture operations represent a specification-intensive segment requiring water-stable vitamin C derivatives for feed applications.
Mexico
Poultry and swine operations in Guanajuato and Jalisco states are consolidating feed additive procurement through integrated supply chains. Mexico's national food safety authority enforces feed-grade vitamin import standards aligned with international Codex guidelines. Monterrey-based feed mills are expanding automated dosing infrastructure for liquid micro-encapsulated vitamin formulations.
North America Feed Vitamins Market Competitive Landscape
Top-tier vendors anchor the integrated premix manufacturing tier, while regional distributors and specialty formulators occupy mid-market positions. The vendor structure concentrates around backward-integrated grain processors and chemical synthesis specialists with captive technical service capabilities. Three archetypes dominate: biotechnology-driven metabolite developers, chemical synthesis multinationals spanning pharmaceutical and nutrition applications, and grain-origination players with captive premix networks. Competitive moves center on multi-year volume-commitment contracting and subscription-based advisory bundling that separates technical service from commodity supply.
Among European-headquartered multinationals, BASF SE and DSM Nutritional Products AG exemplify the chemical synthesis and biotechnology archetypes respectively. Cargill Inc. anchors the grain-origination integrated model through its Corn Belt manufacturing presence. These three occupy positions that represent the dominant competitive vectors: synthesis expertise, biotech R&D pipelines, and upstream agricultural supply control.
| Leading Market Players |
|---|
| Adisseo |
| Archer Daniels Midland Co. |
| BASF SE |
| Brenntag SE |
| Cargill Inc. |
| DSM Nutritional Products AG |
| Evonik Industries |
| Lonza Group Ltd. |
| Nutreco N.V. |
| Others |
Value Network & Pricing Analysis
Micro-encapsulation technology adoption across automated dosing systems is compressing cost structures for liquid vitamin variants while simultaneously concentrating procurement power among integrators with capital to deploy precision infrastructure. This dual shift rewards backward-integrated suppliers with captive manufacturing networks and squeezes commodity traders dependent on spot-market powder volumes.
Pricing Analysis
Cost-down pressure on standard powder premixes accelerates as Midwestern concentrated animal feeding operations consolidate procurement through multi-year volume-commitment contracts. Three-tier pricing structure across certified-premium, FSMA-compliant-standard, and economy-grade levels differentiates suppliers by regulatory tier and technical service bundling. Pricing pressure stems from Chinese acetate intermediate volatility feeding into Vitamin A and E synthesis costs. Mid-sized independent feed mills exhibit highest price sensitivity; large poultry integrators prioritize specification consistency over unit cost.
Supply Chain Analysis
Direct-to-integrator channels handle hyperscale buyer demand across the Corn Belt, while wholesale distributors aggregate fragmented mid-market demand. Bulk vitamin manufacturing concentrates in China, with Shandong and Zhejiang provinces supplying acetate precursors and retinol intermediates. Raw material dependencies rest on petrochemical derivatives for Vitamin E synthesis and corn-derived fermentation feedstocks for B-complex vitamins. Single-source geographic concentration creates tariff exposure and logistics chokepoint risk. Distribution runs through captive premix networks anchored by grain-origination players and independent regional formulators serving spot-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FSMA compliance infrastructure costs and multi-year contracting discipline force sub-scale formulators toward exit or acquisition.
For Market Incumbents: Extend technical service bundling into subscription-based advisory relationships to lock in switching costs against commodity traders. Deepen backward integration into grain origination across Iowa and Nebraska to secure captive premix volume. Invest in micro-encapsulation R&D to defend premium positioning as automated dosing penetration accelerates in southeastern poultry operations. For New Entrants and Emerging Players: Capture underpenetrated custom premix demand in Alberta and Saskatchewan cattle feeding operations where Corn Belt intensity has not yet reached. Target aquaculture specification intensity in British Columbia salmonid operations requiring water-stable vitamin C derivatives. Lead with regulatory advisory capabilities to differentiate from commodity suppliers in cross-border FDA-CFIA certification complexity. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale formulators possessing captive FSMA-certified manufacturing and established technical service teams given accelerated procurement desk consolidation at major protein companies. Long-term viability favors assets with backward integration into grain supply and automated dosing formulation capabilities. Monitor cage-free mandate expansion beyond California and Massachusetts as volume inflection signal for Vitamin D3-specialized suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Corn Belt captive supply secures premix volume commitment and compresses input cost variance. |
| FSMA-Certified Manufacturing Scale-Up | FDA hazard analysis compliance opens multi-year contracting with integrated poultry operations. |
| Micro-Encapsulation Technology Licensing | Heat-stable vitamin variants penetrate pelleted feed applications above 85°C conditioning thresholds. |
| Subscription Advisory Service Launch | Recurring revenue structure monetizes nutritional consulting beyond commodity vitamin transactions. |
| Cross-Border Certification Harmonization | Parallel FDA and CFIA audit streamlining reduces duplicative compliance burden for dual-market suppliers. |
Research Methodology
Independent corroboration across feed mill procurement directors, premix formulation chemists, and regulatory compliance officers underwrites the qualitative findings. Primary interviews with DSM Nutritional Products AG and Cargill Inc. technical service teams, alongside regional distributor account managers, captured contracting dynamics and specification evolution. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, CFIA Feed Program bulletins, USDA Agricultural Marketing Service quality verification standards, and SEC 10-K disclosures from listed nutrition companies. Bottom-up volume estimates from state-level feed production statistics and top-down value reconciliation against customs trade data established analytical triangulation.
Comparable-period anchoring to historical vitamin premix consumption patterns across the analysis window informed projection elasticity assumptions. The forecast framework modeled segmentation across product type, formulation technology, livestock species end-use, and distribution channel economics. CAGRs were derived from regression analysis of procurement contract volumes and specification rate changes. Key inputs included cage-free housing mandate implementation timelines, FSMA compliance infrastructure buildout rates, and micro-encapsulation technology adoption curves in automated dosing systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese supply chain disruptions and EPA nutrient discharge regulation stringency. Practitioners should monitor state-level phosphorus management rulemaking and layer housing welfare mandate expansion for early signals of premix specification adjustment cascades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market