
 Riboflavin Market | 2026-2036
Riboflavin Market Size, Share, and Industry Trends Forecast 2026-2036
Riboflavin Market Analysis
Multi-source fermentation procurement is restructuring supply security across the riboflavin value chain. BASF SE leverages its integrated biotechnology platform to sustain European pharmaceutical-grade output. Zhejiang Medicine Co. Ltd. anchors bulk feed-grade production through scaled fermentation infrastructure in eastern China. Koninklijke DSM NV differentiates via synthetic biology pathways that compete on yield efficiency against traditional microbial methods.
Riboflavin, also designated vitamin B2, functions as an essential water-soluble micronutrient with a characteristic yellow-orange crystalline structure synthesized primarily through microbial fermentation of Bacillus subtilis or Ashbya gossypii. Industrial production targets fortification of wheat flour, dairy analogues, and premix formulations where thermal stability below 120°C governs application viability. Feed Grade dominates volume throughput due to concentrated demand from poultry and swine nutrition programs, while Pharmaceutical Grade captures disproportionate margin pools through USP and EP certification requirements. Dietary Supplements represents the fastest-expanding application channel as direct-to-consumer brands bypass traditional food manufacturer intermediaries.
China's SAMR enforces GB 14751 food additive standards that restrict synthetic riboflavin purity thresholds, while India's FSSAI mandates wheat flour fortification under its national nutrition strategy. The US FDA classifies riboflavin as GRAS for food applications but requires pharmaceutical-grade material to meet USP monograph specifications for tablet and injectable formulations. Stakeholders must monitor fermentation feedstock cost volatility and evolving fortification mandates across Asia-Pacific nutrition programs.
Market Dynamics
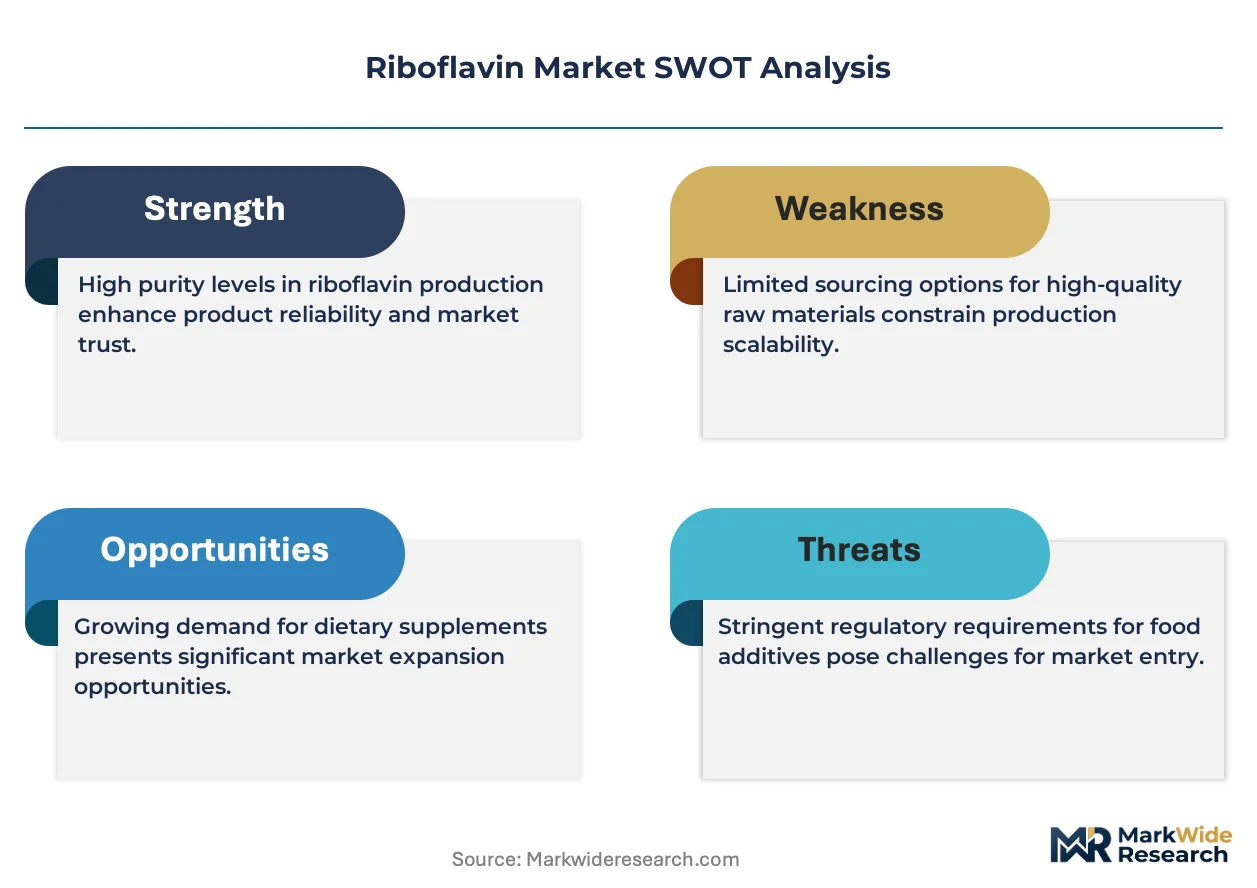
Fermentation feedstock volatility and divergent purity mandates across pharmaceutical and feed-grade channels are compressing margin structures while forcing producers to maintain dual-certification production lines.
Growth Catalysts
- FSSAI wheat flour fortification mandates:India's national nutrition strategy mandates riboflavin inclusion in staple grains, creating institutional procurement pull from millers and premix formulators.
- Direct-to-consumer supplement brands:E-commerce distribution enables bypass of traditional food manufacturer intermediaries, accelerating pharmaceutical-grade volume throughput.
- Microbial yield optimization:Continuous fermentation process improvements in Bacillus subtilis strains are reducing unit production costs for bulk feed-grade material.
Market Restraints
- Feedstock cost volatility:Corn steep liquor and glucose syrup prices fluctuate with agricultural commodity cycles, squeezing fermentation economics.
- Supply concentration in eastern China:Jiangsu and Zhejiang provinces host disproportionate fermentation capacity, exposing buyers to single-region disruption risk.
- Thermal degradation ceiling:Riboflavin's instability above 120°C limits high-temperature food processing applications without microencapsulation investment.
Strategic Opportunities
- Synthetic biology pathway adoption:Engineered Ashbya gossypii strains offer yield efficiency gains over conventional microbial methods for pharmaceutical-grade output.
- Premix formulation partnerships:Direct supply relationships with wheat flour millers in India bypass distributor markups and secure volume commitments.
- Clean-label positioning:Fermentation-derived natural riboflavin commands premium positioning against synthetic alternatives in European dietary supplement channels.
Industry Challenges
- Dual certification complexity:Maintaining simultaneous USP, EP, and GB 14751 compliance requires parallel quality systems and extended audit timelines.
- Specialized fermentation talent scarcity:Industrial microbiology expertise for large-scale vitamin production concentrates at legacy producers, constraining new entrant scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riboflavin Market |
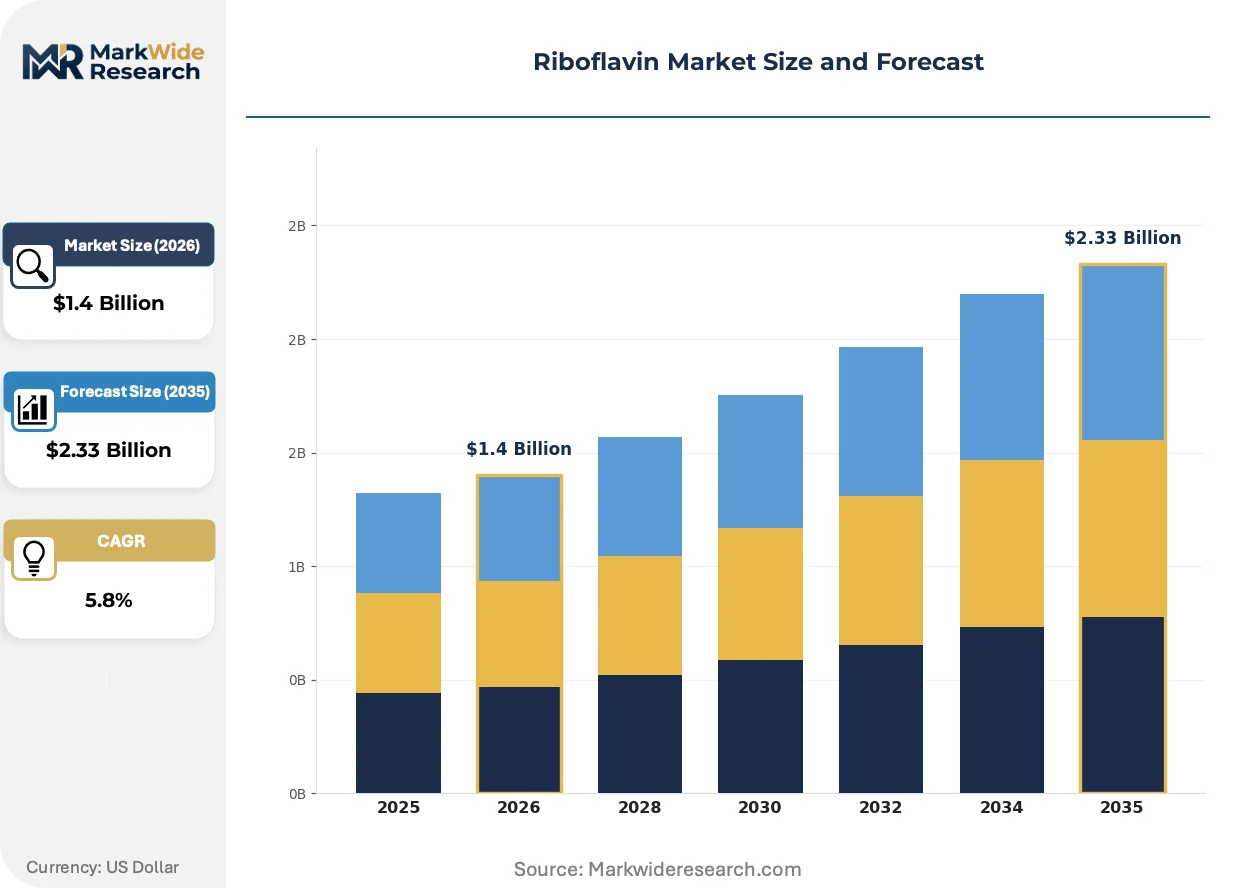
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Feed Grade, Pharmaceutical Grade, Cosmetic Grade Application: Dietary Supplements, Animal Feed, Food Fortification, Nutraceuticals End User: Food Manufacturers, Pharmaceutical Companies, Dietary Supplement Brands, Pet Food Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Shanghai Acebright Pharmaceuticals Group Co. Ltd., Shandong NB Group Co. Ltd., BASF SE, Zhejiang Medicine Co. Ltd., Hebei Shengxue Dacheng Pharmaceutical Co. Ltd., Koninklijke DSM NV, Xinfa Pharmaceutical Co. Ltd., Ningxia Qiyuan Pharmaceutical Co. Ltd., Hubei Guangji Pharmaceutical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riboflavin Market Emerging Trajectories
Biotechnology platforms and regulatory fortification mandates are restructuring how riboflavin is produced, certified, and distributed across pharmaceutical and nutritional channels.
Synthetic biology engineering of microbial chassis is decentralizing production economics away from traditional fermentation strongholds. Startups and mid-scale biotech firms are adopting CRISPR-optimized Bacillus subtilis strains to achieve pharmaceutical-grade yields without billion-liter fermentation infrastructure. This capability diffusion is compressing the capital barrier between feed-grade commodity supply and high-margin certified output.
REACH registration requirements for food additive imports are tightening purity documentation burdens on non-European suppliers. The European Chemicals Agency's expanded substance evaluation protocols now demand comprehensive impurity profiling for riboflavin destined for infant nutrition and medical food applications. German and Dutch premix formulators are consolidating supplier bases to reduce compliance audit overhead.
Subscription-based supplement distribution is fragmenting buyer concentration across direct-to-consumer channels. Brands bypass traditional pharmaceutical wholesale networks through vertically integrated e-commerce platforms, compressing distributor margins while demanding smaller batch sizes with faster turnaround. This channel shift is most pronounced in North American and Western European metropolitan markets where millennial and Gen-Z consumers drive trial-oriented purchasing patterns.
Riboflavin Market Segmentation
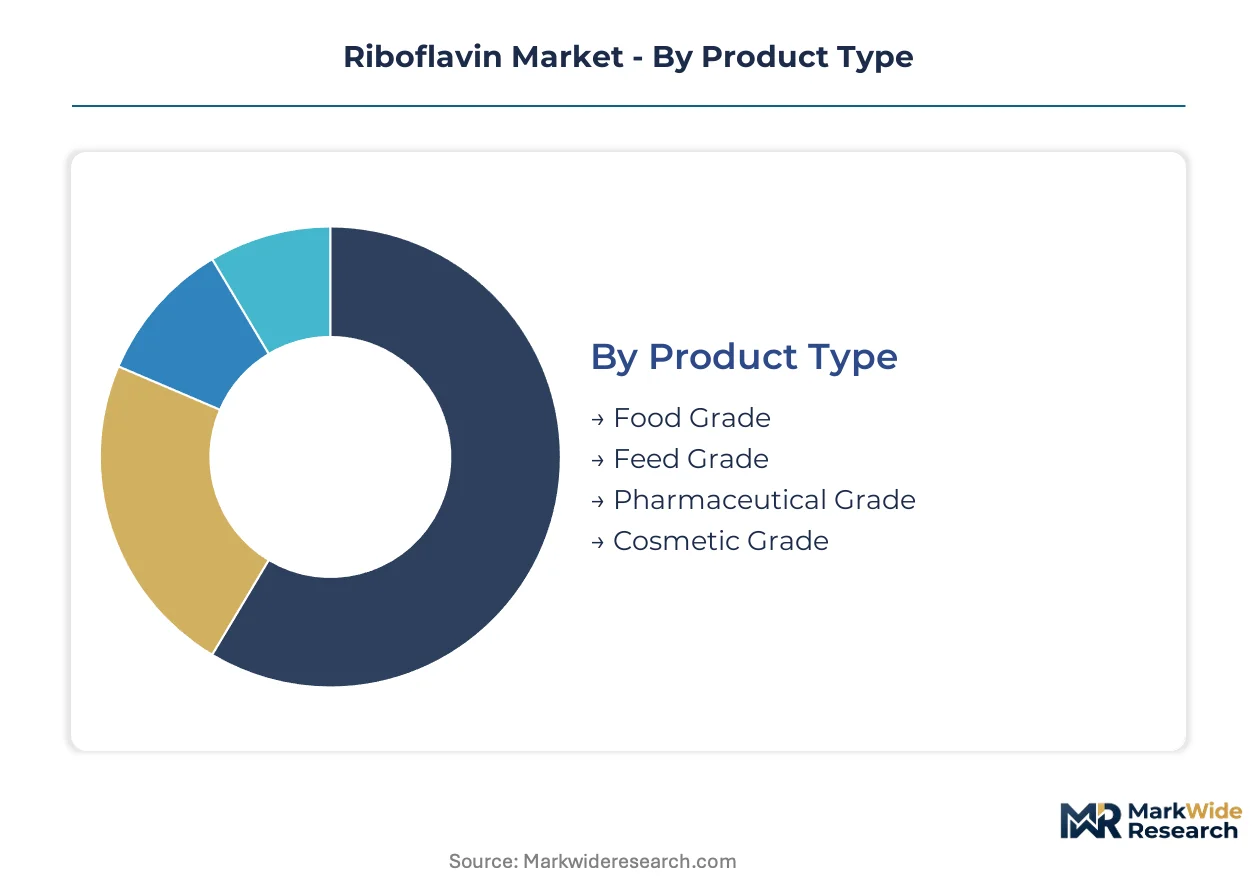
Riboflavin segmentation reflects divergent purity mandates and margin structures across nutritional, pharmaceutical, and feed channels. Each grade demands distinct certification pathways, fermentation protocols, and customer procurement behaviors that reshape competitive positioning.
Product Type:
Volume throughput concentrates in commodity grades while pharmaceutical and cosmetic specifications capture disproportionate margin pools.
- Feed Grade:Standardized powder or granule formulations meeting minimum 96% purity for poultry and swine nutrition programs. Demand clusters in Jiangsu province fermentation facilities serving integrated livestock operations across China and Southeast Asia, with procurement tied to volatile corn steep liquor feedstock economics.
- Pharmaceutical Grade:USP and EP-certified crystalline material exceeding 98% purity with comprehensive impurity profiling for tablet and injectable formulations. Direct-to-consumer supplement brands in North America and Western Europe drive volume expansion through e-commerce channels bypassing traditional pharmaceutical wholesale networks.
- Food Grade:GB 14751-compliant formulations for wheat flour and dairy analogue fortification with thermal stability specifications below 120°C. India's FSSAI mandates institutional procurement from domestic millers.
- Cosmetic Grade:Ultra-pure riboflavin for topical formulations and hair care applications with enhanced solubility profiles. European personal care manufacturers specify REACH-registered material with full substance evaluation documentation.
Today's leader: Feed Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Fortification mandates and channel fragmentation are redistributing volume across institutional and consumer-facing endpoints.
- Animal Feed:Concentrated premix incorporation for broiler and layer poultry operations requiring standardized vitamin premixes. China's Ministry of Agriculture and Rural Affairs enforces additive inclusion rates in commercial feed formulations.
- Dietary Supplements:Direct-to-consumer brands in subscription and e-commerce distribution expanding fastest. Millennial and Gen-Z purchasing patterns in US metropolitan markets favor trial-oriented, smaller-batch procurement.
- Food Fortification:Wheat flour and edible oil mandatory enrichment programs under India's national nutrition strategy creating institutional pull from millers and government procurement channels.
- Nutraceuticals:Functional food positioning in medical food and infant nutrition segments demanding EFSA-compliant purity documentation for European market access.
Animal Feed anchors current volume. Dietary Supplements climb the fastest.
End User:
Procurement sophistication varies sharply between formulated goods manufacturers and direct retail brands.
- Food Manufacturers:Industrial-scale millers and dairy processors sourcing GB 14751 or FSSAI-compliant material for mandatory fortification programs. Procurement concentrates through annual contracts with Zhejiang and Jiangsu fermentation clusters.
- Dietary Supplement Brands:Vertically integrated e-commerce operators demanding USP-certified pharmaceutical-grade material with rapid batch turnaround and flexible MOQs.
- Pharmaceutical Companies:Tablet and injectable formulators requiring EP monograph compliance with extended audit timelines and parallel quality systems.
- Pet Food Producers:Premium companion animal nutrition brands specifying human-grade riboflavin for clean-label positioning in North American and European markets.
Food Manufacturers dominate procurement scale. Dietary Supplement Brands reshape contract structures.
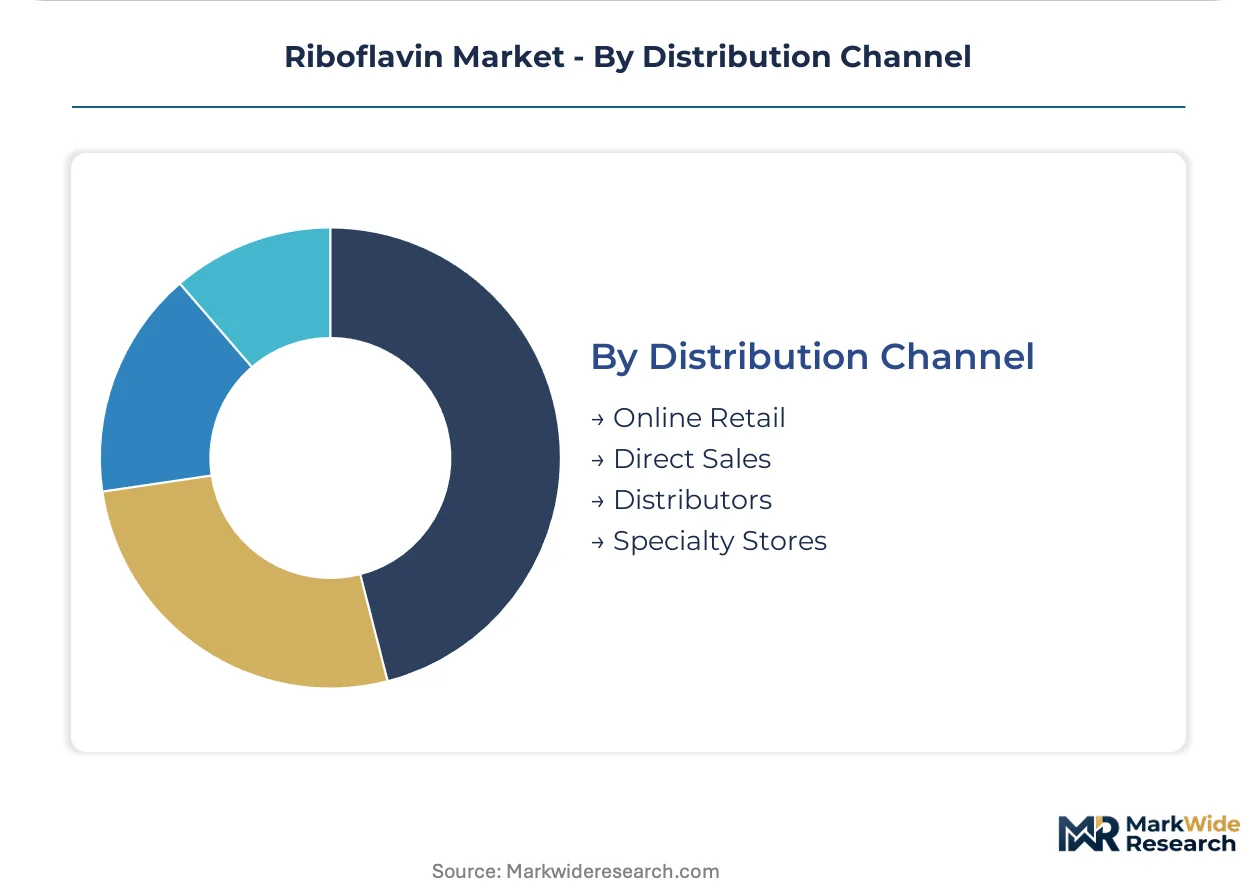
Distribution Channel:
Channel economics fragment as direct relationships displace traditional distributor intermediaries.
- Direct Sales:Long-term supply agreements between fermentation producers and wheat flour millers or pharmaceutical formulators securing volume commitments and bypassing distributor markups.
- Online Retail:Amazon, iHerb, and direct brand storefronts enabling supplement brands to reach consumers without wholesale intermediaries, compressing traditional margin structures.
- Distributors:Regional chemical and ingredient distributors serving mid-scale food manufacturers with inventory management and technical support services.
- Specialty Stores:Health food retailers and professional supplement dispensaries catering to practitioner-channel brands with practitioner-exclusive formulations.
Direct Sales retains volume concentration. Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor fermentation capacity for pharmaceutical and feed-grade riboflavin, with regulatory fortification mandates in India and China reshaping procurement patterns across Asia-Pacific. India's FSSAI wheat flour fortification creates institutional demand pull, while European REACH documentation requirements tighten purity standards for imported material.
China
Jiangsu and Zhejiang fermentation clusters supply the majority of global feed-grade and pharmaceutical-grade riboflavin through scaled microbial production infrastructure. SAMR enforces GB 14751 food additive standards that restrict synthetic riboflavin purity thresholds and impurity profiles. Xinfa Pharmaceutical Co. and Ningxia Qiyuan Pharmaceutical anchor bulk production in these eastern provinces, serving domestic millers and export markets.
India
FSSAI mandates wheat flour fortification under the national nutrition strategy, creating institutional procurement pull from millers and premix formulators across Maharashtra and Gujarat. The central government's subsidy programs for fortified staples accelerate volume commitments from domestic fermentation suppliers. Punjab and Haryana wheat belts concentrate demand for food-grade riboflavin premixes distributed through government channels.
Germany
BASF SE maintains pharmaceutical-grade output through integrated biotechnology platforms serving European tablet and injectable formulators. ECHA REACH registration requirements demand comprehensive impurity profiling for riboflavin destined for infant nutrition and medical food applications. The Rhine-Ruhr industrial corridor hosts specialized premix formulators consolidating supplier bases to reduce compliance audit overhead.
United States
FDA classifies riboflavin as GRAS for food applications while requiring USP monograph compliance for pharmaceutical-grade material in tablet and injectable formulations. Direct-to-consumer supplement brands in metropolitan markets bypass traditional pharmaceutical wholesale networks through vertically integrated e-commerce platforms. New Jersey and North Carolina pharmaceutical manufacturing clusters drive demand for certified raw material with rapid batch turnaround.
Netherlands
Koninklijke DSM NV leverages synthetic biology pathways that compete on yield efficiency against traditional microbial fermentation methods. EFSA-compliant purity documentation requirements govern riboflavin for European nutraceutical and functional food applications. The Rotterdam-Antwerp chemical corridor concentrates premix formulation expertise serving fortified food manufacturers across the European Union.
Riboflavin Market Vendor Landscape
Global majors compete with regional champions across certification-grade tiers, with European pharmaceutical specialists and Chinese fermentation giants occupying distinct margin pools. The market structures around three archetypes: integrated biotechnology platforms pursuing synthetic biology pathways, scaled fermentation operators optimizing Bacillus subtilis yields, and regional premix formulators securing government fortification contracts. Capacity expansion in eastern China and strategic partnerships with Indian wheat millers represent the dominant competitive moves reshaping supply security.
Within the integrated biotechnology tier, Koninklijke DSM NV and BASF SE exemplify European pharmaceutical-grade positioning through advanced microbial engineering capabilities. Among Chinese fermentation specialists, Zhejiang Medicine Co. and Shanghai Acebright Pharmaceuticals Group occupy the scale-driven end, anchoring bulk feed-grade and food-grade supply for Asia-Pacific fortification programs. These players represent contrasting archetypes: yield-optimized synthetic biology versus traditional fermentation infrastructure serving divergent certification requirements.
| Leading Market Players |
|---|
| Shanghai Acebright Pharmaceuticals Group Co. Ltd. |
| Shandong NB Group Co. Ltd. |
| BASF SE |
| Zhejiang Medicine Co. Ltd. |
| Hebei Shengxue Dacheng Pharmaceutical Co. Ltd. |
| Koninklijke DSM NV |
| Xinfa Pharmaceutical Co. Ltd. |
| Ningxia Qiyuan Pharmaceutical Co. Ltd. |
| Hubei Guangji Pharmaceutical Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Industrial microbiology expertise concentrated in Jiangsu and Zhejiang provinces feeds directly into pricing-tier spreads across certification grades, with fermentation talent scarcity widening the cost gap between pharmaceutical-grade and feed-grade output as producers compete for limited technical personnel.
Pricing Analysis
Input-cost pass-through from volatile corn steep liquor and glucose syrup prices runs through contract structures for feed-grade material, while pharmaceutical-grade pricing stratifies across USP, EP, and GB 14751 certification tiers with impurity profiling premiums. Price differentiation hinges on fermentation yield efficiency and dual-certification overhead, with feed-grade buyers exhibiting highest sensitivity to agricultural commodity cycles. Cost compression in bulk feed channels is intensifying as microbial yield improvements outpace certification-grade margin expansion.
Supply Chain Analysis
Riboflavin supply rests on fermentation capacity concentrated in China, India, and the Netherlands, with Bacillus subtilis and Ashbya gossypii strain development drawing from specialized microbial culture collections and synthetic biology platforms. Corn steep liquor, glucose syrup, and engineered microbial chassis constitute critical input dependencies. Single-region vulnerability in eastern China exposes buyers to disruption risk from environmental compliance actions or feedstock logistics constraints. Distribution runs through direct long-term offtake agreements with wheat flour millers and pharmaceutical formulators, supplemented by regional chemical distributors serving mid-scale food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through synthetic biology yield improvements that compress unit costs for pharmaceutical-grade output while premium-tier demand from direct-to-consumer supplement brands strengthens pricing power.
For Market Incumbents: Lock in fermentation talent pools through specialized training partnerships with Jiangsu and Zhejiang technical institutes, insulating against synthetic biology startup encroachment. Secure backward integration into corn steep liquor sourcing through captive supply arrangements with agricultural processors in North China Plain feedstock regions. Prioritize dual-certification capacity expansion to capture FSSAI wheat flour fortification procurement and REACH-registered European nutraceutical demand simultaneously.
For New Entrants and Emerging Players: Subscription-based e-commerce channels offer the most penetrable route for pharmaceutical-grade riboflavin, bypassing distributor markups and established wholesale networks that incumbent fermentation giants dominate. Target direct-to-consumer supplement brands in North American metropolitan markets with smaller-batch, rapid-turnaround USP-certified material. Pursue clean-label positioning through fermentation-derived natural riboflavin certification to command premium positioning against synthetic alternatives in European channels.
For Investors and Strategic Acquirers: Pharmaceutical formulators with vertical integration ambitions are the most active acquirer in this space, seeking captive riboflavin supply for tablet and injectable manufacturing. Mid-scale synthetic biology firms with CRISPR-optimized microbial chassis represent the priority acquisition archetype over legacy fermentation infrastructure. Watch for FSSAI enforcement acceleration in Indian wheat belts as the inflection signal indicating institutional procurement volume commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Biology Pathway Adoption | Engineered Ashbya gossypii strains from Koninklijke DSM NV compete on yield efficiency against traditional Bacillus subtilis fermentation methods. |
| Backward Integration into Feedstock Supply | Captive corn steep liquor sourcing from North China Plain agricultural processors insulates fermentation economics from commodity volatility. |
| Dual-Certification Capacity Expansion | Simultaneous USP, EP, and GB 14751 compliance enables access to Indian FSSAI wheat flour fortification and European REACH-registered nutraceutical channels. |
| Premix Formulation Partnerships | Direct supply relationships with Maharashtra and Gujarat wheat millers bypass distributor markups and secure government procurement volume commitments. |
| Clean-Label Positioning Investment | Fermentation-derived natural riboflavin certification commands premium positioning against synthetic alternatives in European dietary supplement channels. |
Methodological Framework
Bottom-up dietary supplement and animal feed demand modeling reconciled against top-down fermentation capacity tracking forms the analytical core, combining primary interviews with plant managers at Jiangsu and Zhejiang production facilities, procurement leads at Indian wheat flour millers, regulatory affairs specialists navigating FSSAI and SAMR compliance, and technical R&D directors optimizing microbial yields. Secondary validation draws from customs and trade data for riboflavin import-export flows, SAMR GB 14751 enforcement disclosures, FSSAI fortification mandate progress reports, and SEC filings from listed fermentation specialists.
The input-output matrix framing connects fermentation feedstock consumption rates to downstream grade-specific demand across pharmaceutical, food, and feed channels. Segmentation dimensions span certification tier, end-use application, and regional regulatory cluster. CAGRs were derived through growth-rate reconciliation across independent bottom-up and top-down estimates. Forecast inputs incorporate microbial yield improvement trajectories, fortification mandate implementation timelines, and synthetic biology platform adoption curves.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-optimized microbial chassis would alter the outlook if yield efficiency gains outpace projected timelines. Forecasts reflect assumptions regarding FSSAI enforcement consistency, REACH documentation burden evolution, and corn steep liquor price stability. A small set of triggers—synthetic biology startup scaling, eastern China environmental compliance actions, and Indian government subsidy program adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Micronutrients Market