
 Asia-Pacific Vitamin a Market | 2026-2036
Asia-Pacific Vitamin a Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vitamin a Market Outlook
Asset-light toll manufacturing and third-party fermentation leasing is tilting competitive dynamics toward specialists that avoid capital-heavy retinol synthesis plants. DSM leverages backward integration into beta-carotene precursors to sustain margin control across the value chain. Zhejiang NHU Co. Ltd. anchors its position through captive supply of citral intermediates for Vitamin A aldehyde production. BASF competes via technology leadership in continuous-flow esterification processes that reduce solvent waste.
Vitamin A comprises a group of fat-soluble retinoids including retinol, retinal, and retinyl esters synthesized industrially through beta-ionone cyclization or extracted from fish liver oils and plant carotenoids. The compound serves primarily as an essential micronutrient for vision function, immune response, and epithelial tissue maintenance in human and animal systems. Synthetic palmitate dominates volume flows into animal nutrition applications where feed producers prioritize cost-stable dosing against fluctuating carotenoid prices. Natural-source segments occupy narrower but higher-margin positions in pharmaceutical-grade formulations where regulators enforce stricter impurity profiles. Food fortification applications represent the fastest-expanding demand pool as government-mandated programs proliferate across South and Southeast Asia.
China's NMPA enforces GB standards for pharmaceutical-grade retinol purity that constrain import eligibility for non-compliant suppliers. India's FSSAI fortification directives for cooking oils and milk create compliance-driven procurement obligations for domestic food processors and distributors. Japan's MHLW maintains JIS-aligned specifications for supplement-labeling accuracy that shape formulation choices by dietary supplement manufacturers. Stakeholders must monitor how diverging national purity standards affect cross-border formulation registration and batch-release timelines.
Market Dynamics
India's FSSAI fortification mandates for edible oils and dairy are restructuring procurement obligations across the Asia-Pacific Vitamin A value chain, forcing synthetic suppliers to reconfigure batch-release protocols and domestic food processors to absorb compliance-driven input costs.
Growth Catalysts
- FSSAI Oil Fortification Directives:India's mandatory Vitamin A dosing for cooking oils creates procurement obligations for domestic refiners and expands the addressable base for acetate and palmitate suppliers.
- Feed-Grade Cluster Expansion:Shandong and Zhejiang provinces anchor production gravity for livestock nutrition applications, with export contracts extending into Southeast Asian poultry operations.
- Synthetic Retinoid Cost Stability:Feed producers prioritize palmitate formulations over fluctuating natural carotenoid prices, locking in volume commitments with toll manufacturers.
Market Restraints
- GB Standard Purity Barriers:China's NMPA pharmaceutical-grade specifications constrain import eligibility for non-compliant foreign suppliers, fragmenting cross-border registration pathways.
- Citral Intermediate Concentration:Captive supply of this aldehyde precursor sits with a limited set of integrated specialists, creating bottleneck risk for non-backward-integrated formulators.
- Natural-Source Price Volatility:Fish liver oil and plant carotenoid extraction costs swing with marine harvest cycles and agricultural yield variability, compressing margin predictability for premium-grade suppliers.
Strategic Opportunities
- Vietnam and Indonesia Fortification Rollouts:Government-mandated nutrition programs in these underpenetrated markets are expanding the food-grade addressable base beyond India and China.
- Continuous-Flow Esterification Adoption:Solvent-waste reduction technologies are enabling regulatory compliance with China's dual carbon goals while lowering environmental liability for producers.
- Third-Party Fermentation Leasing:Asset-light toll manufacturing models allow specialist entrants to bypass capital-heavy retinol synthesis plants and compete on formulation flexibility.
Industry Challenges
- Retrospective Batch-Release Timelines:Diverging national purity standards across NMPA, FSSAI, and Japan's MHLW force suppliers to maintain parallel testing protocols, extending working capital cycles.
- Cross-Border Formulation Registration Complexity:JIS-aligned supplement-labeling specifications in Japan create friction for Chinese and Indian exporters seeking multi-country product approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vitamin a Market |
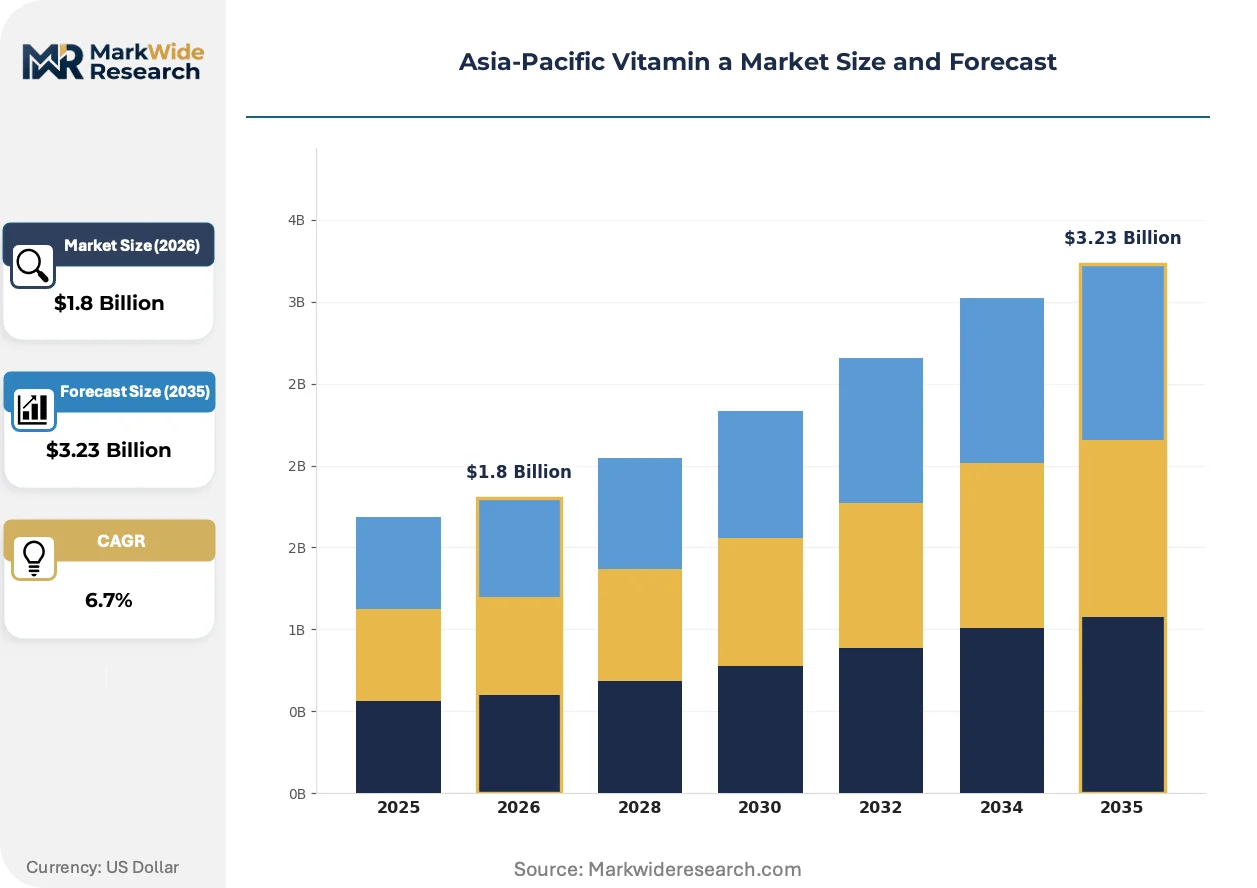
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Palmitate, Acetate Application: Animal Nutrition, Food Fortification, Supplements, Pharmaceuticals End User: Dietary Supplement Manufacturers, Feed Producers, Food Processors, Pharmaceutical Companies Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | DSM, BASF, Zhejiang NHU Co. Ltd., Bluestar Adisseo Co. Ltd., Xiamen Kingdomway Group Co, ZMC Group, Archer Daniels Midland Company, Glanbia plc, Lonza Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vitamin a Market Strategic Shifts
Continuous-flow processing and fermentation-based manufacturing are compressing the traditional batch-reactor model, while regulatory divergence is forcing suppliers to architect parallel compliance systems rather than unified global formulations.
Continuous-flow esterification systems are replacing solvent-intensive batch reactors in synthetic Vitamin A production. Chinese producers in Zhejiang province are adopting these platforms at accelerating pace to meet MEE environmental enforcement. This technology is rendering obsolete the legacy retinol synthesis plants that dominated the 2010s capacity buildout.
FSSAI's edible oil fortification mandates are creating compliance-driven procurement obligations that reshape supplier-customer contracting. Domestic Indian refiners must now source certified retinyl palmitate through approved channels, eliminating spot-market flexibility. The food processing segment is responding by locking in multi-year supply agreements with synthetic specialists who can guarantee batch consistency under CDSCO oversight.
Tablet manufacturers across China and India are consolidating procurement around retinyl palmitate suppliers who offer integrated formulation services. The traditional merchant-chemical model—selling isolated active ingredients—is losing ground to toll-manufactured, ready-to-compress granules. This shift is most visible in Shandong province, where feed-grade and pharmaceutical-grade buyers now demand finished-dosage intermediates rather than raw acetate.
Asia-Pacific Vitamin a Market Segmentation
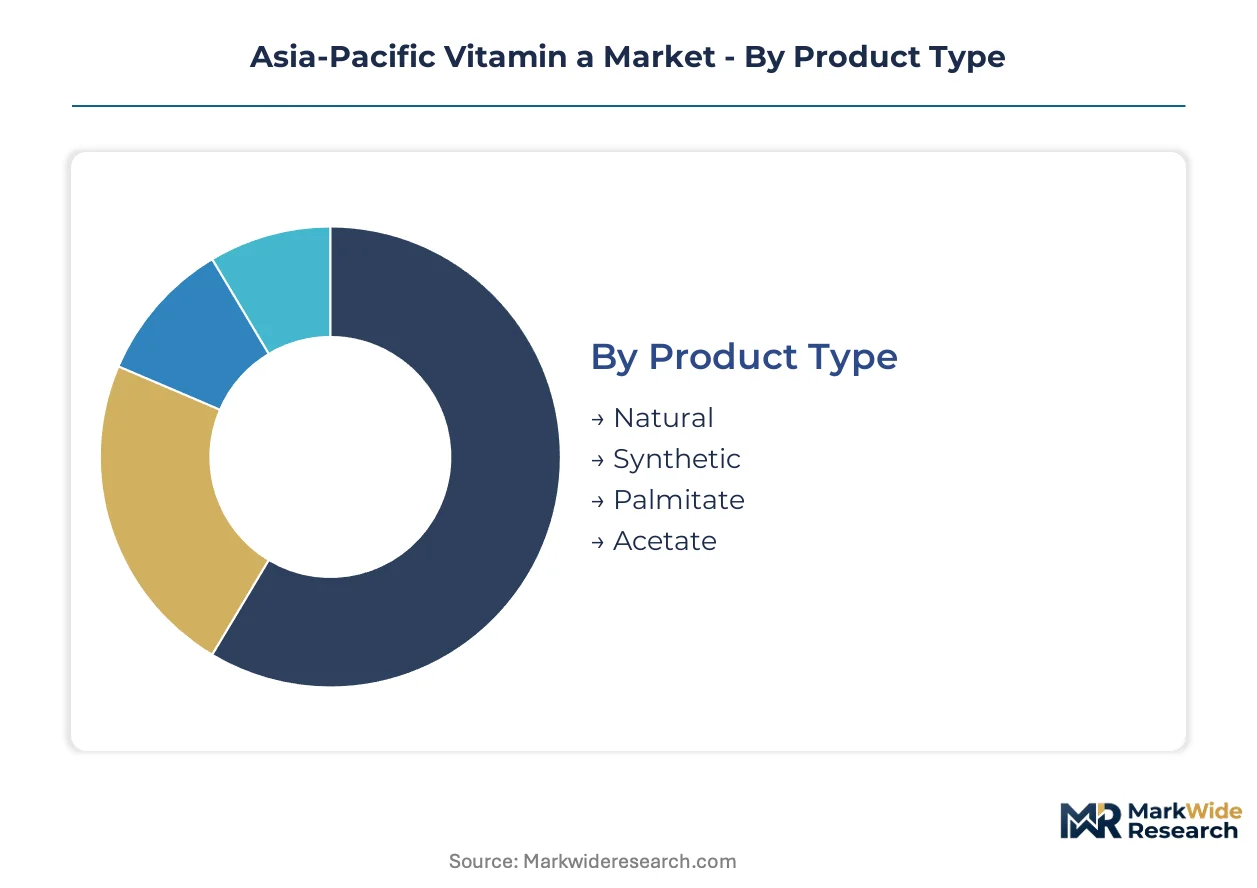
Segmentation in the Asia-Pacific Vitamin A market reveals how divergent purity requirements and end-use specifications fragment procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning across India, China, and Southeast Asia.
Product Type:
Mature synthesis routes dominate volume, while emerging fermentation pathways are carving niche positions in premium applications.
- Synthetic:Retinyl palmitate and acetate produced through beta-ionone cyclization command the bulk of feed-grade and food fortification volumes. Shandong province refiners source synthetic retinoids for livestock operations under cost-stable, long-term contracts that insulate against carotenoid price swings.
- Natural:Fish liver oil and plant carotenoid extracts serve pharmaceutical-grade formulations where NMPA GB standards enforce stricter impurity ceilings than synthetic alternatives permit. India's CDSCO oversight of natural-source batches creates registration friction that limits supplier flexibility.
- Palmitate:The dominant ester form for animal nutrition and food fortification, favored for oxidative stability during high-temperature oil processing.
- Acetate:Preferred for dietary supplement tablets and pharmaceutical formulations requiring precise dosing granularity.
Synthetic handles the majority of throughput; Natural is climbing the fastest on share as pharmaceutical-grade premiums widen.
Application:
Cost tier segmentation separates commodity-scale buyers from premium-grade purchasers with divergent compliance burdens.
- Animal Nutrition:Feed producers across China's livestock belts and Southeast Asian poultry operations constitute the largest volume sink. Palmitate formulations lock in dosing predictability that volatile carotenoid markets cannot match, cementing synthetic supplier relationships.
- Food Fortification:FSSAI-mandated edible oil and dairy dosing in India is expanding the addressable base fastest. Domestic refiners must procure certified retinyl palmitate through approved channels, eliminating spot-market sourcing flexibility.
- Supplements:Tablet manufacturers in China and India are consolidating procurement around suppliers offering toll-manufactured, ready-to-compress granules rather than raw acetate.
- Pharmaceuticals:Ophthalmic and dermatological formulations demand retinol purity levels that constrain import eligibility under NMPA GB standards.
Animal Nutrition handles the majority of throughput; Food Fortification is gaining share fastest.
End User:
Customer type determines whether procurement flows through long-term supply agreements or spot-market flexibility.
- Feed Producers:Concentrated in Shandong and Zhejiang provinces, these buyers prioritize cost-stable synthetic palmitate volumes for livestock and aquaculture operations.
- Food Processors:Indian edible oil refiners face FSSAI compliance obligations that force multi-year contracting with synthetic specialists guaranteeing batch consistency under CDSCO oversight.
- Dietary Supplement Manufacturers:China's tablet formulators are scaling retinyl palmitate procurement while demanding integrated formulation services from toll manufacturers.
- Pharmaceutical Companies:Formulators of ophthalmic solutions and retinoid therapies navigate NMPA purity barriers that fragment cross-border registration pathways.
Feed Producers handle the majority of throughput; Food Processors are expanding most quickly on share.
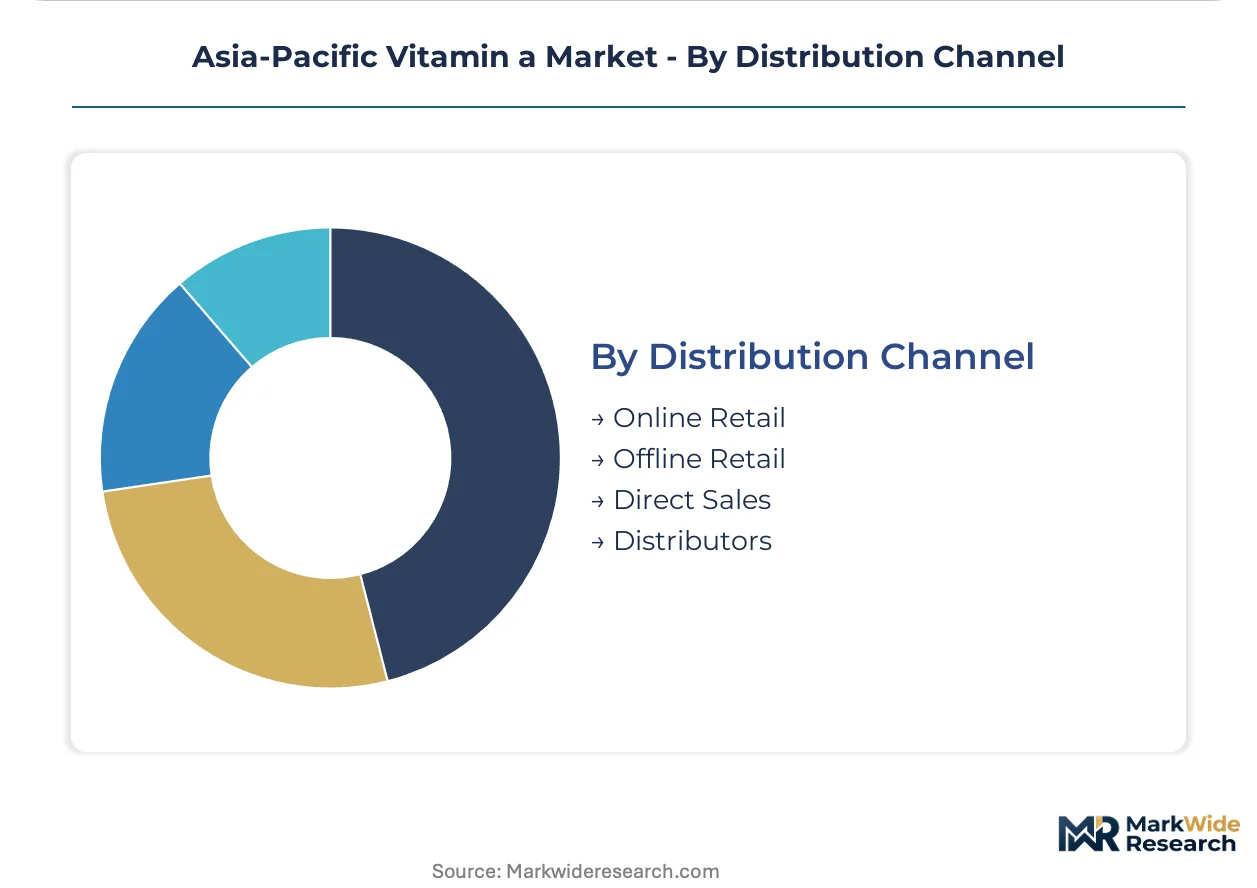
Distribution Channel:
Supply concentration shapes how intermediaries capture value between synthesis plants and end-formulators.
- Distributors:Specialized chemical distributors dominate synthetic Vitamin A flows, managing batch-release documentation for FSSAI and NMPA compliance across fragmented buyer bases.
- Direct Sales:Backward-integrated producers like Zhejiang NHU leverage captive citral supply to bypass intermediaries and contract directly with large feed and food processors.
- Offline Retail:Traditional pharmacy and veterinary supply chains serve supplement and feed-grade buyers in tier-2 and tier-3 Chinese cities.
- Online Retail:E-commerce platforms are emerging for small-volume supplement ingredient procurement, though pharmaceutical and feed-grade volumes resist digital disintermediation.
Distributors handle the majority of throughput; Direct Sales is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI fortification mandates are restructuring procurement obligations across South Asia, while China's NMPA purity barriers and Southeast Asian nutrition programs are fragmenting regulatory pathways. Production clusters in Shandong and Zhejiang provinces anchor supply-side capacity for domestic livestock operations and regional export contracts.
China
Shandong and Zhejiang provinces concentrate feed-grade acetate production for domestic livestock belts and Southeast Asian poultry export contracts. NMPA enforces GB standards for pharmaceutical-grade retinol purity that constrain import eligibility for non-compliant foreign suppliers. Zhejiang-based producers are adopting continuous-flow esterification platforms to meet MEE environmental enforcement.
India
FSSAI mandates for edible oil and dairy fortification are expanding the addressable base for synthetic Vitamin A suppliers and forcing domestic refiners into compliance-driven procurement. CDSCO oversight of natural-source batches creates registration friction that limits supplier flexibility. Maharashtra and Gujarat house the primary food processing clusters absorbing these input costs.
Japan
MHLW maintains JIS-aligned specifications for supplement-labeling accuracy that shape formulation choices by dietary supplement manufacturers. METI industrial policy supports precision fermentation investments for premium-grade applications. The Kanto region around Tokyo concentrates pharmaceutical formulators navigating these purity specifications.
Vietnam
Government-mandated nutrition programs are expanding the food-grade addressable base beyond established Indian and Chinese markets. The country's national pharmaceutical regulator is developing fortification standards modeled on FSSAI precedents. Southern provinces including Dong Nai and Binh Duong are emerging as processing hubs for edible oil fortification.
Indonesia
Ministry of Health directives on staple food fortification are creating new procurement channels for synthetic retinoid suppliers. The central government's nutrition security programs prioritize cost-stable dosing for cooking oil applications. Java-based refiners in Surabaya and Jakarta are locking in multi-year supply agreements with regional specialists.
Asia-Pacific Vitamin a Market Competitive Environment
On the supply side, the industry is consolidating around backward-integrated specialists and asset-light toll manufacturers. The vendor base separates into three strategic archetypes: integrated precursor producers controlling citral intermediates, continuous-flow technology leaders reducing solvent waste, and third-party fermentation lessors bypassing capital-heavy synthesis plants. Dominant competitive moves include captive supply chain control over beta-carotene precursors and technology licensing for environmental compliance.
Among Asia-Pacific-based producers, Zhejiang NHU Co. Ltd. and Bluestar Adisseo Co. Ltd. occupy positions within the integrated precursor tier, while Xiamen Kingdomway Group Co represents the toll-manufacturing archetype. DSM and BASF exemplify multinational technology leaders leveraging continuous-flow processes and backward integration into beta-carotene precursors. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| DSM |
| BASF |
| Zhejiang NHU Co. Ltd. |
| Bluestar Adisseo Co. Ltd. |
| Xiamen Kingdomway Group Co |
| ZMC Group |
| Archer Daniels Midland Company |
| Glanbia plc |
| Lonza Group |
| Others |
Value Chain & Pricing Dynamics
Citral intermediate concentration in Zhejiang and Shandong provinces anchors margin capture at the aldehyde precursor tier, forcing downstream formulators to absorb backward-integrated premiums or accept supply volatility from non-captive sources. This upstream bottleneck stratifies pricing power between integrated specialists and merchant-chemical buyers across feed-grade and pharmaceutical-grade applications.
Pricing Analysis
Certification level creates the primary spread, with NMPA GB-grade retinol commanding substantial premiums over feed-grade palmitate used in livestock operations. Three-tier pricing structure separates pharmaceutical-grade retinol from food-fortification acetate from commodity feed-grade palmitate, with CDSCO and FSSAI compliance costs embedded in the middle tier. Pricing pressure stems from toll-manufacturing competition compressing formulation-service margins, particularly in Shandong province where asset-light entrants undercut legacy synthesis plants. Feed producers exhibit highest price sensitivity, locking in long-term contracts to escape carotenoid volatility, while ophthalmic formulators accept premium pricing for impurity-capped batches.
Supply Chain Analysis
Beta-ionone and citral feedstocks flow predominantly from China, India, and select European specialist producers, with Zhejiang NHU's captive citral operations creating supply security for integrated formulators. Synthetic Vitamin A production rests on petrochemical-derived precursors, fish liver oil harvests, and fermentation-based carotenoid alternatives as primary input streams. Single-source vulnerability concentrates at the citral intermediate tier, where limited backward-integrated specialists control aldehyde supply for retinal synthesis. Distribution runs through specialized chemical distributors managing FSSAI and NMPA batch-release documentation, though direct sales from integrated producers are gaining share among large feed and food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific Vitamin A demand sits in early-cycle expansion, with FSSAI oil fortification mandates and Vietnam-Indonesia program rollouts driving penetration into under-addressed populations.
For Market Incumbents: Harden supply security through captive citral intermediate production or long-term offtake agreements with Zhejiang-based precursor specialists, insulating against toll-manufacturing entrants eroding formulation-service margins. Defend positioning by accelerating continuous-flow esterification adoption to meet MEE environmental enforcement before regulatory deadlines strand legacy batch-reactor capacity. Prioritize multi-year contracting with Indian edible oil refiners facing FSSAI compliance deadlines to lock out spot-market competitors.
For New Entrants and Emerging Players: Vietnam and Indonesia government-mandated nutrition programs offer the most penetrable geographic entry points, with fortification standards still developing and incumbent supplier relationships less entrenched than in India or China. Target toll-manufactured, ready-to-compress granule supply to Chinese and Indian tablet formulators consolidating procurement away from raw acetate merchants. Lead with integrated formulation services rather than isolated active ingredient sales, capturing value downstream where synthesis-plant capital requirements create barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across fermentation-based manufacturing and third-party tolling models, enabling specialist entrants to challenge legacy retinol synthesis economics without billion-yuan plant investments. Target acquisition candidates among continuous-flow technology licensors and citral-captive mid-cap producers positioned between multinational giants and pure-play formulators. Monitor FSSAI enforcement intensity and Vietnam's national pharmaceutical regulator standard-setting as signals of addressable market expansion or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citral Intermediates | Zhejiang-based producers secure aldehyde supply against bottleneck risk from limited specialist sources. |
| Continuous-Flow Esterification Adoption | MEE environmental compliance and solvent-waste reduction render legacy batch reactors obsolete. |
| Long-term Supply Agreements with Indian Refiners | FSSAI mandates eliminate spot-market flexibility, creating locked-in demand for certified palmitate suppliers. |
| Third-Party Fermentation Leasing Models | Asset-light toll manufacturing bypasses capital-heavy synthesis plants for tablet formulation specialists. |
| Geographic Expansion into Vietnam and Indonesia | Government nutrition programs in underpenetrated markets expand food-grade addressable base beyond India and China. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs/trade data, FSSAI and NMPA regulatory filings, and SEC disclosures from listed chemical producers. Primary interviews spanned plant managers at Shandong and Zhejiang synthesis facilities, procurement leads at Indian edible oil refiners, regulatory affairs directors navigating CDSCO and FSSAI batch-release protocols, and distribution channel partners managing cross-border formulation documentation. Bottom-up triangulation across supplier production capacities and top-down validation against regional feed and food fortification demand estimates anchored volume and value assessments.
Forecast inputs incorporate synthetic versus natural product type splits, animal nutrition versus food fortification application shares, and feed producer versus food processor end-user segmentation across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against regulatory mandate implementation schedules and livestock operation expansion trajectories. Industry-specific inputs include FSSAI enforcement intensity assumptions, MEE environmental compliance cost pass-through rates, and citral intermediate supply elasticity estimates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Zhejiang-based integrated producers or accelerated Vietnam-Indonesia fortification rollouts would shift outcomes beyond modeled ranges. Cross-checking against customs export data from Chinese vitamin manufacturers and Indian edible oil import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Vitamin D Market