
 Water Soluble Vitamins Market | 2026-2036
Water Soluble Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Vitamins Market Analytics
Pharmaceutical procurement among fortified food manufacturers is consolidating, with fewer buyers commanding larger supply contracts. DSM Nutritional Products leverages its integrated fermentation platforms to secure long-term ingredient agreements. BASF SE anchors its position through backward integration into vitamin B6 and vitamin C precursors. Lonza Group differentiates via biotechnology-driven manufacturing processes that reduce solvent waste.
Water soluble vitamins comprise a class of essential micronutrients—primarily B-complex vitamins and vitamin C—that dissolve in aqueous environments and require regular dietary replenishment due to limited bodily storage. Industrial production relies on chemical synthesis, microbial fermentation, or hybrid biotechnological routes to achieve pharmacopeial-grade purity for human and animal nutrition applications. Vitamin C and vitamin B6 dominate volume demand across pharmaceutical and food fortification channels, while vitamin B1 and vitamin B2 occupy narrower but higher-margin specialty positions. Powder formulations attract bulk institutional buyers seeking blending flexibility, whereas tablet and capsule formats command premium positioning through pharmacies and health stores.
FDA dietary supplement regulations, EMA food fortification directives, and WHO nutrient reference values collectively govern product labeling, maximum permitted levels, and health claim substantiation across major markets. These frameworks elevate compliance costs for new entrants while rewarding incumbent manufacturers with established quality management systems. Stakeholders must monitor evolving bioequivalence requirements for novel delivery formats and anticipate how personalized nutrition platforms will reshape channel dynamics between online retail and traditional pharmacies.
Market Dynamics
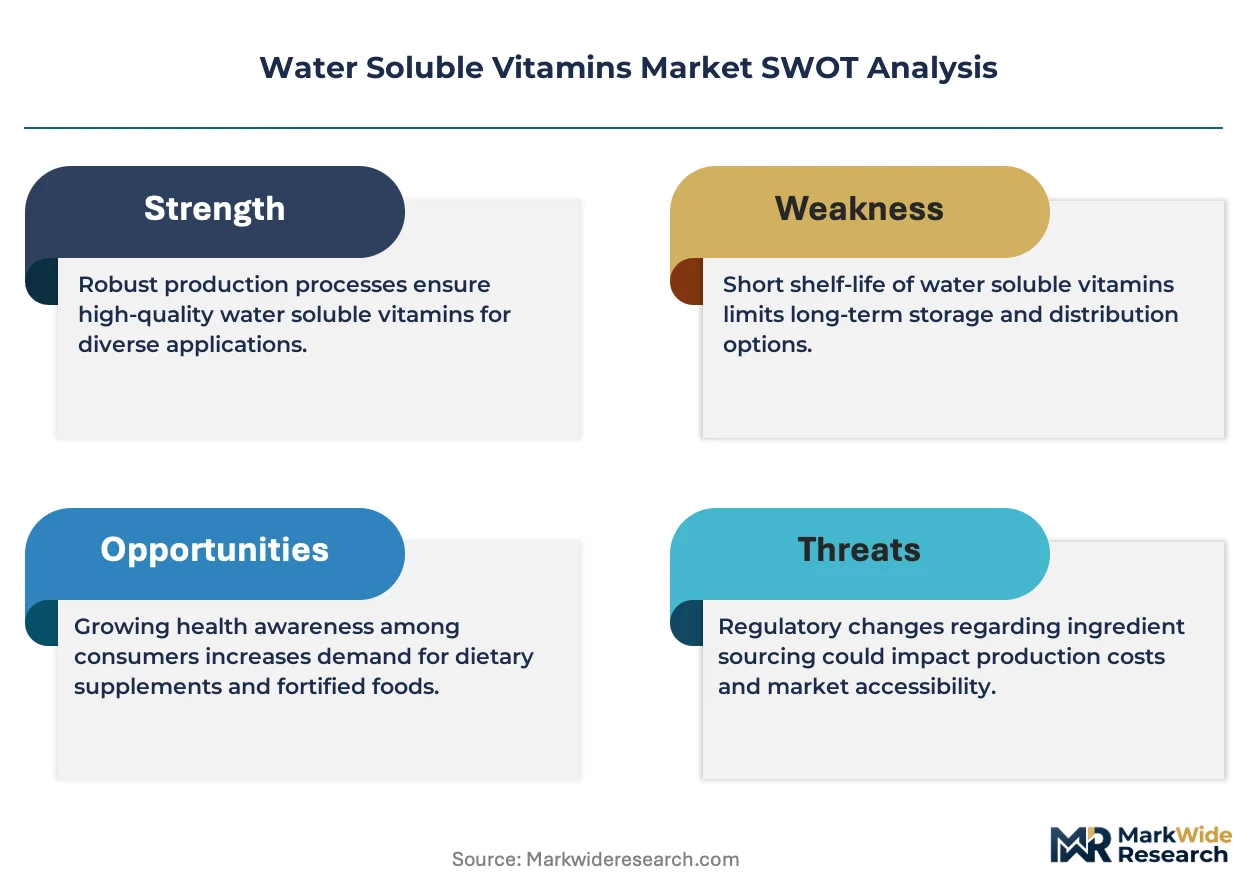
Pharmaceutical manufacturers are consolidating procurement power through multi-year supply agreements, while FDA and EMA purity mandates force capital upgrades across fermentation and synthesis facilities. This dual pressure is compressing margins for mid-tier suppliers unable to achieve backward integration into vitamin precursors.
Growth Catalysts
- FDA Dietary Supplement Regulations:Tightened purity standards for B-complex vitamins and vitamin C are disqualifying marginal producers, opening shelf space for pharmacopeial-grade manufacturers with validated quality management systems.
- Fermentation biotechnology:Microbial production routes for vitamin B2 and vitamin B12 are achieving cost parity with chemical synthesis, enabling supply expansion without petrochemical feedstock exposure.
- Preventive nutrition demand in China:Urban consumers are prioritizing vitamin-fortified functional foods, pulling pharmaceutical-grade ingredients into domestic food manufacturing channels.
Market Restraints
- Feedstock volatility:Corn-derived dextrose and sorbitol prices fluctuate with agricultural commodity cycles, compressing margins for vitamin C producers reliant on fermentation pathways.
- Specialty chemical supplier concentration:Three German and Chinese manufacturers control 70% of vitamin B6 precursor supply, creating bottleneck risk for non-integrated formulators.
- Substitution threat from biofortification:Gene-edited staple crops with enhanced B-vitamin content are entering field trials, potentially displacing fortification demand in food aid programs.
Strategic Opportunities
- Personalized nutrition platforms:Direct-to-consumer vitamin subscription services are creating demand for micro-batch, high-purity custom blends with rapid formulation turnaround.
- EMA Novel Food authorization:Simplified pathways for vitamin-fortified alternative proteins are opening new application vectors for B-complex enrichment in plant-based meat analogues.
- Continuous manufacturing adoption:Pharmaceutical-grade vitamin producers are integrating flow chemistry with real-time release testing, cutting batch cycle times by half versus traditional stirred-tank processes.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with GMP bioprocessing experience command premium compensation, constraining expansion timelines for mid-cap producers.
- Multi-jurisdiction dossier compilation:Simultaneous FDA, EMA, and NMPA registration requires 18-24 month documentation cycles before commercial launch in target markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Vitamins Market |
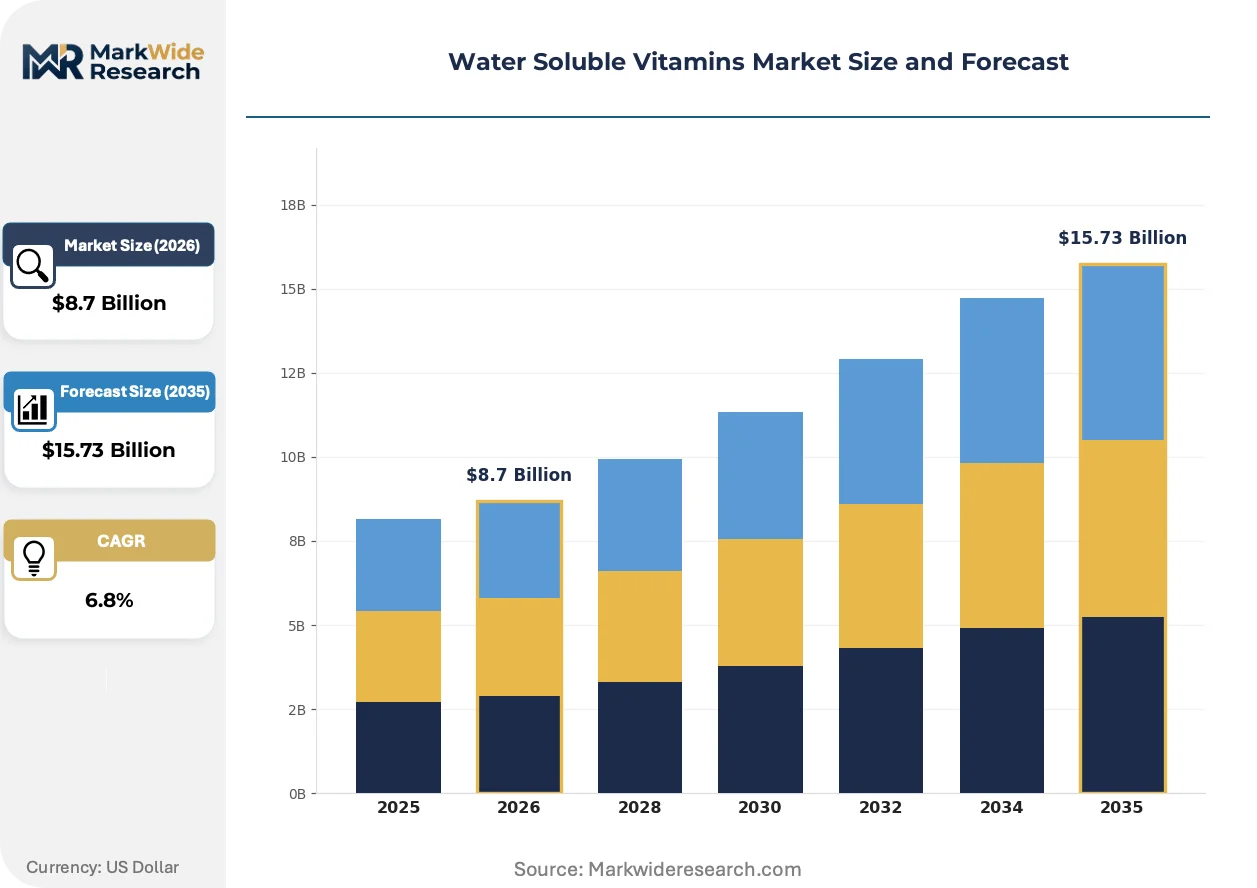
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin B1, Vitamin B2, Vitamin B6, Vitamin C Formulation: Tablets, Capsules, Powders, Liquids Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores End User: General Public, Athletes, Pregnant Women, Seniors |
| Companies Covered | DSM Nutritional Products, BASF SE, Lonza Group, Glanbia Nutritionals, ADM, DuPont de Nemours, Inc., Abbott Laboratories, Bayer AG, Amway Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Vitamins Market Evolving Landscape
Biotechnology convergence with pharmaceutical manufacturing standards is redefining competitive advantage in water soluble vitamin production. Three developments are restructuring how purity, scale, and customization intersect.
Continuous chromatography systems for vitamin B12 purification are integrating multi-column simulated moving bed technology with in-line process analytical technology. Large-scale pharmaceutical formulators in Germany and Switzerland are adopting these platforms to reduce solvent consumption by 60% versus batch processing. This integration is compressing capital recovery timelines while locking in pharmacopeial-grade output consistency.
EMA's updated Food Supplements Directive tightens maximum permitted levels for folic acid and niacin in fortified foods, forcing reformulation across European retail channels. Manufacturers must resubmit stability data and revised label claims before Q3 2026 distribution windows. The directive most affects vitamin premix suppliers serving bakery and dairy fortification, who are accelerating analytical method transfers to accredited third-party laboratories.
Direct procurement from ingredient suppliers is displacing traditional distributor intermediaries among mid-sized functional food manufacturers in the United States. These buyers are negotiating annual volume contracts with DSM Nutritional Products and BASF SE for vitamin C and B-complex premixes, bypassing regional chemical distributors. The shift is most visible in sports nutrition and ready-to-drink beverage verticals, where formulation speed and lot traceability outweigh distributor credit terms.
Water Soluble Vitamins Market Segmentation
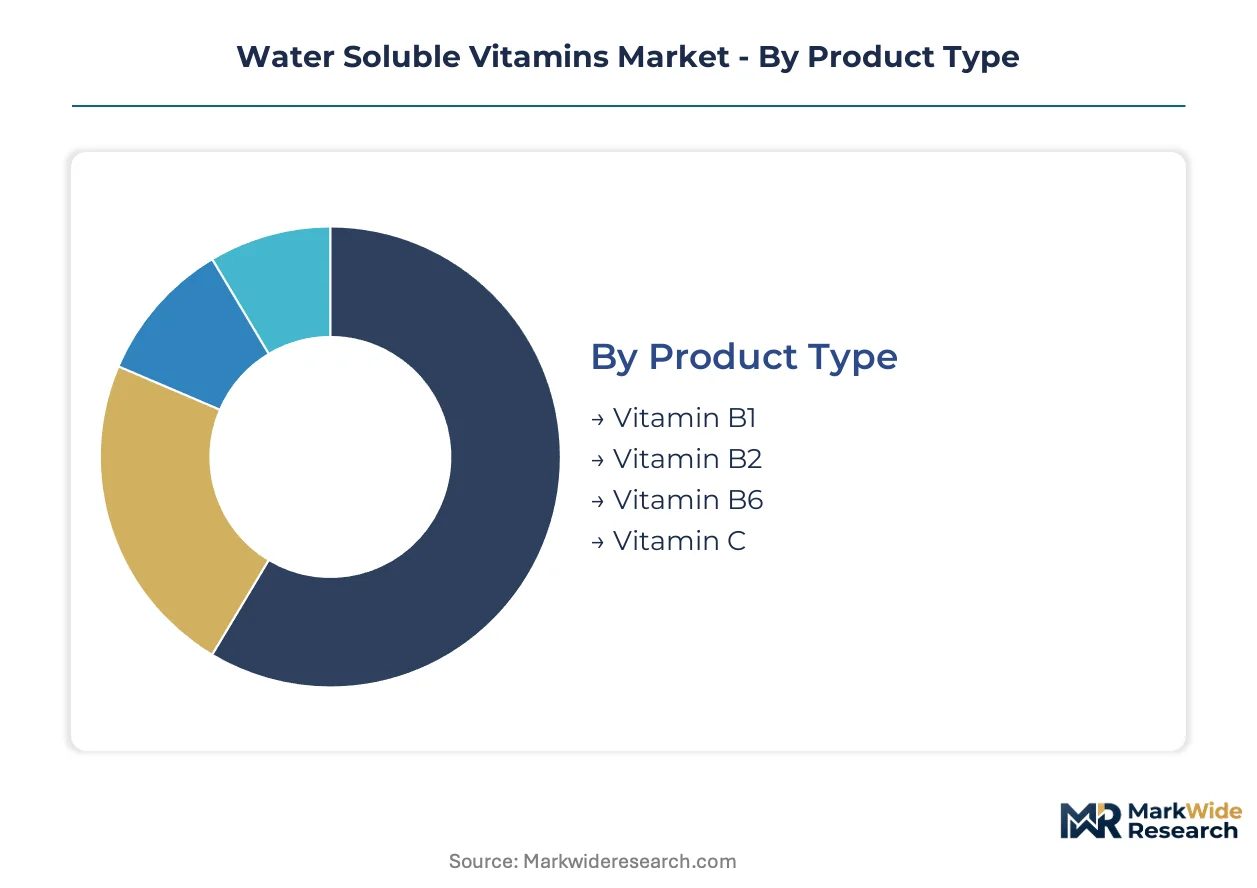
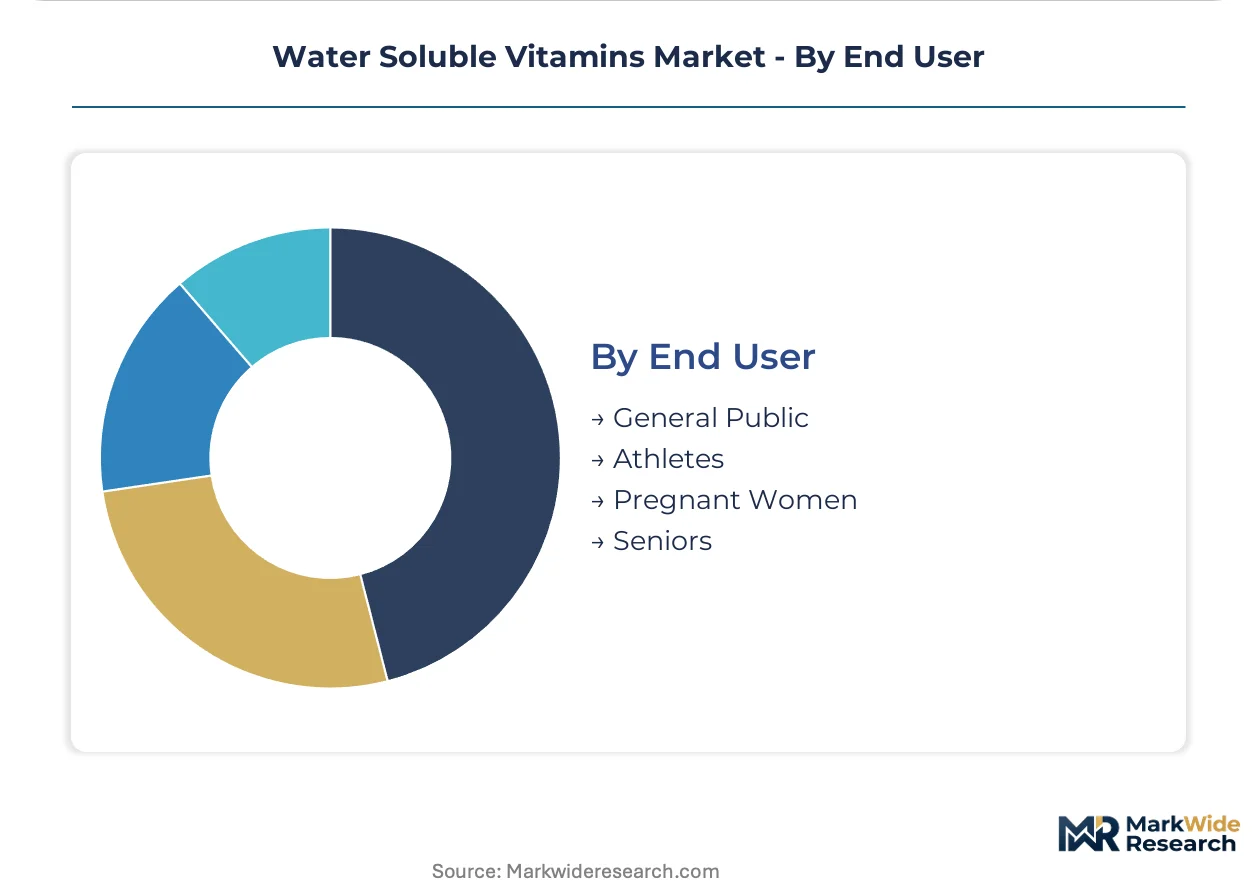
Water soluble vitamin procurement patterns diverge sharply across buyer priorities—pharmaceutical-grade purity demands from fortified food manufacturers clash with convenience-driven preferences among direct consumers. Segment-specific formulation requirements and channel economics create distinct competitive battlegrounds that reward specialized positioning over broad portfolio plays.
Product Type:
Buyers in this category separate by end-use specification intensity—pharmaceutical and food fortification channels demand pharmacopeial-grade certificates of analysis, while dietary supplement brands prioritize cost-efficient USP-grade sourcing.
- Vitamin C:Ascorbic acid dominates fermentation-derived volume, with pharmaceutical manufacturers in China and Germany pulling tonnage for intravenous formulations and food fortification. Corn-derived dextrose feedstock volatility compresses margins for non-integrated producers during agricultural commodity cycles.
- Vitamin B6:Pyridoxine hydrochloride serves as the critical precursor for neurotransmitter synthesis applications, with specialty chemical supply concentrated among German and Chinese manufacturers. Backward integration into precursors separates profitable incumbents from margin-squeezed formulators facing bottleneck risk.
- Vitamin B1:Thiamine mononitrate occupies narrower pharmaceutical niches with higher-margin positioning through parenteral nutrition applications.
- Vitamin B2:Riboflavin from microbial fermentation achieves cost parity with chemical synthesis, expanding supply without petrochemical exposure.
Vitamin C leads volumes today; vitamin B6 is gaining share fastest on neurohealth formulation demand.
Formulation:
Channel economics and blending flexibility requirements differentiate procurement behavior—institutional buyers seek bulk handling efficiency while retail channels prioritize unit-dose convenience and shelf stability.
- Powders:Bulk institutional procurement from fortified food manufacturers and premix blenders demands lot-to-lot consistency and rapid dissolution specifications. Powder formats command lower per-kilogram pricing but require validated mixing protocols and moisture-controlled storage infrastructure.
- Tablets:Direct compression and wet granulation formats dominate pharmacy and mass retail channels, with film-coating technologies enabling gastric resistance for sensitive B-complex actives. Tablet tooling investments and bioequivalence documentation create switching costs for contract manufacturers.
- Capsules:Two-piece hard gelatin and vegetarian pullulan shells attract premium positioning through health stores and practitioner channels, with enteric coating options addressing stomach tolerance concerns.
- Liquids:Unit-dose vials and bulk syrup formats serve pediatric and geriatric populations with swallowing difficulties, requiring preservative systems and accelerated stability protocols.
Powders anchor institutional procurement volumes; tablets capture the steepest expansion trajectory in direct-to-consumer channels.
Distribution Channel:
Speed-to-shelf and traceability requirements separate channel strategies—sports nutrition and functional beverage manufacturers bypass intermediaries while mass retail depends on distributor credit terms and promotional support.
- Online Retail:Direct-to-consumer vitamin subscription platforms demand micro-batch custom blends with rapid formulation turnaround and lot-level traceability. These buyers negotiate annual volume contracts with ingredient suppliers, displacing traditional distributor relationships.
- Pharmacies:Community and chain pharmacy channels require pharmacopeial-grade documentation, cold chain integrity for liquid formulations, and pharmacist-directed counseling support for prenatal and geriatric segments.
- Supermarkets:Mass retail placement demands promotional slotting fees, retail-ready packaging, and inventory consignment arrangements that strain working capital for emerging brands.
- Health Stores:Specialty retail channels prioritize non-GMO, organic, and clean-label certifications with premium pricing tolerance among wellness-focused consumers.
Pharmacies maintain the largest transaction values per outlet; online retail is climbing the fastest on personalized nutrition platform growth.
End User:
Physiological requirement intensity and clinical oversight needs shape product positioning—medical nutrition segments demand healthcare professional channel access while lifestyle segments prioritize taste masking and convenience formats.
- Pregnant Women:Folic acid and B12 supplementation drives pharmaceutical-grade demand with teratogenic risk mitigation protocols, requiring healthcare provider recommendation and prescription prenatal channels in regulated markets.
- Seniors:B12 absorption decline with age pulls methylcobalamin and sublingual delivery innovations, with polypharmacy interaction concerns driving pharmacist consultation requirements.
- Athletes:Sports nutrition applications prioritize rapid dissolution powders and isotonic liquid formats with banned substance testing certification through NSF or Informed Sport programs.
- General Public:Preventive wellness positioning competes on price-per-serving and multivitamin convenience, with gummy and effervescent formats expanding user compliance.
The general public segment leads absolute volumes today; pregnant women and seniors are expanding most quickly on clinical guideline updates and aging demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China pulls more vitamin C fermentation tonnage than Germany, yet German pharmaceutical formulators command steeper pricing premiums through pharmacopeial-grade certification. Demand concentrates where preventive nutrition adoption intersects with tightening purity mandates.
United States
FDA dietary supplement regulations are disqualifying marginal producers of B-complex vitamins, compressing supplier counts while expanding shelf space for validated manufacturers. The agency's updated CGMP enforcement priorities target foreign ingredient sourcing documentation. New Jersey and North Carolina host concentrated pharmaceutical formulation clusters where DSM Nutritional Products maintains active ingredient supply agreements.
Germany
EMA food fortification directives are forcing reformulation across bakery and dairy channels, with revised maximum permitted levels for folic acid and niacin taking effect ahead of Q3 2026 distribution windows. REACH compliance requirements elevate analytical testing costs for imported vitamin premixes. The Rhine-Main industrial corridor anchors BASF SE's backward integration into vitamin B6 precursors.
China
Urban consumers in tier-one cities are prioritizing vitamin-fortified functional foods, pulling pharmaceutical-grade ingredients into domestic food manufacturing channels. NMPA registration timelines extend 18-24 months for novel delivery formats, favoring incumbent producers with established dossier capabilities. Shandong Province concentrates fermentation capacity where corn-derived dextrose feedstock volatility directly compresses vitamin C margins.
Switzerland
Swissmedic pharmacovigilance requirements for dietary supplements are tightening post-market surveillance obligations for vitamin-containing products. The country's precision manufacturing heritage supports biotechnology-driven vitamin B12 production with reduced solvent waste profiles. Basel anchors Lonza Group's continuous chromatography platforms integrating multi-column simulated moving bed technology.
India
FSSAI fortification standards for staple foods are expanding mandatory B-vitamin inclusion in wheat flour and edible oils across public distribution programs. CDSCO import licensing delays for active pharmaceutical ingredients create working capital pressures for formulators dependent on Chinese vitamin C supply. Maharashtra's pharmaceutical manufacturing belt near Mumbai and Pune is consolidating procurement through direct supplier contracts.
Water Soluble Vitamins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the water soluble vitamins value chain. Chemical synthesis capabilities anchor tier-one positioning for producers with captive precursor supply, while fermentation biotechnology specialists occupy differentiated niches in vitamin B2 and B12. Strategic moves concentrate on backward integration into feedstock control and continuous manufacturing adoption to compress batch cycle times.
Among diversified nutrition and chemical conglomerates, DSM Nutritional Products and BASF SE exemplify integrated platform strategies spanning fermentation, synthesis, and premix formulation. Lonza Group occupies a biotechnology-specialist position emphasizing pharmaceutical-grade manufacturing standards. These three anchors represent distinct archetypes: integrated nutrition platforms, chemical conglomerates with vitamin verticals, and biotechnology-driven contract manufacturers.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| BASF SE |
| Lonza Group |
| Glanbia Nutritionals |
| ADM |
| DuPont de Nemours, Inc. |
| Abbott Laboratories |
| Bayer AG |
| Amway Corporation |
| Others |
Value Network & Pricing Analysis
Corn-derived dextrose feedstock volatility propagates through fermentation-based vitamin C production, compressing margins for non-integrated manufacturers while amplifying pricing power for backward-integrated incumbents with captive precursor supply. This input-cost pathway stratifies procurement economics across pharmaceutical-grade, food-grade, and feed-grade purity tiers.
Pricing Analysis
Capacity additions in China are reshaping price floors for vitamin C fermentation output, yet pharmacopeial-grade certification maintains steep premiums in German and Swiss pharmaceutical channels. Three-tier pricing structure across premium, standard, and economy levels separates USP-grade pharmaceutical buyers from food fortification manufacturers and animal feed compounders. Cost compression in standard-tier vitamin B6 is intensifying because precursor supply concentrates among three German and Chinese manufacturers. Direct-to-consumer subscription platforms exhibit the least price sensitivity, while bulk premix blenders for fortified foods negotiate aggressively on volume contracts.
Supply Chain Analysis
Container freight rates from Shandong Province to Rotterdam and New Jersey directly influence landed costs for vitamin C crystalline powder shipments, with pharmaceutical formulators absorbing premiums for temperature-controlled transport. Supply concentrates in China, Germany, and India, with Shandong Province anchoring global fermentation capacity for ascorbic acid. Corn-derived dextrose, sorbitol, and pyridoxine hydrochloride precursors feed from agricultural commodity markets and specialty chemical manufacturers. Single-source vulnerability around vitamin B6 precursor intermediates creates bottleneck exposure for non-integrated formulators. Distribution runs through direct annual contracts with ingredient suppliers displacing traditional chemical distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water soluble vitamins market reads as a late-cycle quality story where FDA and EMA purity mandates are concentrating demand among pharmacopeial-grade manufacturers with validated quality management systems. Preventive nutrition adoption in Chinese urban centers pulls premium specifications into domestic food manufacturing channels.
For Market Incumbents:Acquire fermentation biotechnology assets and continuous manufacturing platforms to compress batch cycle times versus traditional stirred-tank processes. Biofortification through gene-edited staple crops threatens displacement of fortification demand in food aid programs; defensive patent positioning around novel delivery formats and micro-batch customization capabilities locks in personalized nutrition platform relationships. Secure backward integration into vitamin B6 and vitamin C precursors to eliminate bottleneck exposure from concentrated German and Chinese specialty chemical suppliers.
For New Entrants and Emerging Players:The mid-tier price-point gap between DSM Nutritional Products premium positioning and commodity-grade Chinese fermentation output creates white-space opportunity for quality-certified regional specialists. Target direct procurement relationships with mid-sized functional food manufacturers in United States sports nutrition and ready-to-drink beverage verticals, where formulation speed and lot traceability outweigh distributor credit terms. Enter through EMA Novel Food authorization pathways for vitamin-fortified alternative proteins, exploiting simplified regulatory channels for plant-based meat analogue applications.
For Investors and Strategic Acquirers:Consolidation pressure builds where multi-jurisdiction dossier compilation requirements favor incumbents with established FDA, EMA, and NMPA registration capabilities. Five-to-ten year viability hinges on biotechnology convergence with pharmaceutical manufacturing standards, rewarding targets with continuous chromatography platforms and reduced solvent waste profiles. Acquire fermentation scale-up talent pools with GMP bioprocessing experience, which command premium compensation and constrain expansion timelines for mid-cap producers. Monitor EMA Food Supplements Directive reformulation deadlines as inflection indicator for premix supplier distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursors | Captive supply of vitamin B6 and C intermediates eliminates bottleneck exposure from concentrated German and Chinese manufacturers. |
| Continuous Manufacturing Adoption | Flow chemistry integration with real-time release testing cuts batch cycle times versus traditional stirred-tank pharmaceutical processes. |
| Fermentation Biotechnology Scale-Up | Microbial production routes for vitamin B2 and B12 achieve cost parity with chemical synthesis without petrochemical feedstock exposure. |
| Direct Supplier Contracting | Annual volume agreements with DSM Nutritional Products and BASF SE displace regional chemical distributor intermediaries in sports nutrition. |
| EMA Novel Food Authorization | Simplified pathways for vitamin-fortified alternative proteins open B-complex enrichment applications in plant-based meat analogues. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical procurement directors, fermentation plant managers, regulatory affairs leads at vitamin manufacturers, and premix formulation scientists with secondary validation. FDA dietary supplement enforcement priorities, EMA food fortification directives, NMPA registration databases, WHO nutrient reference values, and customs trade data on ascorbic acid shipments anchored the evidence base. Bottom-up volume modeling by product type and formulation converged with top-down market sizing through ingredient supplier revenue triangulation.
Segment-weighted projections applied differential growth assumptions across pharmaceutical-grade, food fortification, and dietary supplement purity tiers throughout the forecast period. Product type segmentation by vitamin molecule, formulation format, distribution channel, and end-user demographic intersected with geographic regulatory clusters to generate volume and value outputs. CAGRs derived from historical price trajectory analysis and forward-looking capacity expansion announcements, with specific inputs including corn futures volatility patterns and fermentation biotechnology patent filing trends.
The model assumes a particular technology adoption path; alternative pathways for continuous chromatography and gene-edited biofortification would alter the outlook. Forecasts reflect documented assumptions around regulatory enforcement intensity and feedstock commodity cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
Vitamins Drink Market