
 Food Fortifying Agents Market | 2026-2036
Food Fortifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Food Fortifying Agents Market Analysis
The capability gap between integrated micronutrient compounders and commodity ingredient traders is collapsing as bioavailability science becomes table stakes for contract wins. BASF SE leverages its Carotenoid and Vitamin E synthesis complexes to sustain technical specifications that smaller blenders cannot replicate. Cargill Incorporated anchors North American grain fortification through captive oilseed processing and direct elevator relationships. Kerry Group plc differentiates via taste-masked mineral encapsulation that competes on sensory performance in flavored dairy applications.
Food fortifying agents are bioactive compounds—vitamins, minerals, amino acids, and nutraceuticals—delivered in powder, liquid, granule, or tablet form to elevate the nutritional density of processed foods and beverages; their functional parameters include thermal stability above 120°C for baking applications and particle sizes below 200 microns for homogeneous dispersion in fluid milk. The vitamin segment leads absolute volume due to mandatory wheat flour and edible oil fortification programs across multiple continents, while amino acid fortification for plant-based protein beverages represents the fastest-growing structural pocket as formulators address lysine and methionine gaps in pea and oat matrices. Mineral premixes in powder form occupy the deepest margin pools because of compounding complexity and the certification burden for infant nutrition-grade iron and zinc compounds.
The US FDA governs GRAS self-affirmation pathways for novel fortifying agents, while India's FSSAI mandates micronutrient standards for staple fortification that directly shape procurement volumes from domestic premixers. The EU EFSA evaluates health claim substantiation for nutraceutical fortification, creating a dual compliance architecture that filters market access for non-European suppliers. Stakeholders must monitor evolving bioequivalence requirements for synthetic versus fermented vitamin forms as procurement committees in food manufacturing consolidate qualified supplier lists.
Market Dynamics
The collapse of technical barriers between integrated micronutrient compounders and commodity traders is compressing margin pools across fortification supply chains, forcing differentiation through bioavailability science and captive processing infrastructure.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory wheat flour and edible oil standards create guaranteed procurement volumes for domestic premixers, locking in multi-year supply contracts with dairy and milling cooperatives.
- Plant-based protein formulation:Lysine and methionine fortification addresses amino acid gaps in pea and oat matrices, pulling demand from beverage manufacturers seeking complete protein claims.
- Thermal stability requirements:Vitamin compounds stable above 120°C enable clean-label baking applications without process modification, expanding addressable market into artisanal and industrial bread segments.
Market Restraints
- Carotenoid synthesis concentration:Three integrated chemical complexes control global vitamin A and beta-carotene supply, creating single-source vulnerability for regional blenders.
- Infant nutrition certification burden:Iron and zinc compounds for early-life applications require pharmacopeial-grade documentation that extends qualification timelines to 18-24 months.
- Fermented vitamin cost premium:Bioequivalent synthetic alternatives trade at 40-60% below fermentation-derived forms, pressuring procurement committees to prioritize price over provenance.
Strategic Opportunities
- Taste-masked mineral encapsulation:Sensory-neutral iron and zinc formats unlock flavored dairy applications where metallic off-notes previously blocked adoption.
- Direct-to-elevator grain fortification:Bypassing centralized milling infrastructure reduces distribution losses and enables real-time premix calibration at receival points.
- EU Green Deal alignment:Carbon-accounted vitamin production processes qualify for preferential procurement under Scope 3 reduction targets for multinational food manufacturers.
Industry Challenges
- Particle size homogeneity:Sub-200 micron dispersion specifications for fluid milk require micronization equipment that smaller compounders cannot access without contract manufacturing partnerships.
- Bioequivalence documentation:Procurement committees now demand comparative absorption studies between synthetic and fermented vitamin forms, extending supplier qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Fortifying Agents Market |
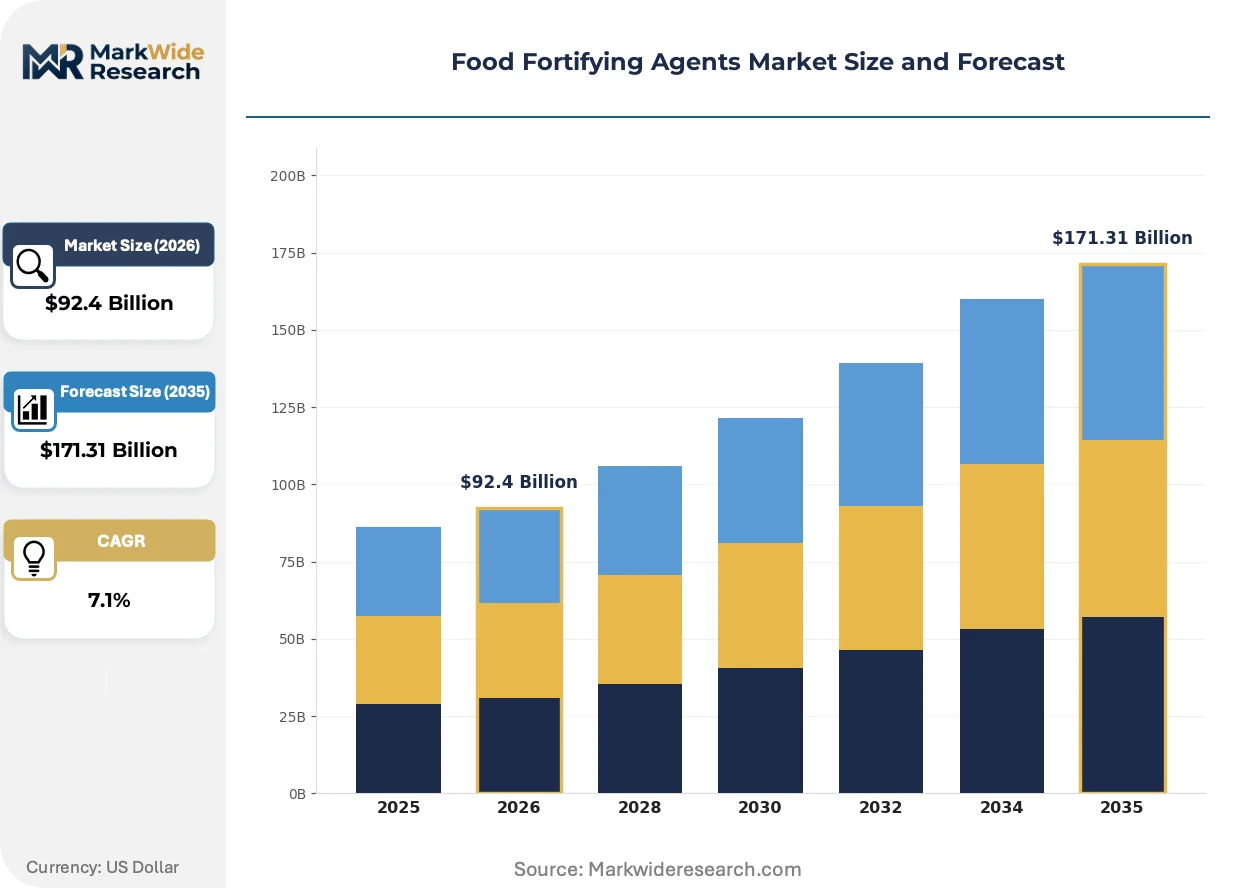
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $171.31 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vitamins, Minerals, Amino Acids, Nutraceuticals Form: Powder, Liquid, Granules, Tablets Application: Dairy Products, Baked Goods, Beverages, Confectionery End User: Food Manufacturers, Retailers, Health Organizations, Consumers |
| Companies Covered | Archer Daniels Midland Company, BASF SE, DSM-Firmenich AG, Cargill Incorporated, Ingredion Incorporated, Kerry Group plc, Nestle SA, DuPont de Nemours Inc., Tate & Lyle Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Fortifying Agents Market Emerging Trajectories
Formulation science is splitting along two tracks: commodity-scale fortification for staple foods versus precision delivery systems for premium nutrition segments, with technology choices increasingly determining addressable margin pools.
Encapsulation technology is bifurcating the mineral premix market. Liposome and lipid-matrix formats protect iron and zinc from oxidation in high-moisture dairy matrices. Premium infant formula manufacturers in Western Europe and North America are adopting these formats at 15-20% price premiums. The technology is compressing margins for unencapsulated commodity mineral suppliers while creating dedicated supply relationships for compounders with in-house microencapsulation capacity.
EFSA's evolving health claim substantiation requirements for nutraceutical fortification are filtering market access for non-European suppliers. Novel bioactive compounds now require human intervention studies demonstrating measurable physiological benefit. Protein-fortified snack and beverage categories face the steepest compliance burden, with several Asian ingredient suppliers withdrawing pending dossier preparation rather than absorbing clinical trial costs.
Buyer concentration among multinational food manufacturers is consolidating qualified supplier lists to three-to-five approved premixers per geography. Procurement committees now mandate dual-source redundancy for critical vitamins, disqualifying single-facility compounders from tender participation. This pattern is most visible in North American grain milling, where direct elevator relationships and captive oilseed processing determine contract allocation.
Food Fortifying Agents Market Segmentation
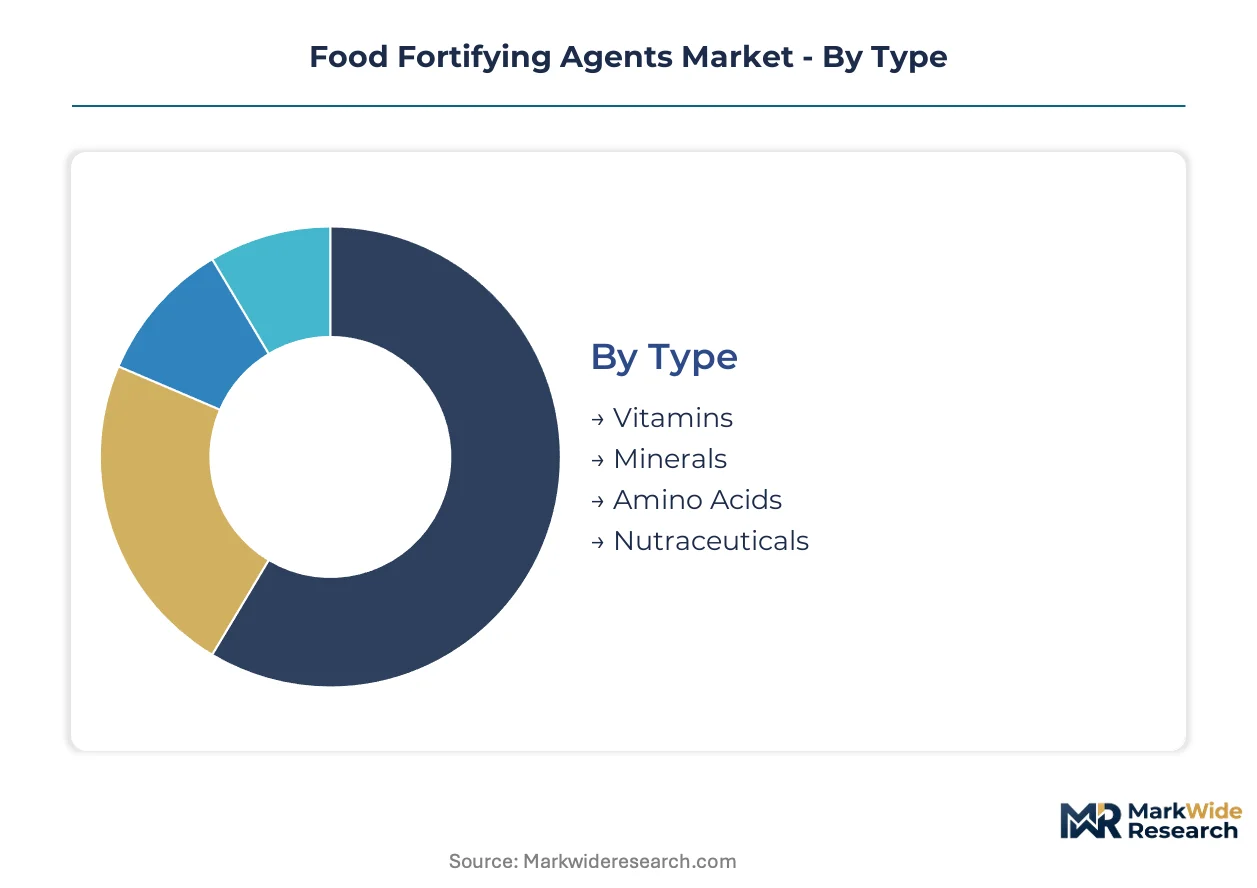
Segmentation in food fortifying agents determines procurement pathways and margin structures. Powder-form vitamins flow through centralized milling cooperatives while encapsulated minerals reach dairy processors via specialized premix channels. Each segment carries distinct technical specifications that filter supplier qualification.
Type:
Vitamins dominate commodity-scale distribution through government fortification programs, while amino acids and nutraceuticals concentrate in premium beverage and supplement channels with tighter supplier lists.
- Vitamins:Thermal-stable compounds above 120°C enable wheat flour and edible oil fortification without process modification. India's FSSAI mandates for staple fortification lock in multi-year procurement volumes for domestic premixers supplying dairy cooperatives.
- Minerals:Iron and zinc premixes require sub-200 micron particle specifications for homogeneous fluid milk dispersion. Pharmacopeial-grade documentation for infant nutrition applications extends supplier qualification timelines to 18-24 months.
- Amino Acids:Lysine and methionine address protein gaps in pea and oat matrices for plant-based beverages.
- Nutraceuticals:EFSA health claim substantiation requirements filter market access for non-European suppliers lacking human intervention study data.
By volume, vitamins lead through mandatory fortification programs. By growth pace, amino acids are climbing fastest as plant-based protein formulations expand.
Form:
Form selection hinges on moisture sensitivity and dispersion requirements. Powders suit dry blending operations while liquids integrate into continuous beverage processing lines.
- Powder:Dominates grain milling and edible oil distribution with shelf stability above 24 months. India's wheat flour fortification programs specify powder premixes calibrated to 150-200 micron particle ranges for elevator-level dosing.
- Liquid:Enables real-time calibration in fluid milk processing with homogeneous dispersion below 0.5% coefficient of variation. Thermal stability constraints limit vitamin selection to carotenoid and tocopherol forms.
- Granules:Intermediate flow properties suit confectionery tableting with reduced dust generation versus fine powders.
- Tablets:Direct-to-consumer fortification bypasses food manufacturing infrastructure in supplement retail channels.
Powder captures the deepest procurement volumes. Liquid formats are gaining share fastest in dairy processing automation.
Application:
Application segments split between mandated staple fortification and discretionary premium nutrition, with divergent margin and certification requirements.
- Dairy Products:Taste-masked iron and zinc encapsulation unlocks flavored milk applications where metallic off-notes previously blocked adoption. Liposome formats command 15-20% price premiums in Western European infant formula.
- Baked Goods:Vitamin stability above 120°C enables clean-label artisanal and industrial bread segments without process modification or off-flavor development.
- Beverages:Amino acid fortification for plant-based protein claims concentrates demand from North American and Western European beverage manufacturers.
- Confectionery:Mineral fortification faces sensory constraints requiring microencapsulation for iron delivery in chocolate matrices.
Dairy applications lead by value concentration. Beverages are expanding most quickly as protein fortification claims proliferate.
End User:
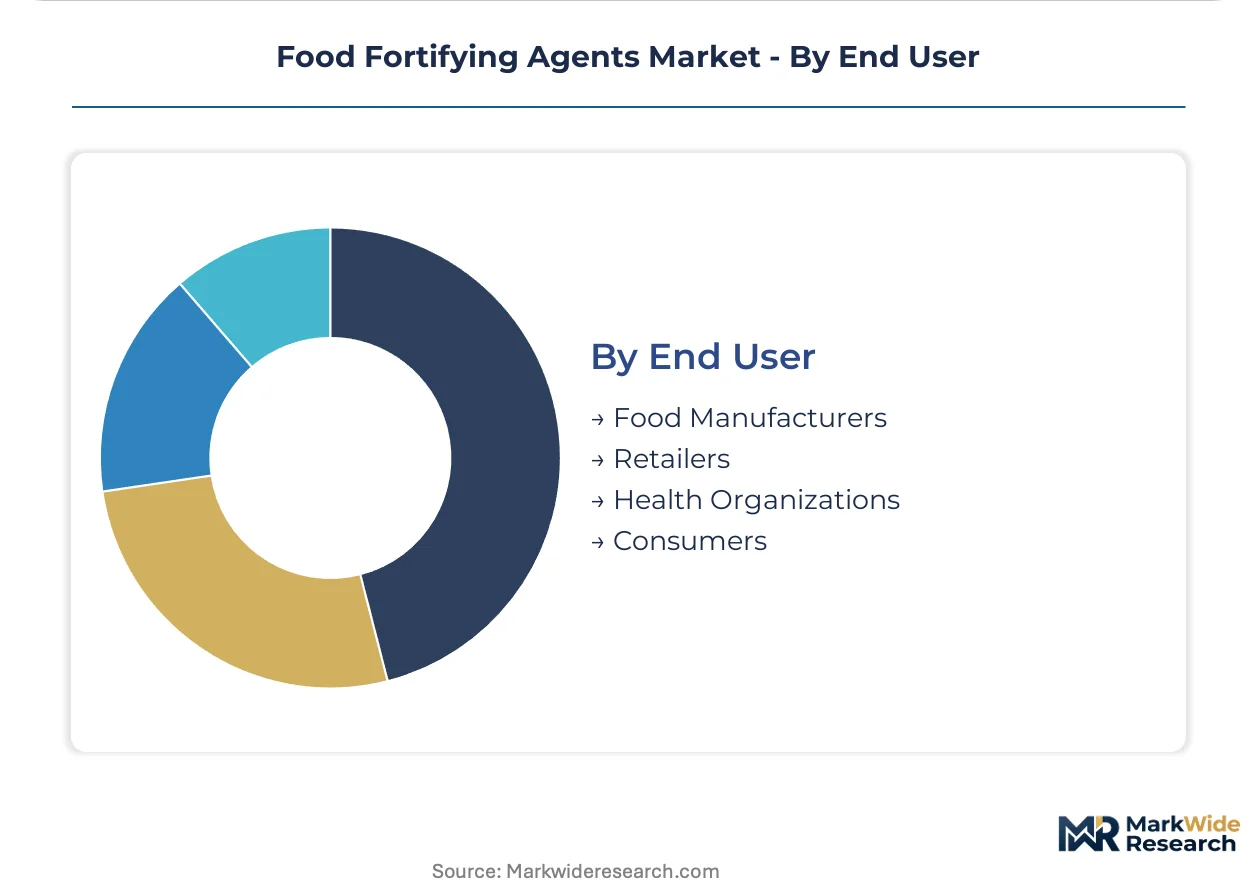
End-user concentration shapes supplier relationship structures, with food manufacturers consolidating qualified premix lists while health organizations drive volume through tender-based procurement.
- Food Manufacturers:Multinational procurement committees now mandate dual-source redundancy for critical vitamins, disqualifying single-facility compounders. Direct elevator relationships and captive oilseed processing determine contract allocation in North American grain milling.
- Retailers:Private-label supplement programs require batch-level traceability documentation that filters supplier bases to integrated compounders with in-house analytical capabilities.
- Health Organizations:Government fortification tenders in India and Indonesia specify FSSAI-aligned micronutrient standards with multi-year volume guarantees.
- Consumers:Direct-to-consumer tablet formats bypass food manufacturing infrastructure, concentrating in pharmacy and e-commerce channels with lower regulatory burden than infant nutrition applications.
Food manufacturers dominate procurement value. Health organizations are scaling fastest as mandatory fortification programs expand across South and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Indian and European markets where regulatory mandates guarantee procurement volumes, while North American grain fortification operates on thinner margins dictated by elevator-level competition and captive oilseed processing economics.
India
FSSAI mandates for wheat flour and edible oil fortification lock in multi-year supply contracts with dairy cooperatives and milling operations. The national food regulator enforces micronutrient standards that directly shape procurement volumes from domestic premixers. Gujarat and Maharashtra host the densest clustering of vitamin compounders serving cooperative dairy infrastructure.
United States
FDA GRAS self-affirmation pathways enable rapid novel ingredient adoption for functional food applications. The agency's flexible regulatory architecture supports innovation in bioactive delivery systems. Minneapolis and Chicago anchor North American grain fortification through direct elevator relationships and captive oilseed processing networks.
Germany
EFSA health claim substantiation requirements filter market access for nutraceutical fortification, creating compliance barriers for non-European suppliers. The EU Green Deal drives preferential procurement toward carbon-accounted vitamin production processes. Frankfurt and Hamburg concentrate formulation R&D for premium infant nutrition applications.
China
SAMR oversight of food additive standards shapes domestic fortification ingredient approval timelines. The country's dual carbon goals pressure multinational manufacturers to document Scope 3 reductions in vitamin supply chains. Shanghai and Jiangsu province host integrated chemical complexes controlling global carotenoid synthesis capacity.
Brazil
ANVISA regulations govern bioactive compound approvals for processed food fortification with extended dossier review cycles. National school feeding programs generate institutional demand for wheat flour micronutrient premixes. São Paulo state concentrates blending operations serving Latin American beverage manufacturers.
Food Fortifying Agents Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical complexes commanding premium positions in bioavailable vitamin synthesis while regional blenders compete on logistics proximity and tender responsiveness. The market structure tiers into three strategic archetypes: global compounders with captive synthesis infrastructure, regional premix specialists with formulation expertise, and commodity traders leveraging distribution scale. Dominant competitive moves include backward integration into oilseed processing for grain fortification channels and technology licensing partnerships for microencapsulation capacity.
Among European-integrated compounders, BASF SE and DSM-Firmenich AG exemplify the synthesis-led archetype with positions anchored in carotenoid and vitamin production complexes. Kerry Group plc represents the formulation-specialist tier with differentiated mineral encapsulation capabilities for sensory-sensitive dairy applications. Cargill Incorporated occupies the agricultural-origins vector, leveraging captive grain and oilseed infrastructure to secure North American milling contracts.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BASF SE |
| DSM-Firmenich AG |
| Cargill Incorporated |
| Ingredion Incorporated |
| Kerry Group plc |
| Nestle SA |
| DuPont de Nemours Inc. |
| Tate & Lyle Plc |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake agreements between Indian dairy cooperatives and domestic premixers lock in vitamin supply access while capping price volatility for wheat flour and edible oil fortification programs. These contracts insulate buyers from spot market swings in carotenoid feedstock costs while guaranteeing compounders baseline volumes through FSSAI-mandated procurement cycles.
Pricing Analysis
The customization-premium spread separates pharmacopeial-grade infant nutrition minerals from commodity iron and zinc compounds for staple food applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, particle size specifications, and encapsulation complexity. Cost compression in standard-grade vitamin premixes is intensifying because bioequivalent synthetic alternatives trade at steep discounts to fermentation-derived forms. Food manufacturers with dual-source mandates exhibit lowest price sensitivity, while regional milling cooperatives operating on thin margins show highest elasticity.
Supply Chain Analysis
China and India anchor global vitamin and mineral premix production, with Jiangsu province hosting integrated carotenoid synthesis complexes and Gujarat clustering domestic compounders serving cooperative dairy infrastructure. Supply chains draw from oilseed processing byproducts, petrochemical-derived precursors, and fermentation biomass as primary inputs. Single-source vulnerability concentrates in beta-carotene and vitamin A synthesis, where three chemical complexes control global capacity. Distribution runs through centralized milling cooperatives for powder premixes and direct-to-elevator channels for grain fortification, with specialized dairy processors accessing encapsulated minerals via technical premix distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among multinational food manufacturers, with procurement committees narrowing qualified supplier lists to three-to-five approved premixers per geography and mandating dual-source redundancy that disqualifies single-facility compounders.
For Market Incumbents: Consolidate backward integration into oilseed processing to secure captive feedstock supply for North American grain fortification contracts. Deepen microencapsulation capacity investments to defend margin position against commodity mineral traders encroaching on sensory-sensitive dairy applications. EFSA's evolving bioequivalence documentation requirements threaten smaller blenders unable to fund comparative absorption studies. For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks offer lowest regulatory barrier for novel bioactive compounds targeting functional food applications. White-space opportunity concentrates in taste-masked mineral formats for flavored dairy segments where metallic off-notes previously blocked adoption, and in direct-to-elevator grain fortification bypassing centralized milling infrastructure. Go-to-market positioning should emphasize real-time premix calibration capabilities at receival points. For Investors and Strategic Acquirers: Capital is best deployed toward regional premix specialists with established FSSAI-aligned qualification and captive formulation expertise serving Indian cooperative infrastructure. Long-term viability hinges on defensible positions in mandatory fortification procurement channels rather than discretionary premium nutrition segments. The signal to watch is consolidation velocity among multinational food manufacturers, as accelerated narrowing of qualified supplier lists will determine which compounders secure multi-year volume guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill leverages captive crushing capacity to secure North American grain milling contracts against commodity traders. |
| Microencapsulation Capacity Expansion | Kerry Group's lipid-matrix iron formats command 15-20% premiums in Western European infant formula applications. |
| FSSAI Certification Fast-Track | Domestic Indian compounders with pre-qualified status capture multi-year dairy cooperative supply mandates. |
| Direct-to-Elevator Distribution Buildout | Bypassing centralized milling infrastructure reduces distribution losses and enables real-time premix calibration. |
| Carbon-Accounted Production Processes | EU Green Deal alignment qualifies vitamin manufacturers for preferential procurement under Scope 3 reduction targets. |
Methodological Framework
A standing panel of premix procurement managers at multinational food manufacturers, technical directors at dairy cooperatives, regulatory affairs leads at domestic compounders, and grain elevator operations managers provided ongoing calibration across the analysis window. Primary interview intelligence combined with FSSAI fortification guidelines, FDA GRAS notifications, EFSA health claim dossiers, and customs trade data for vitamin and mineral premix flows. Bottom-up volume builds from application-level consumption patterns triangulated against top-down market sizing from identified producer capacity.
Consistency checks validated model outputs against external benchmarks including identified producer revenue disclosures and government procurement tender volumes. The analytical framework segmented by type, form, application, and end user across the projection horizon, with CAGRs derived from regression analysis of historical procurement patterns and policy-mandated volume trajectories. Industry-specific forecast inputs included FSSAI enforcement timelines for edible oil fortification and EFSA bioequivalence study completion rates for novel vitamin forms.
Decision-makers should treat outputs as directional under assumptions of sustained FSSAI mandate enforcement and stable carotenoid synthesis capacity; material deviation in regulatory implementation pace or feedstock supply disruption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Vitamin a in Feed Additives Market