
 Vitamins and Minerals Market | 2026-2036
Vitamins and Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamins and Minerals Market Intelligence
Personalized nutrition services, often bundled with direct-to-consumer subscriptions, is rewriting the value chain away from traditional retail channels. Koninklijke DSM N.V. leverages its extensive ingredient portfolio to supply both pharmaceutical and food fortification segments. Meanwhile, consumer-facing giants like Nestlé S.A. and Bayer AG compete through strong brand recognition and expansive distribution networks.
Vitamins and minerals are essential organic and inorganic micronutrients required by the body for a range of metabolic functions, growth, and overall health. These compounds, which include fat-soluble vitamins like Vitamin D and water-soluble ones like Vitamin C, cannot be synthesized in sufficient quantities by the human body and must be obtained from diet or supplementation. Within product types, multivitamins represent the largest category, but single vitamins are showing higher growth. Food fortification and functional foods are rapidly expanding applications, driven by consumer demand for convenient health solutions beyond simple dietary supplements.
Market access and product claims are governed by strict regulatory frameworks, including the FDA's dietary supplement regulations in the United States and the European Food Safety Authority's (EFSA) health claim assessments. In parallel, China's National Medical Products Administration (NMPA) sets stringent registration requirements for health food products, impacting market entry strategies. Navigating these divergent international standards for purity, dosage, and marketing claims remains a critical challenge for manufacturers seeking a global footprint.
Market Dynamics
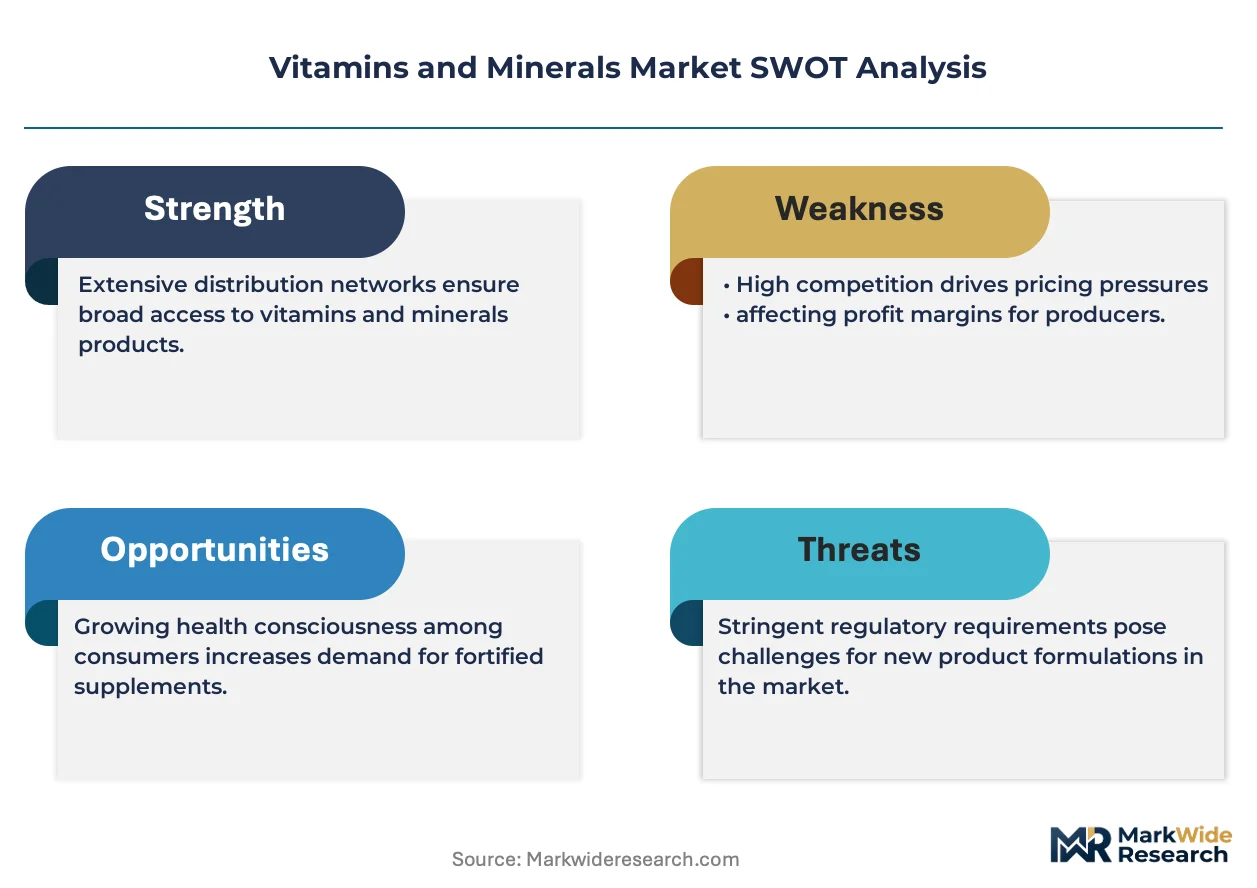
The central tension shaping the vitamins and minerals market is the collision between surging consumer demand for preventative health solutions and an increasingly stringent, fragmented global regulatory landscape that governs product claims, purity, and market access.
Growth Catalysts
- Food Fortification Mandates:National public health initiatives and World Health Organization guidelines encouraging the fortification of staple foods like flour and milk with iron, folic acid, and Vitamin A create a stable, large-scale demand base for specific micronutrients.
- Aging Demographics:An expanding elderly population, particularly in developed economies and China, drives consumption of supplements such as calcium and Vitamin D for bone health and B vitamins for cognitive function, creating a dedicated consumer segment.
- Functional Foods Expansion:Consumer preference for obtaining health benefits through everyday foods and beverages is expanding the application of vitamins and minerals beyond pills into fortified snacks, drinks, and dairy products, broadening the market's reach.
Market Restraints
- Regulatory Divergence:Significant differences in requirements for registration, dosage limits, and health claims between bodies like the US FDA, Europe's EFSA, and China's NMPA create high compliance costs and barriers to entry for global brands.
- Raw Material Volatility:The supply of certain vitamin precursors and minerals is geographically concentrated, exposing manufacturers to price fluctuations and supply chain disruptions driven by geopolitical factors or environmental conditions in key sourcing regions.
- Whole Food Preference:A persistent consumer belief that nutrients are best obtained from a balanced diet of whole foods acts as a substitution threat, limiting the perceived necessity of supplementation for some consumer segments.
Strategic Opportunities
- Personalized Nutrition Platforms:The integration of at-home diagnostic testing with direct-to-consumer subscription services offers a significant opportunity to provide customized vitamin and mineral regimens, moving beyond one-size-fits-all multivitamins.
- Underpenetrated Geographies:Markets in Southeast Asia and Latin America, where disposable incomes are rising and wellness trends are gaining traction, represent new growth frontiers for supplement manufacturers facing saturation in mature markets.
- Plant-Based and Vegan Formulations:Developing and marketing vitamins and minerals sourced from plants, such as algae-derived Vitamin D3 or fermented Vitamin K2, caters to the expanding vegan and clean-label consumer demographic.
Industry Challenges
- Health Claim Substantiation:Manufacturers face the operational challenge of funding and conducting rigorous clinical studies required to substantiate specific health claims, particularly to meet the high evidence thresholds set by regulators like the EFSA.
- Supply Chain Transparency:Ensuring end-to-end traceability and verifying the purity and potency of raw ingredients sourced globally is a persistent operational hurdle, critical for maintaining product quality and regulatory compliance.
- Combating Misinformation:The proliferation of unsubstantiated claims by unregulated sellers on social media and e-commerce platforms creates a challenging environment, requiring reputable brands to invest in consumer education to protect brand equity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamins and Minerals Market |
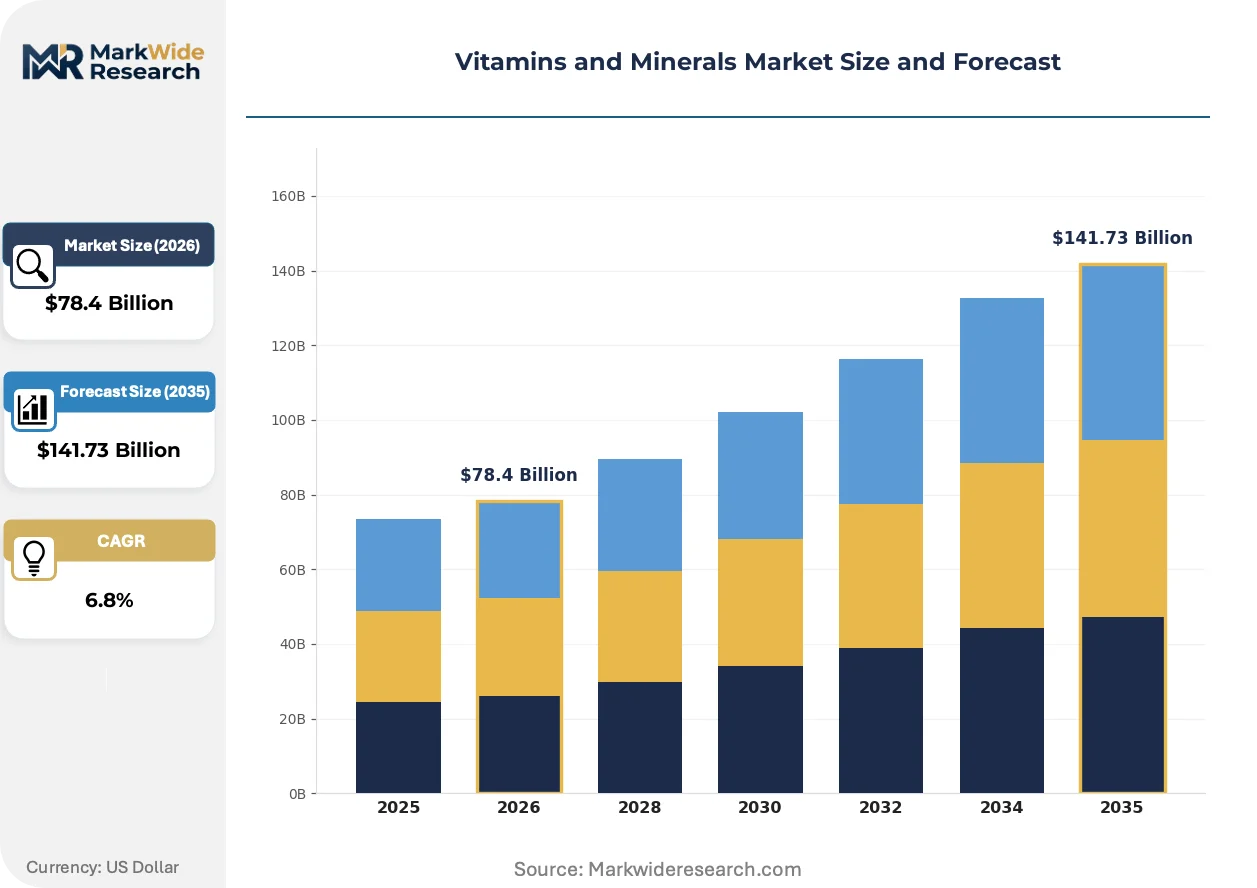
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Single Vitamins, Minerals, Herbal Supplements Application: Dietary Supplements, Food Fortification, Functional Foods, Pharmaceutical Applications End User: Retail Consumers, Clinics, Hospitals, Health Professionals Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Bayer AG, Pfizer Inc., Nestlé S.A., Abbott Laboratories, Pharmavite LLC, Amway Corp., Koninklijke DSM N.V., Haleon plc, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamins and Minerals Market Strategic Shifts & Innovations
The market's evolution is defined by a clear pivot from generic, mass-market formulations toward products emphasizing bioavailability, evidence-based claims, and hyper-personalized delivery models. This transition reflects a more sophisticated consumer base demanding demonstrable efficacy and customized health solutions.
Advanced delivery systems like liposomal encapsulation and nano-emulsions are gaining prominence for their ability to protect sensitive compounds and improve nutrient absorption. Premium supplement and functional food manufacturers are the primary adopters of these methods to differentiate their products. This focus on enhanced bioavailability is rendering obsolete many conventional, low-absorption tablet and powder formulations that fail to deliver a sufficient active dose to the body.
Stricter labeling standards from the US Food and Drug Administration (FDA) are forcing a re-evaluation of product marketing and formulation. These rules mandate clearer presentation of serving sizes and updated daily values for nutrients like Vitamin D and potassium. The dietary supplements category is most impacted, compelling brands to reformulate products and redesign packaging to align with the new fact panels, increasing short-term operational costs.
A notable behavioral change is the rise of quiz-based personalization funnels on direct-to-consumer websites. These digital tools are disrupting the traditional retail experience of browsing crowded shelves in pharmacies or health stores. Consumers answer questions about their lifestyle, diet, and health goals to receive a recommended product bundle, a model most prevalent in the North American market among millennial and Gen Z demographics.
Vitamins and Minerals Market Segmentation
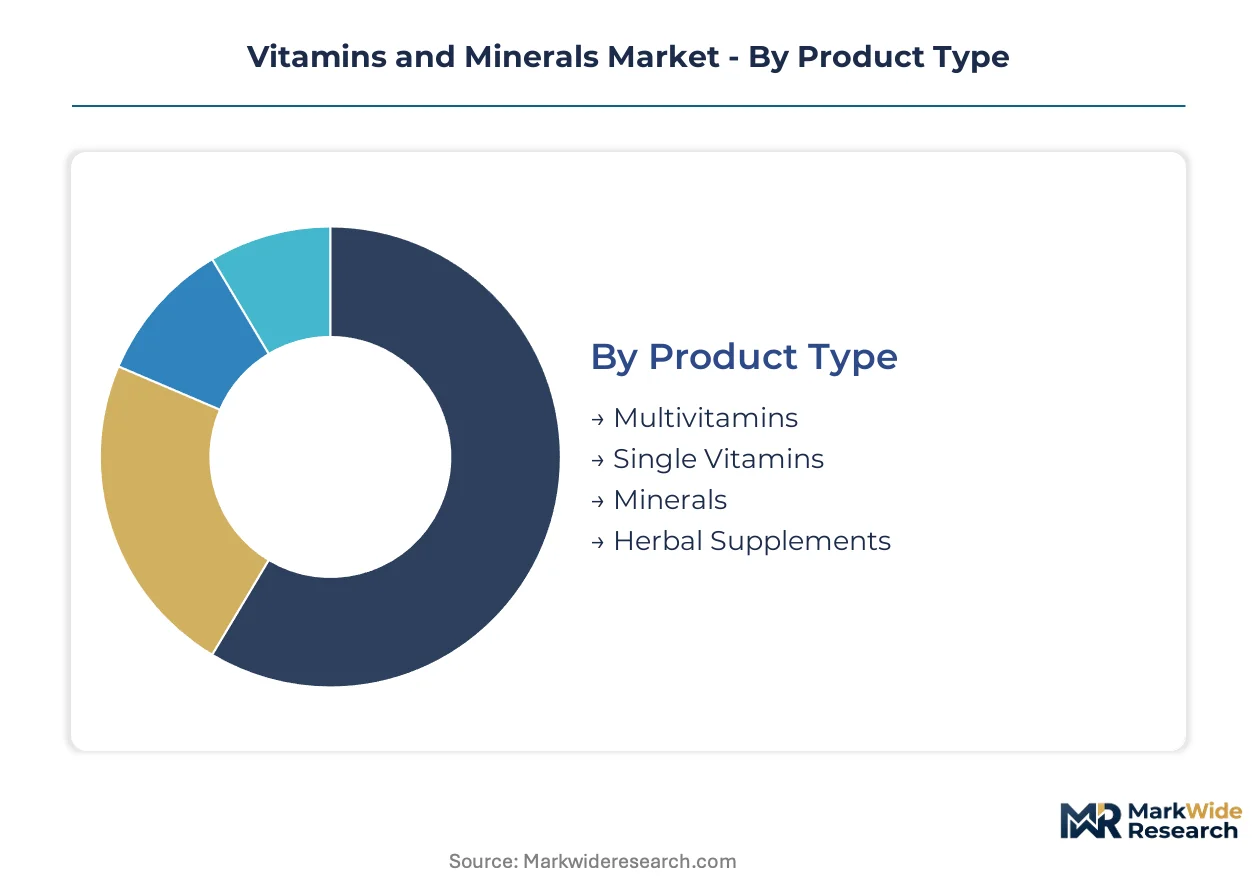
The Vitamins and Minerals Market is intricately segmented, reflecting diverse product formulations, applications, and consumer purchasing behaviors. Understanding these distinctions is crucial for manufacturers to tailor product development and market entry strategies effectively.
Product Type:
Segments within product type exhibit varying purchase frequencies and innovation cycles, influencing product lifespans and marketing efforts.
- Multivitamins:These formulations combine multiple essential vitamins and minerals into a single dose, addressing broad nutritional gaps. Demand concentrates in regions with aging populations, such as China, driven by preventative health trends.
- Single Vitamins:Individual vitamin supplements, such as Vitamin D, Vitamin C, or specific B vitamins, target particular deficiencies or health goals. Personalized nutrition platforms in North America are driving demand for these specialized offerings.
- Minerals:This category includes essential inorganic elements like calcium, magnesium, and iron, crucial for various bodily functions.
- Herbal Supplements:Plant-derived extracts and botanicals, often combined with vitamins or minerals, offer specific health benefits.
Multivitamins dominate the installed consumer base. Single Vitamins are where expansion concentrates.
Application:
Applications for vitamins and minerals span a broad spectrum, from direct consumption to integration within other products.
- Food Fortification:This involves adding vitamins and minerals to staple foods, such as flour or milk, to improve public health outcomes. Public health initiatives and WHO guidelines create stable demand in developing economies.
- Functional Foods:Vitamins and minerals are incorporated into everyday food and beverage products, like fortified yogurts or cereals, offering health benefits beyond basic nutrition. Consumer demand for convenient health solutions drives adoption in North America.
- Dietary Supplements:These are products taken orally containing a dietary ingredient intended to supplement the diet, typically in pill, capsule, or powder form.
- Pharmaceutical Applications:Vitamins and minerals are utilized as active pharmaceutical ingredients or excipients in medicinal formulations.
Dietary Supplements represent a mature segment. Functional Foods are experiencing accelerated adoption.
End User:
End users differentiate by their purchasing motivations and the specific health outcomes they seek.
- Retail Consumers:Individuals purchase vitamins and minerals directly for personal health maintenance, wellness, and preventative care. Preventative health trends and personalized direct-to-consumer models drive significant volume in China.
- Health Professionals:Doctors, dietitians, and nutritionists recommend specific vitamin and mineral regimens to patients based on clinical needs. Clinical efficacy and evidence-based solutions influence purchasing patterns in Europe.
- Clinics:Medical facilities and wellness centers administer or recommend specific vitamin and mineral therapies as part of patient treatment plans.
- Hospitals:These institutional settings utilize vitamins and minerals for patient recovery, nutritional support, and managing deficiencies.
Retail Consumers drive significant market volume. Health Professionals influence high-value, specialized product sales.
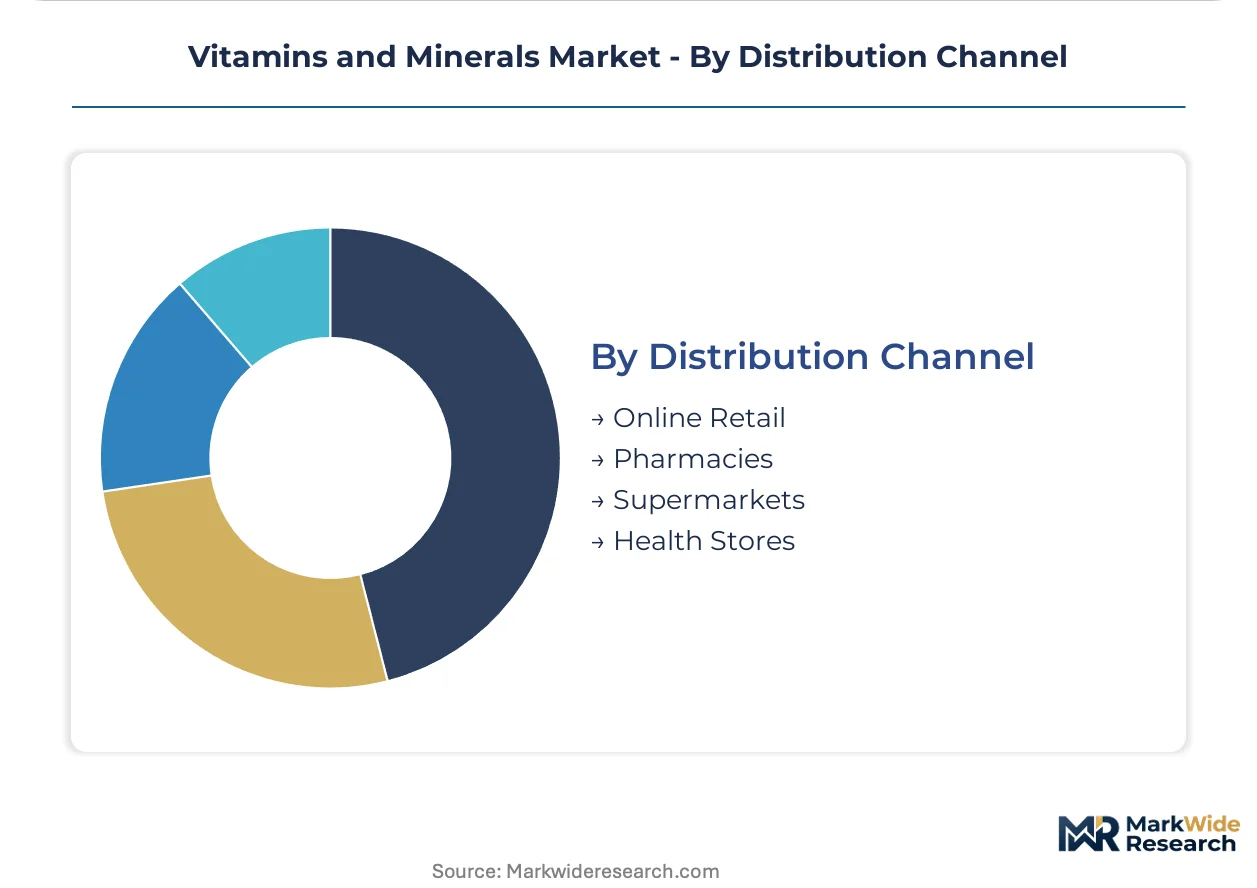
Distribution Channel:
Distribution channels reflect varied consumer access points and purchasing preferences for vitamins and minerals.
- Online Retail:E-commerce platforms and direct-to-consumer websites offer a wide selection and convenient home delivery. Personalized subscription services significantly expand reach among younger demographics in North America.
- Pharmacies:Traditional drugstores provide over-the-counter vitamins and minerals, often with professional advice from pharmacists. Consumer trust in medical settings underpins sales in Europe.
- Supermarkets:Grocery stores offer a broad range of common vitamin and mineral supplements as part of their health and wellness aisles.
- Health Stores:Specialty retailers focus on natural, organic, and niche health products, including a curated selection of vitamins and minerals.
Traditional channels like Supermarkets maintain broad reach. Online Retail is disrupting established purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly, with price-sensitive buyers in emerging markets contrasting with consumers in developed economies prioritizing premium, science-backed formulations. Regulatory harmonization remains a challenge, yet specific national mandates drive predictable demand for fortified products across diverse geographies.
China
An expanding elderly population and rising wellness trends drive consumption of supplements for bone health and cognitive function. China's NMPA sets stringent registration requirements for health food products, impacting market entry strategies. Major cities like Shanghai and Guangzhou feature robust retail consumer bases for imported and domestic vitamin brands.
United States
Preventative health trends and personalized direct-to-consumer models fuel significant volume for individual vitamins and specialized formulations. The US FDA's dietary supplement regulations influence product labeling and marketing claims. California's wellness industry innovates advanced delivery systems and quiz-based personalization platforms.
Germany
Aging demographics sustain demand for multivitamins and specific minerals like magnesium, often recommended by health professionals. Europe's EFSA health claim assessments guide product development and marketing in the region. Munich's pharmaceutical research centers contribute to advanced nutrient formulations and clinical studies.
India
Rising disposable incomes and a growing interest in preventative healthcare expand the consumer base for vitamins and minerals. India's FSSAI regulates food fortification and dietary supplements, ensuring product safety and quality. Bengaluru's burgeoning health-tech sector explores personalized nutrition solutions for urban consumers.
Brazil
Urbanization and lifestyle changes increase interest in immune support and energy-boosting supplements among retail consumers. Brazil's ANVISA oversees health product registration and market access, influencing product availability. São Paulo's food processing industry integrates vitamins into functional beverages and fortified snacks.
Vitamins and Minerals Market Key Industry Players
Capability concentration sits with specialized ingredient suppliers; scale advantage sits with consumer goods conglomerates. The market features a tiered structure, from global pharmaceutical players to niche supplement manufacturers. Companies often pursue portfolio diversification and geographic expansion to capture new consumer segments.
Consumer-facing giants like Nestlé S.A. and Bayer AG compete through strong brand recognition and expansive distribution networks, representing the mass-market archetype. These companies leverage their established presence to offer a wide range of vitamin and mineral products. Meanwhile, Koninklijke DSM N.V. exemplifies a leading ingredient supplier, leveraging its extensive portfolio to serve both pharmaceutical and food fortification segments globally.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Nestlé S.A. |
| Abbott Laboratories |
| Pharmavite LLC |
| Amway Corp. |
| Koninklijke DSM N.V. |
| Haleon plc |
| GSK plc |
| Others |
Cost & Logistics Intelligence
The global shipping lanes' cost dynamics directly influence the supply concentration of vitamin precursors and minerals, ultimately shaping downstream price differentiation for finished products.
Pricing Analysis
Contract-based long-term offtake agreements characterize the pricing model for bulk vitamin and mineral ingredients, providing stability for large manufacturers. Price differentiation stems from the ingredient's purity grade, often certified by standards like USP or EP, and the volume scale of the order. Pricing pressure stems from raw material volatility, particularly for geographically concentrated minerals, leading to cost compression in standard-grade formulations. Retail consumers of basic multivitamins represent the most price-sensitive segment, while buyers of specialized, high-bioavailability formulations exhibit lower sensitivity.
Supply Chain Analysis
Raw material volatility, driven by geopolitical factors in key sourcing regions like China for vitamin C precursors and specific African nations for certain minerals, dominates the vitamins and minerals supply chain risk. Geographic supply concentration for essential vitamin precursors includes China and India, while mineral extraction often centers on Australia and South America. Key raw material dependencies include specific organic compounds for vitamin synthesis and various inorganic mineral ores. Downstream distribution runs through a hybrid model, combining traditional retail channels with expanding online direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vitamins and Minerals Market is experiencing a buyer-power shift, driven by the fragmentation of consumer purchasing towards personalized direct-to-consumer models.
For Market Incumbents:Pre-empt the threat from agile personalized nutrition startups by investing in advanced delivery systems like liposomal encapsulation. Consolidate market share through strategic acquisitions of specialized ingredient suppliers to control critical raw material inputs. This approach leverages vertical integration as a key lever against margin pressure from generic formulations. Develop robust consumer education campaigns to counter misinformation from unregulated sellers, protecting brand equity.
For New Entrants and Emerging Players:Underpenetration in Southeast Asian markets, where rising disposable incomes meet growing wellness trends, offers a significant white-space target. Focus on plant-based and vegan formulations to cater to expanding ethical consumer demographics. A direct-to-consumer subscription model, offering quiz-based personalization funnels, provides an effective go-to-market angle for specialized single vitamins. Target the functional food application segment with novel ingredient combinations for convenient health solutions.
For Investors and Strategic Acquirers:The US FDA's stricter labeling requirements reshapes the acquisition landscape, favoring companies with strong regulatory compliance and transparent supply chains. Long-term viability over a 5-10 year window favors businesses adept at navigating fragmented global regulatory frameworks. Target acquisition archetypes should include specialized ingredient manufacturers with proprietary advanced delivery technologies or established personalized nutrition platforms. A signal to watch is the increasing adoption of clinical study-backed health claims, indicating a shift towards evidence-based product differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bioavailability R&D | Enhances product efficacy and differentiates offerings in a competitive market. |
| Acquire Personalized Nutrition Platforms | Captures direct-to-consumer channels and caters to evolving consumer demands. |
| Expand Plant-Based Portfolio | Addresses the growing vegan and clean-label consumer demographic globally. |
| Strengthen Regulatory Affairs Teams | Ensures compliance with divergent international standards like EFSA and NMPA. |
| Optimize Supply Chain Traceability | Mitigates raw material volatility and ensures product purity for consumers. |
Research Approach
Initial hypotheses were tested against primary input from supplement manufacturers, regulatory affairs specialists, and retail pharmacists, and refined through an iterative process. This involved combining in-depth interviews with industry stakeholders and validating insights against extensive secondary data sources. Secondary research included analysis of FDA filings, EFSA reports, NMPA guidelines, and trade association publications. The research employed both bottom-up and top-down triangulation to ensure data accuracy.
The analytical framework focused on balancing demand-side drivers, such as aging demographics and wellness trends, with supply-side constraints, including raw material availability. Segmentation dimensions modeled across the analysis window included product type, application, end user, distribution channel, and ingredient source. Compound annual growth rates were derived from historical data and projected forward based on identified market dynamics. Demographic shifts and regulatory changes were key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or consumer spending patterns would shift the trajectory of the Vitamins and Minerals Market. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Geopolitical instability and new regulatory mandates represent specific risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Nutritional Analysis Service Market