
 Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market | 2026-2036
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market Outlook
Aftermarket service revenue in nutritional counseling and personalized diet planning is narrowing as manufacturers embed digital health tools directly into product ecosystems. Nestle leverages its extensive dairy and beverage infrastructure to distribute fortified products across Southeast Asian markets. Abbott anchors its position through science-based clinical nutrition formulations targeting metabolic health. PepsiCo competes by extending its beverage portfolio into vitamin-enhanced functional drinks with regional flavor profiles.
Asia-Pacific vitamin fortified and mineral enriched food and beverage encompasses products where micronutrients such as iron, zinc, B-complex vitamins, and vitamin D are added through spray-drying, microencapsulation, or direct blending to achieve defined nutritional claims on finished goods labels. These products serve to address documented dietary deficiencies and support targeted physiological functions across population groups. Functional beverages capture significant margin pools due to premium positioning and repeat consumption patterns among urban professionals. Fortified dairy maintains structural dominance in rural distribution networks where cold chain infrastructure supports daily delivery models. Nutritional bars represent the fastest-expanding segment as convenience-seeking athletes and working professionals adopt portable meal replacements.
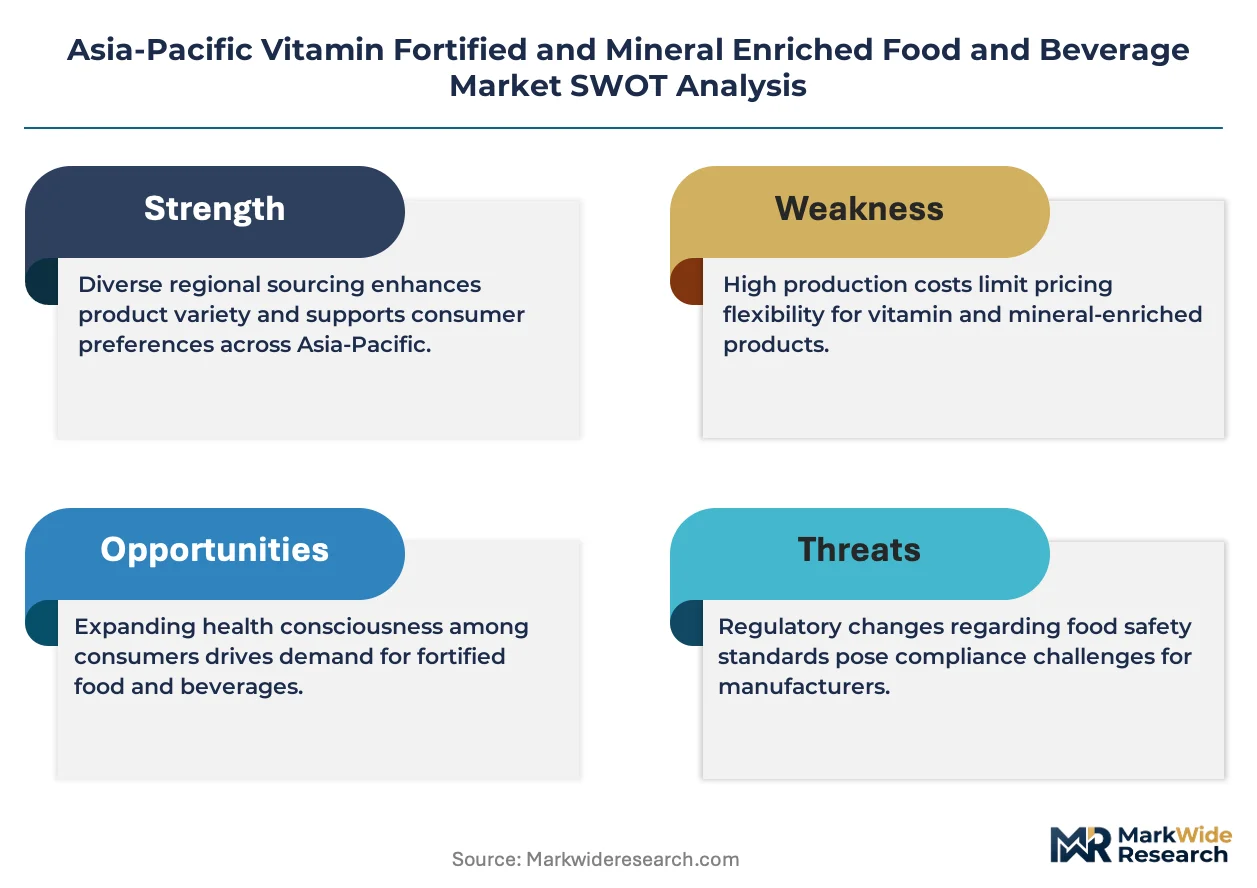
FSSAI fortification standards in India, China's GB nutritional labeling requirements, and Japan's Health Promotion Law collectively mandate micronutrient thresholds and disclosure formats that determine product eligibility for health claims. These frameworks create compliance barriers that favor established manufacturers with analytical laboratories and regulatory affairs capabilities. Stakeholders must monitor evolving permissible nutrient ranges and front-of-pack labeling mandates as these will determine which reformulated products retain shelf access across the region's fragmented retail landscape.
Market Dynamics
FSSAI fortification standards in India are compressing formulation cycles as manufacturers re-engineer product matrices to meet micronutrient disclosure thresholds before enforcement deadlines.
Growth Catalysts
- Urban preventive health pivot:Chinese metropolitan consumers are redirecting food expenditure toward vitamin-enhanced SKUs that address documented D3 and iron deficiencies identified in national nutrition surveys.
- GB nutritional labeling alignment:China's revised pre-packaged food standards are compelling cross-border brands to standardize micronutrient claim formats, reducing regulatory friction for compliant entrants.
- Microencapsulation scale-up:Spray-drying and lipid-coating technologies are stabilizing heat-sensitive vitamins in ready-to-drink formats, extending shelf life in tropical distribution corridors.
Market Restraints
- Vitamin premix cost volatility:Concentrated supply of vitamin D3 and B-complex raw materials through Chinese chemical manufacturers exposes margins to input price swings.
- Cold chain infrastructure gaps:Rural India and Indonesia lack temperature-controlled last-mile networks, limiting fortified dairy penetration outside urban clusters.
- Japan's Health Promotion Law complexity:Functional claim categorization requires clinical substantiation that extends product development timelines by 18-24 months for new entrants.
Strategic Opportunities
- Vietnam's underpenetrated convenience channel:Modern trade expansion in Ho Chi Minh City and Hanoi creates shelf space for fortified RTD beverages targeting office workers.
- Digital health convergence:Integration of micronutrient tracking apps with e-commerce platforms is virtualizing personalized nutrition recommendations that drive repeat purchase.
- Australia TGA novel food pathways:Simplified approval frameworks for bioactive-enriched products offer faster market access for innovators with clinical data packages.
Industry Challenges
- Analytical laboratory scarcity:Validated micronutrient testing capacity concentrates in Singapore and Shanghai, creating bottlenecks for regional manufacturers seeking batch certification.
- Reformulation complexity:Achieving FSSAI iron fortification thresholds in wheat flour without sensory degradation requires enzyme pre-treatment investments that strain mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market |
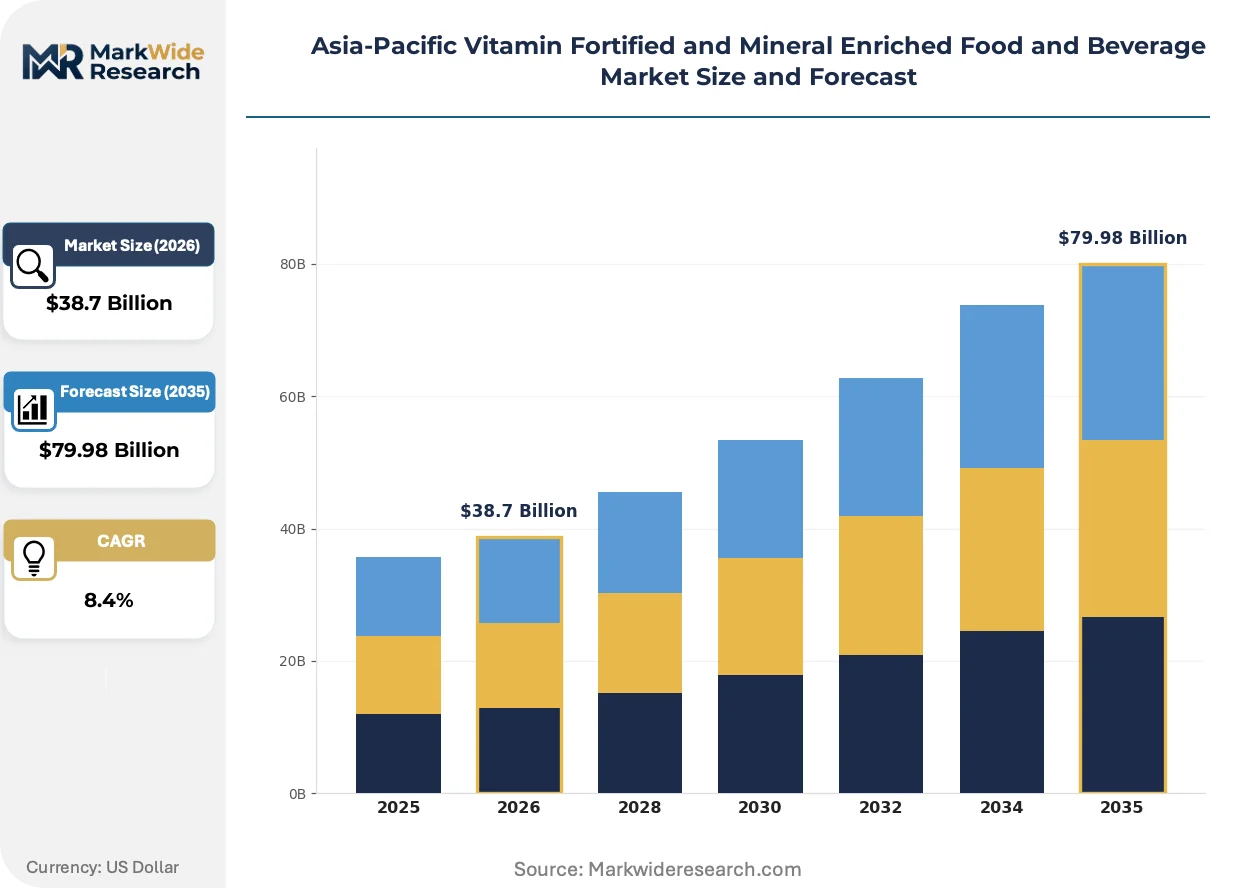
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Beverages, Nutritional Bars, Fortified Dairy, Enriched Grains Ingredient: Vitamins, Minerals, Fiber, Amino Acids End User: Children, Athletes, Pregnant Women, Seniors Distribution Channel: Supermarkets, E-commerce, Health Stores, Convenience Stores |
| Companies Covered | Abbott, Nestle, Kellogg Company, PepsiCo, Amway, Coca-Cola Company, Hain Celestial Group, Campbell Soup, Otsuka Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market Strategic Shifts
Digital infrastructure is collapsing the distance between manufacturer and consumer in Asia-Pacific fortified food markets, enabling direct feedback loops that accelerate product iteration cycles.
Microencapsulation via spray-drying and complex coacervation is virtualizing the stability problem for water-soluble vitamins in ambient beverages. Sports nutrition brands in Australia and South Korea are adopting these barrier technologies at commercial scale. The structural consequence is compression of the premium-functional pricing gap as shelf-stable formats displace refrigerated alternatives.
India's FSSAI fortification mandates for edible oils and milk are forcing ingredient suppliers to standardize premix concentrations across multiple dairy cooperative networks. Large processors in Gujarat and Maharashtra are consolidating supplier relationships to secure batch-to-batch consistency. Small regional dairies without in-house blending capability face exclusion from government procurement channels.
Urban professionals across Southeast Asia are abandoning traditional retail discovery in favor of subscription-based personalized nutrition bundles. Direct-to-consumer platforms in Singapore and Bangkok are capturing recurring revenue through algorithm-driven micronutrient matching. This behavioral shift concentrates brand loyalty with data-integrated players while eroding impulse-driven supermarket purchases.
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market Segmentation
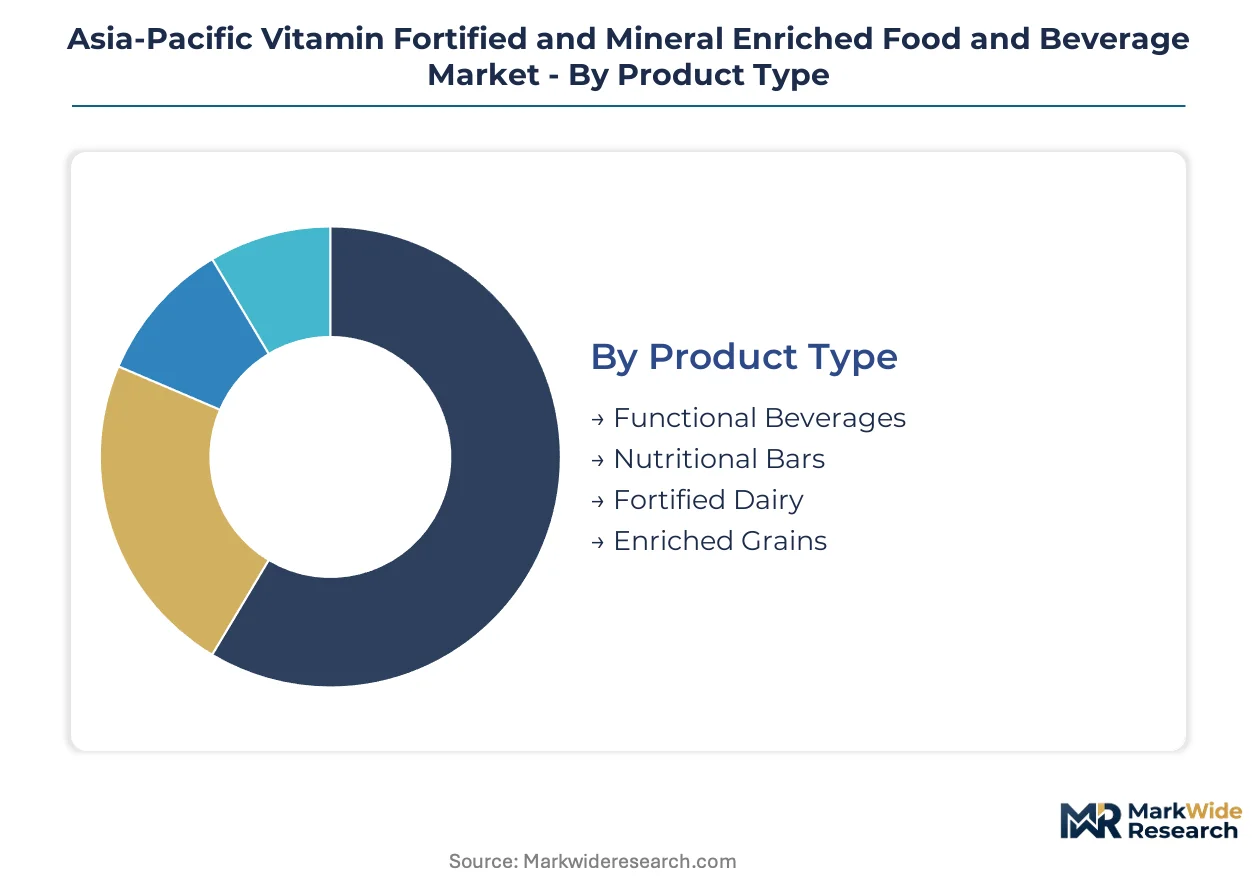
Segmentation in the Asia-Pacific vitamin fortified and mineral enriched food and beverage market reveals distinct technical requirements and channel economics across product formats. Each category carries different regulatory burdens, shelf-life constraints, and consumer education costs that determine manufacturer positioning strategies.
Product Type:
After-sales service intensity varies sharply across product formats, with refrigerated fortified dairy demanding cold chain maintenance and nutritional bars requiring minimal post-purchase support.
- Functional Beverages:Ready-to-drink formulations incorporate heat-stable vitamin premixes through microencapsulation or direct blending. Demand concentrates among urban professionals in Shanghai and Singapore seeking portable micronutrient solutions during commute hours. FSSAI and GB labeling mandates drive reformulation cycles.
- Nutritional Bars:Compressed food matrices deliver protein, fiber, and B-complex vitamins through extrusion and enrobing processes. Athletes in Australia and South Korea drive repeat purchase patterns for pre-workout and recovery applications. Shelf-stable formats reduce distribution complexity versus refrigerated alternatives.
- Fortified Dairy:Milk and yogurt products receive spray-dried vitamin D and iron premixes at processing facilities. Rural India and Indonesia present cold chain infrastructure gaps that limit penetration outside urban clusters.
- Enriched Grains:Wheat flour and rice receive micronutrient coatings through drum-drying or extrusion. FSSAI mandates for edible oil and wheat fortification reshape procurement patterns for Gujarat and Maharashtra processors.
Fortified dairy holds the largest share; momentum sits with nutritional bars.
Ingredient:
Cost tier differentiation separates commodity premix suppliers from specialty bioactive compound manufacturers serving premium positioning strategies.
- Vitamins:Fat-soluble A, D, E, K and water-soluble B-complex, C compounds stabilize through lipid coating or spray-drying. Chinese chemical manufacturers concentrate supply of D3 and B-complex raw materials, exposing margins to input volatility.
- Minerals:Iron, zinc, calcium, and selenium compounds require chelation or microencapsulation to prevent metallic off-flavors. Pregnant women across Southeast Asia drive iron-fortified product selection based on clinical recommendations.
- Fiber:Soluble and insoluble variants from oat, chicory, or psyllium sources enhance digestive health positioning. Seniors in Japan and South Korea prioritize fiber-enriched formulations for metabolic management.
- Amino Acids:Branched-chain and essential amino acid fortification targets muscle protein synthesis claims. Sports nutrition applications in Australia and Thailand adopt these additions for performance positioning.
Vitamins dominate volume; amino acids gain share fastest.
End User:
Application-specific formulation requirements create divergent product development timelines, with pediatric and maternal nutrition demanding extended safety substantiation.
- Children:Iron, zinc, and vitamin A fortification addresses documented deficiency patterns in national nutrition surveys. India's Integrated Child Development Services program channels fortified foods through anganwadi centers.
- Athletes:Protein-amino acid matrices with electrolyte minerals target hydration and recovery positioning. Australia's TGA novel food pathways enable faster approval for clinically substantiated sports nutrition innovations.
- Pregnant Women:Folic acid, iron, and DHA fortification follows WHO prenatal guidelines. FSSAI mandates specific micronutrient thresholds for maternal health product labeling.
- Seniors:Vitamin D, calcium, and B12 fortification addresses absorption decline and bone density maintenance. Japan's Health Promotion Law categorization requires clinical substantiation extending development timelines.
Children represent the largest addressable population; athletes show steepest expansion trajectory.
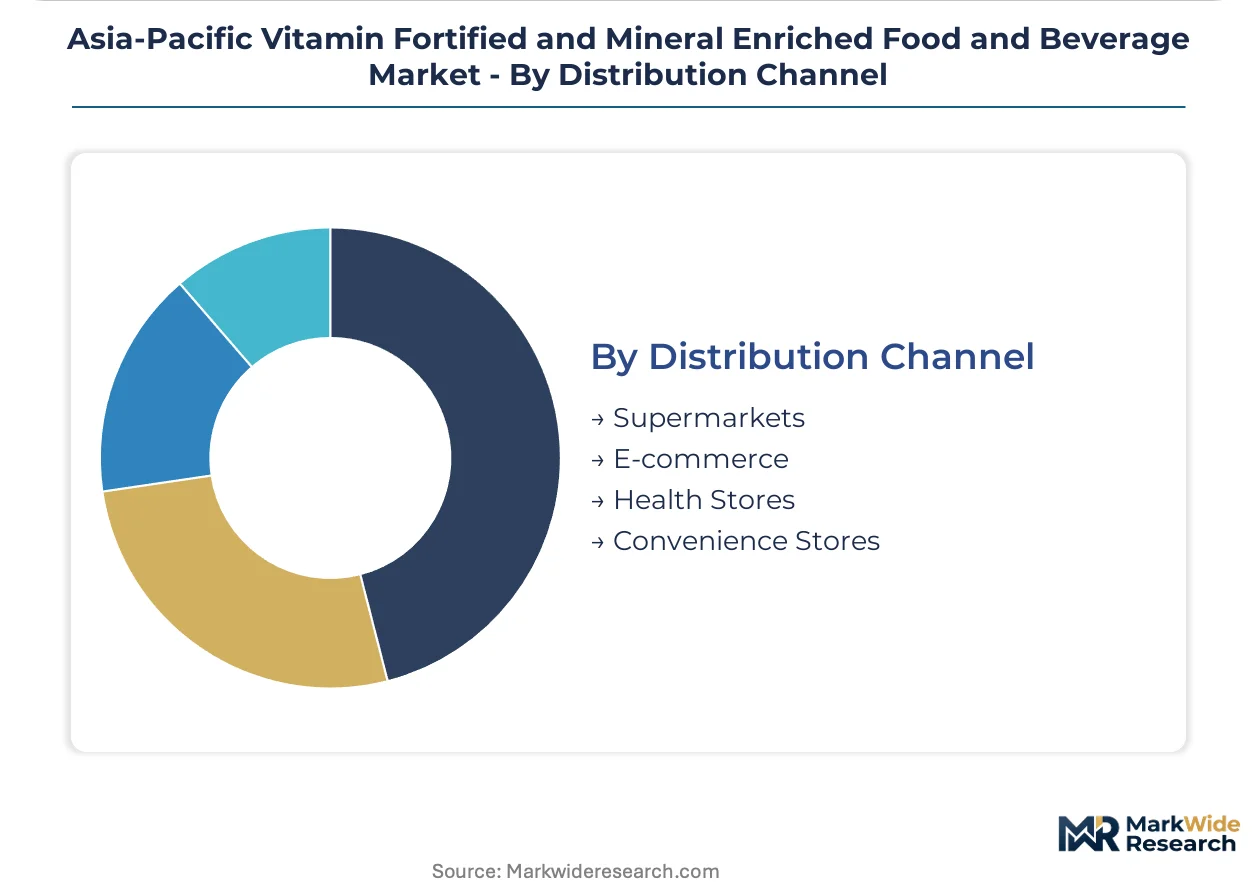
Distribution Channel:
Geography of demand concentration shifts channel investment priorities, with metropolitan digital adoption diverging from rural traditional retail dependence.
- Supermarkets:Modern trade formats in Bangkok, Jakarta, and Manila provide shelf space for multi-SKU fortified portfolios. Front-of-pack labeling compliance determines placement eligibility under FSSAI and GB standards.
- E-commerce:Direct-to-consumer platforms in Singapore and Ho Chi Minh City enable subscription-based personalized nutrition bundles. Algorithm-driven micronutrient matching concentrates loyalty with data-integrated players.
- Health Stores:Specialized retail in Australia and Japan serves clinical nutrition and premium functional positioning. Pharmacist consultation requirements extend purchase decision cycles.
- Convenience Stores:Urban grab-and-go formats in Seoul, Tokyo, and Taipei capture impulse functional beverage purchases. Limited refrigeration capacity favors ambient-stable vitamin formats.
Supermarkets retain volume leadership; e-commerce climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Asia-Pacific, with Chinese urban professionals prioritizing preventive functional beverages while Indian rural distribution relies on fortified dairy through government channels.
China
Metropolitan consumers in Shanghai and Beijing redirect food expenditure toward vitamin D3 and iron-enhanced SKUs following national nutrition survey findings. GB standards for pre-packaged food labeling compel cross-border brands to standardize micronutrient claim formats. Yangtze River Delta processing clusters scale spray-drying infrastructure to stabilize heat-sensitive vitamins in ready-to-drink formats.
India
Integrated Child Development Services channels fortified wheat flour and edible oils through anganwadi centers targeting documented deficiency patterns. FSSAI fortification mandates compress formulation cycles as Gujarat and Maharashtra processors re-engineer product matrices. Dairy cooperatives in these states consolidate supplier relationships to secure batch-to-batch premix consistency.
Japan
Seniors in Tokyo and Osaka prioritize fiber-enriched formulations for metabolic management amid aging demographics. Health Promotion Law categorization demands clinical substantiation extending product development timelines. Kanto region manufacturers concentrate analytical laboratory capacity for micronutrient batch certification.
Australia
Athletes in Sydney and Melbourne drive sports nutrition adoption for pre-workout and recovery applications. TGA novel food pathways enable faster market access for innovators with clinical data packages. Victoria-based processors leverage simplified approval frameworks for bioactive-enriched product launches.
Vietnam
Office workers in Ho Chi Minh City and Hanoi create demand for fortified RTD beverages through modern trade expansion. Convenience channel underpenetration offers shelf space for ambient-stable vitamin formats. Southern processors face cold chain infrastructure gaps limiting fortified dairy penetration outside urban clusters.
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market Competitive Environment
Capability concentration sits with multinational nutrition science specialists; scale advantage sits with diversified food and beverage conglomerates leveraging existing distribution infrastructure. The market structure tiers between clinical-formulation leaders and mass-market portfolio extenders. Three archetypes dominate: science-based clinical nutrition developers, dairy and beverage infrastructure deployers, and functional beverage portfolio diversifiers. Competitive moves center on regulatory compliance capacity building and direct-to-consumer platform integration.
Among diversified nutrition and beverage conglomerates, Abbott, Nestle, and PepsiCo exemplify distinct strategic positioning. Abbott occupies the clinical-formulation tier with science-based metabolic health targeting. Nestle anchors the dairy and beverage infrastructure deployment archetype through Southeast Asian distribution networks. PepsiCo represents functional beverage portfolio extension with regional flavor adaptation. These three players illustrate how regulatory affairs capabilities and cold chain infrastructure control separate market access tiers.
| Leading Market Players |
|---|
| Abbott |
| Nestle |
| Kellogg Company |
| PepsiCo |
| Amway |
| Coca-Cola Company |
| Hain Celestial Group |
| Campbell Soup |
| Otsuka Holdings |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor's cost dynamics compress vitamin premix procurement margins for processors while amplifying price differentiation between FSSAI-compliant fortified dairy and commodity-grade alternatives across Southeast Asian distribution networks.
Pricing Analysis
Long-term offtake contracts for vitamin D3 and B-complex premixes dominate procurement between Gujarat dairy cooperatives and Chinese chemical manufacturers, insulating large processors from spot market volatility that strains mid-tier competitors. Three-tier pricing structure across premium clinical-nutrition, standard fortified-dairy, and economy edible-oil segments reflects certification investment levels and cold chain infrastructure control. Cost compression in economy-tier wheat flour intensifies because FSSAI iron fortification mandates require enzyme pre-treatment investments. Small regional dairies exhibit highest price sensitivity due to batch certification bottlenecks, while Abbott and Nestle leverage scale for least sensitivity.
Supply Chain Analysis
Export-control regimes on microencapsulation spray-drying equipment from Germany and Japan limit technology transfer to Indian and Vietnamese processors, constraining heat-stable vitamin production capacity. Supply concentrates in China for vitamin raw materials, India for dairy processing infrastructure, and Australia for sports nutrition formulation. Raw material dependencies span vitamin D3 chemical precursors, lipid coating compounds, and iron chelation agents. Single-source vulnerability runs through concentrated Chinese vitamin manufacturers. Distribution runs through dairy cooperative networks in rural India, modern trade in Chinese metropolitan clusters, and direct-to-consumer platforms in Singapore and Bangkok.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FSSAI fortification standards and GB labeling requirements constructs defensive moats for incumbents with analytical laboratory networks and pre-existing government procurement relationships.
For Market Incumbents: Harden compliance infrastructure by consolidating premix supplier relationships to secure batch-to-batch consistency under tightening FSSAI enforcement timelines. Expand in-house spray-drying capacity across Maharashtra and Gujarat to capture government channel procurement. Vertical integration into microencapsulation technology acquisition offsets emerging entrant threat from Australian TGA-approval specialists. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated convenience channel for ambient-stable functional beverages targeting Ho Chi Minh City office workers. Target subscription-based personalized nutrition bundles through algorithm-driven micronutrient matching platforms in Singapore and Bangkok. Prioritize direct-to-consumer launch with digital health app integration to bypass entrenched supermarket shelf access barriers. For Investors and Strategic Acquirers: Mid-cap clinical nutrition developers with TGA novel food pathway experience and existing micronutrient tracking app platforms represent priority acquisition targets. Long-term viability hinges on regulatory affairs capability depth and cold chain infrastructure control across tropical distribution corridors. Watch FSSAI enforcement deadline adherence rates as inflection indicator for incumbent margin compression versus consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Heat-stable vitamin production capacity expansion enables ambient beverage shelf-life extension across tropical Southeast Asian corridors. |
| Direct-to-Consumer Platform Integration | Algorithm-driven micronutrient matching concentrates brand loyalty with data-integrated players in Singapore and Bangkok. |
| FSSAI Compliance Certification Investment | Analytical laboratory accreditation secures government procurement channel access for Gujarat and Maharashtra dairy cooperatives. |
| Cold Chain Infrastructure Partnership | Temperature-controlled last-mile networks unlock fortified dairy penetration outside Indonesian and Indian urban clusters. |
| Sports Nutrition Brand Extension | Australia's TGA novel food pathways enable faster approval for clinically substantiated pre-workout and recovery formulations. |
Study Parameters
Desk research of FSSAI regulatory filings, GB nutritional labeling standards, and India nutrition survey data preceded structured interviews with dairy cooperative procurement managers, vitamin premix suppliers, regulatory affairs directors at multinational nutrition companies, and e-commerce platform category heads across Singapore and Vietnam. Secondary validation drew from customs trade records, retail audit databases, and government health program documentation. Bottom-up segment sizing triangulated against top-down macroeconomic consumption projections.
Assumptions held FSSAI fortification enforcement timelines and GB labeling standardization as fixed conditions while varying urbanization rates and digital health adoption curves across the projection horizon. The analytical framework modeled product type, ingredient category, end-user demographic, and distribution channel segmentation dimensions. CAGRs derived from historical consumption elasticity coefficients applied to population cohort projections and per-capita expenditure shifts. Forecast inputs incorporated cold chain infrastructure development pipelines and micronutrient deficiency prevalence trends from national health surveys.
Sensitivities concentrate around FSSAI enforcement acceleration, vitamin premix supply disruptions from Chinese chemical manufacturers, and digital health platform regulatory frameworks. Forecasts reflect documented assumptions regarding urban professional preventive health pivot persistence and government procurement channel stability. Material shifts in India's Integrated Child Development Services program scope or China's dual carbon goals affecting chemical manufacturing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
South America Food Fortifying Agents Market