
 Global Mineral Fortification Market | 2026-2036
Global Mineral Fortification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mineral Fortification Market Foresight
Iron fortification premixes is shifting from ferrous sulfate to encapsulated ferrous bisglycinate in premium infant nutrition applications, improving bioavailability while masking metallic off-notes. BASF SE anchors this transition through its chelated mineral portfolio, while DSM-Firmenich AG leverages micronutrient premix expertise across dairy and bakery channels. Cargill, Incorporated competes on backward integration into grain sourcing for cereal fortification programs.
Mineral fortification denotes the deliberate incorporation of essential inorganic nutrients—typically calcium carbonate, ferrous fumarate, zinc oxide, or potassium iodide at dosages measured in milligrams per serving—into processed foods and supplements to correct population-level deficiencies. Powder fortificants dominate volume due to blending compatibility with flour and salt matrices, though liquid formats are gaining share in beverage applications where dispersion uniformity is critical. Iron fortificants command the largest revenue pool given anemia prevalence, while zinc fortificants represent the fastest-expanding category tied to immune-health positioning in dietary supplements.
The FDA governs GRAS notifications for mineral additives in US food channels, while EFSA establishes population reference intakes that shape European fortification ceilings. India's FSSAI mandates standards for fortified rice kernels under its food safety framework, directly creating institutional demand for premix suppliers. Stakeholders must monitor evolving bioequivalence requirements for novel chelated forms against established inorganic salts.
Market Dynamics
Encapsulation chemistry is consolidating competitive advantage in premium infant nutrition, as manufacturers abandon metallic-tasting ferrous sulfate for chelated bisglycinate forms that mask off-notes while preserving bioavailability. This technical pivot is reshaping premix procurement criteria and supplier qualification timelines across the value chain.
Growth Catalysts
- India's FSSAI rice fortification mandate:Government-mandated distribution of fortified kernels through public distribution systems is institutionalizing premix demand at scale.
- EFSA purity threshold tightening:Updated Food Supplements Directive specifications are accelerating replacement of technical-grade fortificants with pharmaceutical-grade alternatives.
- Southeast Asian infant formula expansion:Regional manufacturers are accelerating iron and zinc premix procurement to serve birth-rate-driven formula consumption.
Market Restraints
- Chelated mineral input cost volatility:Ferrous bisglycinate and zinc glycinate production depends on amino acid feedstock pricing that fluctuates with agricultural commodity cycles.
- Chinese encapsulation technology concentration:A majority of lipid-shell and ethylcellulose coating capacity sits with specialized chemical processors in Jiangsu and Zhejiang provinces.
- GRAS notification friction:FDA review timelines for novel mineral forms extend qualification periods for US market entry beyond typical product development cycles.
Strategic Opportunities
- Beverage dispersion formats:Liquid fortificant demand is accelerating in functional drinks and dairy alternatives where powder homogenization fails.
- Brazilian school feeding programs:Federal procurement of fortified wheat flour for national lunch programs creates institutional volume anchors.
- Dual carbon alignment:EU Green Deal carbon accounting rules favor regional fortificant production over long-haul Asian supply chains.
Industry Challenges
- Bioequivalence study capacity:Demonstrating non-inferiority of novel chelated forms against established inorganic salts requires clinical endpoints that strain CRO availability.
- Legacy salt matrix integration:Replacing ferrous sulfate in existing flour and salt fortification infrastructure without reformulating downstream processing parameters demands extensive line trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mineral Fortification Market |
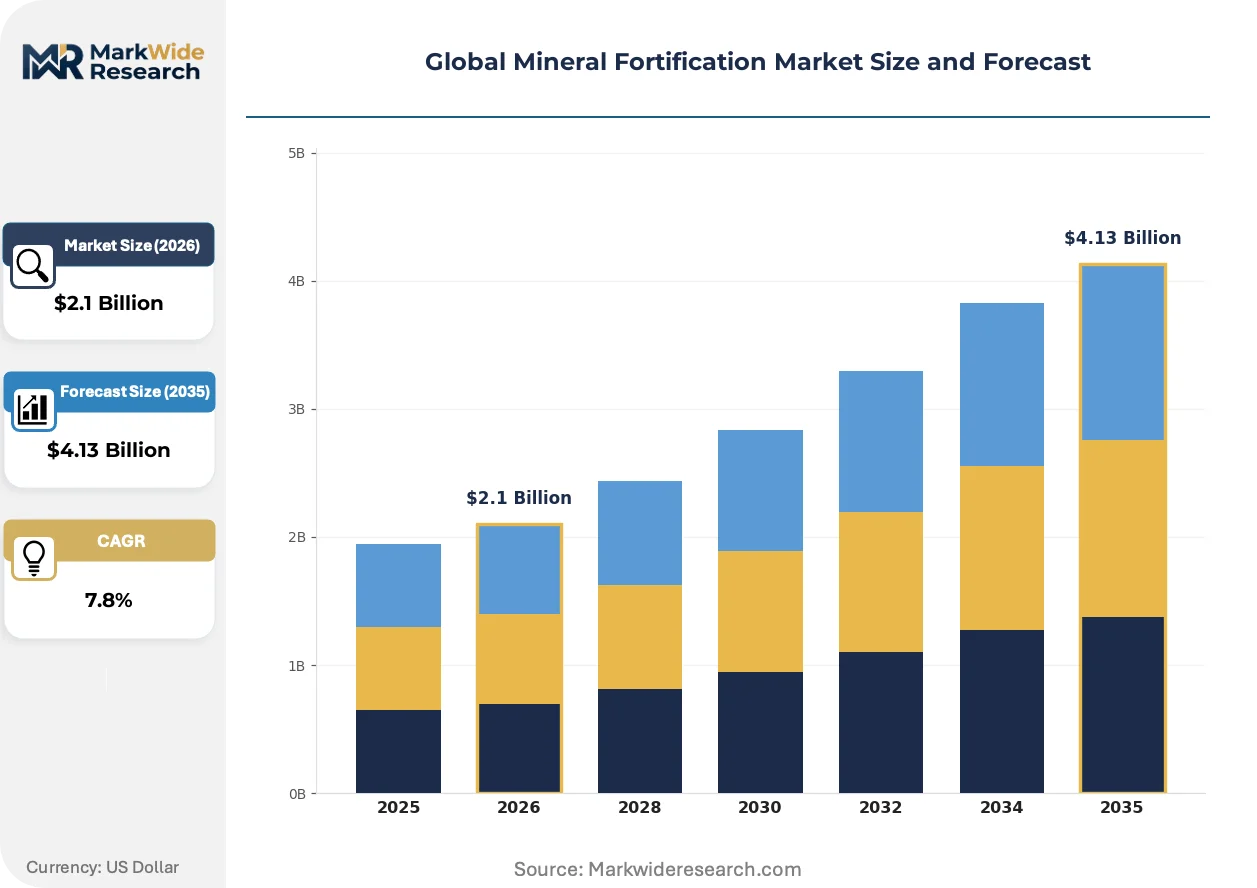
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Fortificants, Iron Fortificants, Zinc Fortificants, Magnesium Fortificants, Iodine Fortificants, Copper Fortificants Application: Dairy Products, Bakery Items, Beverages, Infant Nutrition, Cereals, Confectionery Form: Powder, Liquid, Granules, Capsules, Tablets, Drops End User: Food Manufacturers, Nutraceutical Companies, Beverage Producers, Infant Formula Manufacturers, Animal Feed Producers, Dietary Supplement Makers |
| Companies Covered | BASF SE, Cargill, Incorporated, DSM-Firmenich AG, Archer Daniels Midland Company, Merck KGaA, DuPont de Nemours Inc, Pestell Nutrition Inc, Abbott Laboratories, Balchem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mineral Fortification Market Shifts & Advancements
Active encapsulation platforms are displacing conventional mineral salts across premium positioning tiers, while regulatory jurisdictions compete to set purity benchmarks that reshape supplier qualification. These forces are compressing the viable supplier base and elevating technical chemistry capabilities as a competitive moat.
Encapsulated ferrous bisglycinate is consolidating its position in infant formula applications where metallic off-notes previously limited iron loading. Premium nutrition manufacturers in Western Europe and North America have completed formulation transitions, with mid-tier brands now qualifying suppliers. This chemistry shift is consolidating premix supply relationships around partners with captive chelation and microencapsulation capabilities.
REACH candidate list expansion for nickel and cobalt compounds is forcing fortificant manufacturers to requalify raw material streams and validate alternative catalyst systems in mineral salt production. The regulation is compressing acceptable impurity profiles for zinc oxide and copper sulfate destined for EU food channels. Supplement and functional food brands are responding by demanding full supply chain disclosure from premix partners.
Direct premix procurement by multinational food manufacturers is displacing traditional distributor intermediaries in high-volume cereal and dairy applications. Category leaders are establishing captive blending operations near grain processing hubs to secure fortification integrity. This channel restructuring is most visible in North American and Australian markets where vertical integration into grain sourcing already exists.
Global Mineral Fortification Market Segmentation
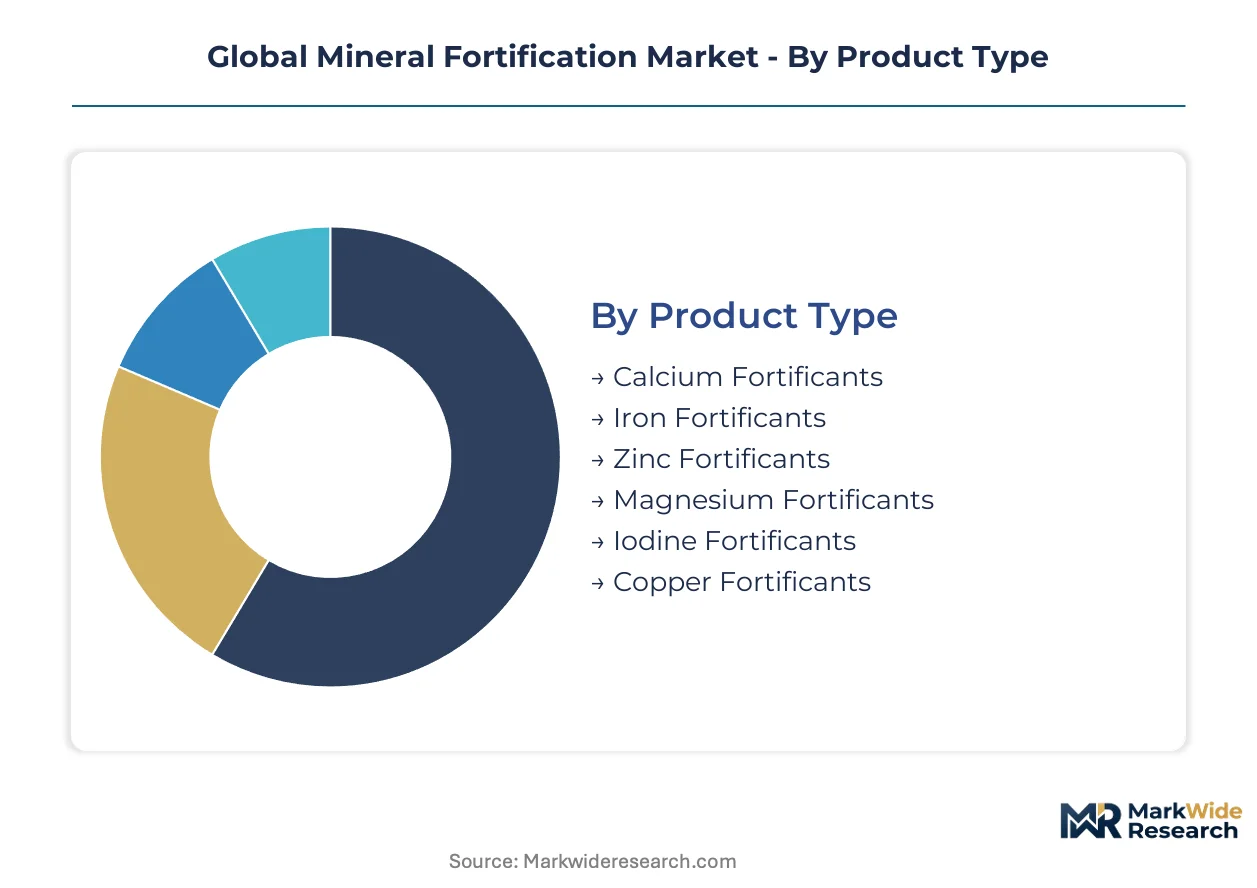
Segmentation in mineral fortification tracks how technical specifications, regulatory thresholds, and application requirements fragment procurement patterns. Each dimension reveals distinct margin structures and supplier qualification barriers that reshape competitive positioning across the value chain.
Product Type:
Standardization dominates commodity mineral salts while customization intensifies for chelated and encapsulated forms serving premium nutrition channels.
- Iron Fortificants:Ferrous sulfate remains the workhorse for mass flour and rice fortification programs, though ferrous bisglycinate chelates command premium positioning in infant formula where metallic off-notes compromise consumer acceptance. India's FSSAI-mandated rice fortification is institutionalizing ferrous fumarate procurement at scale.
- Zinc Fortificants:Zinc oxide serves cost-sensitive salt and cereal applications, while zinc glycinate and zinc picolinate penetrate immune-health supplements and pediatric nutrition where bioavailability claims support price premiums. Southeast Asian formula manufacturers are accelerating zinc premix procurement.
- Calcium Fortificants:Calcium carbonate dominates bakery and dairy fortification for bone-health positioning.
- Magnesium Fortificants:Magnesium oxide and citrate formats serve sports nutrition and relaxation-positioned supplements.
- Iodine Fortificants:Potassium iodate remains the standard for salt iodization programs across South Asia and Africa.
- Copper Fortificants:Copper sulfate and gluconate serve niche applications in hematological supplements and specialized animal nutrition.
Most installed capacity flows through Iron Fortificants. Expansion is steepest in Zinc Fortificants.
Application:
Volume concentrates in staple food channels while value migrates toward specialized nutrition segments with stringent purity requirements.
- Infant Nutrition:Iron and zinc premixes undergo the most rigorous supplier qualification, with EFSA purity thresholds and FDA GRAS notifications creating multi-year approval timelines. Encapsulated ferrous bisglycinate has displaced conventional salts in premium Western European and North American formulations.
- Beverages:Liquid fortificant demand is accelerating in functional drinks and dairy alternatives where dispersion uniformity exceeds powder blending capabilities. This application commands the steepest formulation premiums due to stability challenges.
- Dairy Products:Calcium and vitamin D fortification remains standard across fluid milk and yogurt segments.
- Bakery Items:Iron and B-vitamin premixes integrate into flour fortification for public health programs.
- Cereals:Breakfast cereal manufacturers deploy multi-nutrient premixes for front-of-pack positioning.
- Confectionery:Calcium and magnesium fortification penetrates functional candy and chocolate segments.
Procurement volumes peak in Bakery Items. Value capture concentrates in Infant Nutrition.
Form:
Powder formats leverage existing blending infrastructure while liquid and encapsulated forms require capital-intensive dispersion or coating capabilities.
- Powder:Dominates flour, salt, and cereal fortification due to mechanical blending compatibility with existing grain processing infrastructure. This form captures the largest volume share across institutional procurement programs.
- Liquid:Gaining share in beverage and dairy alternative applications where homogenization ensures dispersion uniformity. Chinese and European processors are expanding lipid-based suspension capacity.
- Granules:Serves intermediate applications requiring controlled release in animal feed and bulk supplements.
- Capsules:Standard for direct-to-consumer dietary supplements with precise unit dosing.
- Tablets:Dominates mass-market multivitamin and mineral supplement formats.
- Drops:Pediatric and geriatric positioning where swallowing difficulties limit solid formats.
Processing economics favor Powder for high-volume channels. Technical differentiation concentrates in Liquid.
End User:
Direct procurement by multinational food manufacturers is displacing distributor intermediaries in high-volume segments, while specialized nutrition channels retain multi-tier sourcing.
- Food Manufacturers:Cereal and dairy processors are establishing captive blending operations near grain hubs to secure fortification integrity, particularly visible in North American and Australian markets with backward integration into sourcing.
- Infant Formula Manufacturers:Qualification timelines for mineral premix suppliers extend 18-36 months due to pharmaceutical-grade purity requirements and clinical validation protocols. Southeast Asian producers are expanding iron and zinc premix procurement.
- Nutraceutical Companies:Demand chelated and encapsulated forms for immune-health and bioavailability positioning.
- Beverage Producers:Require liquid suspension expertise for functional drink fortification.
- Animal Feed Producers:Source mineral premixes for livestock nutrition and aquaculture applications.
- Dietary Supplement Makers:Span from commodity tablet manufacturers to premium capsule specialists.
Contract volumes concentrate with Food Manufacturers. Supplier margins peak with Infant Formula Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor global encapsulation capacity for lipid-shell and ethylcellulose mineral coatings, concentrating technical chemistry expertise that supplies infant formula manufacturers worldwide.
United States
FDA GRAS notifications govern mineral additive approvals for food and supplement channels, with review timelines extending qualification periods for novel chelated forms. Chicago and Minneapolis house major cereal and dairy processing hubs where captive blending operations are displacing distributor intermediaries. Abbott Laboratories exemplifies pharmaceutical-grade premix integration.
Germany
EFSA purity thresholds under the updated Food Supplements Directive are accelerating replacement of technical-grade fortificants with pharmaceutical-grade alternatives. BASF SE anchors chelated mineral production from Ludwigshafen, supplying premium infant nutrition across Western Europe. The country's chemical processing clusters dominate EU fortificant output.
India
FSSAI-mandated rice fortification through public distribution systems is institutionalizing premix demand at unprecedented scale. Ferrous fumarate procurement volumes are expanding to serve government programs across Maharashtra, Gujarat, and Karnataka. Mumbai and Ahmedabad concentrate domestic premix blending capacity for staple food channels.
China
NMPA and SAMR standards govern mineral additive registrations for domestic food manufacturing, while Jiangsu and Zhejiang provinces supply global encapsulation capacity. Shanghai and Guangzhou house beverage innovation centers driving liquid fortificant demand in functional drinks. Chinese processors control majority global capacity for lipid-shell mineral coatings.
Brazil
Federal procurement of fortified wheat flour for national school feeding programs creates institutional volume anchors for premix suppliers. ANVISA regulations shape fortification standards for processed foods and supplements. São Paulo and Minas Gerais concentrate grain processing infrastructure where backward integration into sourcing is advancing.
Global Mineral Fortification Market Competitive Landscape
Global majors compete with regional champions across chelation chemistry and encapsulation technology tiers. The supplier base compresses around three strategic archetypes: diversified chemical conglomerates with captive mineral portfolios, specialized premix blenders with pharmaceutical-grade certification, and grain processors with backward integration into fortification infrastructure. Capacity expansion in encapsulated forms and strategic partnerships for bioequivalence validation represent the dominant competitive vectors reshaping supplier relationships.
Within the diversified chemical tier, BASF SE and DSM-Firmenich AG occupy positions spanning chelated mineral production through micronutrient premix formulation. Cargill, Incorporated exemplifies the grain-integrated archetype, leveraging upstream control over cereal sourcing to anchor fortification programs. Among pharmaceutical-grade specialists, Merck KGaA and Balchem Corporation represent the purity-focused segment serving infant formula and clinical nutrition channels with stringent regulatory requirements.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| DSM-Firmenich AG |
| Archer Daniels Midland Company |
| Merck KGaA |
| DuPont de Nemours Inc |
| Pestell Nutrition Inc |
| Abbott Laboratories |
| Balchem Corporation |
| Others |
Supply & Pricing Matrix
Government procurement programs in India and Brazil anchor volume demand for commodity-grade ferrous sulfate and zinc oxide, compressing margins through competitive bidding while pharmaceutical-grade chelated forms command premium positioning in Western infant nutrition channels.
Pricing Analysis
Input-cost pass-through from amino acid feedstock volatility shapes chelated mineral pricing, with ferrous bisglycinate and zinc glycinate premiums fluctuating alongside agricultural commodity cycles. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates infant formula suppliers from staple food programs. Cost compression in commodity salt matrices is intensifying because Indian FSSAI-mandated rice fortification institutionalizes bulk procurement. Institutional buyers in government distribution systems exhibit highest price sensitivity, while infant formula manufacturers prioritize bioavailability validation over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai aggregate premix shipments from manufacturing clusters before final blending operations. Supply concentration rests on China for lipid-shell encapsulation capacity, Germany for chelation chemistry expertise, and India for government-program premix formulation. Raw material dependencies include amino acid feedstocks from agricultural processors, pharmaceutical-grade mineral salts from specialty chemical producers, and coating polymers from petrochemical derivatives. Single-source vulnerability concentrates in Jiangsu and Zhejiang provinces where majority global encapsulation capacity resides. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries in high-volume cereal and dairy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in chelated mineral transitions, as amino acid feedstock cost optimization and pharmaceutical-grade certification premiums reshape profitability across supplier tiers.
For Market Incumbents: Acquire microencapsulation technology platforms to secure captive coating capabilities against Chinese supply concentration risk. BASF SE and DSM-Firmenich AG demonstrate this defensive posture through integrated chelation and encapsulation portfolios. Backward integration into amino acid feedstock sourcing mitigates agricultural commodity price volatility threatening zinc glycinate margins. For New Entrants and Emerging Players: Launch via beverage dispersion format specialization targeting functional drink manufacturers in Shanghai and Guangzhou innovation hubs. White-space penetration concentrates in liquid fortificant applications where powder homogenization fails, particularly in dairy alternatives and functional beverages. Southeast Asian infant formula manufacturers present accessible entry points with shorter qualification timelines than Western pharmaceutical-grade channels. For Investors and Strategic Acquirers: Grain processors with backward integration into sourcing are the most active acquirer in this space, seeking premix blending capabilities to fortify supply chain control. Long-term viability hinges on regulatory alignment with tightening EFSA purity thresholds and FDA GRAS notification requirements. Encapsulation technology patent filings signal inflection points in competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Acquisition | Captive coating capabilities reduce dependency on Jiangsu and Zhejiang province suppliers. |
| Pharmaceutical-Grade Certification Investment | EFSA purity threshold tightening accelerates replacement of technical-grade fortificants. |
| Liquid Fortificant Capacity Expansion | Beverage dispersion demand in functional drinks exceeds powder blending capabilities. |
| Backward Integration into Amino Acid Sourcing | Agricultural commodity cycle exposure in chelated mineral production demands feedstock control. |
| Government Program Partnership | India's FSSAI rice fortification mandate institutionalizes premix demand at unprecedented scale. |
Research Methodology
Multiple input streams — premix manufacturer production data, government procurement records, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant managers at chelation facilities, procurement leads at infant formula manufacturers, distribution channel partners in grain processing hubs, and technical R&D directors at encapsulation specialists informed supply-side dynamics. Secondary validation drew from FSSAI fortification standards documentation, EFSA Food Supplements Directive updates, FDA GRAS notification filings, and customs trade data for mineral salt imports.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor projection assumptions. Segmentation dimensions modeled include fortificant chemistry tier, application channel, form factor, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to procurement volume indicators. Forecast inputs incorporated government program rollout schedules, infant formula birth-rate correlations, and encapsulation technology adoption curves.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on rice fortification mandates, breakthroughs in non-chelated bioavailability enhancement, and geopolitical disruptions to Chinese encapsulation capacity. Forecasts reflect documented assumptions about amino acid feedstock price stability and qualification timeline continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Vitamin Yeast Market