

Encapsulated Vitamin C Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Vitamin C Market Insights
Chinese contract manufacturers is pivoting toward liposome-compatible spray-drying capacity to serve nutraceutical brands seeking heat-stable vitamin C matrices. BASF SE leverages its integrated feedstock position in ascorbic acid precursors to sustain cost advantages across European personal care channels. Croda International anchors its position through specialized lipid-based encapsulation technologies that dominate premium cosmetic applications. Evonik Industries competes via controlled-release polymer systems that extend bioavailability windows for pharmaceutical clients.
Encapsulated vitamin C denotes ascorbic acid or its mineral salts enclosed within protective matrices—typically phospholipid liposomes, cyclodextrin complexes, or ethylcellulose coatings—to shield the active from oxidative degradation and gastric pH exposure while enabling targeted intestinal release. Spray-dried and fluid-bed coating methods predominate at commercial scale, with particle sizes ranging from 50 to 500 microns depending on end-use dissolution requirements. The ascorbic acid segment leads in volume throughput due to its foundational role across supplement and fortification applications, while calcium ascorbate commands margin premiums in buffered formulations for sensitive gastric populations. Powder delivery forms occupy the largest share of industrial offtake, though capsule formats are capturing growth in direct-to-consumer channels where unit-dose convenience drives purchasing decisions.
EFSA novel food assessments and REACH substance evaluations shape ingredient approval timelines and coating material selections for European suppliers. FDA GRAS self-affirmation pathways and cGMP manufacturing rules govern US market entry, while China's NMPA and GB standards dictate import registration for encapsulated actives used in domestic health food filings. Stakeholders must monitor evolving pharmacopeial monographs for dissolution testing methods, as compendial changes would force reformulation investments across multiple geographies simultaneously.
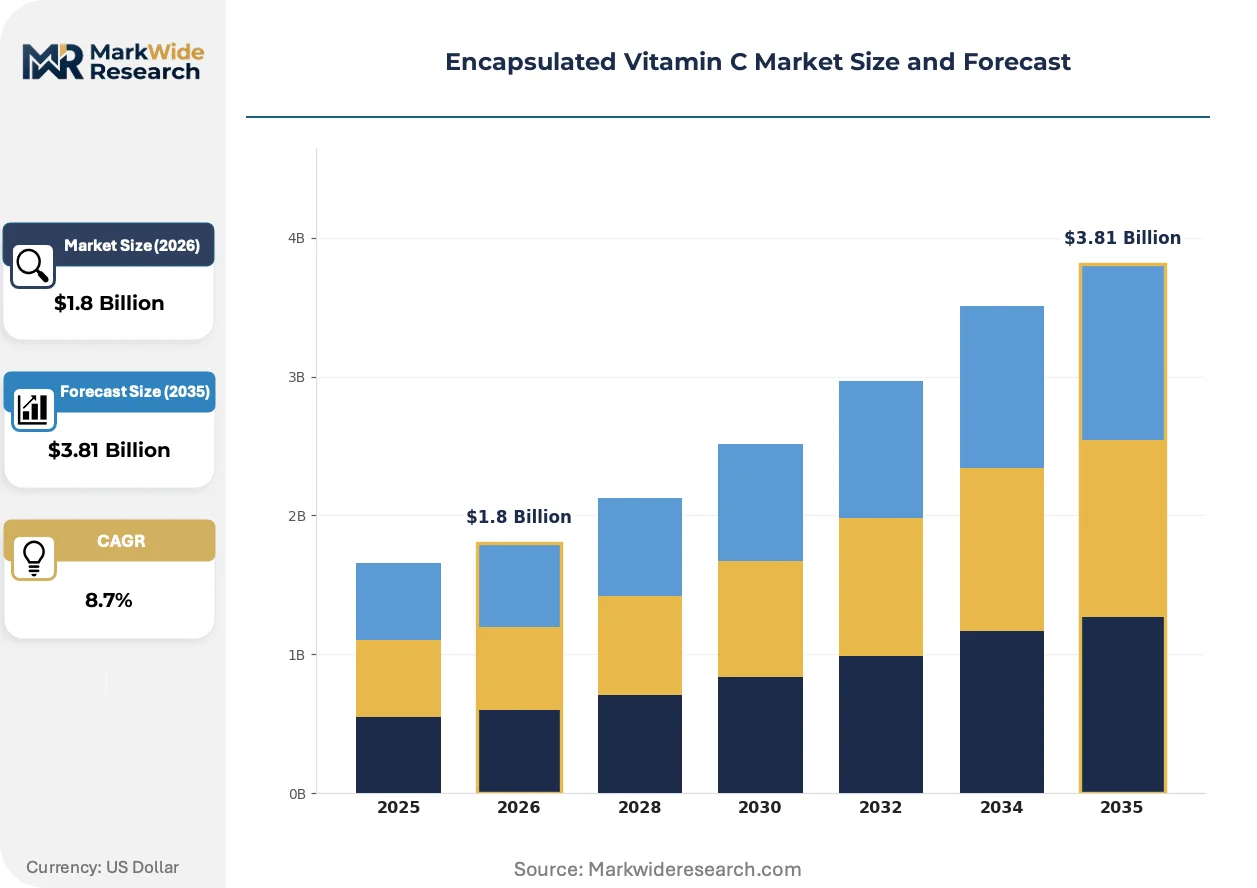
Market Dynamics
REACH compliance timelines for liposomal delivery systems are compressing formulation approval cycles, forcing European suppliers to accelerate coating material substitutions ahead of ECHA substance evaluations.
Growth Catalysts
- EFSA novel food pathways:Streamlined consultations for encapsulated ascorbate variants enable faster market entry for functional food applications in Germany and France.
- Liposome-compatible spray-drying:Chinese contract manufacturers are scaling heat-stable vitamin C matrix capacity to serve nutraceutical brands demanding gastric-resistant delivery forms.
- Dietary supplements reformulation:Brands across Germany, China, and the United States prioritize shelf-stability claims, driving procurement of ethylcellulose-coated and cyclodextrin-complexed variants.
Market Restraints
- Phospholipid feedstock volatility:Liposome production depends on phosphatidylcholine supply concentrated among soybean and sunflower processors, exposing margins to agricultural commodity swings.
- Coating material regulatory friction:ECHA evaluations of ethylcellulose and polymer encapsulants create approval uncertainty for European personal care and pharmaceutical channels.
- Ascorbic acid precursor concentration:Integrated feedstock positions among select chemical conglomerates limit negotiating leverage for mid-tier encapsulation specialists.
Strategic Opportunities
- Buffered calcium ascorbate expansion:Sensitive gastric populations in aging demographics represent underpenetrated demand for mineral-salt encapsulated variants with pH-neutral release profiles.
- Capsule format direct-to-consumer channels:Unit-dose convenience preferences are opening e-commerce and subscription-model distribution for finished encapsulated vitamin C products.
- Controlled-release polymer convergence:Pharmaceutical clients seeking extended bioavailability windows create pull for ethylcellulose and hydroxypropyl methylcellulose coating combinations.
Industry Challenges
- Compendial dissolution testing alignment:Evolving pharmacopeial monographs across USP, EP, and ChP standards force simultaneous reformulation investments for multi-territory suppliers.
- Cross-functional talent scarcity:Liposomal formulation chemistry and fluid-bed coating process engineering expertise concentrates among a narrow specialist workforce.
- Legacy spray-drying asset retrofitting:Converting conventional ascorbic acid drying capacity for liposome-compatible output demands capital-intensive equipment upgrades.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Vitamin C Market Trends and Innovations
Encapsulation technology is pivoting toward precision release mechanisms and regulatory-compliant coating innovations, reshaping competitive positioning across pharmaceutical, nutraceutical, and cosmetic end-uses.
Automated fluid-bed coating systems are automating particle size distribution control for ethylcellulose-encapsulated ascorbic acid, enabling pharmaceutical manufacturers to meet narrow dissolution specifications with reduced batch-to-batch variation. Nutraceutical contract manufacturers in Germany and China are deploying these systems at commercial scale. The technology is automating quality assurance workflows previously dependent on manual sampling protocols.
EFSA novel food consultation procedures are tightening documentation requirements for liposomal vitamin C used in functional foods, extending approval timelines for suppliers lacking prior novel food dossier experience. French and German food manufacturers face reformulation delays as EFSA requests additional stability data for phospholipid matrices. Premium cosmetic brands are pivoting toward cyclodextrin complexation as an alternative encapsulation route with clearer regulatory precedent.
Direct procurement of encapsulated actives by finished goods brands is displacing traditional distributor intermediaries in the United States and Chinese health food sectors. Supplement brands now contract directly with spray-drying specialists for custom particle size and coating specifications. This channel compression is most visible among direct-to-consumer vitamin brands seeking proprietary formulation differentiation.
Encapsulated Vitamin C Market Segmentation
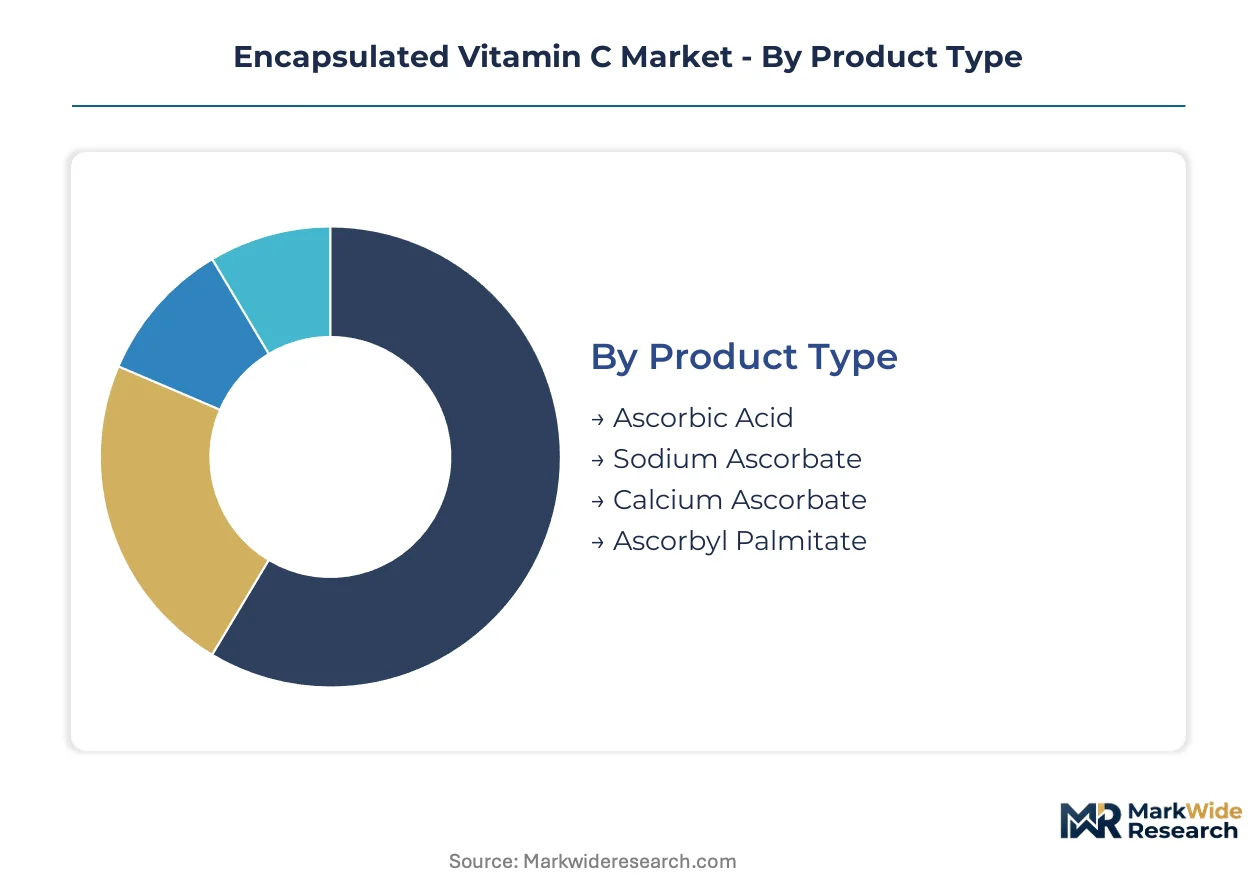
Encapsulated vitamin C formulations diverge sharply across chemical identity, physical presentation, and regulatory destination, with each axis imposing distinct coating requirements and dissolution specifications. Procurement patterns in Germany, China, and the United States reveal how end-use applications dictate encapsulation technology selection and approval pathway complexity.
Product Type:
Chemical specification determines coating compatibility and release profile engineering across pharmaceutical and nutraceutical channels.
- Ascorbic Acid:The foundational free-acid form requires ethylcellulose or cyclodextrin barriers to prevent oxidative browning during shelf storage. German supplement manufacturers drive volume demand for spray-dried variants with 50-100 micron particle specifications.
- Calcium Ascorbate:This buffered mineral salt delivers pH-neutral release for sensitive gastric populations, commanding formulation premiums in aging demographic segments across France and the United States. Liposome encapsulation of this salt variant remains technically challenging due to ionic interference with phospholipid bilayer stability.
- Sodium Ascorbate:Water-soluble salt form preferred for liquid delivery applications requiring rapid dissolution without acidity.
- Ascorbyl Palmitate:Fat-soluble ester derivative enabling oil-phase incorporation in cosmetic emulsions and functional food matrices.
Ascorbic acid leads on scale; calcium ascorbate leads on momentum.
Delivery Form:
Physical presentation governs manufacturing capital requirements and channel economics from bulk ingredient supply to finished goods.
- Powder:Spray-dried and fluid-bed coated powders dominate industrial offtake for fortification and bulk supplement manufacturing. Chinese contract manufacturers are scaling liposome-compatible spray-drying capacity to serve heat-stable matrix demand from nutraceutical brands.
- Capsules:Unit-dose convenience drives direct-to-consumer channel growth, with gelatin and HPMC shell formulations enabling gastric-resistance claims without additional enteric coating.
- Tablets:Compressed forms require granulation pre-processing and face compression-force limitations on coating integrity.
- Liquid:Liposomal suspensions and micellar solutions target pediatric and geriatric populations with swallowing difficulties, though phospholipid feedstock volatility constrains margin stability.
Powder commands volume throughput; capsules are expanding most quickly in premium channels.
Application:
End-use destination determines regulatory jurisdiction and stability testing protocols across divergent approval frameworks.
- Dietary Supplements:Shelf-stability and gastric-resistance claims drive reformulation investment across Germany, China, and the United States. FDA GRAS self-affirmation and China's NMPA health food registration create dual-track compliance burdens for multinational brands.
- Functional Foods:EFSA novel food consultations for encapsulated ascorbate variants are compressing approval timelines for French and German food manufacturers. Phospholipid matrix stability data requirements have extended dossier preparation cycles.
- Cosmetics:Premium positioning favors cyclodextrin complexation with clearer EU regulatory precedent than liposomal alternatives under REACH substance evaluations.
- Animal Nutrition:Feed fortification applications prioritize cost-optimized ethylcellulose coatings over pharmaceutical-grade liposomal delivery.
Dietary supplements anchor demand scale; functional foods face the steepest regulatory climb.
End User:
Customer type concentration shapes technical service requirements and contract manufacturing specialization.
- Pharmaceutical Companies:Controlled-release polymer systems from Evonik extend bioavailability windows, requiring narrow dissolution specifications and pharmacopeial compliance across USP, EP, and ChP standards simultaneously.
- Nutraceutical Firms:Direct procurement of encapsulated actives is displacing distributor intermediaries in the United States and China, with brands contracting spray-drying specialists for proprietary particle size specifications.
- Personal Care Manufacturers:Croda International's lipid-based encapsulation technologies dominate premium cosmetic applications, though ECHA evaluations of coating materials create approval uncertainty.
- Feed Producers:Price-sensitive bulk demand concentrates on ascorbic acid powders with basic ethylcellulose barriers rather than sophisticated liposomal systems.
Nutraceutical firms lead on procurement innovation; pharmaceutical companies impose the tightest specification tolerances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China operate on divergent regulatory timelines for encapsulated ascorbate approvals, while the United States maintains distinct FDA self-affirmation pathways that compress market entry for reformulated supplement brands.
United States
Dietary supplement brands in California and New York Metro are driving direct procurement of spray-dried encapsulated actives for shelf-stability claims. FDA GRAS self-affirmation pathways enable faster formulation launches compared to European novel food procedures. Greater Boston hosts contract manufacturing clusters specializing in fluid-bed coating systems for pharmaceutical-grade vitamin C matrices.
Germany
Functional food manufacturers in Bavaria and North Rhine-Westphalia are expanding procurement of liposomal vitamin C following EFSA consultation streamlining for encapsulated ascorbate variants. REACH compliance timelines for phospholipid delivery systems are compressing coating material substitution cycles. BASF SE's Ludwigshafen operations anchor integrated feedstock positions in ascorbic acid precursors.
China
Nutraceutical contract manufacturers in the Yangtze River Delta are scaling liposome-compatible spray-drying capacity to serve heat-stable matrix demand. NMPA health food registration rules and GB standards dictate import procedures for encapsulated actives used in domestic filings. Zhejiang and Jiangsu provinces concentrate spray-drying specialists serving direct-to-consumer vitamin brands.
France
Premium cosmetic formulators in Île-de-France are pivoting toward cyclodextrin complexation as EFSA requests additional phospholipid stability data for liposomal variants. ANSM and ECHA substance evaluations create regulatory friction for ethylcellulose coating materials in personal care channels. Lyon-based encapsulation specialists are expanding cyclodextrin production capacity.
Japan
Aging demographic demand for buffered calcium ascorbate formulations is expanding in the Kanto region around Tokyo. PMDA and METI oversight of functional food claims creates distinct approval pathways for gastric-resistant delivery systems. Osaka-Kansai manufacturing clusters specialize in ethylcellulose coating technologies for pharmaceutical clients.
Encapsulated Vitamin C Market Competitive Landscape
German chemical conglomerates anchor one tier through integrated ascorbic acid precursor positions; Chinese and European encapsulation specialists hold differentiated positions in coating technology and liposomal formulation. The vendor structure exhibits moderate concentration with three to five integrated players commanding upstream feedstock control while mid-tier specialists compete on coating customization. Strategic archetypes include backward-integrated precursor producers, lipid-based encapsulation technology licensors, and contract spray-drying operators serving direct procurement trends. Capacity expansion in liposome-compatible spray-drying and polymer coating system licensing represent dominant competitive vectors.
Among Germany-based diversified chemical producers, BASF SE and Evonik Industries exemplify integrated feedstock and controlled-release polymer archetypes respectively. Croda International occupies a position within the lipid-based encapsulation specialist tier, representing premium cosmetic application focus. These three entities anchor distinct competitive positions without overlapping technology claims.
| Leading Market Players |
|---|
| BASF SE |
| Croda International |
| Evonik Industries |
| Symrise |
| Dow |
| Ashland |
| Clariant |
| Seppic |
| Lonza |
| Others |
Pricing and Supply Chain Analysis
Specialist liposomal formulation chemists concentrated in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta create labor-cost differentials that widen pricing-tier spreads between pharmaceutical-grade liposomal encapsulation and commodity spray-dried powders. REACH compliance investments and phospholipid feedstock volatility compound these cost structures, forcing mid-tier suppliers into narrower margin bands while integrated precursor producers defend pricing power.
Pricing Analysis
Capacity additions in China's Zhejiang and Jiangsu provinces are reshaping price floors for standard-grade spray-dried ascorbic acid powders. Three-tier pricing structure across premium, standard, and economy levels separates liposomal pharmaceutical grades from fluid-bed coated nutraceutical intermediates and basic ethylcellulose feed fortification grades. Price differentiation rests on EFSA novel food dossier completion status and REACH coating material approvals. Cost compression in standard powder tiers is intensifying because Chinese contract manufacturers are scaling liposome-compatible capacity. Feed producers exhibit highest price sensitivity; pharmaceutical clients demonstrate lowest sensitivity due to bioavailability specification rigidity.
Supply Chain Analysis
Single-source vulnerability sits with phosphatidylcholine feedstock concentrated among Argentine and Ukrainian sunflower processors and Chinese soybean lecithin refiners. Manufacturing capacity clusters in China, Germany, and the United States for encapsulation equipment and coating technology licensing. Raw material dependencies include ascorbic acid precursors from integrated chemical conglomerates, phospholipid matrices from agricultural processors, and ethylcellulose from cellulose ether specialists. Tariff exposure on phospholipid imports into the European Union creates margin volatility for liposomal formulators. Distribution runs through direct procurement channels displacing traditional distributor intermediaries in nutraceutical end-uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulated vitamin C procurement functions as a geographic-arbitrage play between REACH-regulated European coating material substitutions and China's streamlined NMPA health food registration pathways for gastric-resistant delivery forms. Regulatory compliance cost differentials of 15-25 percentage points between these jurisdictions create margin expansion opportunities for multi-territory suppliers.
For Market Incumbents: Acquire liposome-compatible spray-drying assets in the Yangtze River Delta to capture Chinese contract manufacturing demand for heat-stable vitamin C matrices. BASF SE's integrated precursor position and Evonik's controlled-release polymer systems face displacement risk from Chinese equipment licensors offering comparable fluid-bed coating automation at lower capital intensity. Defend margin position through backward integration into phospholipid feedstock tolling agreements with Argentine sunflower processors, securing coating material supply ahead of ECHA substance evaluation timelines. For New Entrants and Emerging Players: Contract spray-drying specialists serving direct-to-consumer vitamin brands represent the most penetrable channel partner type for proprietary particle size specifications. White-space targets include buffered calcium ascorbate formulations for aging demographics in Japan's Kanto region and cyclodextrin complexation for French premium cosmetic brands pivoting from liposomal alternatives. Unit-dose capsule formats for e-commerce subscription models offer the clearest go-to-market angle, bypassing distributor intermediaries that incumbent suppliers still serve. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier encapsulation specialists lacking integrated precursor positions but holding fluid-bed coating process engineering expertise. Long-term viability through the projection horizon favors suppliers with dual-track regulatory capabilities across FDA GRAS self-affirmation and EFSA novel food pathways. Acquisition target archetype: German or Chinese contract manufacturers with liposome-compatible spray-drying capacity and existing novel food dossier experience. The signal to watch is ECHA substance evaluation acceleration for ethylcellulose coating materials, which would force asset write-downs among polymer-dependent suppliers and create distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phospholipid Feedstock | Secures coating material supply ahead of ECHA evaluations affecting BASF SE and Croda International. |
| Liposome-Compatible Spray-Drying Capacity Expansion | Captures Chinese nutraceutical demand for heat-stable vitamin C matrices with gastric-resistance claims. |
| Dual-Track Regulatory Dossier Investment | Enables simultaneous FDA GRAS and EFSA novel food market entry for functional food manufacturers. |
| Cyclodextrin Complexation Technology Licensing | Addresses French cosmetic formulators pivoting from liposomal variants under REACH uncertainty. |
| Direct-to-Consumer Capsule Format Launch | Bypasses distributor intermediaries through e-commerce subscription models for unit-dose convenience. |
Research Methodology
Coverage spans Germany, China, the United States, France, and Japan, with primary inputs from each territory's regulatory and manufacturing clusters. The analysis combines primary interviews with liposomal formulation chemists, spray-drying plant managers, regulatory affairs leads at encapsulated ingredient suppliers, and procurement directors at finished supplement brands with secondary validation. Secondary sources include EFSA novel food consultation records, FDA GRAS self-affirmation filings, NMPA health food registration databases, customs trade data for phospholipid imports, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling were triangulated to produce segment-level outputs.
Rate-of-change decomposition across the analysis window isolates volume drivers by chemical specification, delivery form, and end-use application. The forecast framework models encapsulated vitamin C demand through segmentation dimensions including ascorbic acid versus mineral salt variants, powder versus capsule versus liquid presentations, and dietary supplement versus functional food versus cosmetic regulatory destinations. CAGRs were derived from regression analysis of historical procurement patterns and projected reformulation cycles. Industry-specific forecast inputs include EFSA novel food approval velocity, REACH substance evaluation timelines, and Chinese contract manufacturing capacity utilization rates.
Revisions become necessary when ECHA accelerates ethylcellulose coating material evaluations, when NMPA modifies health food registration rules for encapsulated actives, or when phospholipid feedstock volatility disrupts liposomal production economics. Forecasts reflect assumptions about regulatory pathway efficiency and coating technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.