
 Savory Ingredients Market | 2026-2036
Savory Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Ingredients Market Intelligence
Yeast extract is hardening its position as the preferred replacement for synthetic monosodium glutamate in premium formulations. Symrise leverages captive fermentation capacity to secure supply continuity across European savory portfolios. Kerry Group Plc anchors its competitive stance through backward integration into dairy and meat flavor precursors. Ajinomoto Co., Inc. dominates traditional umami chemistry while navigating the clean-label transition.
Savory ingredients encompass flavor-active compounds, reaction flavors, and extractives that deliver umami, roasted, and meat-like sensory profiles through controlled Maillard reactions, enzymatic hydrolysis, or fermentation at specified pH and temperature parameters. These inputs serve industrial food manufacturers seeking to standardize taste intensity, reduce sodium, or mask off-notes in plant-based matrices. Yeast extract and hydrolyzed vegetable protein together occupy the core of the product-type landscape, with natural extracts representing the fastest-expanding margin pool as label-conscious buyers shift procurement criteria. Application demand concentrates in snacks and ready-to-eat meals, where shelf-stable flavor intensity commands premium positioning.
FDA GRAS determinations and EFSA sodium-reduction benchmarks jointly shape formulation roadmaps for suppliers selling into the United States and European Union. The EU Green Deal's farm-to-fork targets are forcing savory ingredient houses to document upstream agricultural emissions and pivot toward fermentation-derived alternatives. Stakeholders must monitor how clean-label certification schemes evolve to determine which extraction technologies retain market access.
Market Dynamics
The EU's F-Gas Regulation is forcing extraction technology upgrades across European savory ingredient production, compressing margins for solvent-dependent manufacturers while advantaging fermentation-based suppliers with captive bioprocessing capacity.
Growth Catalysts
- Clean-label umami chemistry:Foodservice operators in Germany are replacing synthetic monosodium glutamate with yeast extract in premium formulations, creating pull-through demand for fermentation-derived alternatives.
- EFSA sodium-reduction benchmarks:These targets are mandating reformulation across ready-to-eat meal portfolios, expanding addressable demand for savory ingredients that deliver intensity without salt loading.
- Plant-based matrix masking:Off-note suppression in meat analogues is driving technical specification of Maillard-reaction flavors by industrial food manufacturers seeking taste parity.
Market Restraints
- Agricultural input volatility:Wheat and soy protein costs fluctuate with commodity cycles, compressing margins for hydrolyzed vegetable protein producers without long-term supply contracts.
- Flavor house concentration:Frankfurt and Hamburg clusters control critical fermentation capacity, creating geographic supply risk for buyers dependent on just-in-time delivery.
- Extraction technology lock-in:Legacy solvent-based facilities face stranded asset risk under tightening EU Green Deal farm-to-fork emission documentation requirements.
Strategic Opportunities
- Underpenetrated snack applications in France:Clean-label savory coatings for baked chips remain technically underserved relative to German and UK market development.
- Fermentation-converged biomanufacturing:Precision-controlled enzymatic hydrolysis paired with synthetic biology is opening novel peptide profiles beyond traditional yeast extract functionality.
- Direct procurement from flavor houses:Large food manufacturers are bypassing traditional distribution tiers to secure volume commitments and technical collaboration on custom reaction flavors.
Industry Challenges
- Maillard reaction specialist scarcity:Food chemists capable of optimizing pH-temperature parameters for consistent batch-to-batch sensory output command premium compensation and limited availability.
- CSRD-aligned emission verification:Upstream agricultural documentation for Scope 3 reporting requires new data infrastructure and supplier audit protocols that extend certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Ingredients Market |
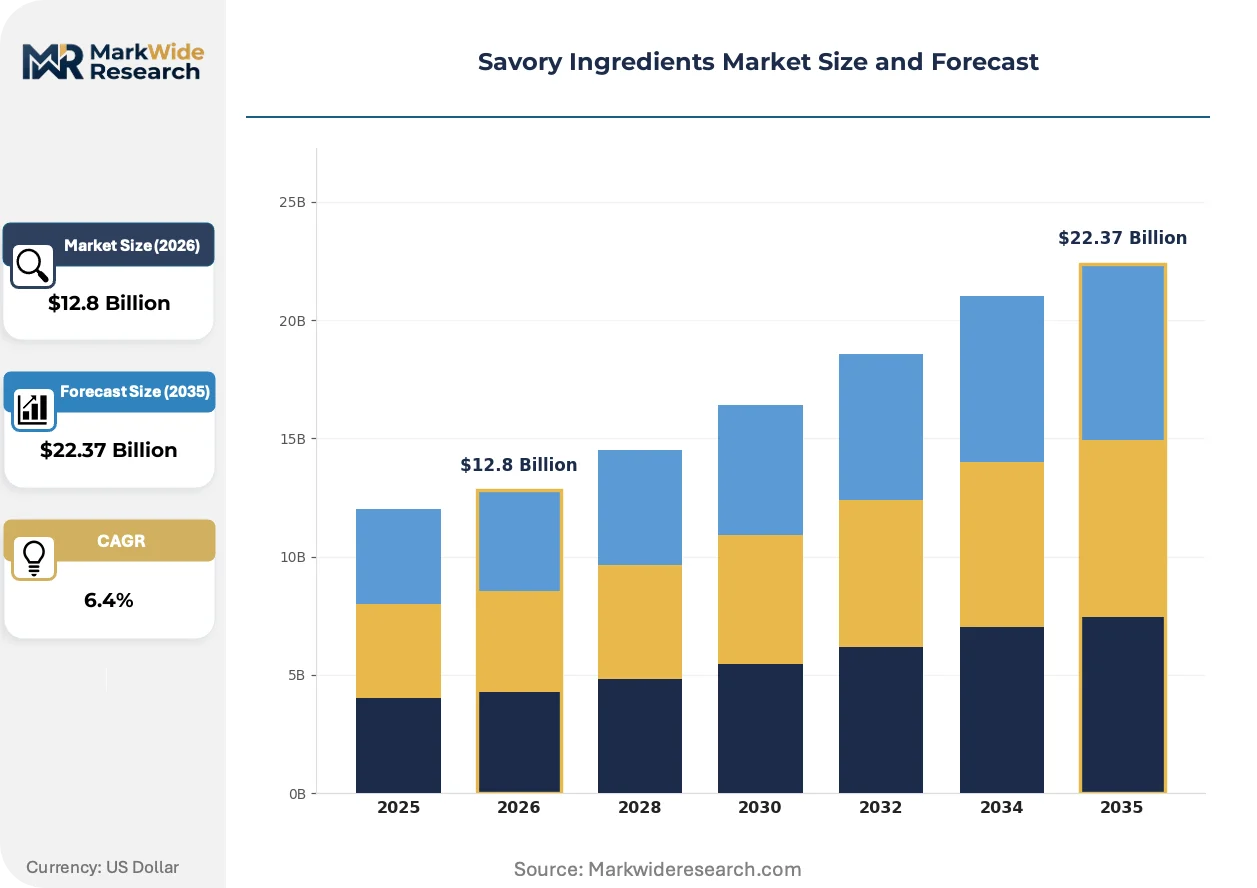
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Extract, Hydrolyzed Vegetable Protein, Autolyzed Yeast, Monosodium Glutamate, Natural Extracts Application: Soups, Sauces, Snacks, Ready-to-Eat Meals, Meat Alternatives End User: Food & Beverage Manufacturers, Foodservice Providers, Ingredient Suppliers, Private Label Producers Packaging Type: Powder Bags, Liquid Containers, Bulk Sacks, Sachets, Bottles |
| Companies Covered | Symrise, Sensient Technologies Corporation, Kerry Group Plc, Koninklijke DSM N.V., ADM, Ajinomoto Co., Inc., Tate & Lyle PLC, Ingredion, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Ingredients Market Strategic Shifts & Innovations
Fermentation-derived savory platforms are displacing extraction-dependent supply chains, while regulatory emission frameworks and buyer procurement centralization are compressing traditional channel structures across European and North American markets.
Precision fermentation for savory peptide production is consolidating technical differentiation among suppliers with in-house strain development capabilities. Industrial food manufacturers are specifying these inputs for plant-based meat applications where batch consistency outweighs cost premiums. The technology is consolidating competitive position around bioprocess control rather than agricultural sourcing scale.
The EU Green Deal's farm-to-fork emission targets are mandating granular upstream documentation from savory ingredient houses. Suppliers must now verify agricultural carbon intensity for wheat and soy precursors to retain access to EU procurement channels. Natural extract categories face the steepest compliance burden due to dispersed raw material sourcing across multiple member states.
Buyer concentration among multinational food manufacturers is compressing negotiation cycles and unbundling technical service from base ingredient supply. Large ready-to-eat meal producers are demanding dedicated R&D collaboration on sodium-reduction formulations in exchange for volume commitments. Germany exhibits the most pronounced procurement centralization, with flavor houses competing on application-specific development speed rather than catalog breadth.
Savory Ingredients Market Segmentation
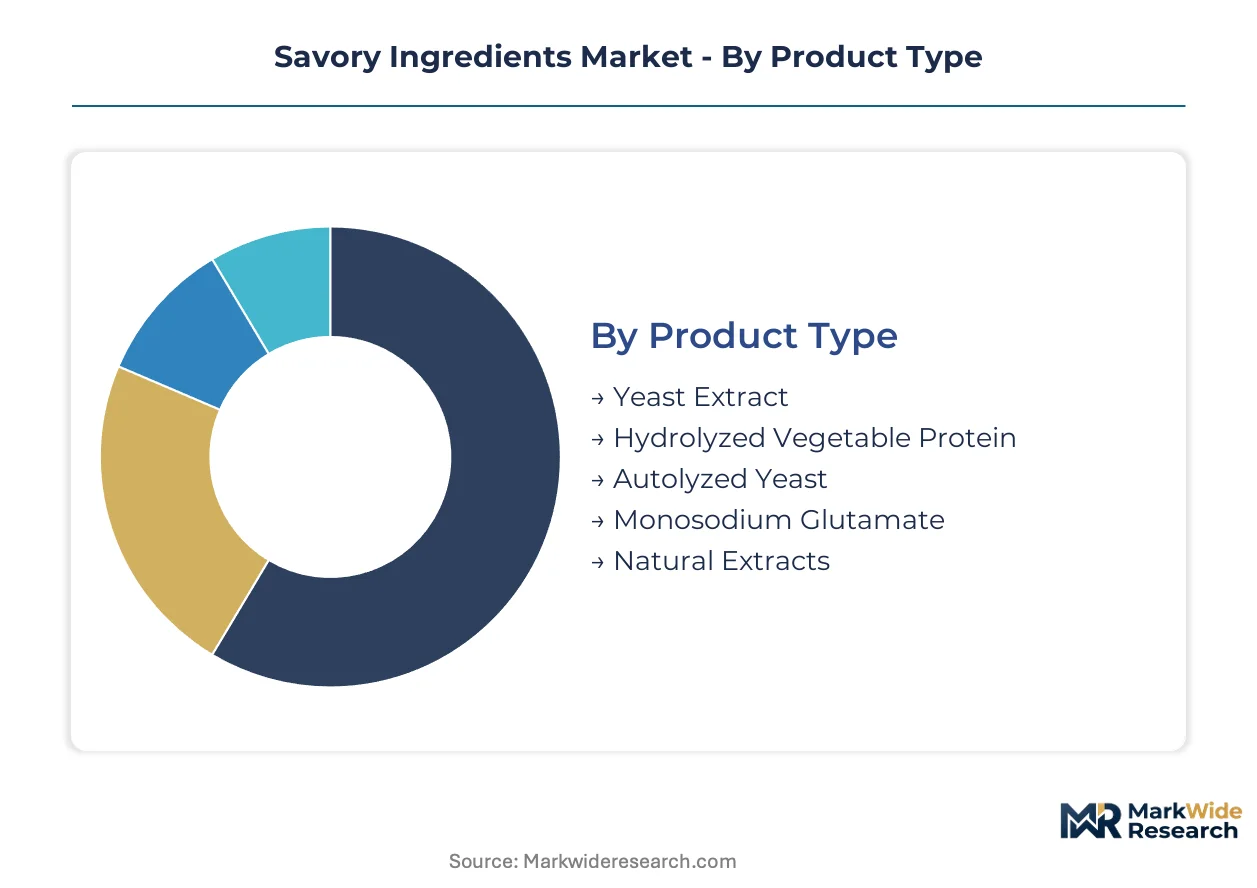
Savory ingredient procurement decisions hinge on label positioning, application performance, and supply chain traceability. Technical specification varies sharply across fermentation-derived versus extractive platforms, driving divergent margin structures and regulatory exposure.
Product Type:
Fermentation technology and extraction chemistry define competitive differentiation across the ingredient landscape.
- Yeast Extract:Autolyzed Saccharomyces cerevisiae cells deliver concentrated glutamate and nucleotide profiles through controlled enzymatic breakdown. German foodservice operators specify this input for clean-label umami enhancement in premium ready-to-eat portfolios, though F-Gas Regulation compliance costs pressure solvent-dependent competitors.
- Hydrolyzed Vegetable Protein:Acid or enzymatic hydrolysis of wheat, soy, or corn gluten yields peptide-rich savory bases with pronounced roasted notes. Demand concentrates in industrial snack seasoning applications where cost-efficient intensity masks sodium reduction, yet agricultural input volatility compresses margins for producers lacking long-term supply contracts.
- Autolyzed Yeast:Self-digestion of yeast cells under temperature-controlled conditions produces milder flavor profiles than acid hydrolysis alternatives. This segment serves manufacturers seeking subtle umami contribution without overt yeast character declaration.
- Monosodium Glutamate:Crystalline sodium salt of glutamic acid remains the reference standard for pure umami intensity despite clean-label headwinds. Asian market formulations and economy-tier processed foods sustain volume, while European premium segments accelerate substitution.
- Natural Extracts:Botanical and fungal-derived savory compounds from mushrooms, tomatoes, and seaweed supply label-friendly positioning. EU Green Deal farm-to-fork documentation requirements impose the steepest compliance burden due to dispersed agricultural sourcing across multiple member states.
Yeast extract leads on scale; natural extracts lead on momentum.
Application:
End-use performance requirements dictate specification intensity and technical service engagement levels.
- Soups:Thermal stability and salt-compatibility dominate formulation priorities for dehydrated and canned formats. Sodium-reduction mandates from EFSA expand specification of yeast-derived intensity enhancers in European retail portfolios.
- Sauces:Viscosity compatibility and shelf-stable flavor persistence require tailored hydrolyzed protein fractions. Industrial manufacturers demand batch consistency for pourable condiments and cooking bases.
- Snacks:Surface adhesion and fat-resistance properties distinguish savory coatings for extruded and baked formats. Clean-label baked chip applications in France remain technically underserved relative to German market development.
- Ready-to-Eat Meals:Retort processing tolerance and freeze-thaw stability command premium positioning for reaction flavors. Large manufacturers negotiate dedicated R&D collaboration in exchange for volume commitments, particularly in centralized German procurement.
- Meat Alternatives:Off-note suppression in plant-based matrices drives Maillard-reaction flavor specification for taste parity. Precision fermentation peptides are gaining share where batch consistency outweighs cost premiums.
Ready-to-eat meals command the deepest technical engagement; meat alternatives are climbing the fastest.
End User:
Customer scale and formulation capability determine channel structure and pricing architecture.
- Food & Beverage Manufacturers:Multinational processors with captive R&D specify custom reaction flavors and secure direct procurement relationships. These buyers unbundle technical service from base ingredient supply to compress negotiation cycles.
- Foodservice Providers:Chain operators and contract caterers prioritize standardized taste intensity across distributed kitchen footprints. Clean-label umami transition is most pronounced in German premium foodservice.
- Ingredient Suppliers:Blenders and distributors aggregate volume across smaller accounts, absorbing inventory risk and documentation burden for CSRD-aligned emission verification.
- Private Label Producers:Retailer-owned brand manufacturers balance cost position with label claims, often specifying mid-tier hydrolyzed proteins over premium fermentation alternatives.
Food and beverage manufacturers concentrate procurement leverage; foodservice providers are expanding specification fastest.
Packaging Type:
Logistics configuration and handling requirements segment the fulfillment layer.
- Powder Bags:Multi-wall paper or polyethylene constructions dominate yeast extract and hydrolyzed protein distribution. Shelf-stable formats suit ambient supply chains and industrial-scale dosing equipment.
- Liquid Containers:Drum and intermediate bulk container formats serve high-volume sauce manufacturers seeking pumpable handling and rapid dispersion.
- Bulk Sacks:Flexible intermediate bulk containers consolidate agricultural commodity movements for hydrolyzed vegetable protein precursors.
- Sachets:Single-serve portions address foodservice portion control and consumer convenience positioning in retail.
- Bottles:Retail-ready liquid concentrates and table sauces utilize standard packaging lines with established filling infrastructure.
Powder bags anchor industrial volume; liquid containers are gaining share in automated processing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Hamburg anchor European savory ingredient production, with fermentation capacity clustering around these logistics hubs serving industrial food manufacturers across the continent.
Germany
Foodservice operators in Frankfurt and Hamburg are replacing synthetic monosodium glutamate with yeast extract in premium formulations. The EU F-Gas Regulation is forcing extraction technology upgrades that compress margins for solvent-dependent manufacturers. Flavor houses around these port cities compete on application-specific development speed for centralized procurement contracts.
United States
FDA GRAS determinations shape formulation roadmaps for suppliers selling into industrial snack and ready-to-eat meal channels. Sodium-reduction benchmarks from federal health agencies expand specification of umami enhancers that deliver intensity without salt loading. Midwest agricultural processing corridors supply wheat and soy precursors for hydrolyzed vegetable protein production.
France
Clean-label savory coatings for baked chips remain technically underserved relative to German market development, creating specification gaps for fermentation-derived alternatives. EFSA emission documentation requirements under the EU Green Deal impose compliance burdens on natural extract categories with dispersed agricultural sourcing. Paris-based food manufacturers are consolidating procurement leverage for custom reaction flavors.
China
Dual carbon goals from MEE are pressuring extraction facilities to document upstream agricultural emissions and pivot toward fermentation-derived platforms. Yangtze River Delta industrial zones concentrate precision fermentation capacity for peptide production serving plant-based meat applications. Domestic flavor houses are securing captive bioprocessing capacity to reduce import dependence.
Japan
METI standards for food additive safety sustain demand for traditional umami chemistry in economy-tier processed foods while premium segments accelerate clean-label substitution. Kanto region flavor scientists command premium compensation for Maillard reaction optimization expertise. Tokyo-headquartered manufacturers balance domestic fermentation heritage with export positioning for European clean-label markets.
Savory Ingredients Market Key Industry Players
Global majors compete with regional champions across fermentation capacity and extraction technology portfolios. The vendor base separates into consolidated fermentation specialists with captive bioprocessing assets and fragmented extractive suppliers facing stranded asset risk. Three archetypes dominate: integrated flavor houses with backward control over dairy and meat precursors, precision fermentation platforms with in-house strain development, and commodity hydrolyzed protein processors exposed to agricultural input volatility. M&A activity concentrates on securing fermentation capacity, while strategic partnerships target direct procurement relationships with multinational food manufacturers.
Within the integrated flavor house tier, Symrise and Kerry Group Plc exemplify archetypes combining captive fermentation assets with precursor integration. Ajinomoto Co., Inc. occupies a position bridging traditional umami chemistry and clean-label transition dynamics. These three anchors represent divergent strategic postures on the fermentation-versus-extraction spectrum.
| Leading Market Players |
|---|
| Symrise |
| Sensient Technologies Corporation |
| Kerry Group Plc |
| Koninklijke DSM N.V. |
| ADM |
| Ajinomoto Co., Inc. |
| Tate & Lyle PLC |
| Ingredion |
| Givaudan |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's farm-to-fork emission documentation gates qualified supply for savory ingredient houses, with verified upstream agricultural carbon intensity now a prerequisite for premium-tier pricing access in European procurement channels. Buyers in Germany and France withhold volume commitments from suppliers lacking CSRD-aligned Scope 3 reporting infrastructure, bifurcating the market between compliant fermentation specialists and stranded extraction-dependent competitors.
Pricing Analysis
Input-cost pass-through from wheat and soy commodity cycles compresses margins for hydrolyzed vegetable protein producers without long-term supply contracts, while fermentation-derived alternatives command stability premiums. Three-tier pricing structure across premium, standard, and economy levels separates natural extract formulations with full farm-to-fork traceability from mid-tier yeast extracts and commodity MSG. Price differentiation hinges on clean-label certification grade and volume scale, with private label producers exhibiting highest price sensitivity and multinational food manufacturers least sensitive where technical collaboration is bundled. Pricing pressure stems from F-Gas Regulation compliance costs pressuring solvent-dependent extraction facilities.
Supply Chain Analysis
CSRD-aligned emission verification gates supplier qualification, with Frankfurt and Hamburg fermentation clusters anchoring European supply alongside Yangtze River Delta precision fermentation capacity in China. Raw material dependencies center on wheat gluten, soy protein isolates, and yeast biomass feedstocks. Single-source vulnerability concentrates in German flavor house clusters controlling captive bioprocessing assets. Distribution runs through direct procurement relationships between large food manufacturers and integrated flavor houses, bypassing traditional distribution tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EFSA sodium-reduction benchmarks and EU F-Gas Regulation compliance costs continuously reshaping competitive economics and procurement criteria across European savory ingredient channels.
For Market Incumbents: Anchor competitive position through backward integration into dairy and meat flavor precursors, securing captive supply continuity as agricultural input volatility intensifies. Expand fermentation capacity in Germany to defend against precision fermentation entrants from Asia. Invest in CSRD-aligned data infrastructure before emission verification becomes a hard procurement gate. For New Entrants and Emerging Players: French baked chip manufacturers seeking clean-label savory coatings represent an underserved buyer archetype with technical specification gaps relative to German market development. Precision fermentation platforms should target meat alternative applications where batch consistency commands premium positioning over cost. Partner with industrial snack producers on sodium-reduction formulation collaboration to bypass entrenched flavor house relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among solvent-dependent extraction specialists facing stranded asset risk under tightening EU Green Deal requirements. Long-term viability favors fermentation-converged biomanufacturing with in-house strain development capabilities. Watch for inflection signals in German procurement centralization rates, where direct manufacturer-flavor house relationships accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive bioprocessing assets secure supply continuity under F-Gas Regulation pressure. |
| Backward Integration into Precursors | In-house production of dairy and meat flavor bases reduces agricultural input exposure. |
| CSRD Emission Verification Infrastructure | Scope 3 documentation capability unlocks European procurement access for natural extracts. |
| Precision Fermentation Platform Development | Synthetic biology-enabled peptide profiles differentiate beyond traditional yeast extract functionality. |
| Direct Procurement Relationship Formation | Volume commitments with multinational food manufacturers compress traditional channel margins. |
Research Approach
Bottom-up application modeling reconciled against top-down fermentation capacity tracking forms the analytical core, combining primary interviews with flavor house technical directors, food manufacturer procurement leads, foodservice chain operators, and regulatory affairs specialists with secondary validation from EFSA guidance documents, EU F-Gas Regulation filings, SEC disclosures from listed ingredient suppliers, and customs trade data on wheat and soy protein movements. Triangulation between demand-side specification trends and supply-side capacity announcements ensures consistency across volume and value outputs.
Historical trendline analysis of yeast extract and hydrolyzed vegetable protein price movements, cross-referenced with agricultural commodity indices, informs growth trajectory calibration across the projection horizon. Segmentation dimensions modeled include product type, application performance requirements, end-user scale and formulation capability, and regional regulatory framework clusters. CAGRs derive from elasticity-adjusted demand curves incorporating EFSA sodium-reduction mandate penetration rates and clean-label substitution dynamics in premium foodservice channels.
Inputs from flavor house capacity announcements and food manufacturer procurement disclosures were available through the study window; gaps in private fermentation facility utilization rates introduce uncertainty bands around precision fermentation growth assumptions. Forecasts reflect documented assumptions on regulatory enforcement timing and buyer procurement centralization velocity. A model refresh is warranted upon material change in EU Green Deal farm-to-fork emission verification deadlines or F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asparagus Extract Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Caramel Malt Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Liquid Egg Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Yeast Derivatives Market
Ingredients
Oat Grass Powder Market
Ingredients
Global Natural Gum Market
Ingredients
Home Baking Ingredients Market
Ingredients
High Oleic Oil Market
Ingredients
Confectionery Ingredients Market
Ingredients
US Ingredients Market
Ingredients
Europe Soy Protein Market
Ingredients
Heart Health Ingredients Market