
 Food Grade Vitamin B Market | 2026-2036
Food Grade Vitamin B Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Vitamin B Market Insights
Fermentation-based bioprocessing is tilting production economics away from petrochemical synthesis toward microbial cell factories. DSM Nutritional Products leverages decades of strain optimization to sustain premium positioning in B2 and B12 fractions. Zhejiang Medicine Co., Ltd. anchors Asia-Pacific supply through integrated fermentation and downstream refining capacity. Lonza Group AG differentiates via pharmaceutical-grade cGMP compliance that extends into food-grade vitamin B contract manufacturing.
Food grade vitamin B denotes a family of water-soluble micronutrients—thiamine (B1), riboflavin (B2), niacin (B3), and cobalamin (B12)—manufactured to purity specifications exceeding 98% and free from heavy metal contaminants, intended for incorporation into human consumables rather than feed or industrial applications. The B12 and B3 categories lead value contribution due to limited natural bioavailability and high fortification intensity in plant-based alternatives. Nutritional Supplements command margin pools above Food Fortification because finished brands absorb ingredient premiums through direct-to-consumer pricing. Beverage applications are gaining share as functional drink producers seek stable, taste-masked B-vitamin premixes for shelf-stable formats.
The FDA enforces 21 CFR 172 and 184 standards for vitamin B additives in U.S. foods, while the EFSA under EU regulation 1925/2006 governs maximum fortification levels across member states. China's NMPA and GB standards for food nutritional fortifiers impose batch-level testing that shapes export eligibility for domestic manufacturers. Stakeholders must monitor evolving national maximum-level harmonization between Codex Alimentarius and regional regulators to preempt reformulation costs.
Market Dynamics
Fermentation-based bioprocessing is displacing petrochemical synthesis as the dominant production pathway, tightening purity specifications while expanding capacity for B12 and B-complex outputs. This structural shift concentrates margin capture among strain-optimization specialists and integrated fermentation operators.
Growth Catalysts
- EU Novel Food Regulations:Tightened purity thresholds for synthetic vitamin inputs are accelerating qualification of fermentation-derived alternatives in fortified foods and supplements.
- Plant-based dairy alternatives:Vegan cheese and milk producers require cobalamin fortification at intensities exceeding traditional dairy, pulling B12 volumes into beverage and dairy-analogue manufacturing.
- China's domestic fermentation scale-up:Integrated producers in Zhejiang and Shandong provinces have expanded downstream refining capacity, reducing import dependency for food manufacturers across East Asia.
Market Restraints
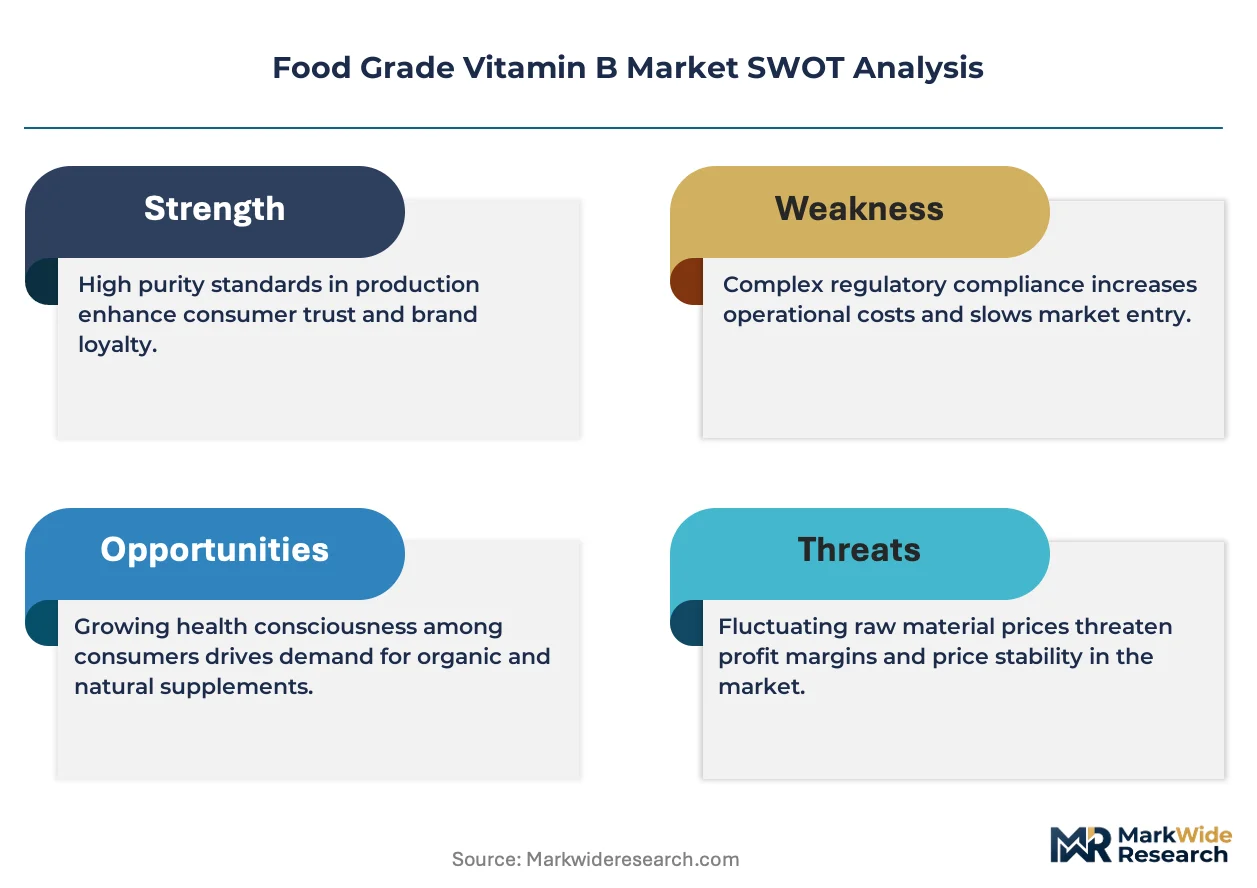
- Corn syrup and glucose feedstock volatility:Fermentation economics depend on agricultural carbohydrate inputs subject to climate-driven price swings and biofuel policy competition.
- Single-source strain dependency:Proprietary microbial cell lines for riboflavin and cobalamin remain concentrated among three legacy optimization houses, creating supply vulnerability.
- Cross-contamination protocols:Pharmaceutical-grade cGMP facilities face extended changeover timelines when toggling between food-grade and feed-grade B-vitamin runs.
Strategic Opportunities
- India's fortified staple mandate expansion:FSSAI's rice and wheat fortification directives create volume pull for thiamine and niacin premixes in institutional procurement channels.
- Stable-isotope B12 for diagnostics:Convergence of food-grade purity standards with radiolabeling requirements is opening adjacent revenue in clinical nutrition and research supply.
- Direct-to-brand premix platforms:Functional beverage startups are bypassing traditional distributors through vertically integrated formulation services that combine taste-masking with B-vitamin stability engineering.
Industry Challenges
- Strain engineering talent scarcity:Industrial microbiology programs produce insufficient metabolic engineering specialists to staff expanded fermentation capacity.
- Heavy metal batch-testing bottlenecks:GB standards and EU 1925/2006 maximum-level enforcement require third-party verification queues that extend delivery timelines by four to six weeks.
- Legacy petrochemical asset stranding:Synthetic B3 producers face compressed returns as fermentation economics improve, complicating reinvestment decisions for mid-cycle facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Vitamin B Market |
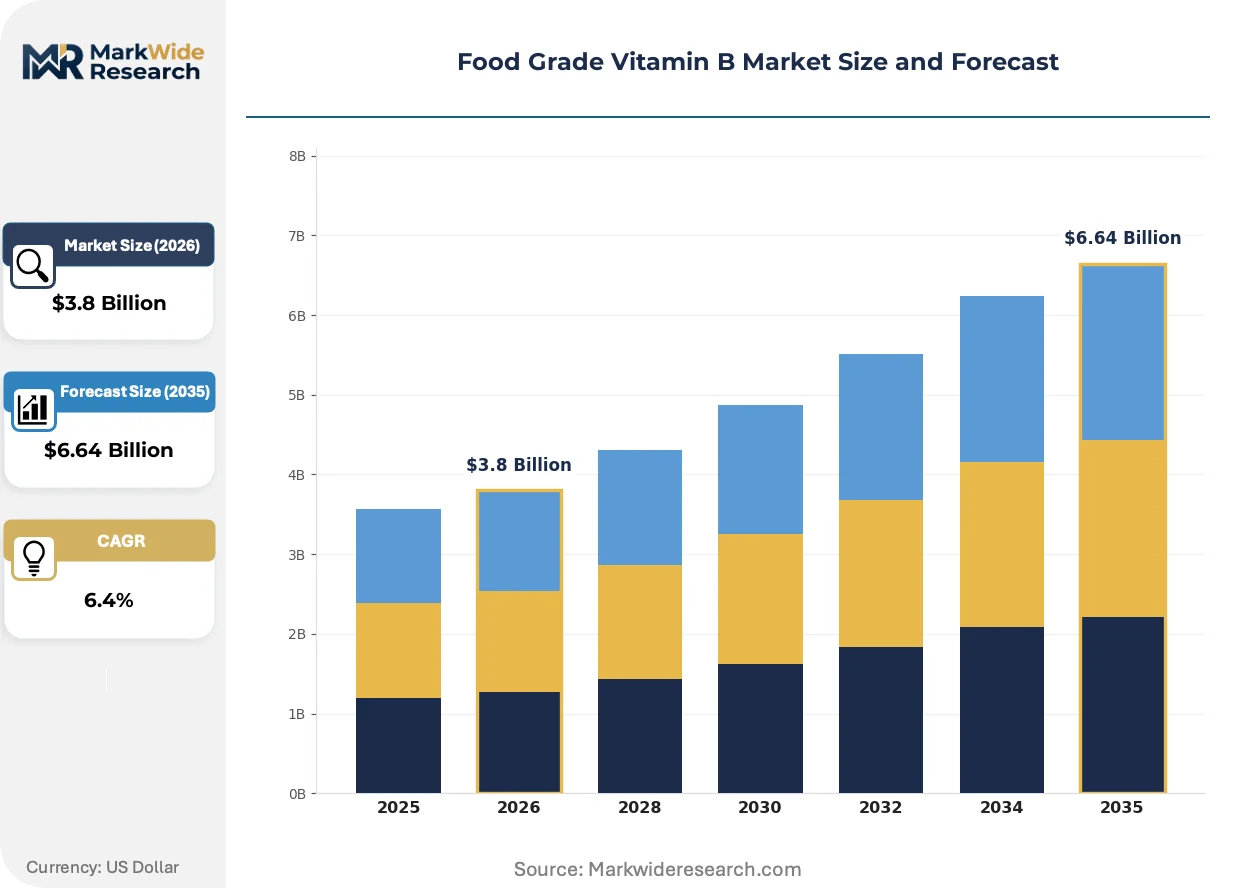
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: B1, B2, B3, B12 Application: Food Fortification, Nutritional Supplements, Beverages, Dairy Products End User: Food Manufacturers, Dietary Supplement Companies, Beverage Producers, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | BASF SE, DSM Nutritional Products, Nutraceutical Corporation, Lonza Group AG, Evonik Industries AG, Kemin Industries, Zhejiang Medicine Co., Ltd., Shandong Huarun Pharmaceutical Co., Ltd., Ferro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Vitamin B Market Trends and Innovations
Production technology and regulatory frameworks are converging to favor biological manufacturing pathways, while downstream formulation demands reshape how B-vitamins reach end consumers. These shifts are compressing traditional supply hierarchies and opening new competitive positions.
Continuous fermentation with real-time metabolite monitoring is hybridizing batch and perfusion modes to maximize B12 titers. Contract manufacturers serving supplement brands are adopting these systems to reduce cycle times and improve lot-to-lot consistency. The technology is compressing minimum efficient scale thresholds, enabling regional production hubs to compete with legacy centralized facilities.
EFSA's updated guidance on maximum fortification levels under Regulation 1925/2006 is forcing reformulation of high-dose energy drinks and meal replacements. Manufacturers are splitting B-vitamin loads across multiple SKUs or switching to bioavailable forms that achieve efficacy at lower declared doses. The beverage segment is responding most aggressively, with functional drink producers redesigning entire product lines to maintain label claims.
Ingredient buyers are consolidating supplier relationships around integrated fermentation-to-premix providers capable of certifying full chain-of-custody. Large supplement brands are reducing their vendor panels from twelve to four qualified sources, prioritizing those with in-house stability testing and regulatory dossier support. This concentration is most visible in North American and Western European markets where finished-product liability exposure drives risk-averse procurement.
Food Grade Vitamin B Market Segmentation
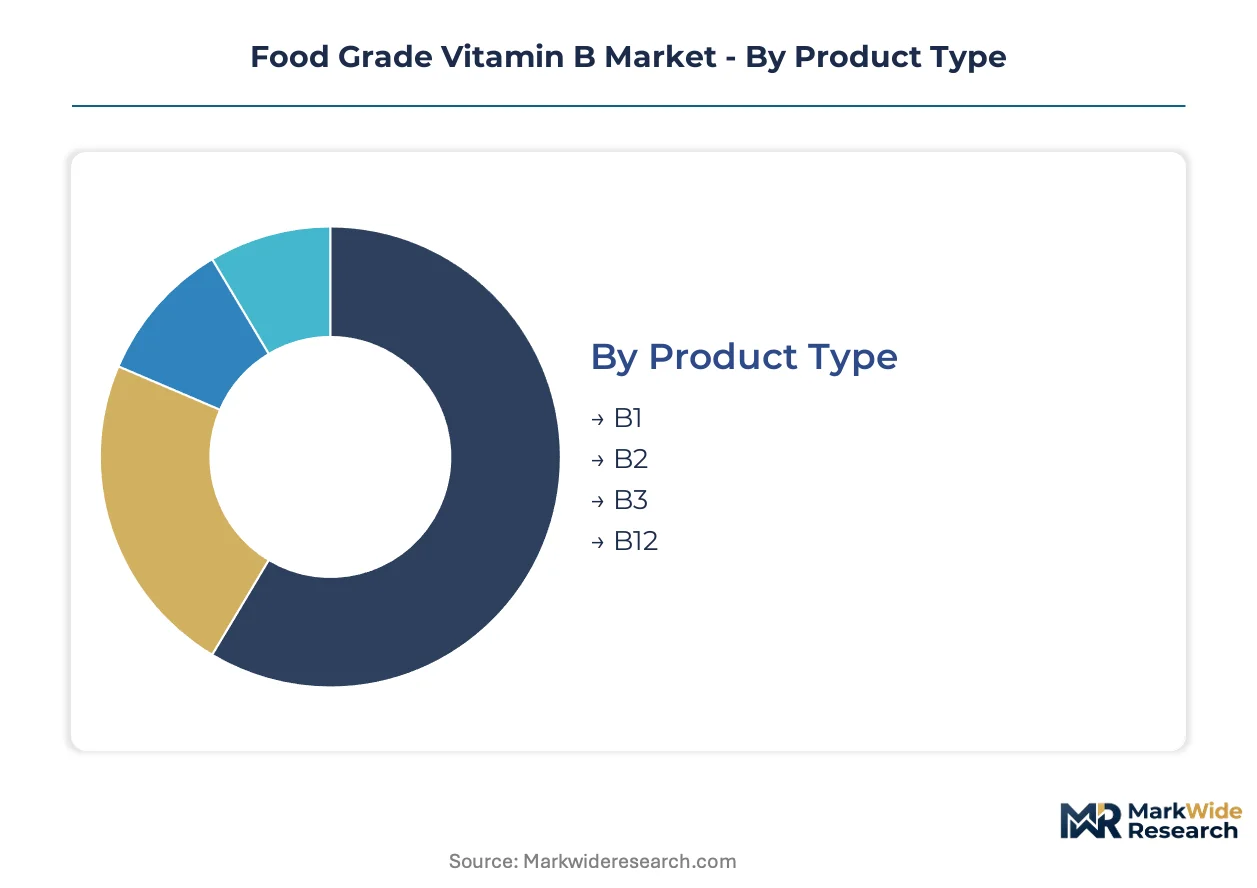
Food grade vitamin B procurement patterns diverge sharply across product categories and end-use channels, with fermentation-derived B12 commanding premium qualification protocols while commodity B3 flows through high-volume fortification contracts. Understanding these segment boundaries clarifies where margin pools concentrate versus where scale economies dominate purchasing decisions.
Product Type:
After-sales technical support intensity varies dramatically across vitamin B fractions, with B12 requiring strain-lineage documentation and stability certification that synthetic B3 simply does not trigger.
- B12:Cobalamin production relies on proprietary Propionibacterium or Pseudomonas denitrificans strains optimized over decades. Dairy-alternative manufacturers in Germany and the Netherlands require batch-level purity attestations exceeding 99% for vegan cheese fortification, creating documentation burdens that filter supplier pools.
- B3:Niacin and niacinamide now derive predominantly from microbial fermentation of glucose feedstocks, displacing legacy petrochemical routes. Chinese fermentation houses in Zhejiang province have scaled capacity to serve pan-Asian food fortification programs, particularly India's FSSAI-mandated wheat and rice enrichment.
- B1:Thiamine mononitrate serves institutional flour fortification programs with standardized purity specifications that minimize supplier switching costs.
- B2:Riboflavin from Ashbya gossypii fermentation supplies yellow colorant applications in pasta and dairy alongside nutritional fortification.
By volume, B3 leads. By growth pace, B12 is ahead.
Application:
Cost tier stratification separates commodity fortification contracts from premium supplement formulations, with beverage applications occupying an intermediate position where taste-masking technology determines supplier selection.
- Nutritional Supplements:Direct-to-consumer brands absorb ingredient premiums through subscription pricing models, enabling qualification of pharmaceutical-grade B-vitamin sources. cGMP-compliant contract manufacturers in Switzerland and the United States capture margin through integrated premix and stability-testing services.
- Food Fortification:Mandatory enrichment programs for flour, rice, and cooking oil operate on procurement tenders where price-per-kilogram dominates supplier selection. India's FSSAI directives and Nigeria's national food fortification alliance generate predictable volume baselines.
- Beverages:Functional drink producers seek heat-stable, non-bitter B-vitamin premixes for shelf-stable formats, prioritizing formulation partnerships over commodity sourcing.
- Dairy Products:Plant-based milk and yogurt alternatives require cobalamin fortification at intensities exceeding traditional dairy, pulling B12 volumes into oat and almond protein processing.
Food Fortification moves the most tonnage. Nutritional Supplements capture the widest margins.
End User:
Customer type determines whether procurement flows through centralized commodity tenders or specialized technical partnerships with formulation support.
- Dietary Supplement Companies:These firms demand comprehensive regulatory dossiers for FDA 21 CFR compliance and EFSA novel food submissions, consolidating vendor relationships around integrated fermentation-to-premix providers.
- Food Manufacturers:Industrial bakeries and cereal producers prioritize supply security through multi-year contracts with fermentation houses capable of certifying full chain-of-custody.
- Beverage Producers:Functional drink startups bypass traditional distribution through vertically integrated formulation services combining taste-masking with B-vitamin stability engineering.
- Pharmacies:Retail pharmacy chains stock food-grade B-complex products alongside pharmaceutical offerings, creating dual-channel demand for identical ingredient specifications.
Food Manufacturers dominate volume procurement. Dietary Supplement Companies drive specification intensity.
Distribution Channel:
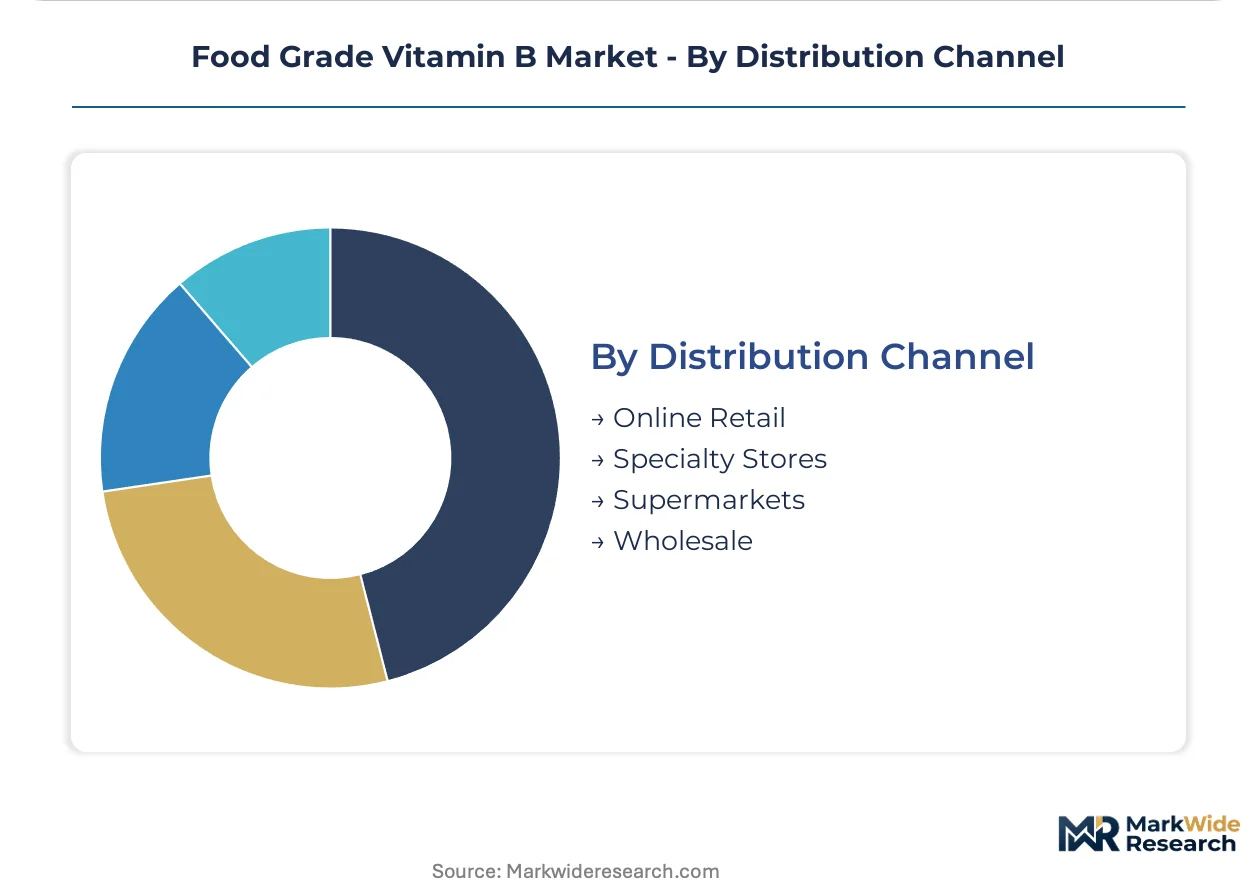
Supply concentration varies by channel, with wholesale and direct contracts serving institutional buyers while online retail fragments purchasing into smaller, specification-diverse orders.
- Wholesale:Bulk B-vitamin distribution to food manufacturers and premix blenders concentrates in Rotterdam and Singapore hub ports, with inventory financing terms shaping supplier loyalty.
- Online Retail:E-commerce platforms enable small supplement brands to access minimum-order quantities previously reserved for major manufacturers, fragmenting demand into diverse specification requests.
- Specialty Stores:Health food retailers stock premium-positioned B-complex products with organic or non-GMO certifications, requiring documentation streams that commodity channels ignore.
- Supermarkets:Mass-market fortified food distribution prioritizes cost minimization through private-label sourcing contracts with minimal technical qualification overhead.
Wholesale channels move the greatest volume. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation houses in Zhejiang and Shandong provinces supply B-vitamin premixes to food manufacturers across Germany, India, and the United States, establishing East Asia as the dominant export node for food-grade B12 and B3 complexes.
United States
Dietary supplement brands absorb ingredient premiums through subscription pricing models, pulling pharmaceutical-grade B-vitamin volumes through cGMP-compliant contract manufacturers. FDA enforces 21 CFR 172 and 184 standards for vitamin B additives, tightening batch documentation requirements. New Jersey and North Carolina host concentrated premix blending capacity serving direct-to-consumer brands.
Germany
Vegan cheese and oat milk producers require cobalamin fortification at intensities exceeding traditional dairy, generating specialized B12 demand. EFSA maximum fortification levels under EU Regulation 1925/2006 force reformulation of high-dose energy drinks. Hamburg and Frankfurt anchor import distribution for Chinese fermentation-derived inputs.
China
Domestic food manufacturers have reduced import dependency as Zhejiang Medicine and Shandong Huarun Pharmaceutical scaled integrated fermentation and downstream refining capacity. NMPA and GB standards for food nutritional fortifiers impose batch-level testing that shapes export eligibility. The Yangtze River Delta concentrates fermentation research clusters advancing strain optimization.
India
FSSAI-mandated rice and wheat fortification programs generate institutional procurement volume for thiamine and niacin premixes. The country's national food regulator maintains strict maximum-level enforcement across staple grain distribution. Gujarat and Maharashtra host premix blending facilities serving government tender channels.
Switzerland
Pharmaceutical-grade cGMP compliance extends into food-grade vitamin B contract manufacturing, capturing premium margin pools from European supplement brands. Swissmedic oversight harmonizes with EFSA novel food requirements for cross-border dossier acceptance. Basel anchors integrated formulation services combining stability testing with regulatory support.
Food Grade Vitamin B Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions, creating a structure where integrated fermentation-to-premix providers capture margin through documentation depth while commodity distributors compete on carbohydrate feedstock efficiency. The vendor base stratifies around three archetypes: legacy strain-optimization houses with decades of microbial cell line development, integrated Chinese fermentation operators with captive refining capacity, and cGMP-compliant contract manufacturers serving pharmaceutical-adjacent food-grade requirements. Dominant competitive moves include backward integration into glucose feedstock sourcing and geographic expansion through regional premix formulation partnerships.
Within the strain-optimization tier, DSM Nutritional Products exemplifies premium positioning sustained through proprietary Propionibacterium and Pseudomonas denitrificans lineages. Among Chinese integrated operators, Zhejiang Medicine Co., Ltd. and Shandong Huarun Pharmaceutical Co., Ltd. occupy positions defined by scaled fermentation output and downstream purification infrastructure. Lonza Group AG sits within the cGMP-compliant contract manufacturing archetype, bridging pharmaceutical-grade compliance into food-grade vitamin B production.
| Leading Market Players |
|---|
| BASF SE |
| DSM Nutritional Products |
| Nutraceutical Corporation |
| Lonza Group AG |
| Evonik Industries AG |
| Kemin Industries |
| Zhejiang Medicine Co., Ltd. |
| Shandong Huarun Pharmaceutical Co., Ltd. |
| Ferro Corporation |
| Others |
Pricing and Supply Chain Analysis
Chinese fermentation capacity in Zhejiang and Shandong provinces anchors upstream B-vitamin supply, concentrating margin capture among integrated operators with captive glucose feedstock sourcing and downstream refining infrastructure. This geographic concentration of microbial cell factory capacity positions strain-optimization specialists to extract premiums from pharmaceutical-grade buyers while commodity B3 flows through high-volume tender channels.
Pricing Analysis
Fermentation-derived B12 commands substantial premiums over legacy petrochemical B3, with pharmaceutical-grade cGMP certification and strain-lineage documentation driving price differentiation. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates buyers by compliance burden and liability exposure. Cost compression in synthetic B3 is intensifying because Chinese fermentation houses have scaled glucose-to-niacin capacity, eroding petrochemical economics. Food manufacturers running government fortification tenders exhibit highest price sensitivity, while direct-to-consumer supplement brands absorb ingredient premiums through subscription pricing models.
Supply Chain Analysis
Extended payment terms from Rotterdam and Singapore hub distributors shape working capital requirements for premix blenders serving European and Southeast Asian food manufacturers. Supply concentrates in China, India, and Switzerland, with Zhejiang fermentation houses feeding German dairy-alternative producers and Swiss cGMP contract manufacturers. Corn syrup and glucose feedstock volatility, agricultural carbohydrate inputs, and proprietary microbial strain dependencies create single-source vulnerability for riboflavin and cobalamin. Distribution runs through wholesale hub ports with inventory financing terms, supplemented by direct contracts between integrated fermentation operators and large supplement brands consolidating vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based bioprocessing is displacing petrochemical synthesis as the dominant production pathway, with EU novel food regulations and FDA fortification guidelines tightening purity thresholds that favor microbial cell factories over synthetic chemistry.
For Market Incumbents: Build regulatory dossier depth as a moat against emerging fermentation operators in China and India. Incumbents should secure backward integration into glucose feedstock sourcing to buffer agricultural price volatility, while investing in continuous fermentation systems with real-time metabolite monitoring to compress cycle times against regional hub competitors. Strain engineering talent scarcity threatens capacity expansion timelines; incumbents must lock metabolic engineering specialists through academic partnerships before new entrants capture this limited pool.
For New Entrants and Emerging Players: India's fortified staple mandate expansion offers the most penetrable institutional procurement channel, with FSSAI-directed rice and wheat enrichment generating predictable volume baselines for thiamine and niacin premixes. New entrants should bypass established distribution hierarchies through vertically integrated formulation services targeting functional beverage startups, combining taste-masking technology with B-vitamin stability engineering to capture direct-to-brand relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated fermentation-to-premix providers with in-house stability testing and full chain-of-custody certification capabilities. Long-term viability in this market hinges on regulatory compliance depth rather than commodity scale, with five-to-ten year returns favoring operators positioned at the convergence of food-grade purity and pharmaceutical-grade cGMP standards. The signal to watch is batch-testing queue extension at third-party verification facilities, which would indicate tightening enforcement of EU 1925/2006 and GB standards and accelerate supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Optimization Investment | DSM Nutritional Products leverages decades of Propionibacterium lineage development to sustain premium positioning in B12 fractions. |
| Integrated Fermentation Scale-Up | Zhejiang Medicine and Shandong Huarun Pharmaceutical have reduced import dependency across East Asian food manufacturing. |
| cGMP Compliance Extension | Lonza Group AG bridges pharmaceutical-grade standards into food-grade vitamin B contract manufacturing for European supplement brands. |
| Direct-to-Brand Premix Platforms | Functional beverage startups bypass traditional distributors through vertically integrated formulation services with taste-masking capabilities. |
| Feedstock Backward Integration | Glucose sourcing control buffers fermentation economics against climate-driven agricultural price swings and biofuel policy competition. |
Research Methodology
A spread of perspectives from fermentation plant managers, supplement brand procurement leads, regulatory affairs directors at premix blenders, and FSSAI enforcement officers converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation from FDA 21 CFR guidance documents, EFSA novel food submissions, NMPA GB standards filings, and customs trade data for B-vitamin premix flows. Bottom-up volume modeling across product types and applications triangulated against top-down macroeconomic indicators.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vitamin B fraction, application channel, end-user archetype, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for policy inflection points and technology substitution curves. Industry-specific forecast inputs incorporated FSSAI fortification mandate expansion timelines and EFSA maximum-level harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported fermentation operators or rapid EU regulatory acceleration would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Tocopherols Market