
 South America Vitamin Fortified and Mineral Enriched Food and Beverage Market | 2026-2036
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market Analytics
Brazilian ingredient suppliers is rebalancing toward domestic micronutrient premix capacity as import substitution gains traction. Nestlé S.A. leverages its Pan-regional dairy fortification infrastructure to anchor supply continuity. PepsiCo, Inc. competes through sports nutrition line extensions targeting Brazilian gym culture. Abbott Laboratories specializes in clinical-grade formulations for senior nutrition segments across Argentina and Chile.
Vitamin fortified and mineral enriched food and beverage denotes products where micronutrients are added during or after processing to achieve specified nutritional claims, typically requiring stability-tested premixes that withstand thermal treatment and shelf-life degradation. These products serve to address documented dietary gaps in populations with rising non-communicable disease burdens. Functional foods and nutritional bars represent the most established margin pools, while energy drinks command accelerating volume growth through gym and convenience channel penetration. Sports nutrition applications lead value capture, though general health positioning sustains broader household penetration across income tiers. Distribution through supermarkets still dominates transaction volume, yet online retail is displacing traditional health stores for repeat purchases in metropolitan Brazil.
ANVISA governs micronutrient claim thresholds and maximum fortification limits in Brazil, while Argentina's national food code enforces parallel compositional standards that shape cross-border product harmonization. The EU Green Deal's extraterritorial sustainability traceability requirements are beginning to condition South American export-oriented fortification ingredient sourcing. Stakeholders must monitor how pending Mercosur regulatory convergence on nutrient reference values will reshape formulation portfolios and label architectures.
Market Dynamics
ANVISA's updated fortification guidelines are compressing formulation timelines and forcing premix suppliers to accelerate stability testing protocols across Brazilian manufacturing corridors.
Growth Catalysts
- Sports nutrition demand:Brazilian and Argentine fitness consumers are driving volume uptake through gym-channel penetration of protein-fortified beverages and mineral-enriched recovery products.
- ANVISA regulatory clarity:The agency's tightened micronutrient labeling requirements are standardizing claim thresholds, reducing compliance fragmentation for cross-border formulations.
- Southeastern urban corridor concentration:Health-conscious middle-class households in São Paulo and Rio de Janeiro metropolitan zones dominate premium fortified food purchasing.
Market Restraints
- Import-dependent premix inputs:Brazilian domestic micronutrient capacity remains insufficient, exposing formulators to currency volatility and lead-time extension from Asian suppliers.
- Thermal degradation limits:Vitamin C and B-complex stability under UHT dairy processing constrains fortification intensity in ambient-stable milk categories.
- Mercosur regulatory divergence:Argentina's national food code maintains parallel compositional standards that complicate harmonized label architectures for regional product portfolios.
Strategic Opportunities
- Chilean senior nutrition gap:Underpenetrated clinical-grade formulation demand among aging populations in Santiago and Valparaíso offers specialized margin pools for targeted entrants.
- Online retail channel expansion:E-commerce platforms are displacing traditional health stores for repeat purchases in metropolitan Brazil, enabling direct-to-consumer micronutrient subscription models.
- EU Green Deal traceability:Extraterritorial sustainability sourcing requirements are conditioning export-oriented ingredient procurement, creating first-mover advantage for certified supply chain operators.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities produce insufficient graduates with dual competence in food science and micronutrient bioavailability optimization.
- Legacy dairy infrastructure retrofit costs:Existing UHT and spray-drying lines require capital-intensive modification to handle oxygen-sensitive vitamin premixes without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Vitamin Fortified and Mineral Enriched Food and Beverage Market |
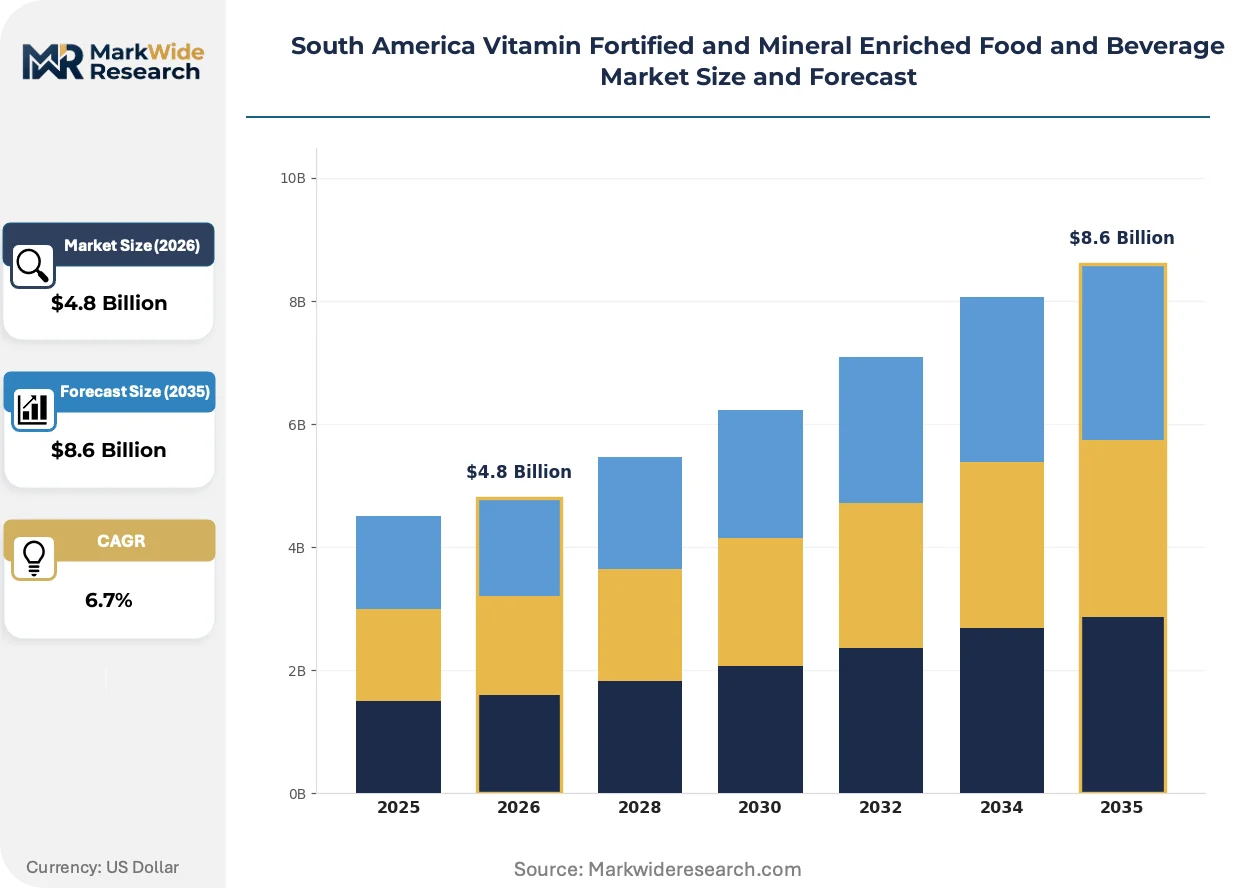
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Nutritional Bars, Vitamin Supplements, Functional Foods Application: Sports Nutrition, Meal Replacement, General Health, Weight Management End User: Children, Adults, Seniors, Athletes Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | Nestlé S.A., PepsiCo, Inc., The Coca-Cola Company, Kellanova, Abbott Laboratories, General Mills, Danone S.A., The Hain Celestial Group, Amway Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market Evolving Landscape
Encapsulation technologies and digital traceability systems are compressing the gap between laboratory stability testing and commercial shelf-life performance across South American fortification operations.
Microencapsulation of heat-sensitive vitamins using lipid-based matrices is absorbing thermal stress during UHT milk processing, enabling Brazilian dairy processors to maintain label claim potency through 180-day ambient distribution cycles. Mid-tier cooperatives in Minas Gerais are piloting these systems at commercial scale. The technology is absorbing margin pressure from reformulation costs by extending product viability in supermarket ambient aisles.
ANVISA's pending alignment with Codex Alimentarius reference values is tightening maximum fortification ceilings for iron and zinc in staple foods. Brazilian breakfast cereal manufacturers must reformulate portfolios to comply with revised thresholds before enforcement deadlines. The policy shift most acutely affects mass-market positioned brands dependent on high-dose mineral claims for competitive differentiation.
Gym-based purchasing is rotating toward ready-to-drink formats over powdered mixes among Brazilian fitness consumers seeking convenience without shaker preparation. Convenience stores adjacent to São Paulo training facilities are expanding refrigerated SKU counts at the expense of dry goods shelf space. This pattern concentrates in southeastern metropolitan zones where disposable income and training frequency intersect most densely.
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market Segmentation
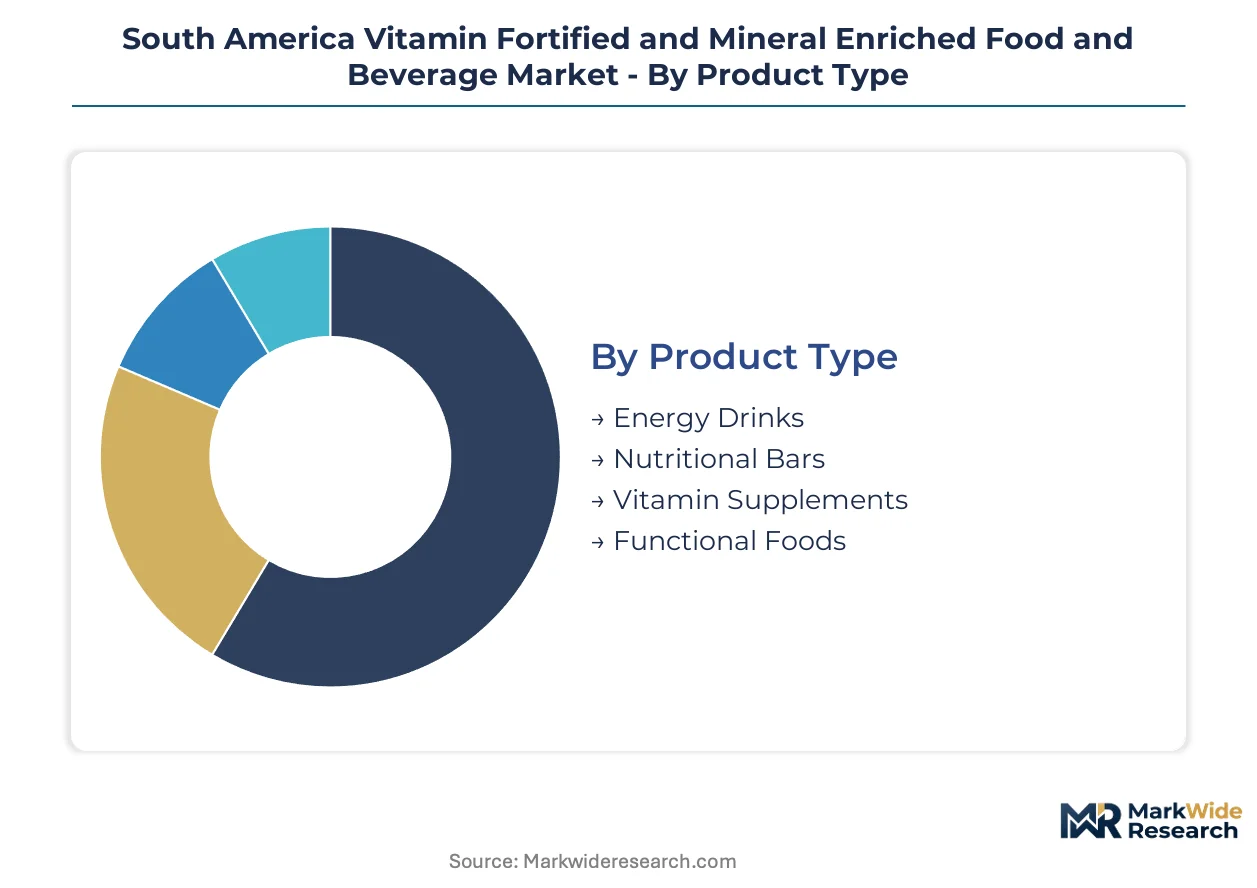
Fortified food and beverage portfolios in South America require segment-specific ANVISA compliance pathways, with thermal stability thresholds and micronutrient claim ceilings varying sharply across product formats. Formulation teams must align premix specifications against distinct regulatory burdens before commercial rollout.
Product Type:
ANVISA's fortification guidelines impose divergent stability-testing obligations across these categories, with dairy-adjacent formats facing the most stringent thermal degradation protocols.
- Functional Foods:Ambient-stable milk, yogurt, and breakfast cereals carry the heaviest ANVISA documentation burden for iron and zinc maximum limits. São Paulo metropolitan supermarkets dominate volume movement for premium-positioned fortified dairy lines.
- Energy Drinks:Caffeine-plus-B-vitamin formulations require separate stability validation for acidic pH matrices. Brazilian gym-channel penetration in Rio de Janeiro and Belo Horizonte is concentrating demand for mineral-enriched recovery variants.
- Nutritional Bars:Shelf-life claim validation demands accelerated aging studies for lipid-oxidation-sensitive vitamin premixes.
- Vitamin Supplements:Clinical-grade formats trigger Argentina's national food code parallel registration requirements for cross-border distribution.
Functional foods sits at the top of the volume ranking, with energy drinks climbing the fastest.
Application:
Margin structures diverge sharply across these use cases, with clinical-positioned segments commanding formulation premiums over mass-market health claims.
- Sports Nutrition:Protein-fortified beverages and electrolyte recovery systems require gym-channel cold-chain integrity. Argentine fitness consumers in Buenos Aires and Córdoba are driving uptake of ready-to-drink formats over powdered alternatives.
- General Health:Broad household penetration depends on supermarket price accessibility and simplified label claims. Southeastern Brazilian middle-class households in the São Paulo-Rio corridor sustain the core revenue base.
- Meal Replacement:Complete nutrition positioning demands micronutrient density validation against ANVISA reference daily intake benchmarks.
- Weight Management:Calorie-controlled fortification requires careful balancing of satiety signaling with vitamin bioavailability.
Sports nutrition captures the steepest margin expansion, while general health maintains the broadest household penetration.
End User:
Demographic targeting determines both micronutrient dosage architecture and distribution channel priority, with pediatric and geriatric segments triggering enhanced safety documentation.
- Adults:Working-age consumers in Brazil's southeastern urban corridor drive repeat purchase frequency for convenience-positioned fortified beverages. ANVISA's updated labeling requirements are standardizing claim thresholds for this mass-market segment.
- Seniors:Clinical-grade formulations for Chile's aging Santiago and Valparaíso populations require specialized bioavailability optimization. Abbott Laboratories has anchored supply continuity for this underpenetrated margin pool.
- Children:School-age targeting demands strict iron and zinc ceiling compliance under pending Codex alignment.
- Athletes:Competitive positioning requires batch-tested certification for banned substance absence.
Adults represents the largest addressable population, with seniors gaining share fastest as Chilean demographic shifts accelerate.
Distribution Channel:
Channel selection dictates both pricing architecture and consumer education burden, with digital platforms displacing traditional health stores for replenishment purchases.
- Supermarkets:Ambient-aisle placement for UHT dairy and breakfast cereals depends on 180-day shelf-life validation. Minas Gerais cooperatives are piloting microencapsulation systems to secure this channel positioning.
- Online Retail:E-commerce platforms enable direct-to-consumer micronutrient subscription models with reduced intermediation costs. Metropolitan Brazilian repeat purchasers are rotating toward digital channels for convenience.
- Health Stores:Specialty retail retains importance for first-time trial and clinical-grade product education.
- Convenience Stores:Gym-adjacent locations in São Paulo are expanding refrigerated SKU counts for ready-to-drink sports nutrition.
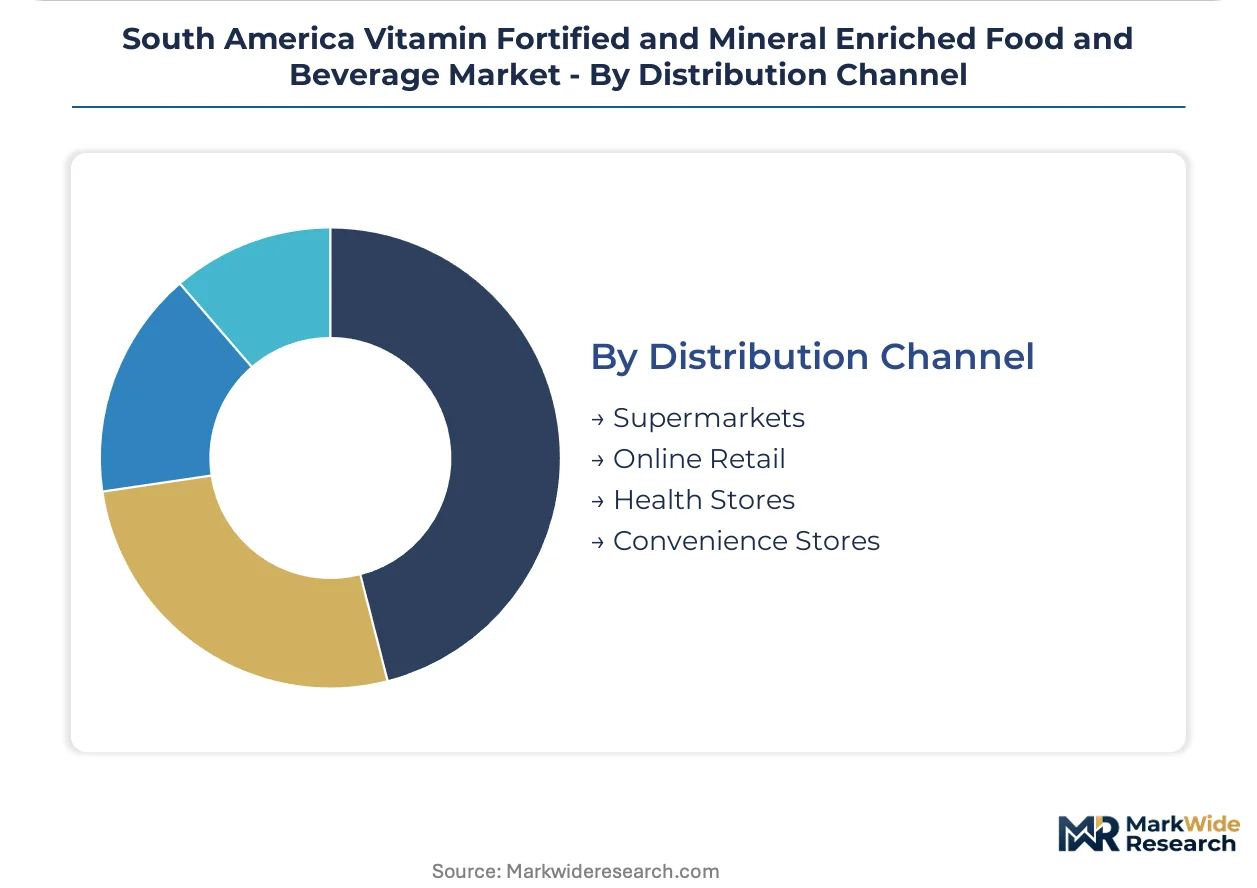
Supermarkets holds the transaction volume lead, with online retail expanding most quickly through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as Brazilian formulators absorb ANVISA compliance costs while Argentine and Chilean operators exploit labeling threshold differentials. Manufacturers migrate micronutrient premix sourcing toward domestic capacity to compress lead-time exposure from Asian supply chains.
Brazil
Southeastern metropolitan clusters in São Paulo and Rio de Janeiro concentrate demand for sports nutrition and fortified dairy. ANVISA's updated fortification guidelines are compressing formulation timelines and forcing premix suppliers to accelerate stability testing protocols. Minas Gerais cooperatives are piloting microencapsulation systems at commercial scale to secure ambient-aisle positioning in supermarket channels.
Argentina
Buenos Aires and Córdoba fitness consumers are driving uptake of ready-to-drink formats over powdered alternatives in gym-channel distribution. The national food code maintains parallel compositional standards that complicate harmonized label architectures for regional product portfolios. Domestic breakfast cereal manufacturers face reformulation deadlines as pending Codex alignment tightens maximum fortification ceilings.
Chile
Santiago and Valparaíso present underpenetrated clinical-grade formulation demand among aging populations seeking specialized margin pools. The country's national food regulator enforces micronutrient claim thresholds that shape cross-border product harmonization with Argentine and Brazilian standards. Abbott Laboratories has anchored supply continuity for this geriatric nutrition segment through targeted distribution infrastructure.
Colombia
Bogotá metropolitan health-conscious households are sustaining volume growth for convenience-positioned fortified beverages. The national health ministry's pending alignment with regional fortification standards is creating compliance preparation cycles among domestic processors. Andean urban corridors are emerging as secondary demand centers as disposable income expansion penetrates beyond traditional Brazilian and Argentine markets.
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clinical-grade specialization and direct-to-consumer subscription models. The market structure concentrates around multinational food conglomerates with Pan-regional dairy fortification infrastructure and specialized nutrition companies with bioavailability optimization capabilities. Three archetypes dominate: diversified consumer goods conglomerates leveraging scale, clinical nutrition specialists commanding formulation premiums, and agile regional cooperatives piloting encapsulation technologies. Competitive moves center on portfolio diversification into sports nutrition line extensions and strategic partnerships with domestic premix suppliers to reduce import dependency.
Among Switzerland-based conglomerates, Nestlé S.A. and specialized health science operators, Abbott Laboratories exemplify divergent strategic positioning within the fortified nutrition space. Nestlé S.A. anchors supply continuity through existing Pan-regional dairy infrastructure, while Abbott Laboratories occupies a clinical-grade tier targeting aging demographic segments. PepsiCo, Inc. sits within the diversified consumer goods archetype, competing through convenience-channel penetration and gym-adjacent distribution formats.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Kellanova |
| Abbott Laboratories |
| General Mills |
| Danone S.A. |
| The Hain Celestial Group |
| Amway Corporation |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's extraterritorial sustainability traceability requirements are gating qualified supply access and premium-tier pricing power for South American fortification ingredient buyers. ANVISA's tightened micronutrient labeling standards are compressing margins for non-compliant suppliers while rewarding certified operators with pricing premiums in Brazilian supermarket channels.
Pricing Analysis
Retailer markup layers in Brazilian supermarket channels absorb significant margin from micronutrient premix suppliers serving UHT dairy and breakfast cereal categories. Three-tier pricing structure across clinical-grade, mass-market fortified, and economy private-label levels separates Abbott Laboratories' senior nutrition positioning from Nestlé's mainstream dairy lines and regional cooperative economy offerings. Cost compression in mass-market tiers is intensifying because ANVISA reformulation deadlines are forcing accelerated stability testing investments. Price-sensitive household purchasers in São Paulo's middle-class corridors drive volume, while clinical-grade geriatric buyers in Santiago exhibit lowest price elasticity.
Supply Chain Analysis
Hub-and-spoke distribution patterns from São Paulo and Rio de Janeiro regional centers feed southeastern Brazilian supermarket and gym-channel demand. Supply concentrates in Brazil for dairy fortification infrastructure, Argentina for cereal processing, and Chile for clinical nutrition formulation. Raw material dependencies draw from Chinese vitamin C and B-complex suppliers, Indian mineral premix sources, and domestic Brazilian dairy protein streams. Single-source vulnerability from Asian micronutrient inputs exposes formulators to currency volatility and lead-time extension. Distribution runs through supermarket ambient aisles for functional foods, with e-commerce platforms displacing health stores for repeat purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Vitamin Fortified and Mineral Enriched Food and Beverage Market functions as a stable compounder. Brazilian and Argentine fitness culture sustains steady sports nutrition volume expansion across gym and convenience channels.
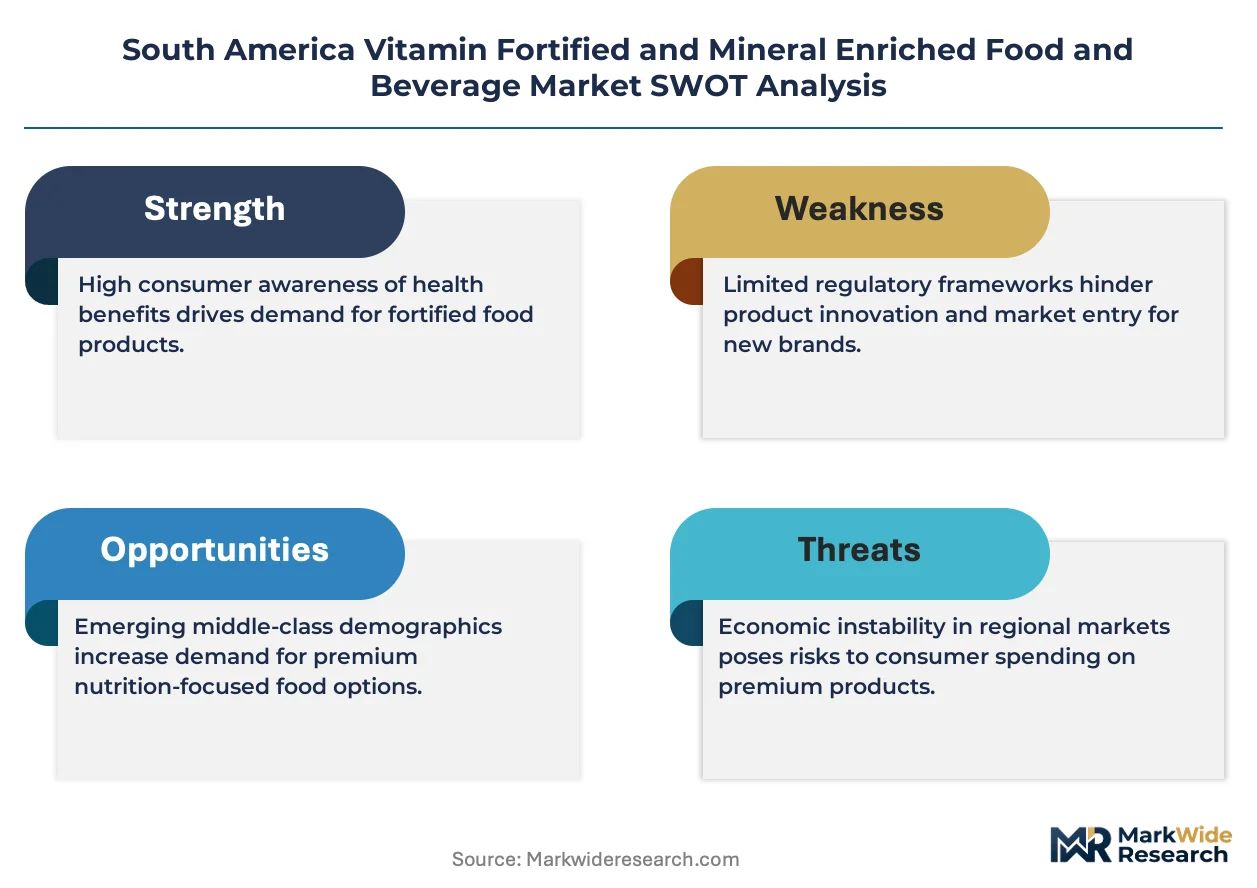
For Market Incumbents: Extend microencapsulation technology licensing to mid-tier cooperatives in Minas Gerais before competitors capture ambient-aisle positioning. Anchor supply continuity through backward integration into domestic premix capacity as import substitution accelerates. Defend against agile regional cooperatives piloting stability-tested formulations by accelerating ANVISA compliance documentation for cross-border portfolios. For New Entrants and Emerging Players: Lipid-based vitamin matrix technologies offer a technology-first wedge into Brazilian UHT dairy processing where thermal degradation has constrained incumbent fortification intensity. Target Chile's underpenetrated clinical-grade senior nutrition segment in Santiago and Valparaíso where Abbott Laboratories has anchored supply but specialized margin pools remain available. Pursue direct-to-consumer subscription models through e-commerce platforms displacing traditional health stores for metropolitan Brazilian repeat purchases. For Investors and Strategic Acquirers: Roll-up economics work for clinical nutrition specialists because ANVISA and Codex alignment is fragmentating formulation capabilities across compliance tiers. Five-to-ten year viability hinges on demographic aging in Chile and Argentina expanding geriatric nutrition addressable markets. Target acquisition archetypes: bioavailability-optimization laboratories with ANVISA registration pathways. Watch for EU Green Deal sustainability certification adoption as inflection indicator for premium-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables Minas Gerais cooperatives to secure 180-day ambient shelf-life validation for UHT dairy. |
| Domestic Premix Capacity Buildout | Reduces Brazilian formulator exposure to Asian supplier currency volatility and lead-time extension. |
| Direct-to-Consumer Subscription Launch | Captures metropolitan Brazilian repeat purchasers rotating from health stores to e-commerce platforms. |
| Clinical-Grade Geriatric Line Extension | Addresses underpenetrated Santiago and Valparaíso aging population demand with bioavailability-optimized formulations. |
| EU Green Deal Certification Program | Conditions export-oriented ingredient sourcing for first-mover advantage in sustainability-traceable supply chains. |
Research Methodology
Multiple input streams — primary interviews with formulation chemists, ANVISA regulatory affairs specialists, and supermarket category buyers; secondary validation through customs trade records, ANVISA fortification guideline filings, and dairy cooperative production disclosures — were reconciled through bottom-up and top-down triangulation. Supply-side data from Brazilian micronutrient premix manufacturers and demand-side patterns from São Paulo metropolitan retail audits were cross-referenced against Argentine national food code documentation and Chilean clinical nutrition distribution records.
Data-stream reconciliation across product type, application, end user demographic, and distribution channel dimensions produced volume and value outputs over the projection horizon. Segmentation modeling captured functional foods, energy drinks, nutritional bars, and vitamin supplements by sports nutrition, general health, meal replacement, and weight management applications. CAGRs were derived from trend extrapolation of Brazilian gym-channel penetration rates and Argentine ready-to-drink format adoption curves, calibrated against ANVISA regulatory timeline assumptions.
The model holds under stable ANVISA-Codex alignment trajectory; deviation in Mercosur regulatory convergence timing or EU Green Deal enforcement stringency would shift premium-tier pricing assumptions. Forecasts reflect documented stakeholder input and secondary source validation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Fortified Baby Food Market