
 Global Vitamins Market | 2026-2036
Global Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitamins Market Outlook
Subscription-based personalized vitamin services are restructuring how consumers purchase nutritional supplements, shifting transactions from one-time retail buys to recurring revenue models. BASF leverages its petrochemical feedstock integration to sustain cost leadership in bulk vitamin synthesis. dsm-firmenich anchors its position through biotechnology-driven fermentation processes for specialty vitamin forms. Glanbia competes in sports nutrition channels where vitamin premixes command premium positioning.
Vitamins comprise organic micronutrients essential for metabolic regulation, typically synthesized through chemical transformation or microbial fermentation with purity thresholds exceeding 98% for pharmaceutical-grade applications. These compounds serve as critical inputs in food fortification, animal nutrition, and human dietary supplementation where deficiency correction drives clinical and commercial value. Vitamin B complexes dominate volume throughput due to their integration into feed additives for livestock operations across multiple continents. Gummies represent the fastest-expanding formulation type as palatability concerns reshape adult compliance behavior. Online retail channels capture margin pools through direct-to-consumer subscription mechanics that bypass traditional pharmacy intermediaries.
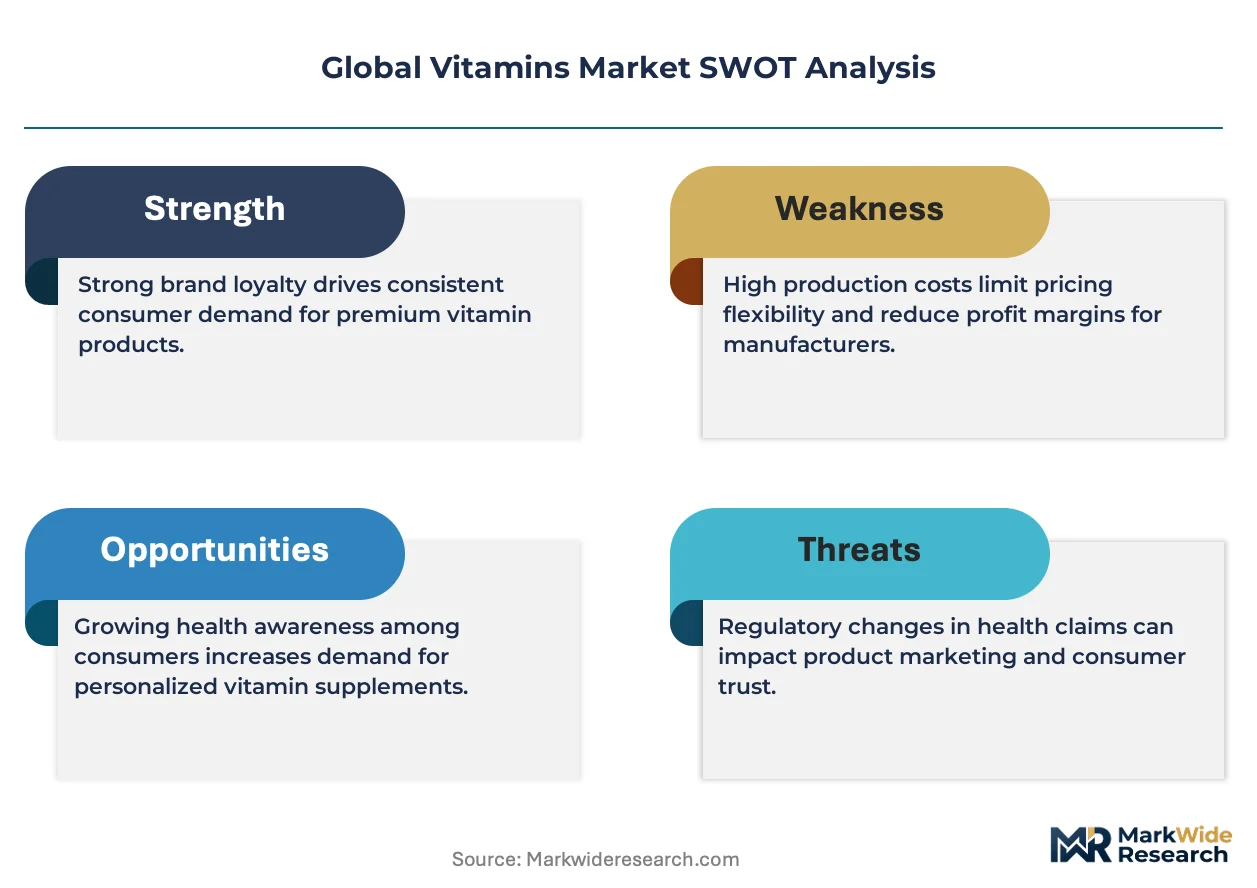
The FDA oversees Current Good Manufacturing Practice regulations for dietary supplements in the United States, while the EMA and EFSA coordinate novel food ingredient assessments and health claim validations across European jurisdictions. China's NMPA and SAMR enforce GB standards for domestic vitamin production and import registration, creating compliance barriers for foreign suppliers. Stakeholders must monitor evolving bioequivalence requirements for synthetic versus naturally derived vitamin forms as regulatory divergence between jurisdictions intensifies qualification costs.
Market Dynamics
Subscription mechanics are restructuring vitamin distribution by collapsing traditional retail intermediaries into direct-to-consumer platforms that capture recurring revenue streams and granular consumer health data.
Growth Catalysts
- Elderly Preventive Health Demand:Aging populations in Germany and Japan are adopting daily multivitamin regimens as frontline interventions against cognitive decline and bone density loss, expanding the chronic-use patient base beyond acute deficiency treatment.
- EFSA Health Claims Regulation:The European Union's tightening substantiation requirements for label claims is paradoxically strengthening compliant brands by creating competitive moats against unsubstantiated market entrants.
- Microbial Fermentation Advancement:Biotechnology-driven production processes for specialty vitamin forms are reducing synthetic chemistry dependence and enabling stereospecific isomer production that commands pharmaceutical-grade premiums.
Market Restraints
- Petrochemical Feedstock Volatility:Bulk vitamin synthesis remains tethered to naphtha and propylene derivatives, exposing BASF and Chinese state-owned producers to energy price swings that compress margin predictability.
- Chinese Production Concentration:Synthetic vitamin capacity clustering in Shandong and Zhejiang provinces creates single-source vulnerability for global feed additive supply chains serving livestock operations across Brazil and the United States.
- Bioequivalence Validation Gaps:Regulatory divergence between FDA pharmaceutical standards and SAMR food-grade classifications for natural versus synthetic vitamin forms intensifies cross-border qualification costs and timeline uncertainty.
Strategic Opportunities
- Indian Preventive Health Penetration:FSSAI fortification mandates for staple foods create embedded vitamin demand in a market where per-capita supplement consumption remains one-fifth of developed economy levels.
- Personalized Nutrition Platforms:At-home biomarker testing integration with algorithm-driven supplement formulation is opening recurring-revenue channels that bypass pharmacy retail entirely.
- Gummy Format Expansion:Palatability-driven compliance behavior among adult consumers is elevating gelatin and pectin-based delivery systems from pediatric niches to mainstream positioning in United States and United Kingdom markets.
Industry Challenges
- Fermentation Scale-Up Expertise Scarcity:Industrial microbiology talent capable of optimizing yield in 100,000-liter bioreactors for vitamin B2 and B12 production concentrates at dsm-firmenich and select Chinese state laboratories, constraining competitor entry.
- Cross-Jurisdictional Registration Complexity:Simultaneous FDA NDI notification, EFSA novel food assessment, and NMPA import registration for a single vitamin K2 menaquinone variant requires 18-36 month coordinated regulatory affairs investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitamins Market |
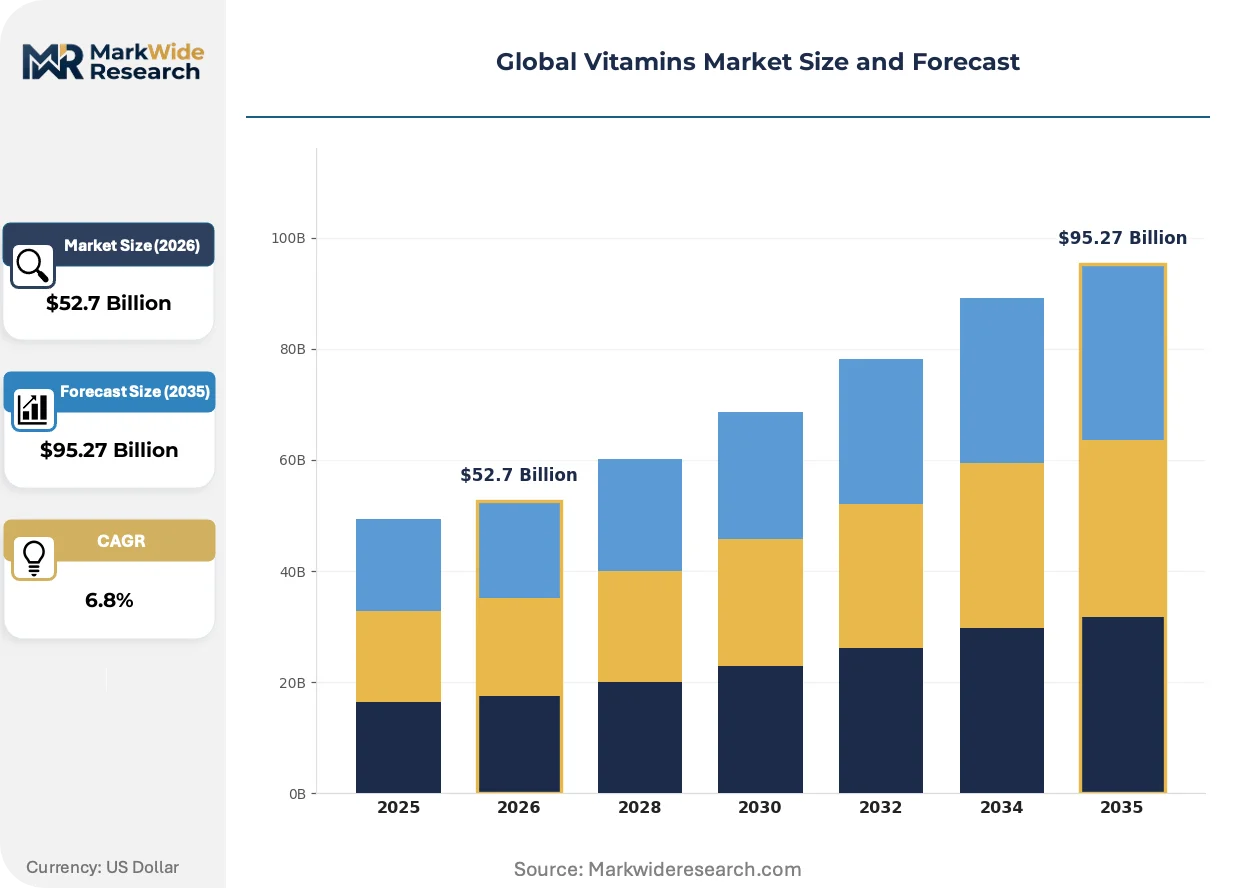
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin A, Vitamin B, Vitamin C, Vitamin D Formulation Type: Tablets, Capsules, Powders, Gummies End User: Adults, Children, Pregnant Women, Elderly Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | BASF, dsm-firmenich, Archer Daniels Midland Company, SternVitamin GmbH & Co. KG, Glanbia, Lonza, Bayer AG, Pfizer, Adisseo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitamins Market Strategic Shifts
Continuous bioprocessing and precision fermentation are converging to displace batch chemistry in vitamin manufacturing, while regulatory frameworks and consumer channel preferences undergo simultaneous recalibration.
Precision fermentation using engineered yeast strains is electrifying the production economics of vitamin D3 and K2, converting sterol precursors through enzymatic pathways that eliminate traditional wool grease extraction. Pharmaceutical manufacturers in Switzerland and Denmark are adopting these platforms to secure supply chains decoupled from lanolin volatility. This biotechnology shift is compressing synthetic chemistry's cost advantage in high-purity specialty segments where stereoisomer specificity determines bioactivity.
China's NMPA and SAMR enforcement of revised GB standards for vitamin production and import registration is tightening documentary requirements for foreign suppliers seeking market access. Domestic manufacturers in Shandong province are leveraging this regulatory friction to defend market share through accelerated local certification. The policy shift most acutely affects European and North American brands targeting China's direct-to-consumer e-commerce channels.
Direct subscription platforms are displacing pharmacy retail as the primary acquisition channel for adult multivitamin users in the United States and United Kingdom. These models bundle automated replenishment with digital health coaching, capturing lifetime value metrics that traditional retail cannot replicate. The behavioral pivot is most visible among millennials managing chronic conditions through preventive supplementation rather than reactive pharmaceutical intervention.
Global Vitamins Market Segmentation
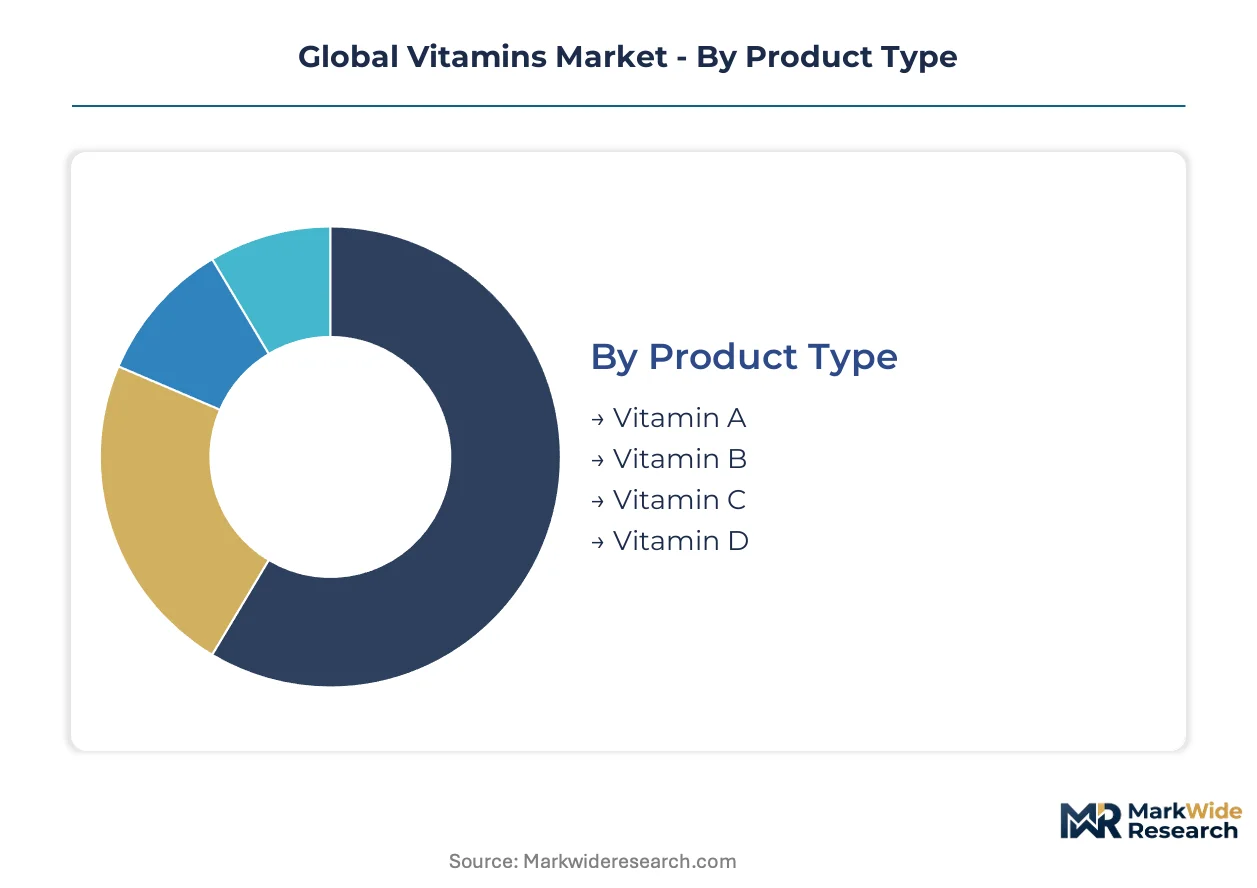
Vitamin market segmentation reveals how formulation innovation, demographic targeting, and channel mechanics create distinct competitive arenas. Each axis carries unique margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Biochemical synthesis pathways and stereoisomer specificity define competitive differentiation across vitamin categories.
- Vitamin A:Retinol and retinyl ester forms require controlled-environment synthesis due to photosensitivity degradation. Feed fortification in Brazil and the United States consumes bulk volumes, while pharmaceutical-grade retinoid production concentrates in Switzerland for dermatology applications. Synthetic beta-carotene from BASF and Chinese state-owned producers dominates commodity supply.
- Vitamin B:Complex of eight distinct water-soluble compounds manufactured through fermentation or chemical synthesis depending on specific B-factor. Thiamine and riboflavin production clusters in Shandong province feed global livestock operations, while cobalamin (B12) fermentation requires specialized microbiology expertise concentrated at dsm-firmenich. This complex anchors volume throughput across human supplements and animal nutrition.
- Vitamin C:Ascorbic acid synthesized via Reichstein-Grüssner process or two-step fermentation from glucose. Chinese manufacturers in Jiangsu province control bulk supply chains for food fortification and dietary supplements.
- Vitamin D:Cholecalciferol (D3) traditionally extracted from lanolin or produced via UV irradiation of 7-dehydrocholesterol. Precision fermentation platforms in Denmark and Switzerland are displacing wool grease dependence for pharmaceutical-grade supply.
Mature deployment sits with Vitamin B complexes. Newer deployment is concentrated in Vitamin D fermentation-derived specialty forms.
Formulation Type:
Delivery system selection directly shapes patient compliance curves and manufacturing capital requirements.
- Tablets:Compressed powder matrices with disintegrants and binders enabling high-speed production economics. Direct compression technology at Glanbia and Indian contract manufacturers serves mass-market multivitamin positioning in Germany and Japan.
- Capsules:Gelatin or HPMC shells encapsulating powders, granules, or oils for modified release profiles. Liquid-filled hard capsules for fat-soluble vitamins command premium positioning in United States specialty channels.
- Gummies:Gelatin or pectin-based chewable matrices with flavor masking for palatability-driven compliance. Adult adoption in United Kingdom and United States markets is climbing the fastest as subscription platforms target millennials with chronic condition management.
- Powders:Bulk active ingredients or effervescent granules for beverage fortification and sports nutrition integration. Direct-to-consumer sachet formats bypass traditional pharmacy intermediaries.
Tablets and capsules retain institutional procurement dominance. Gummies are gaining share fastest in direct-to-consumer channels.
End User:
Physiological life-stage requirements create distinct dosage, formulation, and channel preferences.
- Adults:Working-age consumers aged 18-64 seeking preventive supplementation or lifestyle optimization. Subscription platforms in the United States target this cohort with personalized multivitamin stacks based on at-home biomarker testing.
- Children:Pediatric formulations require palatability engineering and age-appropriate dosing precision. Gummy formats dominate this segment in United Kingdom retail.
- Pregnant Women:Folate and iron requirements drive prescription-adjacent positioning with obstetrician endorsement channels. Prenatal multivitamins in Germany carry EFSA-substantiated neural tube defect prevention claims.
- Elderly:Consumers over 65 with elevated needs for bone density, cognitive function, and absorption-optimized forms. Daily multivitamin regimens in Japan serve frontline interventions against sarcopenia and cognitive decline.
Adult segments anchor subscription platform revenue. Elderly targeting is expanding most quickly in preventive health positioning.
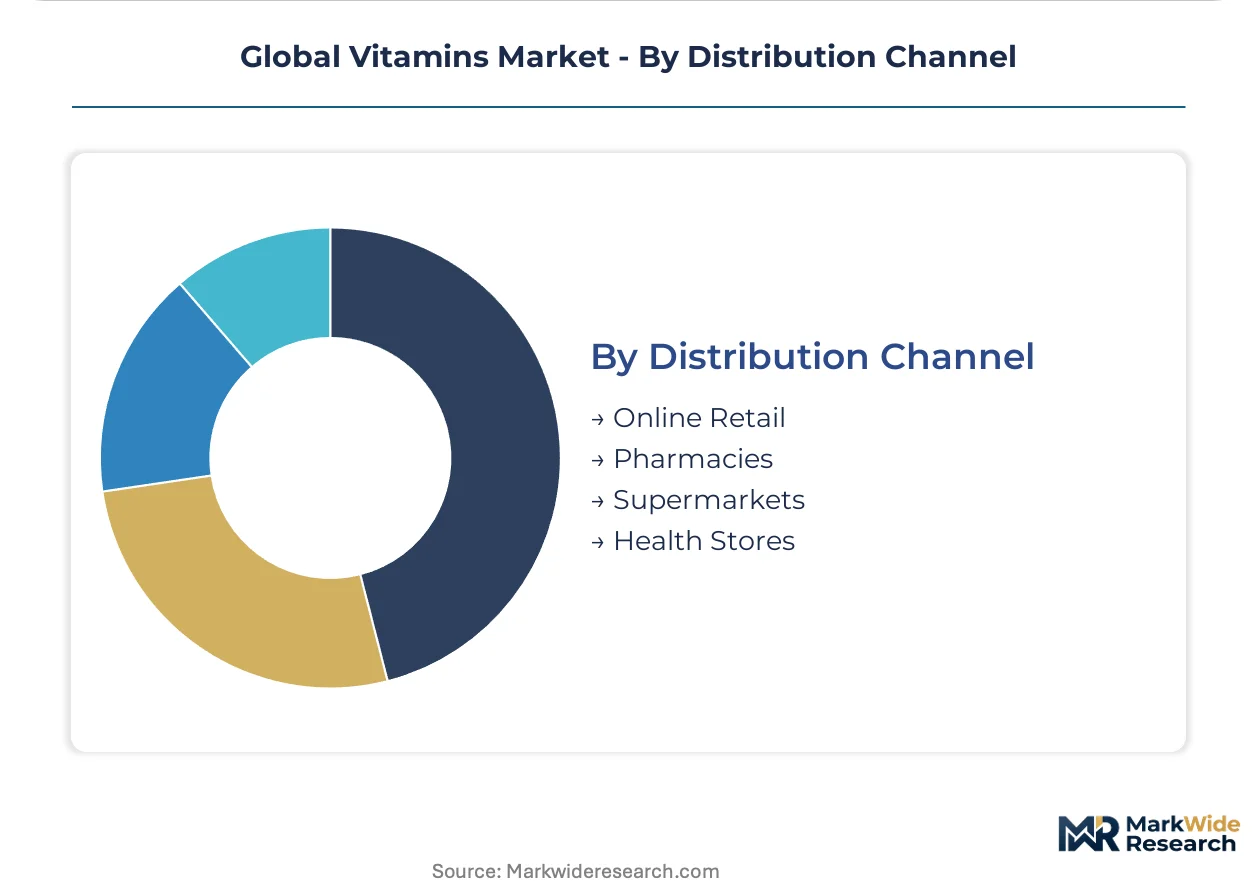
Distribution Channel:
Channel selection determines margin capture, consumer data access, and regulatory compliance burden.
- Online Retail:Direct-to-consumer platforms with automated replenishment and health coaching bundling. Amazon and specialized subscription services in the United States capture lifetime value metrics unavailable to brick-and-mortar competitors.
- Pharmacies:Pharmacist-assisted selection with clinical credibility endorsement. German and Japanese pharmacy networks retain loyalty for condition-specific vitamin recommendations.
- Supermarkets:Mass-market accessibility with price-competitive private label positioning. FSSAI-mandated fortified staples in Indian supermarkets embed vitamin demand at point of grocery purchase.
- Health Stores:Specialty retailers with trained staff and premium brand curation. United Kingdom independents and GNC franchise networks serve enthusiast consumers seeking novel vitamin K2 menaquinone variants.
Pharmacy and supermarket channels retain mass-market volume. Online retail represents the steepest expansion trajectory for recurring-revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of bulk vitamin intermediates while the United States and Germany consume the highest per-capita volumes of finished formulations. This geographic split between production and consumption creates distinct regulatory and logistics imperatives for suppliers.
China
Domestic manufacturers in Shandong and Zhejiang provinces scale synthetic vitamin capacity to serve global feed additive demand. NMPA and SAMR enforcement of revised GB standards tightens documentary requirements for foreign suppliers seeking direct-to-consumer e-commerce access. Shandong province anchors bulk thiamine and riboflavin output for livestock operations across Brazil and the United States.
United States
Millennial consumers drive subscription platform adoption for personalized multivitamin stacks based on at-home biomarker testing. FDA Current Good Manufacturing Practice regulations govern dietary supplement quality systems with inspection protocols that differ from pharmaceutical-grade standards. Direct-to-consumer channels in California and New York capture recurring revenue streams that bypass traditional pharmacy intermediaries.
Germany
Aging populations adopt daily multivitamin regimens as frontline interventions against cognitive decline and bone density loss. EFSA substantiation requirements for health claims create competitive moats against unsubstantiated market entrants. Pharmacy networks in Bavaria and North Rhine-Westphalia retain consumer loyalty for condition-specific vitamin recommendations.
India
FSSAI fortification mandates for staple foods create embedded vitamin demand in a market where per-capita supplement consumption remains below developed economy levels. CDSCO and FSSAI coordinate on novel food ingredient assessments with timelines that extend qualification periods for imported finished goods. Maharashtra and Gujarat host contract manufacturing clusters serving domestic and export markets.
Japan
Elderly consumers over 65 expand the chronic-use patient base through preventive supplementation targeting sarcopenia and cognitive function. PMDA and METI oversee quality standards with emphasis on absorption-optimized forms for aging physiology. Kanto region manufacturers specialize in premium formulations for both domestic consumption and regional export.
Global Vitamins Market Competitive Environment
Capital-heavy producers compete with asset-light designers as the market structures around distinct capability requirements. Bulk synthesis operations demand petrochemical integration and fermentation infrastructure that few players can replicate. Three archetypes dominate: integrated chemical conglomerates with feedstock advantages, biotechnology specialists with fermentation expertise, and brand aggregators with direct-to-consumer platform control. Competitive moves center on capacity expansion in Chinese manufacturing zones and strategic partnerships that secure distribution access in regulated Western markets.
Within the integrated chemical tier, BASF leverages petrochemical feedstock integration to sustain cost leadership in bulk vitamin synthesis. Among biotechnology specialists, dsm-firmenich anchors its position through fermentation processes for specialty vitamin forms. At the brand aggregation end, Glanbia occupies a position in sports nutrition channels where vitamin premixes command differentiated positioning. These three represent distinct strategic paths rather than direct competitors across identical segments.
| Leading Market Players |
|---|
| BASF |
| dsm-firmenich |
| Archer Daniels Midland Company |
| SternVitamin GmbH & Co. KG |
| Glanbia |
| Lonza |
| Bayer AG |
| Pfizer |
| Adisseo |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation platforms for vitamin D3 and K2 production are compressing synthetic chemistry's historical cost advantage while simultaneously redistributing supply concentration toward biotechnology-capable facilities in Denmark and Switzerland. This dual shift fragments pricing power away from petrochemical-integrated bulk producers toward specialty manufacturers commanding pharmaceutical-grade premiums.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade vitamin forms accelerates because precision fermentation yields stereospecific isomers that eliminate traditional extraction dependencies. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived specialty vitamins from synthetic commodity grades and feed-additive bulk volumes. Price differentiation traces to certification grade under FDA pharmaceutical standards versus SAMR food-grade classifications, with brand premiums attaching to EFSA-substantiated health claims. Subscription-based direct-to-consumer platforms exhibit lowest price sensitivity due to recurring revenue mechanics, while livestock feed additive procurement remains most cost-responsive.
Supply Chain Analysis
Returns and quality-control flows for temperature-sensitive vitamin shipments concentrate reverse logistics investment around pharmaceutical distribution hubs in Germany and the United States. Bulk synthesis capacity clusters in China's Shandong and Zhejiang provinces, with fermentation expertise concentrating at dsm-firmenich facilities in Switzerland and select Danish biotechnology sites. Raw material dependencies include naphtha derivatives for synthetic routes, glucose feedstocks for fermentation, and gelatin or pectin for gummy formulations. Single-source vulnerability from Chinese production concentration threatens global feed additive supply chains. Distribution runs through direct-to-consumer subscription platforms, pharmacy networks, and supermarket retail channels with divergent margin profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around fermentation-capable producers as regulatory divergence and capital intensity force out synthetic-only competitors lacking biotechnology scale.
For Market Incumbents: Hedge against petrochemical feedstock volatility by accelerating backward integration into glucose supply chains or securing long-term fermentation feedstock offtake agreements. Defend position by investing in EFSA health claim substantiation to create regulatory moats against unsubstantiated entrants in European pharmacy channels. Prioritize capacity addition in Shandong province to maintain cost competitiveness in bulk B-vitamin segments serving Brazilian and United States livestock operations. For New Entrants and Emerging Players: Enter via personalized nutrition platforms targeting millennial consumers in the United States with at-home biomarker testing integration and algorithm-driven supplement formulation. White-space opportunity sits with gummy format expansion for adult compliance in United Kingdom direct-to-consumer channels, where palatability-driven behavior shifts bypass traditional tablet incumbents. Go-to-market angle should leverage subscription mechanics with automated replenishment to capture lifetime value metrics unavailable to retail competitors. For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology specialists possessing industrial-scale fermentation expertise given tightening EFSA substantiation requirements and FDA pharmaceutical-grade standards. Long-term viability favors platforms with demonstrated 100,000-liter bioreactor yield optimization capability across the next decade. Acquisition target archetype includes precision fermentation specialists with vitamin K2 menaquinone or D3 production platforms. Signal to watch is NMPA import registration approval velocity for foreign suppliers seeking China e-commerce access.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Denmark and Switzerland facilities secure supply chains decoupled from lanolin volatility. |
| EFSA Health Claim Substantiation | Regulatory investment creates competitive moats against unsubstantiated market entrants in Germany. |
| Direct-to-Consumer Platform Launch | Subscription mechanics capture recurring revenue streams bypassing pharmacy intermediaries in the United States. |
| Backward Integration into Feedstocks | Glucose supply chain control reduces synthetic chemistry dependence for fermentation platforms. |
| Cross-Jurisdictional Registration Coordination | Simultaneous FDA, EFSA, and NMPA filings accelerate market access timelines for vitamin K2 variants. |
Study Parameters
Document review covered FDA Current Good Manufacturing Practice regulations, EFSA novel food assessments, NMPA GB standards, and customs trade data, complemented by interviews with fermentation plant managers at biotechnology specialists, procurement leads at livestock feed additive distributors, regulatory affairs directors navigating multi-jurisdictional registrations, and pharmacy category buyers in Germany and Japan. Secondary validation drew from SEC filings of integrated chemical conglomerates, dsm-firmenich sustainability disclosures, and FSSAI fortification mandate documentation. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Historical consumption patterns were cross-referenced against panel input from industry stakeholders to construct analytical framework projections. Segmentation dimensions modeled include vitamin category, formulation type, end-user demographic, and distribution channel complexity. CAGRs were derived through regression analysis of historical volume trajectories adjusted for regulatory inflection points and technology substitution rates. Industry-specific forecast inputs incorporated precision fermentation yield improvement curves and EFSA health claim approval timelines.
Revisions become necessary when NMPA enforcement actions disrupt China import registration pathways, when petrochemical feedstock volatility exceeds historical bands, or when precision fermentation platforms achieve cost parity with synthetic routes faster than modeled. Practitioners should monitor SAMR documentary requirement changes, Shandong province production disruption indicators, and millennial subscription platform churn rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
South America Food Fortifying Agents Market