
 Fortified Breakfast Spreads Market | 2026-2036
Fortified Breakfast Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Breakfast Spreads Market Analysis
Health-oriented millennial households is unwinding the traditional family-pantry buyer archetype that long dominated breakfast spread procurement. Nestlé S.A. leverages its pediatric nutrition heritage to anchor fortified chocolate spread credibility with parent segments. Unilever Plc sustains broad retail penetration through dual-branding across premium and everyday price tiers. The J.M. Smucker Company competes aggressively in nut butter fortification with added protein and omega positioning.
Fortified breakfast spreads are emulsion-based or gelled food products with added micronutrients, proteins, fibers, or whole-grain components, manufactured through controlled thermal processing to preserve bioactive stability while achieving spreadable viscosity. Their primary commercial purpose is to deliver condensed nutritional value in convenient breakfast formats that replace or supplement conventional bread toppings. Nut butters lead product type margins due to premium positioning and clean-label ingredient costs, while protein enrichments within ingredient type categories are expanding fastest as sports nutrition logic migrates into mainstream breakfast occasions. Online retail distribution channels are capturing growth from subscription-model startups, though supermarkets still control the bulk volume through end-cap promotional placement.
The FDA governs nutrient content claims and fortification ceilings under U.S. food labeling regulations, while EFSA and the EU Green Deal framework shape permissible health claims and sustainable sourcing disclosures across European markets. India's FSSAI has tightened micronutrient premix standards for imported fortified spreads, creating compliance friction for multinational entrants. Stakeholders must monitor diverging national fortification ceilings and evolving front-of-pack labeling mandates to avoid formulation fragmentation that would splinter production economies.
Market Dynamics
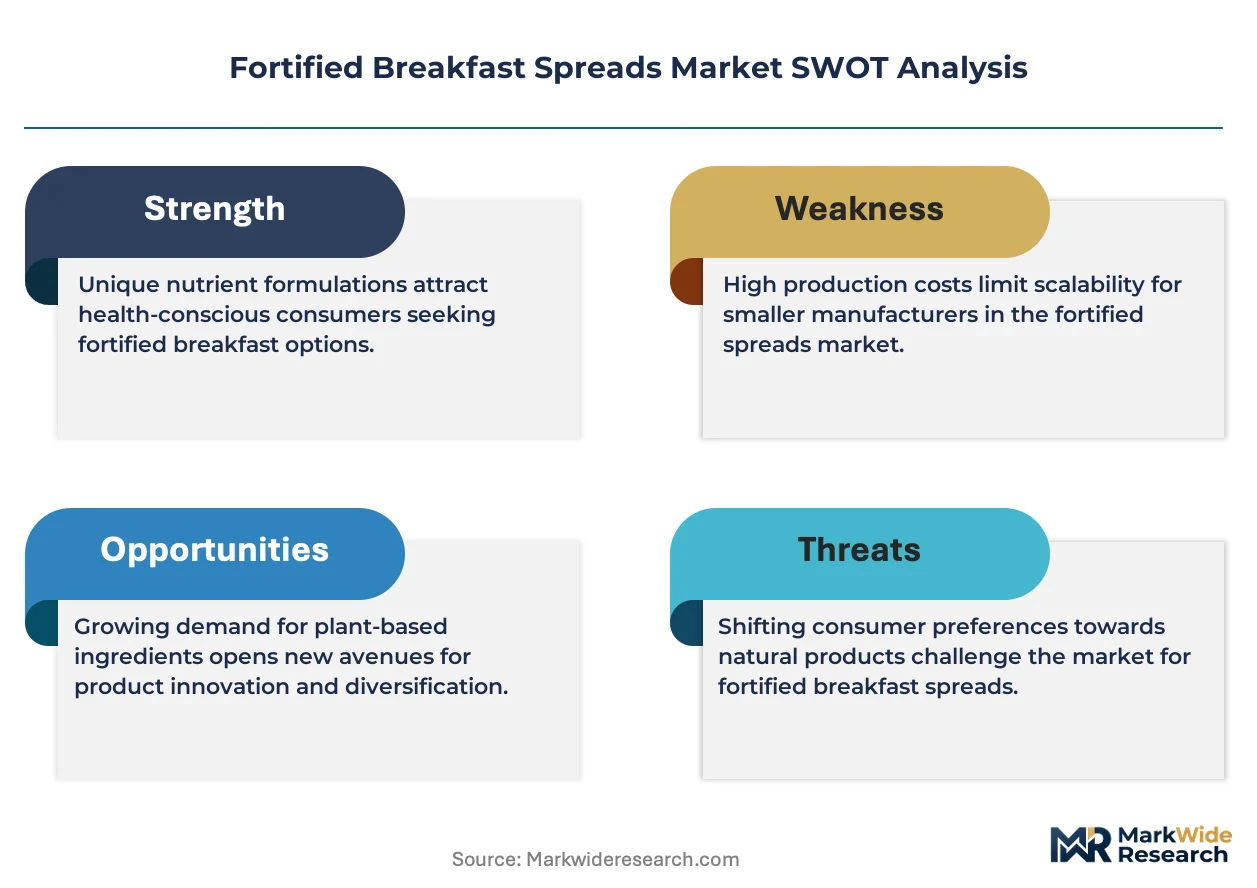
Clean-label ingredient mandates and front-of-pack labeling schemes are compressing formulation flexibility across the fortified breakfast spreads sector, forcing manufacturers to rebuild emulsion stability without artificial stabilizers or high-sugar bases.
Growth Catalysts
- EU Green Deal sustainable sourcing disclosures:Mandatory carbon footprint tracking for imported nut butters is accelerating supplier certification upgrades across European retail networks.
- Sports nutrition end-use migration:Protein-fortified spreads are capturing morning consumption occasions from traditional shakes and bars among athletic households.
- Controlled thermal processing advances:Precision pasteurization systems preserve heat-sensitive micronutrients in vitamin-enriched formulations without viscosity degradation.
Market Restraints
- Palm oil input cost volatility:Spreadable viscosity requirements tie manufacturers to tropical oil supplies exposed to climate-driven harvest fluctuations and export restrictions.
- FSSAI micronutrient premix standards:India's tightened import specifications create compliance bottlenecks for multinational brands seeking entry into organized retail.
- Clean-label emulsifier scarcity:Replacement of synthetic lecithin with sunflower or rapeseed alternatives narrows qualified supplier pools and extends procurement lead times.
Strategic Opportunities
- German private-label shelf space expansion:Aldi and Lidl networks are allocating end-cap positioning to store-brand fortified spreads with Nutri-Score A/B ratings.
- Subscription-model direct-to-consumer channels:Recurring delivery platforms bypass supermarket slotting fees while capturing nutritional personalization data.
- Fiber-protein dual fortification convergence:Prebiotic fiber integration with plant protein isolates addresses digestive wellness and satiety positioning simultaneously.
Industry Challenges
- Bioactive stability certification timelines:Shelf-life validation for heat-sensitive vitamin matrices extends product development cycles by eight to fourteen months.
- Legacy emulsion equipment retrofitting:Existing thermal processing lines require capital-intensive upgrades to handle lower-sugar, higher-protein formulations without phase separation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Breakfast Spreads Market |
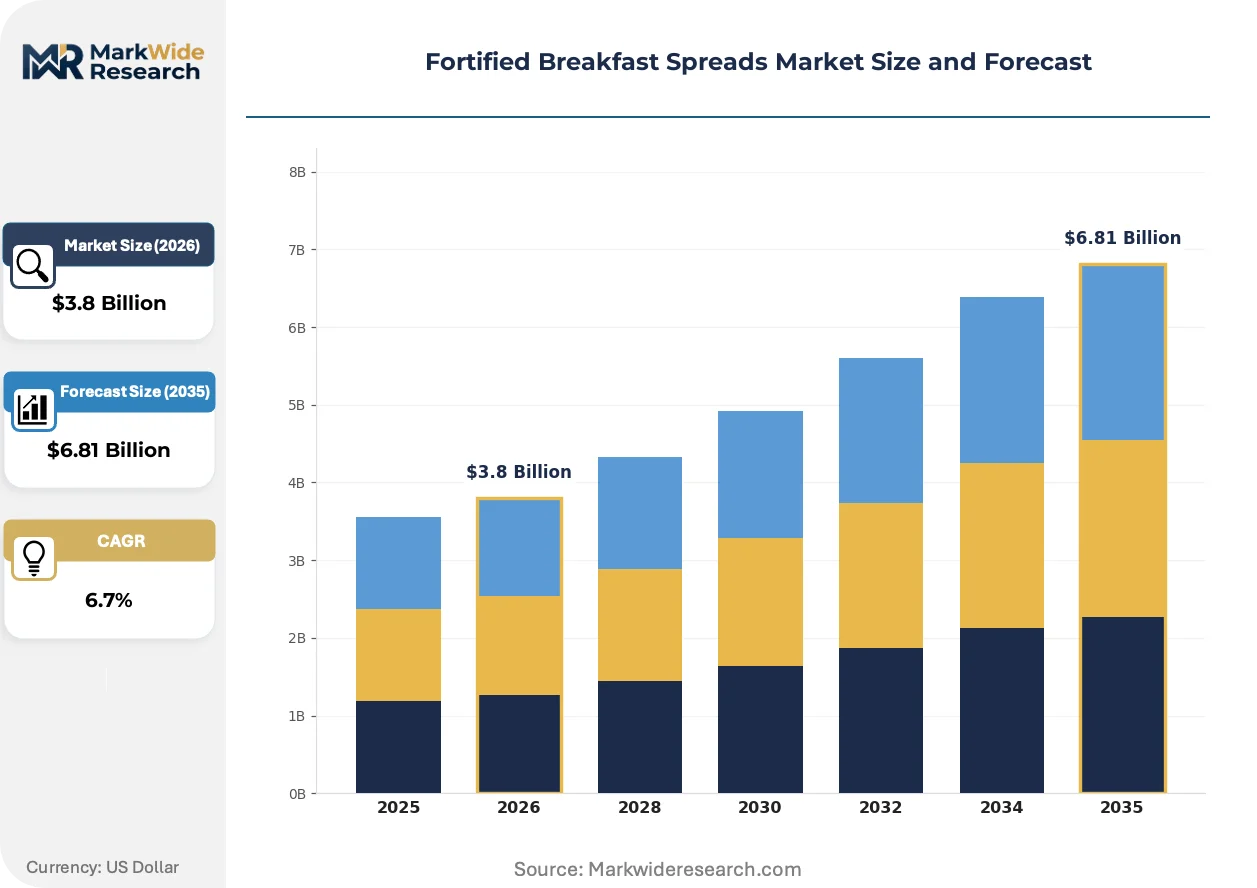
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Butters, Fruit Spreads, Chocolate Spreads, Creamy Spreads Ingredient Type: Whole Grains, Protein Enrichments, Fiber Sources, Natural Sweeteners End User: Households, Food Service, Hotels, Cafés Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Nestlé S.A., Unilever Plc., Ferrero Group, The Kraft Heinz Company, The J.M. Smucker Company, Conagra Brands Inc., The Hershey Company, Andros SAS, Premier Foods Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Breakfast Spreads Market Emerging Trajectories
Formulation science and retail channel structures are diverging simultaneously as manufacturers navigate incompatible demands for extended shelf stability and minimal processing claims.
Microencapsulation technology for lipid-soluble vitamins is bifurcating product development pipelines. Premium tier producers are adopting spray-dried lipid shell systems to mask off-flavors in omega-fortified nut butters. Mass-market brands retain conventional premix dispersion, accepting shorter shelf-life claims. This technical split is compressing mid-tier positioning that cannot justify encapsulation costs nor compete on clean-label credentials.
REACH chemical safety assessments and EU F-Gas Regulation phase-down schedules are reshaping industrial refrigeration dependencies in spread manufacturing facilities. Cold-chain stability requirements for probiotic-fortified formulations now face equipment replacement pressures. German and Dutch processing plants are piloting ammonia-based cooling systems to maintain temperature-controlled emulsion integrity without synthetic refrigerant exposure.
Pantry stocking patterns among millennial households are fragmenting bulk purchase behavior into smaller-format, higher-frequency buying. Single-serve fortified spread pods are displacing traditional jar formats in urban convenience retail. This rotation is most pronounced in UK and French metropolitan markets where refrigerator space constraints and portability preferences reshape breakfast routine logistics.
Fortified Breakfast Spreads Market Segmentation
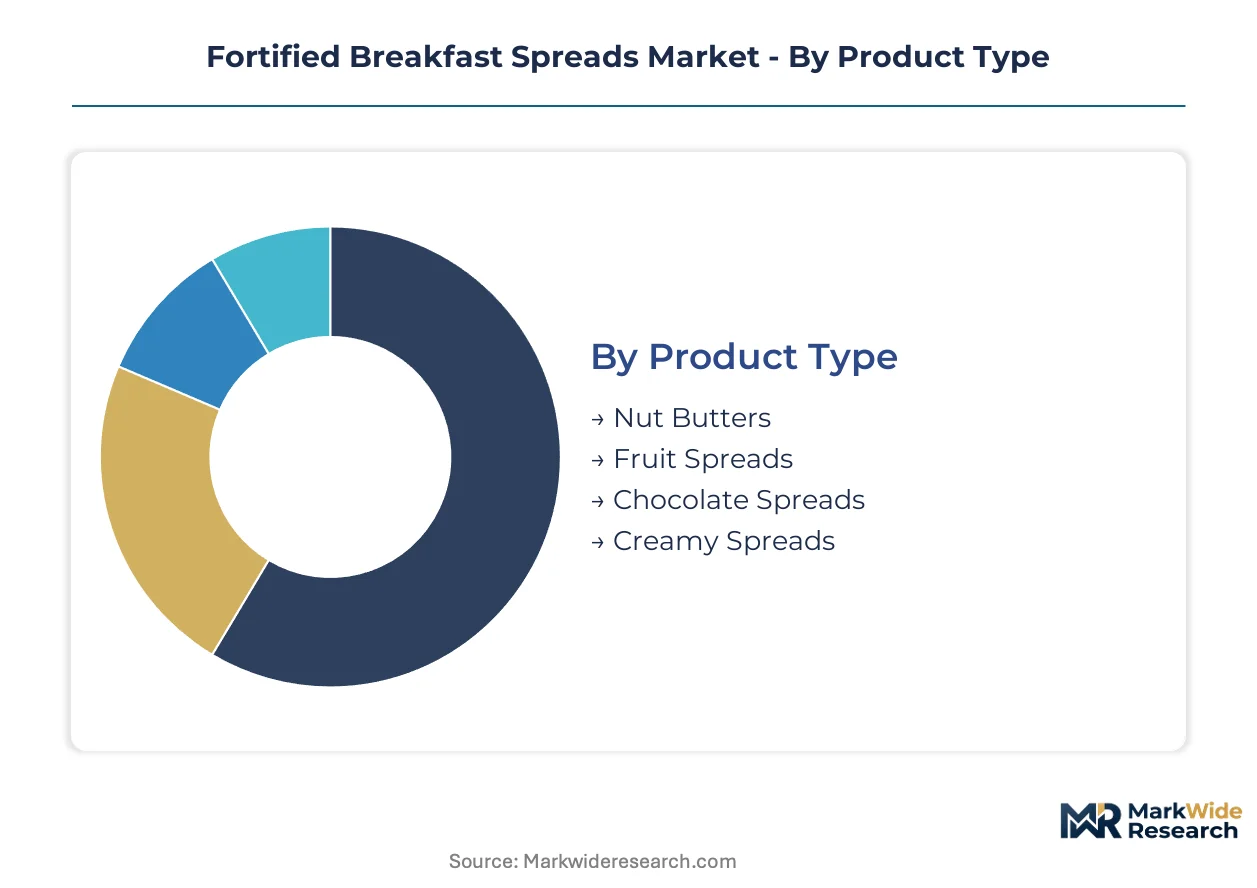
Segmentation in fortified breakfast spreads reveals where formulation investments concentrate and which channels capture shifting consumption patterns. Product type and ingredient composition decisions determine margin structures, while distribution channel selection shapes brand accessibility versus premium positioning trade-offs.
Product Type:
Nut butters face the sharpest substitution pressure from private-label alternatives and emerging seed-based spreads, forcing differentiation through fortification intensity and sourcing certification.
- Nut Butters:Almond, peanut, and cashew bases carry premium positioning through clean-label ingredient costs and protein density. German retailers Aldi and Lidl now stock fortified private-label nut butters with Nutri-Score A ratings, compressing branded shelf space.
- Chocolate Spreads:Cocoa-based emulsions with added micronutrients leverage pediatric nutrition credibility among parent segments. Nestlé anchors this segment through heritage positioning, though EU sugar reduction mandates force reformulation toward natural sweetener bases.
- Fruit Spreads:Reduced-sugar jams with fiber fortification target health-conscious households seeking traditional breakfast formats.
- Creamy Spreads:Dairy-alternative and hybrid emulsions occupy mid-tier positioning between indulgence and functional nutrition claims.
Nut butters anchor the volume base while chocolate spreads gain share at the steepest rate through child-targeted fortification marketing.
Ingredient Type:
Cost tier stratification separates commodity premix suppliers from proprietary encapsulation technology holders, with protein isolate sourcing commanding the widest price spreads.
- Protein Enrichments:Plant protein isolates from pea, rice, and sunflower sources integrate into spreadable matrices through controlled thermal processing. Sports nutrition logic migration into breakfast occasions drives fastest expansion in this category.
- Fiber Sources:Prebiotic inulin and chicory root fibers address digestive wellness positioning alongside satiety claims. Dual fortification with protein isolates creates convergent product development pipelines in UK and French metropolitan markets.
- Whole Grains:Milled oat, quinoa, and amaranth components add texture complexity and micronutrient density.
- Natural Sweeteners:Monk fruit, stevia, and allulose replacements reduce glycemic load while maintaining palatability in reduced-sugar formulations.
Fiber sources anchor the volume base while protein enrichments expand most quickly as athletic consumption patterns mainstream.
End User:
Customer type fragmentation accelerates as single-serve formats displace bulk household purchasing among urban millennial demographics.
- Households:Pantry stocking behavior fragments into smaller-format, higher-frequency buying patterns. Refrigerator space constraints in UK and French metropolitan markets drive single-serve pod adoption over traditional jar formats.
- Food Service:Institutional procurement specifications emphasize portion control and extended ambient stability for hospitality operations.
- Hotels:Breakfast buffet positioning favors individually wrapped fortified spreads for hygiene and waste reduction compliance.
- Cafés:Artisan coffee chains specify premium nut butter pairings for toast and pastry programs.
Households anchor the volume base while cafés gain share at the steepest rate through premium positioning partnerships.
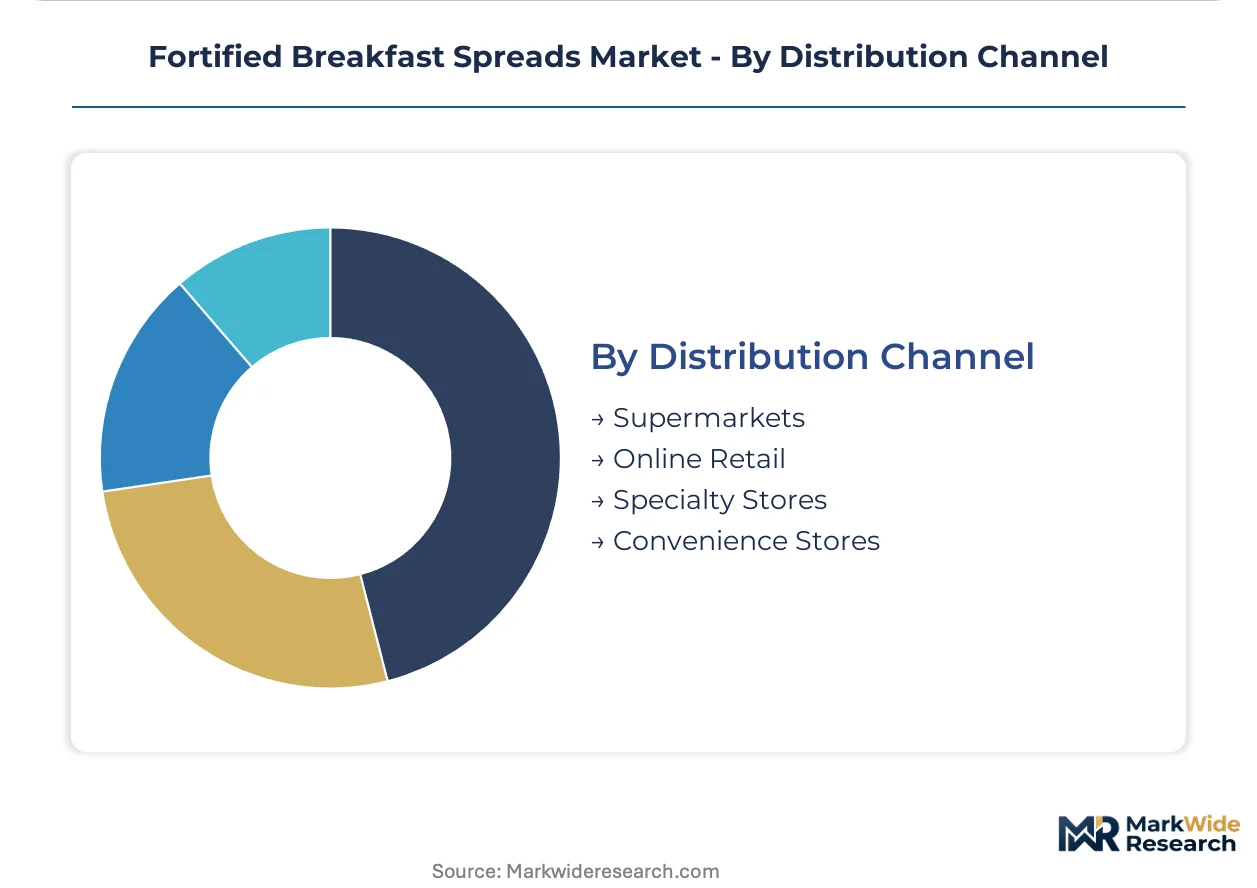
Distribution Channel:
Supply concentration in supermarket end-cap placement faces erosion from direct-to-consumer subscription models capturing nutritional personalization data.
- Supermarkets:End-cap promotional placement controls bulk volume, with German networks allocating premium positioning to Nutri-Score A/B rated fortified spreads. Slotting fees and promotional calendars structure competitive access.
- Online Retail:Subscription-model startups bypass traditional retail gatekeepers while building recurring revenue and consumer preference datasets. Protein-fortified spread subscriptions capture athletic household loyalty through personalized delivery scheduling.
- Specialty Stores:Health food retailers emphasize clean-label certification and local sourcing narratives.
- Convenience Stores:Urban proximity retail stocks single-serve pods for immediate consumption occasions.
Supermarkets anchor the volume base while online retail climbs the fastest through subscription-model customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites continental distribution for fortified spread manufacturers supplying northern European retail networks. This logistics backbone enables rapid shelf replenishment across Aldi and Lidl supply chains.
Germany
Private-label fortified spreads command expanding shelf space across Aldi and Lidl networks, with Nutri-Score A/B ratings driving procurement specifications. The EU Green Deal mandates carbon footprint disclosures for imported nut butter suppliers. Bavarian processing plants pilot ammonia-based cooling systems to maintain emulsion stability for probiotic-fortified formulations.
United States
Sports nutrition migration into breakfast occasions accelerates protein-fortified spread adoption among athletic households. FDA nutrient content claims and fortification ceilings structure permissible health messaging on packaging. Greater Chicago's food manufacturing corridor hosts precision pasteurization facilities preserving heat-sensitive micronutrients in vitamin-enriched formulations.
France
Single-serve fortified spread pods displace traditional jar formats in Paris and Lyon metropolitan markets due to refrigerator space constraints. EFSA health claim authorizations determine permissible digestive wellness positioning for fiber-fortified products. The Île-de-France region concentrates clean-label emulsifier R&D facilities developing sunflower lecithin alternatives.
India
Urban millennial households drive demand for protein-enriched spreads as daily nutrition routines shift in Mumbai and Bangalore. FSSAI tightened micronutrient premix standards for imported fortified spreads, creating compliance friction for multinational entrants. Gujarat's food processing special economic zones attract domestic manufacturers seeking to bypass import bottlenecks.
United Kingdom
Subscription-model startups capture nutritional personalization data through recurring delivery platforms bypassing supermarket slotting fees. REACH chemical safety assessments reshape industrial refrigeration dependencies in spread manufacturing facilities. The Midlands region hosts retrofitting specialists upgrading legacy thermal processing lines for higher-protein formulations.
Fortified Breakfast Spreads Market Vendor Landscape
Listed leaders compete with private specialists across price-tier and channel access dimensions in the fortified breakfast spreads sector. The vendor base fragments across multinational conglomerates, regional private-label suppliers, and direct-to-consumer subscription startups. Three archetypes dominate: heritage nutrition brands leveraging pediatric credibility, retail-private-label operators optimizing Nutri-Score positioning, and sports-nutrition crossover specialists targeting athletic households. Capacity expansion and clean-label formulation partnerships constitute the dominant competitive moves reshaping supply relationships.
Within the heritage nutrition tier, Nestlé S.A. and Unilever Plc exemplify multinational scale advantages in fortified spread positioning. The J.M. Smucker Company occupies a specialist position in nut butter fortification. These three entities represent divergent strategic anchors—Nestlé through pediatric nutrition heritage, Unilever through dual-branding across premium and everyday tiers, and J.M. Smucker through aggressive protein and omega positioning in nut butter segments.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever Plc. |
| Ferrero Group |
| The Kraft Heinz Company |
| The J.M. Smucker Company |
| Conagra Brands Inc. |
| The Hershey Company |
| Andros SAS |
| Premier Foods Plc |
| Others |
Supply Flow & Price Mechanics
Sunflower and rapeseed lecithin substitution for synthetic emulsifiers is redrawing procurement geography toward Eastern European oilseed processors while inflating clean-label input costs by fifteen to twenty-five percent against legacy formulations. This ingredient transition simultaneously compresses mid-tier brand margins and rewards premium positioning that can absorb certification premiums.
Pricing Analysis
Volume-discount tiering separates subscription-model direct-to-consumer brands from supermarket slotting-fee structures. Price differentiation hinges on Nutri-Score certification grade and organic sourcing credentials. Pricing pressure intensifies in private-label nut butters as Aldi and Lidl networks compress branded shelf space. Household buyers in German discount channels exhibit highest price sensitivity; athletic households purchasing protein-fortified subscriptions show lowest sensitivity due to personalization premiums.
Supply Chain Analysis
Inventory lead times for clean-label emulsifiers have extended from six to ten weeks as qualified sunflower lecithin suppliers concentrate in Ukraine, Bulgaria, and Argentina. Raw material dependencies include palm oil from Indonesia and Malaysia, cocoa butter from Côte d'Ivoire and Ghana, and pea protein isolates from Canada and France. Tariff exposure on Southeast Asian tropical oils constitutes the primary structural risk. Distribution runs through Rotterdam cold-chain hubs for European retail replenishment and Chicago-area precision pasteurization facilities for North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through front-of-pack labeling mandates creates sticky formulation standards that favor incumbents with compliance infrastructure already deployed.
For Market Incumbents: Shield market position by accelerating ammonia-based cooling system retrofits in German and Dutch processing plants before EU F-Gas Regulation phase-down deadlines tighten. Deepen upstream control over sunflower lecithin supply through offtake agreements with Bulgarian and Ukrainian oilseed processors to preempt clean-label emulsifier scarcity. This counters private-label substitution pressure from Aldi and Lidl networks.
For New Entrants and Emerging Players: Anchor in subscription-model direct-to-consumer channels where nutritional personalization data builds recurring revenue without supermarket slotting fee barriers. Target athletic households in US metropolitan markets with protein-fortified positioning that migrates sports nutrition logic into breakfast occasions. Launch through personalized delivery scheduling platforms that bypass retail gatekeeper concentration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clean-label formulation specialists with proprietary microencapsulation capabilities. Long-term viability over the next decade hinges on bioactive stability certification infrastructure that extends product development cycles but creates durable competitive separation. Watch FSSAI micronutrient premix standard evolution as the inflection signal for India market access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Emulsifier Backward Integration | Sunflower lecithin offtake agreements with Bulgarian processors secure supply against synthetic replacement scarcity. |
| Ammonia-Based Cooling Retrofit | German and Dutch facilities maintain probiotic-fortified emulsion stability under EU F-Gas phase-down schedules. |
| Subscription-Model Direct Launch | Recurring delivery platforms capture athletic household loyalty while bypassing Aldi and Lidl slotting fees. |
| Nutri-Score A/B Certification Investment | Private-label spreads in German discount networks command end-cap positioning through front-of-pack rating compliance. |
| Microencapsulation Technology Licensing | Spray-dried lipid shell systems mask off-flavors in omega-fortified nut butters for premium tier differentiation. |
Methodological Framework
A spread of perspectives from brand managers at multinational nutrition companies, category buyers at German discount retail networks, supply planners at nut butter processors, and regulatory affairs specialists at EFSA and FDA converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs records, Nielsen retail audit data, SEC 10-K filings, and EU Green Deal implementation documents. Bottom-up volume triangulation across product type, ingredient composition, and distribution channel dimensions was cross-checked against top-down macroeconomic elasticity assumptions.
Segmentation dimensions modeled include product type hierarchy, fortification intensity tier, clean-label certification status, and regional regulatory cluster variations across the analysis window. CAGRs were derived from elasticity-adjusted consumption trend extrapolation. Forecast inputs incorporated sports nutrition end-use migration rates, private-label shelf space allocation shifts in German retail, and FSSAI compliance timeline assumptions for India market entry.
Decision-makers should treat outputs as directional under base assumptions of sustained EU labeling mandate enforcement and stable tropical oil trade flows; material deviation in palm oil tariff regimes or front-of-pack scoring algorithm revisions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Essential Micronutrients Market