
 Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market | 2026-2036
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market Analytics
Multi-source procurement is restructuring how institutional buyers secure therapeutic food supplies. GC Rieber Compact AS anchors European manufacturing capacity for compressed nutrient bars. Valid Nutrition specializes in plant-based RUSF formulations that bypass peanut supply constraints. Edesia leverages US-based production to sustain rapid-response contracts with UNICEF and USAID.
Ready-to-use therapeutic food and supplementary food are lipid-based pastes or compressed bars delivering energy, protein, and micronutrients in shelf-stable formats requiring no cooking or water. Peanut-based formulations dominate RUTF production due to caloric density, palatability, and established supply chains. Distribution channel dynamics reveal hospitals capturing the highest-margin procurement contracts, while online platforms represent the fastest-growing access point for supplementary food in middle-income settings. End-user segmentation shows children under five constituting the core demand pool, with pregnant women emerging as a high-priority expansion segment for RUSF programs.
WHO guidelines, Codex Alimentarius standards, and national food safety regulators in producing countries collectively determine product composition, packaging claims, and import eligibility. These frameworks elevate barriers for new entrants while rewarding manufacturers with pre-qualified supplier status. Stakeholders must monitor evolving procurement shifts toward local production mandates and plant-based formulation requirements.
Market Dynamics
Humanitarian procurement agencies are consolidating supplier rosters around pre-qualified manufacturers with demonstrated rapid-response capacity, compressing margins for second-tier producers while rewarding integrated players with multi-year framework agreements.
Growth Catalysts
- Community-based Management of Acute Malnutrition (CMAM):Ethiopia's government-led CMAM programs anchor regional supply commitments and create predictable demand pipelines for RUTF manufacturers.
- WHO Guideline Updates:Revised WHO guidelines for severe acute malnutrition treatment expand eligibility criteria and increase per-patient product volumes in emergency nutrition programs.
- Peanut Supply Chain Maturation:Established agricultural processing infrastructure in West Africa reduces raw material volatility for lipid-based paste formulations.
Market Restraints
- Input Cost Volatility:Vegetable oil and milk powder prices fluctuate with commodity markets, compressing formulation margins for producers without backward integration into ingredient sourcing.
- Supply Concentration Risk:Three European manufacturers control compressed bar production capacity, creating bottleneck vulnerability for UNICEF emergency stockpiling requirements.
- Codex Alimentarius Compliance Burden:Harmonized micronutrient specifications require reformulation investments that disadvantage smaller producers without dedicated regulatory affairs functions.
Strategic Opportunities
- Local Production Mandates:Ethiopia's industrialization policies incentivize domestic RUTF manufacturing through tax holidays and import substitution frameworks.
- Plant-based Formulation Expansion:Chickpea and soybean protein isolates enable RUSF products that bypass peanut allergen concerns and aflatoxin testing requirements.
- Direct-to-Consumer Digital Channels:E-commerce platforms in Kenya and Nigeria connect supplementary food products to middle-income households outside formal aid distribution networks.
Industry Challenges
- Specialized Formulation Expertise Gap:Food technologists with lipid-based nutrient paste experience command premium compensation, constraining R&D expansion at mid-size manufacturers.
- Pre-qualification Timeline Compression:UNICEF supplier assessment cycles extend 18-24 months, delaying market entry for new entrants with innovative formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market |
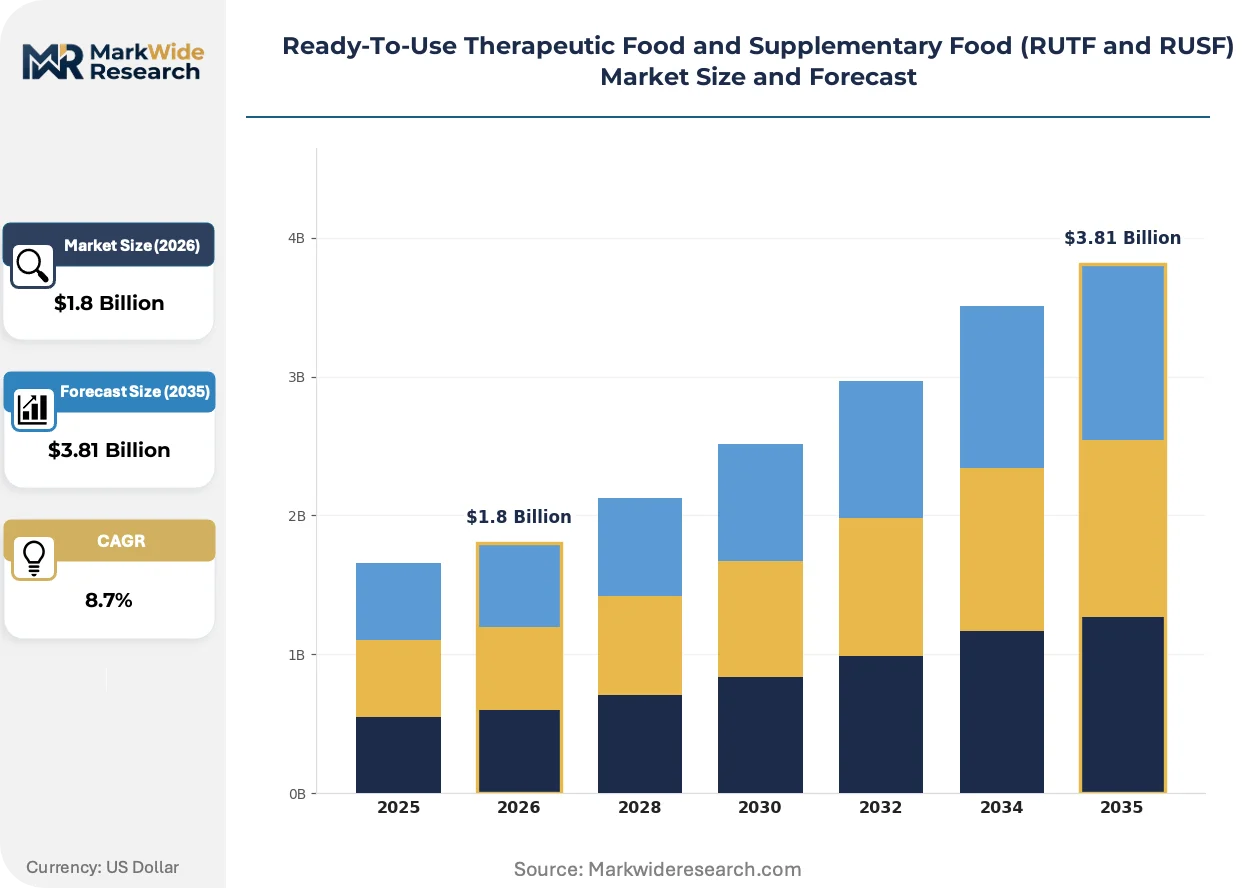
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peanut-Based, Milk-Based, Cereal-Based, Legume-Based Distribution Channel: Pharmacies, Hospitals, Retail Stores, Online Platforms End User: Children, Pregnant Women, Elderly, Malnourished Adults Packaging Type: Packets, Tetra Packs, Cans, Jars |
| Companies Covered | Nuflower Foods, GC Rieber Compact AS, Valid Nutrition, Edesia, Nutrivita Foods, InnoFaso, Diva Nutritional Products, Insta Products, Meds & Food for Kids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market Evolving Landscape
Formulation science and procurement digitization are converging to reshape how therapeutic foods reach end-users, with shelf-life extension technologies and local production incentives driving competitive differentiation among suppliers.
Novel lipid encapsulation systems are electrifying micronutrient stability in tropical storage conditions. UNICEF and USAID procurement officers prioritize suppliers with demonstrated 24-month shelf-life validation under 30°C/75% humidity protocols. This capability compression is marginalizing manufacturers dependent on cold-chain distribution infrastructure.
REACH regulation amendments in the European Union tighten packaging material compliance requirements for imported food aid shipments. Manufacturers must now document full chemical substance inventories for laminated foil sachets and outer cartons. Suppliers with EU-based conversion operations hold structural advantage over those reliant on Asian packaging subcontractors.
Hospital procurement officers in Kenya and Uganda are consolidating annual RUSF purchases through centralized e-procurement platforms that transparently benchmark unit pricing across pre-qualified vendors. This aggregation behavior displaces fragmented spot-buying patterns and compresses price dispersion between premium and standard formulation tiers.
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market Segmentation
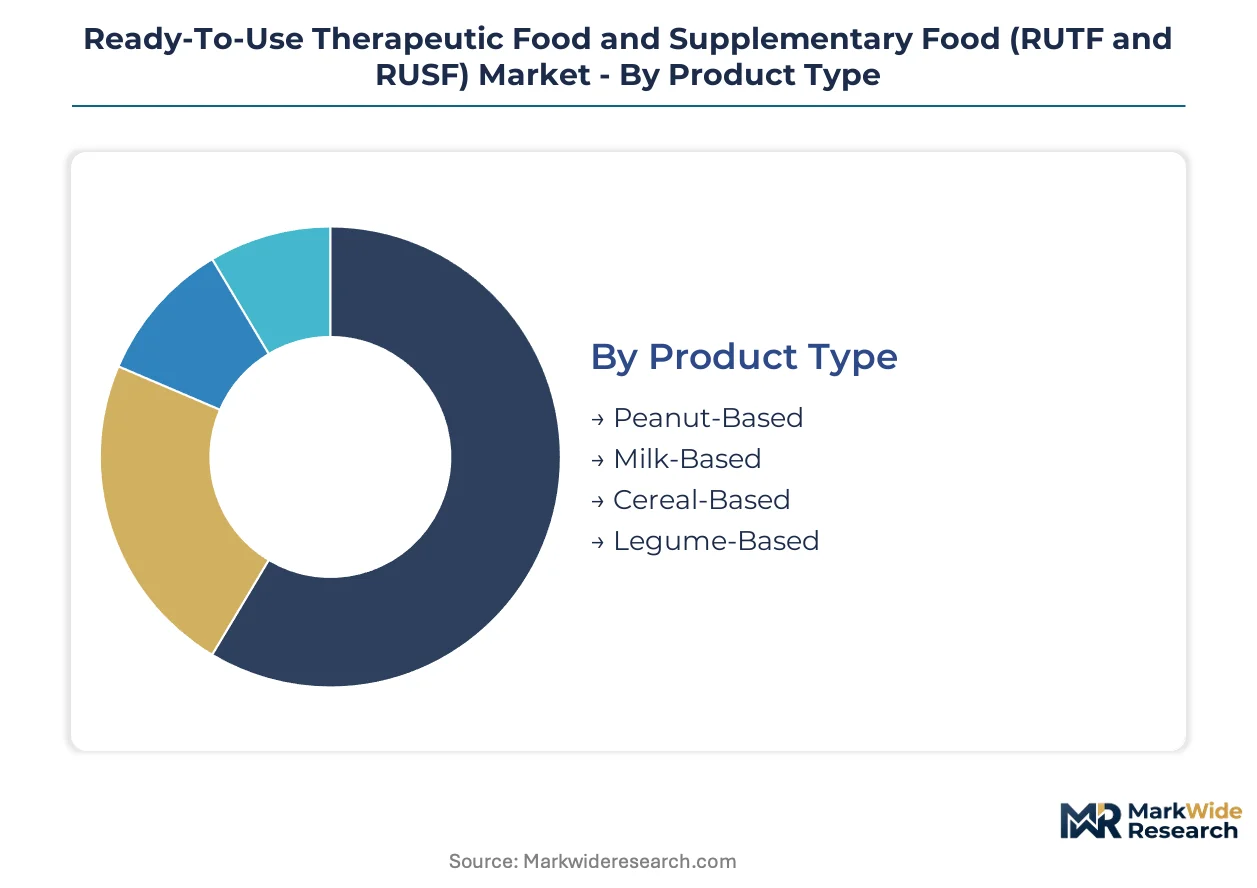
RUTF and RUSF procurement flows through distinct technical and commercial channels that reshape supplier priorities. Product formulation determines manufacturing investment requirements, while distribution channel selection locks in margin structures and regulatory compliance burdens.
Product Type:
Peanut-based formulations command the highest procurement volumes, yet plant-based alternatives are capturing premium positioning as allergen concerns reshape specifications.
- Peanut-Based:Lipid-dense pastes combining roasted peanuts, vegetable oil, milk powder, and micronutrient premixes deliver caloric concentration exceeding 500 kcal per 100g. UNICEF emergency stockpiles in Ethiopia and South Sudan anchor demand for this format, though aflatoxin testing requirements lengthen quality assurance cycles.
- Milk-Based:Spray-dried whey and skim milk formulations target moderate acute malnutrition protocols where protein bioavailability takes precedence over energy density. Kenya's Ministry of Health prioritizes these products for urban hospital-based CMAM programs, creating procurement concentration in Nairobi and Mombasa distribution hubs.
- Cereal-Based:Extruded grain flours blended with oil and fortificants serve supplementary feeding contexts where cost minimization outweighs therapeutic intensity.
- Legume-Based:Chickpea and soybean isolates bypass peanut supply constraints while meeting WHO protein specifications.
Mature deployment sits with Peanut-Based formulations. Newer deployment is concentrated in Legume-Based alternatives.
Distribution Channel:
Institutional procurement concentrates volume, yet digital channels are restructuring how middle-income households access supplementary nutrition products.
- Hospitals:Inpatient CMAM programs and stabilization centers generate the highest-margin procurement contracts through centralized tender processes. Uganda's Mulago National Referral Hospital and Kenyatta National Hospital in Kenya anchor East African demand, with framework agreements spanning 24-36 month cycles.
- Online Platforms:E-commerce penetration in Lagos, Nairobi, and Accra connects RUSF products to direct-to-consumer demand outside formal aid networks. Jumia and local pharmacy aggregators are expanding same-day delivery coverage for supplementary foods targeting pregnant women and elderly populations.
- Pharmacies:Community retail networks handle outpatient therapeutic program dispensing with prescription-linked inventory management.
- Retail Stores:Supermarket chains in urban Nigeria and Kenya stock RUSF products for preventive nutrition purchase.
Procurement gravity centers on Hospitals for therapeutic applications. Online Platforms represent the fastest-growing access trajectory for supplementary nutrition.
End User:
Demographic targeting determines formulation micronutrient profiles and packaging specifications across the product portfolio.
- Children:Under-five populations with severe acute malnutrition drive RUTF volume through ready-to-eat paste formats optimized for appetite stimulation and rapid weight gain. Ethiopia's national CMAM scale-up targets this segment exclusively, with community health workers conducting household screening in Amhara and Oromia regions.
- Pregnant Women:RUSF expansion into antenatal care protocols creates demand for iron-folate enriched products with reduced sodium content. Nigeria's primary health centers in Kano and Kaduna states are piloting integrated maternal nutrition programs.
- Elderly:Texture-modified formulations address chewing difficulties in aging populations with micronutrient deficiencies.
- Malnourished Adults:HIV and tuberculosis co-morbidity programs in Malawi and Zambia generate specialized procurement for adult therapeutic feeding.
Programmatic investment concentrates on Children. Emerging deployment is accelerating in Pregnant Women segments.
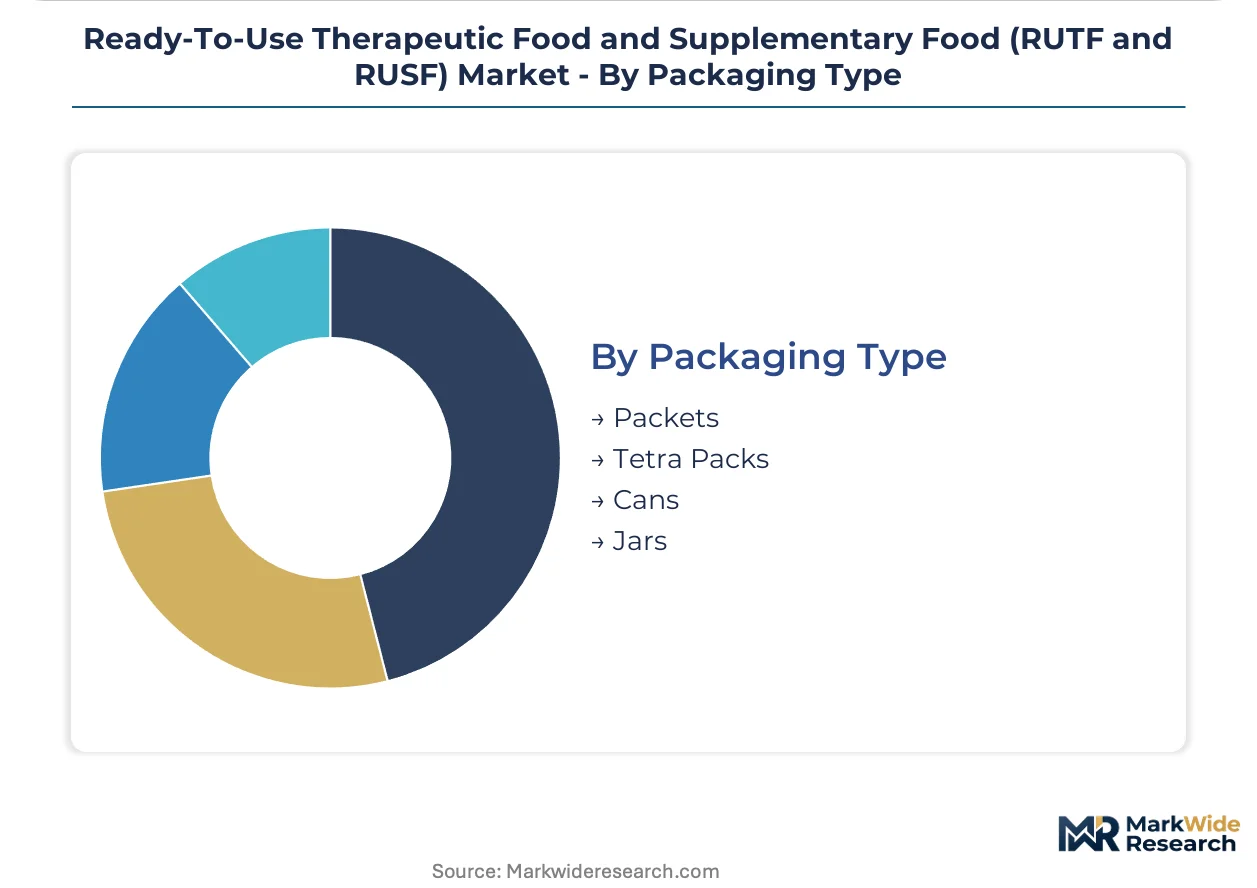
Packaging Type:
Shelf-life requirements and field distribution logistics dictate material selection across humanitarian and commercial supply chains.
- Packets:Multi-layer aluminum foil sachets with nitrogen flushing achieve 24-month stability at tropical humidity levels. REACH-compliant laminates from EU converters satisfy UNICEF's chemical substance documentation requirements for shipments into the Horn of Africa.
- Tetra Packs:Aseptic carton formats enable ready-to-drink RUSF liquid products for hospital and clinic dispensing in Kenya's urban centers.
- Cans:Metal containers serve institutional bulk procurement for camp-based feeding programs.
- Jars:Plastic and glass formats target retail shelf presence in Nigerian supermarkets.
Humanitarian procurement relies on Packets. Commercial channel expansion is concentrating in Tetra Packs for liquid supplementary formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peanut cultivation belts in West Africa and East African CMAM scale-up programs anchor therapeutic food procurement geography. Manufacturing capacity clusters near humanitarian logistics hubs in Ethiopia, Kenya, and South Sudan. Regional supply commitments harden around government-led nutrition programs and UNICEF pre-qualified supplier networks.
Ethiopia
Government-led CMAM programs in Amhara and Oromia regions generate predictable RUTF demand through community health worker screening networks. The Ethiopian Food and Drug Authority enforces WHO-aligned micronutrient specifications for imported therapeutic foods. Industrial parks in Hawassa and Bole Lemi host emerging local production facilities seeking import substitution benefits.
Kenya
Urban hospital-based CMAM programs in Nairobi and Mombasa concentrate high-margin procurement for milk-based formulations. Kenya Bureau of Standards mandates aflatoxin testing protocols for peanut-derived imports entering through Mombasa port. Kenyatta National Hospital anchors East African demand through 24-36 month framework agreements with pre-qualified suppliers.
Nigeria
Integrated maternal nutrition pilots in Kano and Kaduna states expand RUSF deployment for pregnant women through primary health centers. The National Agency for Food and Drug Administration and Control regulates iron-folate enrichment claims on supplementary food packaging. Lagos-based e-commerce platforms connect direct-to-consumer demand outside formal aid distribution channels.
United States
Rapid-response contracts with USAID and UNICEF sustain production capacity for emergency stockpiling requirements. FDA facility registration and FSMA compliance prerequisites filter supplier eligibility for federal procurement programs. Rhode Island-based manufacturing clusters leverage coastal logistics for Horn of Africa shipment consolidation.
India
Domestic RUSF formulation development targets moderate acute malnutrition protocols in Bihar and Uttar Pradesh. Food Safety and Standards Authority of India certification requirements govern micronutrient premix importation and local blending operations. Gujarat-based agricultural processing infrastructure supplies refined vegetable oils to regional therapeutic food manufacturers.
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and formulation specialization. The supplier base stratifies between integrated European manufacturers with compressed bar capacity and emerging local producers in East Africa. Three archetypes dominate: WHO-pre-qualified humanitarian suppliers, plant-based formulation specialists, and government-contract domestic manufacturers. Competitive moves concentrate on local production licensing and plant-based R&D partnerships.
Within the pre-qualified humanitarian tier, GC Rieber Compact AS and Edesia exemplify rapid-response capacity archetypes. Valid Nutrition occupies a position as a plant-based formulation specialist bypassing peanut supply constraints. Nuflower Foods and Nutrivita Foods represent emerging regional champions targeting local production mandates in East African markets.
| Leading Market Players |
|---|
| Nuflower Foods |
| GC Rieber Compact AS |
| Valid Nutrition |
| Edesia |
| Nutrivita Foods |
| InnoFaso |
| Diva Nutritional Products |
| Insta Products |
| Meds & Food for Kids |
| Others |
Value Network & Pricing Analysis
UNICEF pre-qualified suppliers command premium pricing power through multi-year framework agreements that bundle emergency response capacity with product certification. This buyer concentration compresses margins for second-tier producers while rewarding integrated manufacturers with demonstrated rapid-response logistics.
Pricing Analysis
Warranty and shelf-life validation services are unbundled from base product pricing, with 24-month tropical stability testing offered as a premium add-on. Three-tier pricing structure across premium, standard, and economy levels separates WHO-pre-qualified formulations from national-standard and unbranded alternatives. Price differentiation hinges on Codex Alimentarius compliance tier and backward integration into peanut oil processing. Cost compression in economy-tier RUSF is intensifying because Ethiopian import substitution policies favor domestic blenders. Government procurement officers show highest price sensitivity, while hospital CMAM programs prioritize certification over unit cost.
Supply Chain Analysis
Peanut oil supply rests on West African agricultural processing infrastructure in Senegal, Ghana, and Nigeria. Milk powder inputs draw from European Union dairy cooperatives and New Zealand commodity traders. Single-source vulnerability concentrates in laminated foil sachet conversion, where REACH-compliant EU converters dominate UNICEF documentation requirements. Distribution runs through Mombasa and Djibouti port consolidation hubs before last-mile deployment via community health worker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Codex Alimentarius micronutrient specifications function as a cost-of-compliance moat, filtering out smaller blenders lacking dedicated regulatory affairs capacity while securing multi-year contracts for pre-qualified incumbents.
For Market Incumbents: Anticipate local production mandate acceleration in Ethiopia and Kenya by licensing formulation technology to emerging domestic manufacturers. Secure backward integration into West African peanut oil crushing capacity before commodity traders consolidate origination control. Codex reformulation cycles threaten margin stability for producers without in-house premix blending operations.
For New Entrants and Emerging Players: Begin with plant-based RUSF formulations targeting Nigerian maternal nutrition pilots in Kano and Kaduna states, where peanut allergen concerns create specification white space. Direct-to-consumer e-commerce channels in Lagos and Nairobi offer the most penetrable access trajectory outside UNICEF procurement concentration. Partner with local pharmacy aggregators for same-day delivery infrastructure rather than building captive distribution.
For Investors and Strategic Acquirers: The window for entry favors plant-based formulation specialists with validated chickpea protein isolates and existing FSSAI or EFDA regulatory dossiers. Acquisition targets should demonstrate 18-24 month pre-qualification pathway progress with documented micronutrient stability data. Watch for UNICEF supplier roster expansion announcements as the inflection signal for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Production Licensing | Ethiopian industrial park tax holidays reduce landed cost versus European imports. |
| Plant-Based Formulation R&D | Chickpea isolates bypass aflatoxin testing cycles that delay peanut-based shipments. |
| Pre-Qualification Fast-Track | WHO pre-qualified status unlocks multi-year UNICEF framework agreement eligibility. |
| Backward Integration into Oil Crushing | Senegal peanut processing capacity secures caloric density consistency for RUTF paste. |
| E-Commerce Channel Partnership | Jumia pharmacy aggregator integration reaches pregnant women outside CMAM networks. |
Research Methodology
Independent corroboration across UNICEF procurement officers, Ethiopian Food and Drug Authority inspectors, and Kenyan hospital pharmacy directors underwrites the qualitative findings. Primary interviews with RUTF manufacturing plant managers, West African peanut oil processors, and laminated packaging converters were validated against secondary sources including Codex Alimentarius micronutrient standards, USAID commodity procurement databases, and FAO agricultural trade statistics. Bottom-up demand modeling from CMAM program enrollment data triangulates with top-down therapeutic food production capacity estimates.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include product formulation type, distribution channel, end-user demographic, and packaging format. CAGRs were derived from government nutrition program budget trajectories and humanitarian emergency response funding patterns. Peanut oil commodity price volatility and REACH packaging compliance amendment timelines fed directly into scenario-weighted outputs.
Underlying measurement precision varies by segment; hospital procurement contract values carry tighter precision than direct-to-consumer e-commerce estimates. Forecasts reflect documented assumptions regarding CMAM scale-up commitments and Codex specification stability. Aflatoxin testing protocol changes or Ethiopian import tariff adjustments could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Liquid Vitamins Market