
 Vitamin a in Feed Additives Market | 2026-2036
Vitamin a in Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin a in Feed Additives Market Insights
Pharmaceutical-grade retinyl ester specifications is bifurcating the competitive landscape into premium and commodity tiers. BASF SE leverages its integrated chemical synthesis platform to sustain cost advantages in acetate production. DSM-Firmenich anchors its position through microencapsulation technology leadership that protects vitamin A stability during pelleting. Adisseo competes aggressively in premix formulations tailored to tropical climate conditions where heat degradation accelerates.
Vitamin A in feed additives denotes retinoid compounds—principally retinyl acetate and retinyl palmitate—synthesized through β-ionone cyclization and formulated at international units ranging from 500,000 to 2,500,000 IU per gram for livestock supplementation. These compounds prevent hypovitaminosis A, support epithelial integrity, and optimize feed conversion ratios across monogastric and ruminant systems. Poultry applications dominate volume throughput due to intensive broiler and layer operations requiring precise growth promotion dosing. Aquaculture represents the fastest-expanding animal type as salmonid and shrimp producers escalate micronutrient fortification to replace fishmeal dependency. Liquid premix forms command premium positioning in automated dosing systems, while powder variants retain cost-sensitive swine and ruminant contracts.
EU EFSA maximum residue limits and FDA feed ingredient approvals govern cross-border product registration and formulation ceilings. China's MEE environmental discharge standards and SAMR feed additive catalog revisions reshape manufacturing location decisions for multinational suppliers. India BIS feed-grade vitamin specifications and CDSCO import clearance protocols create layered compliance requirements for entrants. Stakeholders must monitor evolving national positive lists for feed additives and assess backward integration into β-ionone precursor supply as a strategic hedge against raw material volatility.
Market Dynamics
EU REACH compliance and F-Gas Regulation revisions are forcing feed-grade vitamin A manufacturers to reconfigure synthesis pathways and reformulate premix stability profiles, tightening specifications while Brazil's integrated broiler sector concentrates demand in tropical climate zones.
Growth Catalysts
- Commercial poultry intensification:Large-scale broiler and layer operations in Brazil and Southeast Asia require precise micronutrient dosing to optimize feed conversion ratios and epithelial health in high-density housing systems.
- Aquaculture feed fortification mandates:Salmonid and shrimp producers are escalating vitamin A inclusion to replace fishmeal dependency, creating new volume throughput as aquaculture expands faster than terrestrial livestock sectors.
- β-ionone synthesis advances:Improved cyclization chemistry and precursor availability are lowering production costs for retinyl acetate and retinyl palmitate, expanding accessible supply for cost-sensitive swine and ruminant formulators.
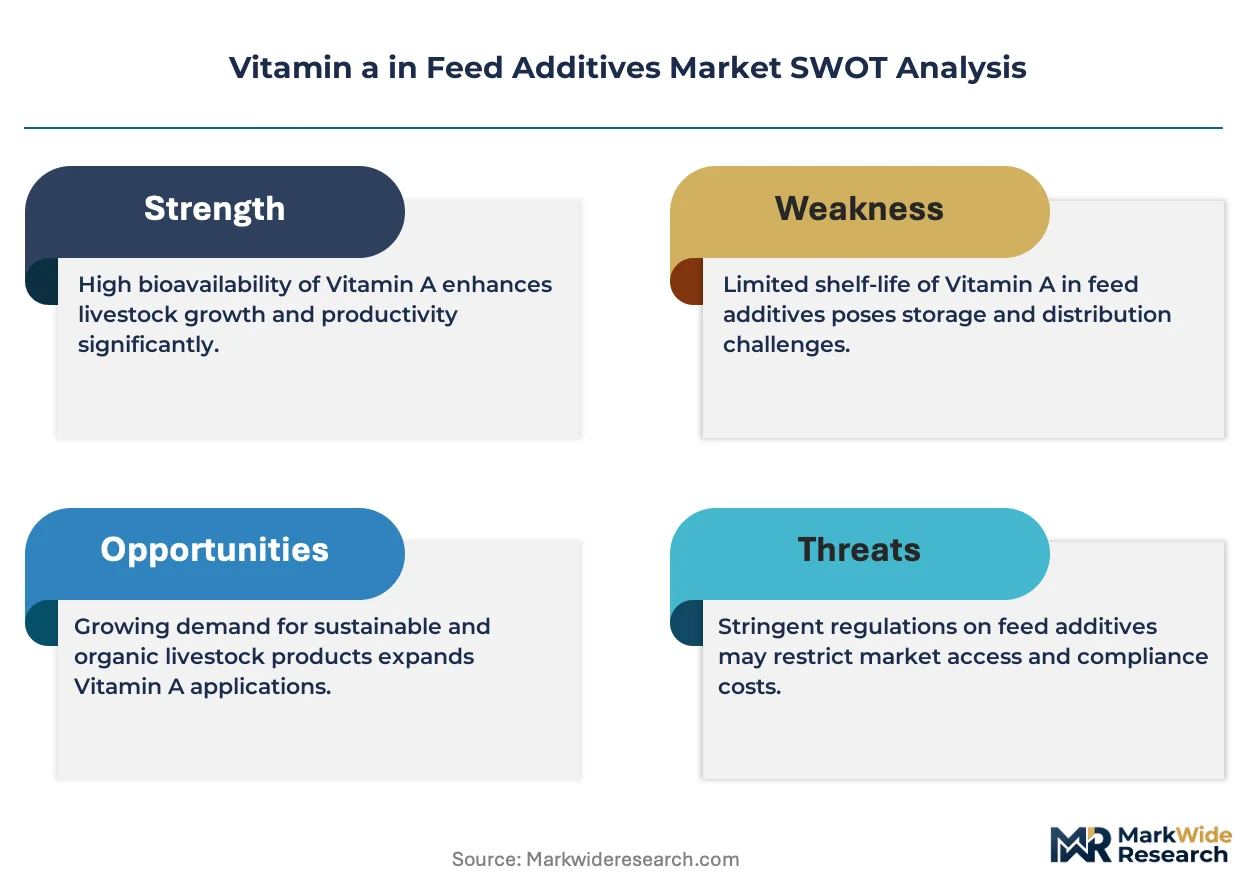
Market Restraints
- Raw material volatility:β-ionone precursor supply concentrates in limited chemical synthesis clusters, exposing manufacturers to price swings in petrochemical feedstocks and citral derivatives.
- EU regulatory friction:EFSA maximum residue limits and REACH substance registration requirements create layered compliance costs and formulation ceilings that disadvantage smaller premix suppliers.
- Heat degradation limitations:Retinyl ester stability during high-temperature pelleting remains technically constrained, requiring expensive microencapsulation or limiting geographic deployment in tropical processing environments.
Strategic Opportunities
- Automated dosing systems:Liquid premix formats command premium positioning in integrated operations with precision feed delivery infrastructure, displacing manual powder handling in advanced poultry facilities.
- India feed additive expansion:BIS feed-grade specifications and SAMR-aligned catalog revisions are opening formal channels for multinational suppliers to serve India's consolidating dairy and poultry sectors.
- Environmental discharge incentives:China's MEE standards and dual carbon goals are rewarding manufacturers with closed-loop β-ionone production and reduced solvent waste profiles.
Industry Challenges
- Microencapsulation talent scarcity:Formulation chemists with expertise in lipid-shell stability engineering and tropical degradation modeling command premium compensation, constraining R&D expansion at mid-tier suppliers.
- Multi-jurisdiction registration timelines:Simultaneous FDA feed ingredient approvals, EU EFSA evaluations, and CDSCO import clearances create 18-36 month product launch cycles that tie up working capital.
- Legacy premix integration:Automated dosing infrastructure requires retrofitting or replacement of existing powder-handling systems, creating friction in customer conversion to higher-margin liquid formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin a in Feed Additives Market |
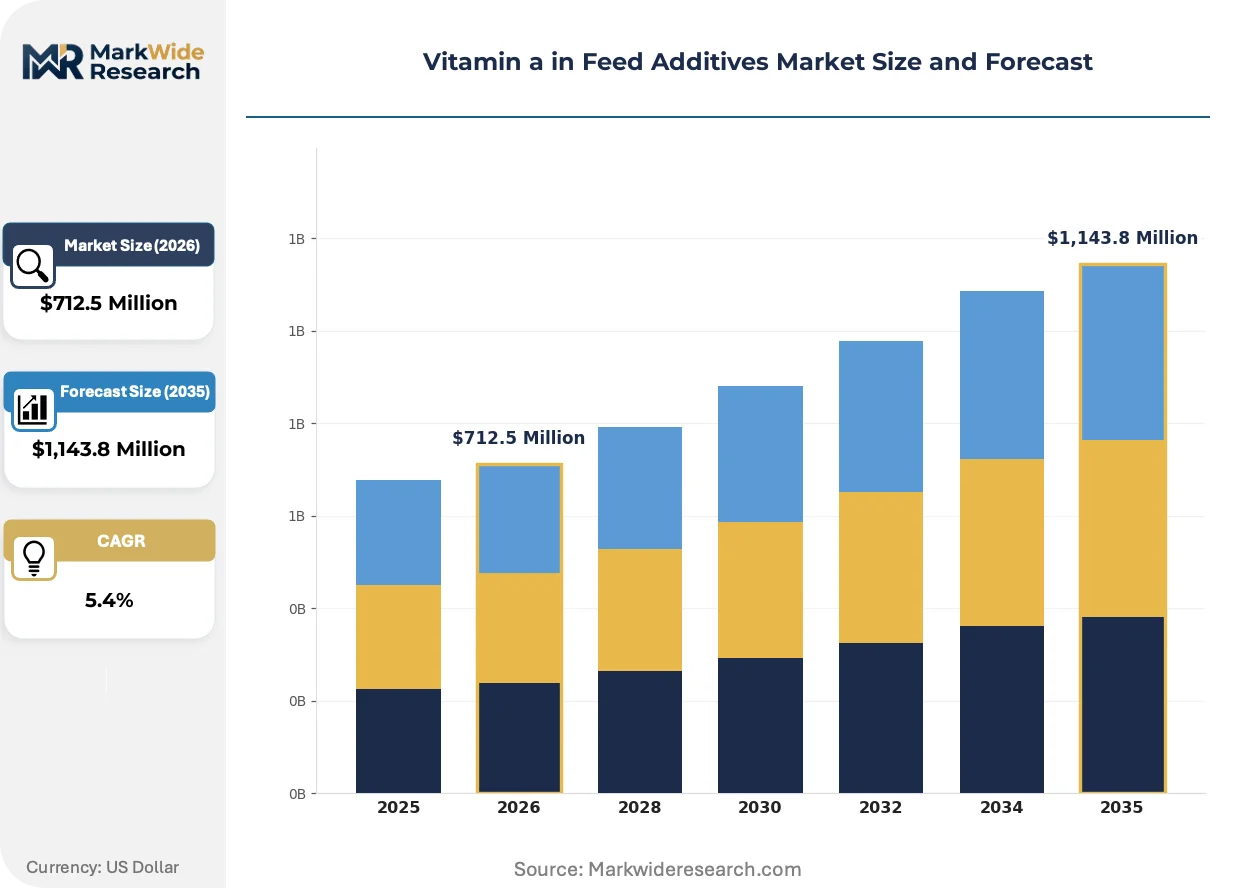
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,143.8 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin A Palmitate, Vitamin A Acetate, Beta-Carotene, Retinyl Acetate Animal Type: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Premix Function: Growth Promotion, Reproduction, Immune Function, Vision |
| Companies Covered | Cargill, Incorporated, ADM, BASF SE, DSM-Firmenich, Evonik Industries AG, Adisseo, Kemin Industries, Inc., Alltech, Ajinomoto Health & Nutrition North America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin a in Feed Additives Market Trends and Innovations
Microencapsulation technology and automated feed delivery systems are reshaping how vitamin A reaches livestock, with stability engineering and precision dosing converging to displace conventional powder premixes in advanced operations.
Cold-water dispersible lipid-shell microspheres is supplanting standard spray-dried beadlet formulations in high-performance poultry and aquaculture feeds. Salmonid producers in Norway and Chile are adopting these formats at accelerating rates to prevent vitamin A degradation during extrusion. This technology is supplanting commodity-grade powder variants in premium contract segments while compressing margins for undifferentiated suppliers.
EU F-Gas Regulation revisions and REACH substance restriction proposals are tightening feed additive manufacturing emissions standards and solvent recovery requirements. Chemical synthesis operations face capital-intensive abatement retrofits or relocation decisions. Vitamin A acetate producers with integrated European facilities are most affected, accelerating backward integration into precursor supply or shifting production to jurisdictions with transitional environmental enforcement.
Direct procurement relationships between integrated livestock operators and vitamin A manufacturers are consolidating channel structures, displacing traditional distributor intermediaries in Brazil and Thailand. Large broiler integrators now negotiate annual volume contracts specifying IU stability guarantees and climate-conditioned delivery protocols. This pattern is most visible in Southeast Asia's expanding aquaculture feed sector, where traceability requirements and lot-specific certification are becoming standard tender conditions.
Vitamin a in Feed Additives Market Segmentation
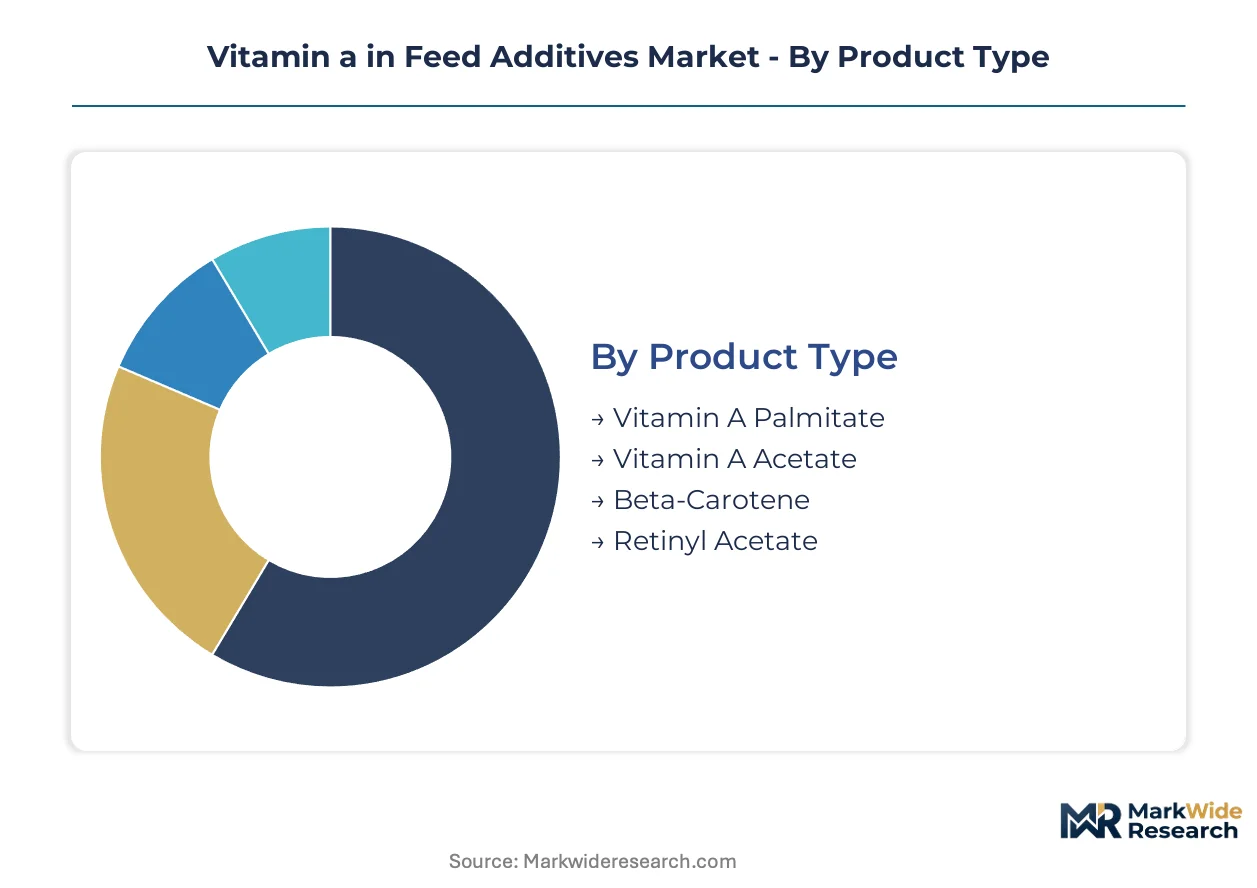
Vitamin A feed additive segmentation reveals distinct channel economics. Product type determines synthesis investment requirements. Animal type dictates formulation stability needs. Form drives automation compatibility and margin structure.
Product Type:
Channel mix varies sharply by ester chemistry. Retinyl acetate flows through high-volume poultry integrators. Retinyl palmitate serves ruminant compounders demanding heat stability. Beta-carotene commands specialty aquaculture contracts with provitamin specifications.
- Vitamin A Palmitate:Long-chain fatty acid ester synthesized from retinol and palmitic acid delivers superior thermal stability for pelleting operations above 85°C. Brazilian broiler integrators specify palmitate for tropical climate distribution where warehouse temperatures exceed standard storage conditions. By volume, palmitate leads. By growth pace, beta-carotene is ahead.
- Vitamin A Acetate:Shorter-chain ester offers higher IU concentration per gram and faster intestinal absorption kinetics in monogastric systems. Southeast Asian layer operations favor acetate for precision dosing in automated systems where bioavailability per unit cost drives procurement decisions.
- Beta-Carotene:Provitamin A carotenoid extracted from algae or fermented Blakeslea trispora serves salmonid producers requiring natural pigment deposition alongside vitamin A activity.
- Retinyl Acetate:Synthetic crystalline form specified in pharmaceutical-grade feed additives for breeding stock with elevated epithelial integrity requirements.
Acetate esters dominate volume throughput. Palmitate variants claim premium positioning in climate-stressed supply chains.
Animal Type:
Cost tier stratification separates intensive from extensive systems. Poultry operations absorb micronutrient costs within integrated margins. Ruminant applications face price pressure from forage substitution economics. Aquaculture contracts specify stability-guaranteed formats at substantial premia.
- Poultry:Broiler and layer operations account for majority volume through precisely calibrated premix inclusion rates optimizing feed conversion ratios and respiratory epithelial health in high-density housing. EU EFSA maximum residue limits and Brazil's MAPA inspection protocols govern cross-border shipment certification requirements for poultry-grade formulations.
- Aquaculture:Salmonid and shrimp producers escalate vitamin A fortification to replace fishmeal micronutrient profiles, with Norwegian and Chilean operations adopting cold-water dispersible microencapsulated formats. This segment climbs the fastest as marine ingredient prices force alternative protein adoption.
- Swine:Nursery and grower diets incorporate standard beadlet formulations with lower stability specifications than poultry, reflecting less severe pelleting temperatures.
- Ruminants:Dairy and beef operations show lowest per-head vitamin A intensity due to rumen microbial synthesis and forage provitamin content, limiting premix penetration.
Poultry maintains volume leadership. Aquaculture posts the steepest expansion trajectory.
Form:
Customer type bifurcates between automated integrators and manual compounders. Liquid formats serve precision-dosing operations with infrastructure investment capacity. Powder variants retain cost-sensitive independent feed mills. Granular and premix formats occupy intermediate positions.
- Liquid:Oil-based or emulsified concentrates designed for automated dosing systems in integrated poultry and aquaculture facilities, commanding substantial premia over dry formats. Thailand's CP Group and Brazil's JBS operate proprietary liquid dosing infrastructure displacing traditional distributor channels.
- Powder:Spray-dried beadlet formulations serving independent feed mills and smaller swine operations without liquid handling equipment, competing primarily on unit cost.
- Granular:Intermediate particle size for semi-automated batching systems in mid-tier compounders seeking flowability without full liquid conversion investment.
- Premix:Vitamin-mineral complexes blended by third-party specialists for direct farm delivery, concentrating traceability risk and quality liability with the premix manufacturer.
Powder retains volume dominance. Liquid formats gain share fastest in new-build facilities.
Function:
Application priority shapes specification intensity. Growth promotion drives standard inclusion rates. Reproduction and immune function command elevated dosing in breeding stock. Vision support remains niche in specific aquaculture and laboratory animal applications.
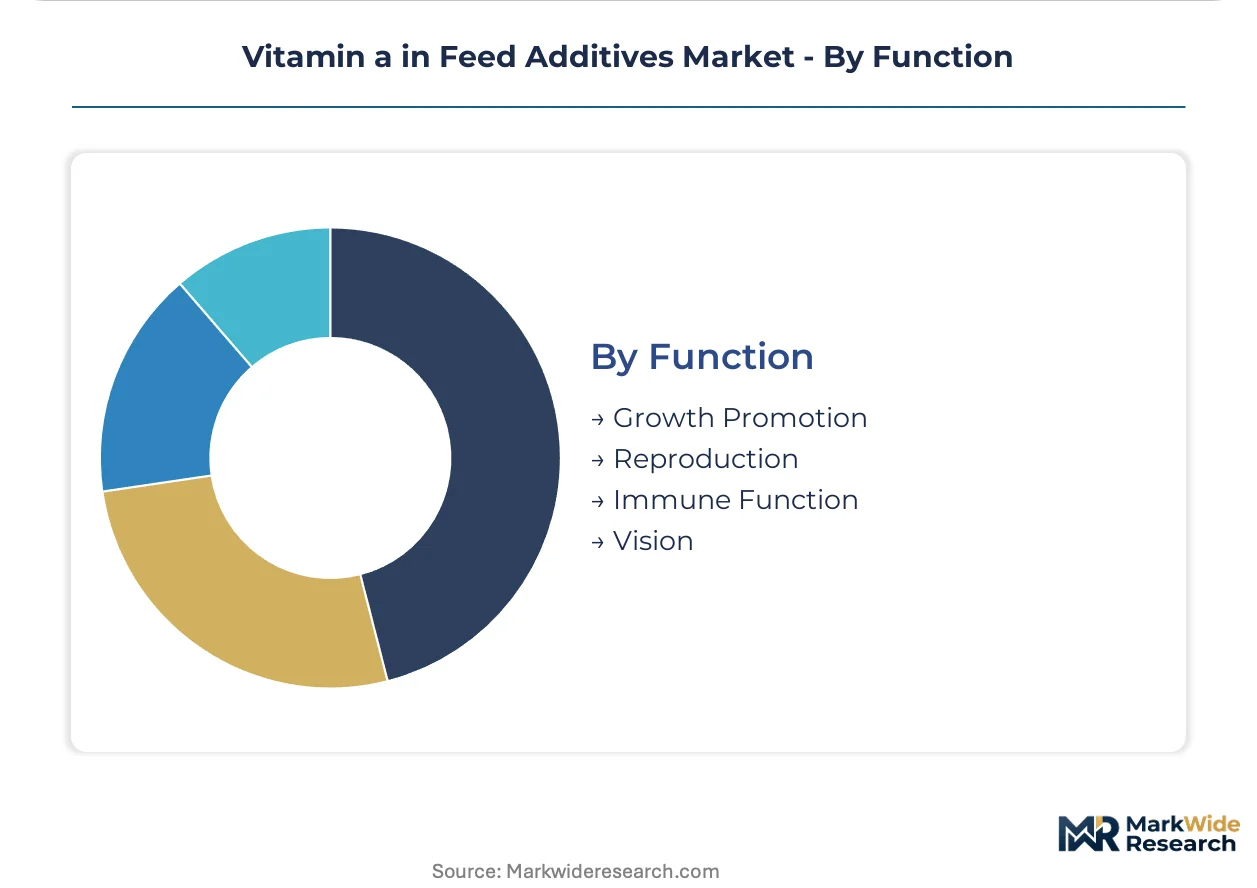
- Growth Promotion:Standard epithelial integrity and feed conversion optimization in commercial broiler and finisher swine operations, representing baseline inclusion rates across all geographic markets. China's SAMR feed additive catalog establishes minimum and maximum permitted levels for growth-promotion claims.
- Immune Function:Elevated vitamin A protocols for disease challenge periods and antibiotic-free production systems, particularly in US sow herds and EU poultry facing reduced therapeutic options.
- Reproduction:Breeding stock formulations with 2-3x standard inclusion rates for spermatogenesis and embryonic development support in purebred and grandparent operations.
- Vision:Specialized retinal health applications in laboratory primates, exotic aquaculture species, and premium pet food segments with limited commercial feed volume.
Growth promotion leads by volume. Immune function applications expand most quickly under antibiotic reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil's integrated broiler sector absorb micronutrient costs within operational margins, while India's independent feed mills remain acutely price-sensitive. European formulators face the steepest compliance-driven cost inflation. China's state-backed consolidation creates divergent procurement patterns across coastal and interior provinces.
Brazil
Integrated broiler operations in São Paulo and Paraná drive concentrated vitamin A premix procurement through direct manufacturer contracts. MAPA inspection protocols and ANVISA feed additive registrations govern cross-border shipment certification for poultry-grade formulations. The western Paraná feed mill cluster around Cascavel processes the highest per-capita vitamin A tonnage in Latin America.
China
State-backed livestock consolidation in Shandong and Guangdong provinces escalates automated dosing system deployment. SAMR feed additive catalog revisions and MEE environmental discharge standards reshape manufacturing location decisions for multinational suppliers. The Yangtze River Delta chemical synthesis corridor near Shanghai concentrates domestic β-ionone precursor production.
United States
Antibiotic-free poultry mandates in the Southeast and Midwest elevate immune-function vitamin A protocols above standard growth-promotion inclusion rates. FDA feed ingredient approvals and state-level veterinary feed directive enforcement create layered compliance requirements. Iowa's corn-soy belt hosts the densest concentration of automated swine and poultry feed mills.
India
Consolidating dairy cooperatives in Maharashtra and Gujarat formalize vitamin A procurement previously sourced through informal channels. BIS feed-grade specifications and CDSCO import clearance protocols create layered entry barriers for multinational suppliers. The Pune-Nashik poultry belt emerges as the fastest-growing premix consumption cluster.
Germany
Specialty aquaculture feed compounders in northern Schleswig-Holstein specify cold-water dispersible microencapsulated formats for salmonid producers. EFSA maximum residue limits and REACH substance registration requirements impose the strictest formulation ceilings globally. The Hamburg chemical synthesis hub houses integrated retinyl ester production facilities serving EU-wide distribution.
Vitamin a in Feed Additives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with microencapsulation specialists commanding premium positioning while integrated chemical manufacturers defend volume share. The market structures around three tiers: multinational chemical conglomerates with captive precursor supply, nutrition-focused specialists with formulation IP, and regional premix blenders serving price-sensitive independents. Dominant competitive moves include backward integration into β-ionone supply and geographic expansion through distributor displacement in Southeast Asia.
Among the integrated chemical conglomerates, BASF SE and DSM-Firmenich exemplify divergent strategic positioning. BASF SE anchors the cost-optimized tier through its Ludwigshafen synthesis platform. DSM-Firmenich occupies the technology-premium position. Adisseo sits within the regional-specialist archetype, competing aggressively in tropical climate formulations. These three patterns—integrated chemical, technology-premium, and climate-specialist—capture the competitive structure.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| BASF SE |
| DSM-Firmenich |
| Evonik Industries AG |
| Adisseo |
| Kemin Industries, Inc. |
| Alltech |
| Ajinomoto Health & Nutrition North America, Inc. |
| Others |
Pricing and Supply Chain Analysis
Fishmeal replacement in aquaculture feed formulations simultaneously redraws procurement geography toward Norway and Chile while compressing vitamin A premia as salmonid producers negotiate volume-stability guarantees. This substitution dynamic concentrates buyer power among integrated operators capable of specifying microencapsulated formats, forcing suppliers to absorb climate-conditioned logistics costs within contract pricing.
Pricing Analysis
After-sales technical service and stability-guarantee contracts drive lifetime value for vitamin A manufacturers, with BASF SE and DSM-Firmenich bundling climate-conditioned delivery protocols and lot-specific certification into multi-year agreements. Three-tier pricing structure across pharmaceutical-grade, feed-grade microencapsulated, and commodity beadlet formats separates premium stability guarantees from standard heat-tolerance specifications. Cost compression in commodity acetate esters is intensifying because Brazilian integrators are consolidating procurement through direct manufacturer contracts, bypassing distributor markups. Independent feed mills in India and Southeast Asia exhibit acute price sensitivity, while Norwegian aquaculture operations absorb substantial premia for cold-water dispersible formats.
Supply Chain Analysis
Inventory lead times for β-ionone precursors extend through petrochemical feedstock cycles, with manufacturers holding strategic reserves against citral derivative volatility. Production gravity centers on Germany's Ludwigshafen chemical corridor, China's Yangtze River Delta synthesis cluster, and Singapore's tropical-formulation specialist facilities. The supply chain draws from petrochemical naphtha streams, citral extraction from lemongrass and Litsea cubeba, and specialized lipid-shell encapsulation polymers. Single-source vulnerability concentrates in German integrated synthesis platforms serving EU REACH-compliant formulations. Distribution runs through direct procurement relationships with Brazil's JBS and Thailand's CP Group, displacing traditional distributor intermediaries in premium contract segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitamin A feed additive markets fragment across climate-stressed tropical operations, antibiotic-free mandate regions, and aquaculture expansion zones, with each demand pocket rewarding distinct formulation capabilities rather than scale economics alone.
For Market Incumbents: Consolidate microencapsulation talent pools through targeted acquisition of lipid-shell engineering specialists in Southeast Asia, where heat degradation modeling expertise commands premium compensation. Deepen backward integration into β-ionone precursor supply through partnership with China's Yangtze River Delta chemical synthesis corridor, securing captive feedstock against petrochemical volatility while meeting MEE environmental discharge standards. For New Entrants and Emerging Players: Lead with automated dosing system compatibility in India's consolidating dairy cooperatives, where Maharashtra and Gujarat procurement formalization creates first-mover advantage for liquid premix formats. Target the Pune-Nashik poultry belt with climate-conditioned delivery protocols and BIS-certified formulations, displacing informal channel suppliers through traceability guarantees and direct farm relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional premix blenders in Southeast Asia possessing tropical formulation IP but lacking automated dosing infrastructure capital. Long-term viability across the analysis window hinges on microencapsulation technology ownership and direct channel access to integrated livestock operators. Watch for EU F-Gas Regulation enforcement acceleration as inflection indicator, as REACH substance restriction proposals will force capital-intensive abatement retrofits that favor acquirers with balance sheet capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into β-Ionone Precursor Supply | Captive feedstock from China's Yangtze River Delta insulates against citral derivative price volatility. |
| Cold-Water Dispersible Microencapsulation Scale-Up | Norwegian salmonid producers specify lipid-shell formats preventing degradation during extrusion. |
| Direct Procurement Channel Development | Brazil's JBS and Thailand's CP Group negotiate annual volume contracts displacing distributors. |
| Tropical Climate Formulation R&D Investment | Heat degradation modeling expertise addresses warehouse temperature exceedance in Paraná feed mills. |
| Automated Dosing System Partnership | Liquid premix compatibility with CP Group infrastructure commands substantial contract premia. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with vitamin A synthesis plant managers, poultry integrator procurement directors, aquaculture feed formulators, and SAMR regulatory affairs specialists; and secondary validation through customs/trade databases, EU EFSA maximum residue limit filings, SEC 10-K disclosures from listed chemical conglomerates, and BIS feed-grade specification documents. Bottom-up triangulation across β-ionone production volumes, premix formulation throughputs, and species-specific inclusion rates converged with top-down expenditure analysis from integrated livestock operators.
Across the projection horizon, the analytical framework modeled vitamin A feed additive demand through segmentation dimensions spanning ester chemistry, animal type, physical form, and regional regulatory cluster. CAGRs were derived from compound growth trajectory analysis rather than single-point extrapolation, incorporating aquaculture feed fortification mandates, antibiotic-free poultry protocol adoption, and automated dosing system deployment curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained aquaculture expansion, stable REACH enforcement trajectories, or continued β-ionone precursor availability would require recalibration. Forecasts reflect documented assumptions regarding climate-conditioned logistics cost absorption and direct procurement channel consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Multivitamin Gummies Market