
 Fortified Baby Food Market | 2026-2036
Fortified Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Baby Food Market Analysis
Multi-source ingredient procurement is hardening as the dominant supply strategy across fortified baby food manufacturing. Nestle leverages backward integration into dairy and micronutrient premix operations to secure formula stability. Danone anchors its competitive stance through specialized organic supply chains in France and Germany. Mead Johnson Nutrition competes on pediatric nutrition science credentials, sustaining premium positioning in clinical channels.
Fortified baby food denotes infant and toddler nutrition products with added vitamins, minerals, or bioactive compounds such as iron, zinc, DHA, or probiotics, manufactured through thermal processing, aseptic filling, or freeze-drying to preserve micronutrient integrity; its primary purpose is to bridge dietary gaps during critical neurodevelopmental windows. Pouches now lead packaging type growth due to convenience-driven urban parenting and reduced per-serving waste, while cereals command the largest revenue pool within product type segmentation given repeat purchase frequency and broad age-range applicability. Online distribution channels are expanding fastest as subscription models and direct-to-parent platforms reshape replenishment behavior.
The FDA enforces infant formula nutrient specifications and Current Good Manufacturing Practice standards, while the EMA and EFSA coordinate on novel ingredient approvals and contaminant thresholds across Europe; China's SAMR mandates GB standard compliance for imported and domestic infant foods alike. These layered requirements elevate compliance costs but also create barriers that favor established manufacturers with regulatory affairs infrastructure. Stakeholders must monitor evolving micronutrient ceiling regulations and front-of-pack labeling mandates as the primary variables that will reshape product portfolios and market access conditions.
Market Dynamics
Dual-income household expansion across urban centers is compressing meal preparation windows for infant feeding, creating sustained pull for shelf-stable, micronutrient-dense formats that bypass traditional cooking stages.
Growth Catalysts
- SAMR GB Standard Alignment:China's unified safety benchmarks for imported and domestic infant foods reduce regulatory friction for compliant entrants, accelerating portfolio localization by multinational manufacturers.
- DHA and ARA Enrichment Protocols:Lipid microencapsulation advances preserve long-chain polyunsaturated fatty acid stability through thermal processing, expanding neurodevelopmental positioning in premium tier products.
- Urban Parent Time Scarcity:Working mothers in metropolitan China, India, and Brazil face average commutes exceeding 90 minutes, driving pouch-format adoption for transit-feeding convenience.
Market Restraints
- Organic Dairy Input Volatility:Certified organic milk powder commands 40-60% price premiums over conventional, squeezing margin structures for formula-dependent manufacturers.
- European Contaminant Threshold Tightening:The European Commission's revised maximum levels for heavy metals in infant foods force reformulation cycles and supply base audits, elevating compliance costs disproportionately for mid-tier players.
- Freeze-Drying Capacity Concentration:Commercial lyophilization infrastructure clusters in Switzerland, Germany, and select US contract manufacturing sites, creating geographic supply risk for brands seeking clean-label processing claims.
Strategic Opportunities
- Sub-Saharan Africa Underpenetration:Commercial infant food access rates below 15% in Nigeria, Kenya, and Ethiopia present whitespace for affordable fortified cereal formats adapted to local grain preferences.
- Subscription Replenishment Platforms:Direct-to-parent digital channels bypass traditional retail slotting fees, enabling margin recovery and first-party data capture for personalized nutrition recommendations.
- Probiotic-Strain Regulatory Tailwinds:EFSA's evolving qualified presumption of safety framework for specific Lactobacillus and Bifidobacterium strains opens gut-health positioning in European markets previously restricted to general wellness claims.
Industry Challenges
- Pediatric Nutritionist Talent Scarcity:Formulation science roles requiring dual expertise in food engineering and early-life metabolic development command salary premiums that strain R&D budgets outside top-tier manufacturers.
- Aseptic Filling Line Retrofit Costs:Transitioning legacy thermal processing equipment to extended-shelf-life pouch formats demands capital outlays exceeding $12 million per production site, consolidating investment capacity among scaled players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Baby Food Market |
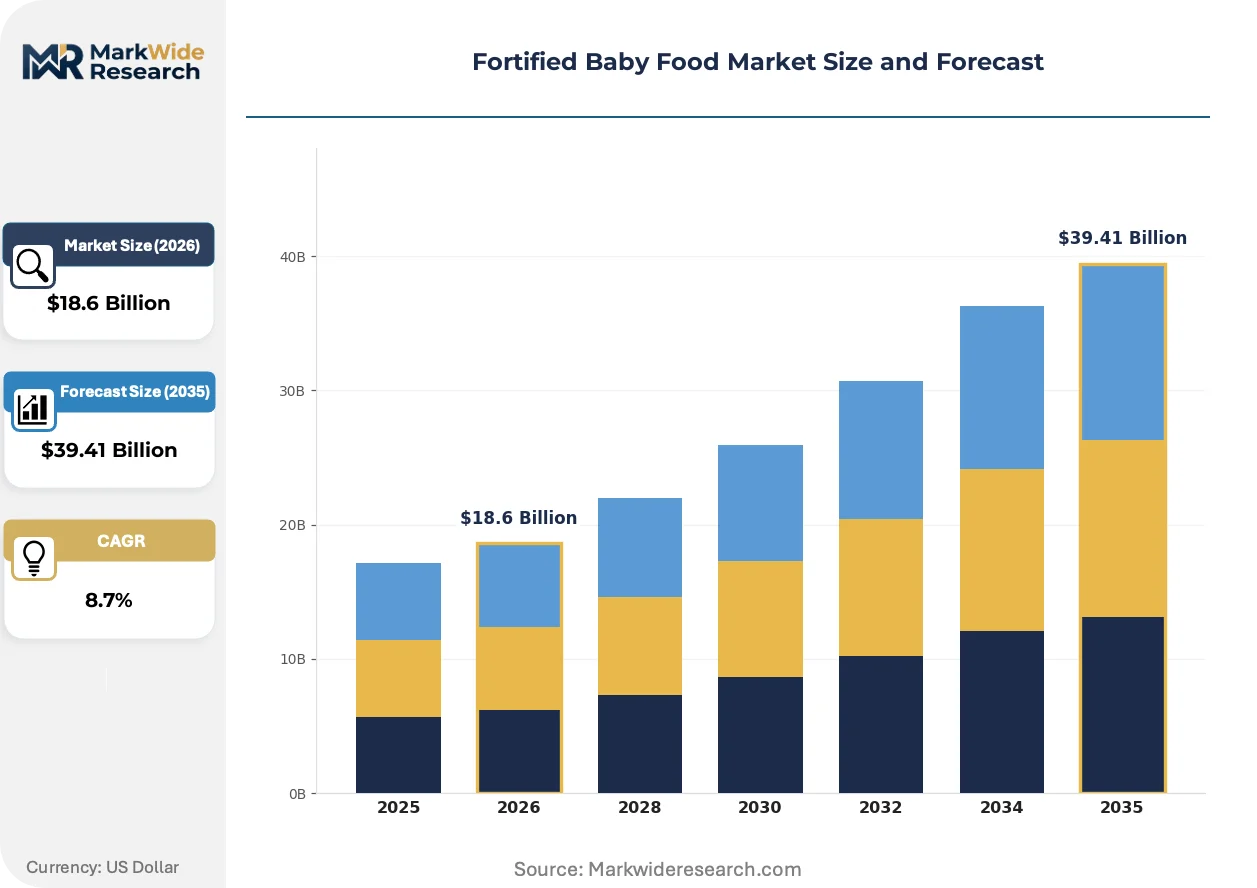
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Cereals, Snacks, Powders Ingredient Type: Fruits, Vegetables, Grains, Dairy Packaging Type: Jars, Pouches, Tubs, Cans Distribution Channel: Supermarkets, Online, Convenience Stores, Health Food Stores |
| Companies Covered | Nestle, Danone, Abbott Laboratories, Hipp, Mead Johnson Nutrition, Hero Group, Kraft Heinz Company, FrieslandCampina, Earth's Best, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Baby Food Market Emerging Trajectories
Clean-label preservation technologies and precision micronutrient delivery systems are redefining product architecture, while regulatory science investments separate compliant portfolios from reformulation laggards.
Microencapsulation of heat-sensitive vitamins using modified starch and gum arabic matrices is consolidating as the dominant stability solution for retort-processed infant cereals. Manufacturers in Germany and Japan have adopted these lipid-shell technologies at commercial scale, enabling iron and zinc fortification levels previously degraded by conventional thermal treatment. This consolidation is compressing the competitive set to suppliers with in-house particle engineering capabilities.
REACH authorization requirements for novel food contact substances are tightening migration testing protocols for pouch laminates across European manufacturing. Industrial consequence includes extended material qualification timelines of 18-24 months for alternative biodegradable films. Brands targeting German and French markets are responding by locking multi-year supply agreements with incumbent film converters rather than pursuing unproven substrate transitions.
Urban millennial parents are consolidating purchase decisions through pediatrician-validated recommendation platforms, displacing traditional retail discovery. Subscription services bundling developmental milestone tracking with automated formula replenishment are capturing loyalty in Shanghai, São Paulo, and Los Angeles metro corridors. This behavioral pivot favors manufacturers with clinical channel relationships and digital infrastructure investments over legacy retail-dependent competitors.
Fortified Baby Food Market Segmentation
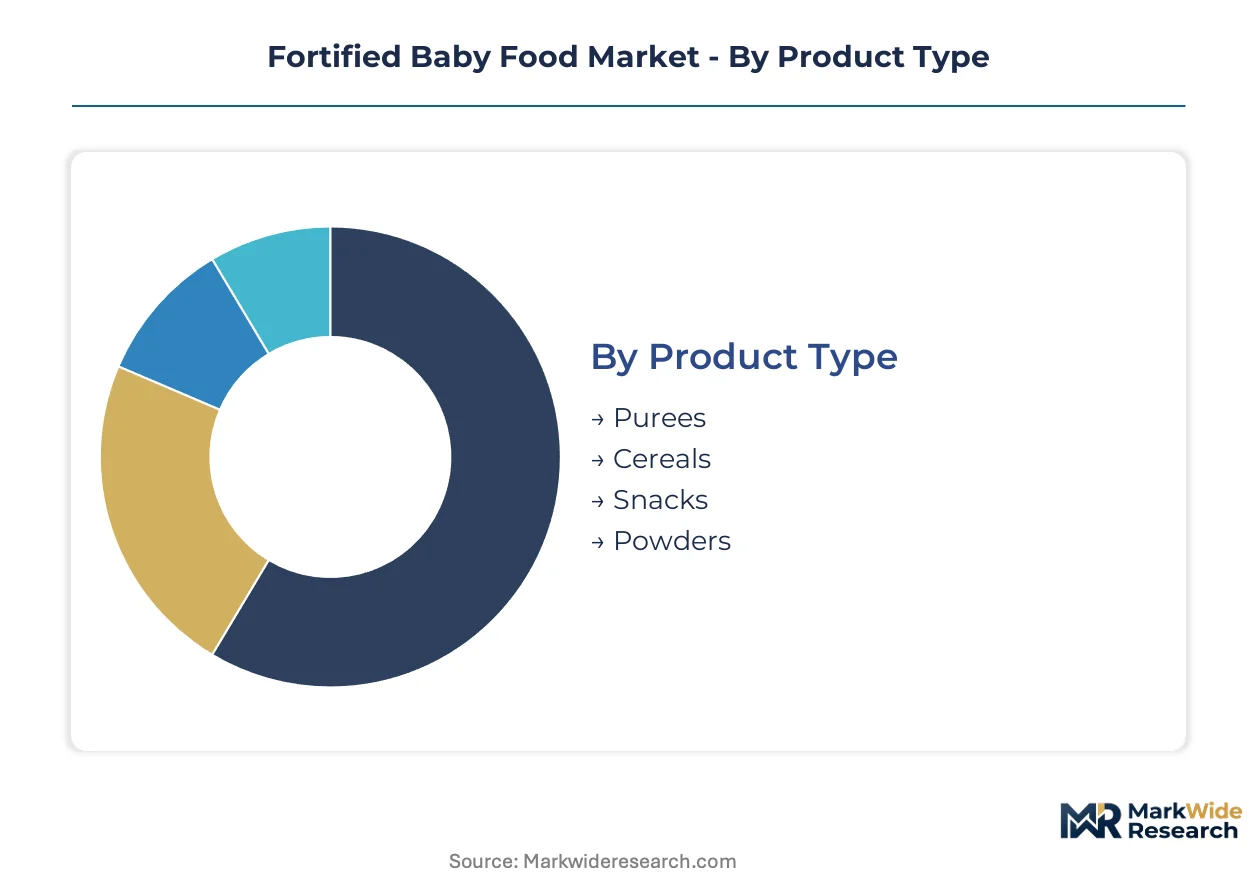
Segmentation in fortified baby food reveals how convenience, nutrition density, and channel accessibility partition parental purchasing decisions. Manufacturers configure supply chains and R&D investments around these divides to capture recurring consumption across developmental stages.
Product Type:
Cereals anchor volume throughput while pouches command premium per-unit economics, creating a bifurcated portfolio strategy across price tiers.
- Cereals:Iron-fortified oat and rice-based formulations undergo extrusion and micronutrient spray-coating to preserve bioavailability through shelf life. Repeat purchase frequency concentrates demand in suburban US households and tier-2 Chinese cities where pediatrician recommendation drives brand loyalty. Powdered and dry formats tolerate ambient distribution without cold chain dependency.
- Purees:Fruit and vegetable blends with added zinc or vitamin C utilize high-pressure processing or mild thermal treatment to retain texture and nutrient integrity. Urban millennial parents in São Paulo and Mumbai metro corridors favor these for transitional feeding stages between breast milk and solids. Clean-label positioning with single-ingredient transparency commands shelf space in premium retail.
- Snacks:Puffed grain and freeze-dried fruit pieces with calcium or DHA enrichment target toddler self-feeding milestones.
- Powders:Spray-dried formula bases and cereal mixes require reconstitution, dominating price-sensitive segments in emerging markets.
Today's leader: Cereals. Tomorrow's challenger: Purees.
Ingredient Type:
Supply security and allergen management separate ingredient sourcing strategies, with dairy and grain networks commanding the most capital-intensive backward integration.
- Dairy:Whey protein concentrates and milk fat blends serve as the lipid and amino acid backbone for formula products. New Zealand and Dutch dairy cooperatives supply premium organic streams to Nestle and Danone manufacturing sites in Ireland and France. Lactose intolerance prevalence in East Asian populations limits penetration in China without hydrolyzed variants.
- Grains:Rice, oat, and quinoa flours provide carbohydrate substrates with lower allergenicity than wheat. Indian and Nigerian domestic brands source from local milling cooperatives to hit price points below imported competition. Arsenic monitoring in rice-based products consumes regulatory affairs bandwidth across US and European quality control labs.
- Fruits:Apple, banana, and mango purees supply natural sweetness and vitamin C carriers.
- Vegetables:Sweet potato, carrot, and spinach incorporations address vegetable exposure protocols in early feeding guidelines.
Dairy and grains absorb the majority of procurement capital; fruit and vegetable streams offer differentiation through origin storytelling.
Packaging Type:
Material science investments and retail slotting economics determine which formats achieve shelf dominance in each geography.
- Pouches:Multi-layer laminates with spout fitments enable one-handed feeding and reduced per-serving waste. German and Japanese converters supply high-barrier films that extend shelf life without preservatives, though REACH migration testing extends qualification timelines. Urban Chinese parents purchase these through subscription platforms for workplace daycare packing.
- Jars:Glass containers with metal lug caps retain premium positioning in European organic segments. French and Italian retailers favor visible product presentation for trust signaling. Weight and breakage constraints limit e-commerce viability compared to flexible alternatives.
- Tubs:Polypropylene containers with peelable lidding dominate powder and cereal formats.
- Cans:Metal packaging persists in powdered formula for extended shelf stability in tropical climates.
Pouches are expanding most quickly in urban convenience channels; jars defend margin in European premium retail.
Distribution Channel:
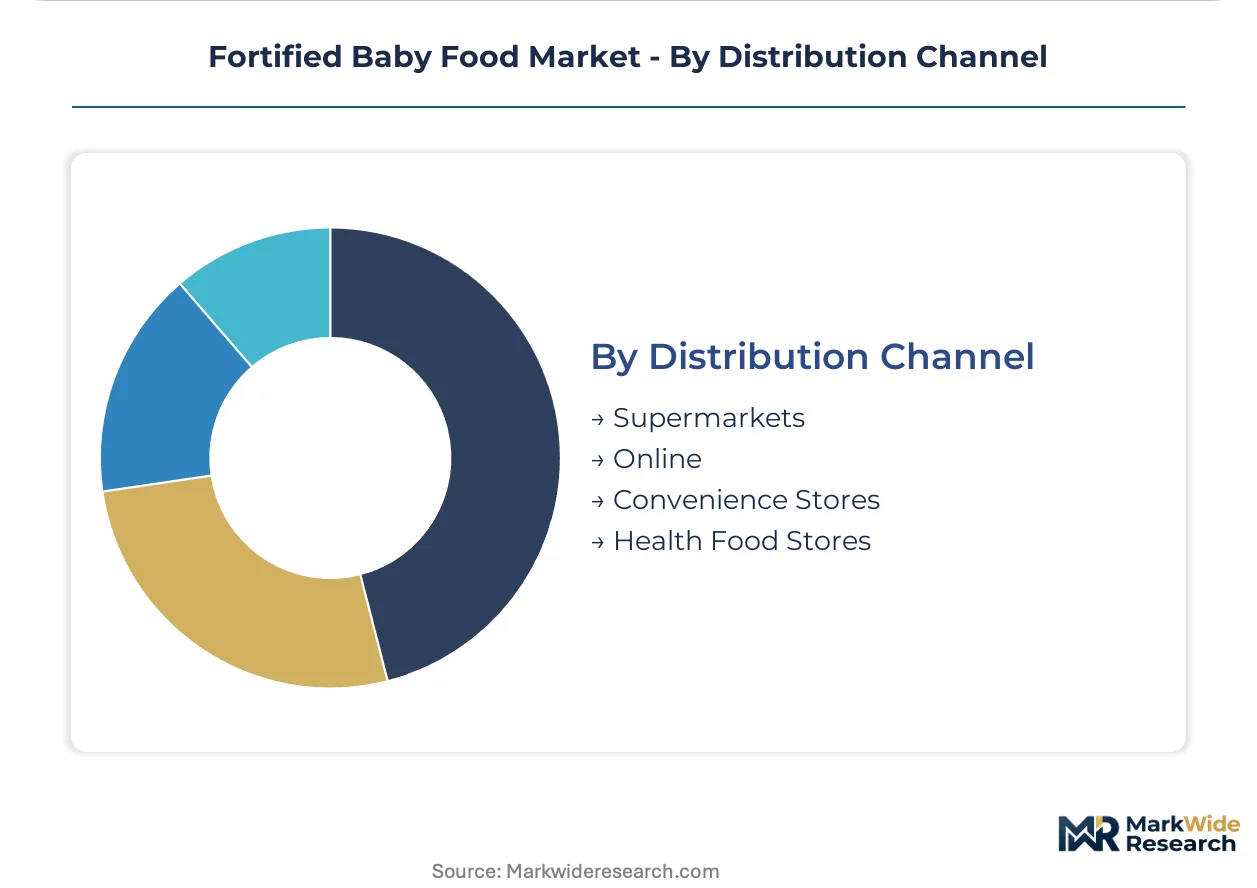
Channel selection determines customer data access, working capital requirements, and margin capture for manufacturers at each growth stage.
- Online:Direct-to-parent platforms and marketplace storefronts bypass retail slotting fees while capturing first-party consumption data. Subscription replenishment models with developmental milestone content lock in loyalty in Los Angeles, Shanghai, and London metro corridors. SAMR registration requirements for cross-border e-commerce into China filter out non-compliant entrants.
- Supermarkets:Mass merchandisers in the US and hypermarkets in Brazil provide discovery and trial conversion for new parents. Category management negotiations favor scaled manufacturers with trade promotion budgets. Planogram positioning near diaper and formula aisles drives impulse basket expansion.
- Convenience Stores:Urban grab-and-go formats stock single-serve pouches for transit feeding.
- Health Food Stores:Specialist retailers in Germany and California curate organic and allergen-free assortments.
Online channels are gaining share fastest; supermarkets retain volume concentration in suburban family demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors fortified baby food demand concentration through its dense dual-income household base and sophisticated e-commerce infrastructure for subscription replenishment models.
China
Urban millennial parents in Beijing and Guangzhou drive pouch-format adoption for transit-feeding convenience during commutes exceeding 90 minutes. SAMR GB standard alignment reduces regulatory friction for compliant multinational entrants, accelerating portfolio localization. Manufacturing clusters in Jiangsu and Zhejiang provinces concentrate spray-drying and aseptic filling capacity for domestic brands strengthening their fortified portfolios.
United States
Suburban households in Texas and Florida generate repeat purchase frequency for iron-fortified cereals through pediatrician-driven brand loyalty. FDA infant formula nutrient specifications and Current Good Manufacturing Practice standards elevate compliance costs that favor established manufacturers with regulatory affairs infrastructure. Production sites in Wisconsin and California concentrate thermal processing and microencapsulation capabilities for DHA-enriched formats.
Germany
Organic supply chains in Bavaria and North Rhine-Westphalia anchor Danone's competitive positioning through specialized dairy procurement. ECHA REACH authorization requirements for novel food contact substances extend pouch laminate qualification timelines to 18-24 months. Berlin and Hamburg metro corridors concentrate clean-label product development for premium retail channels.
France
Glass jar formats retain premium positioning in Paris and Lyon organic segments where visible product presentation signals trust. EFSA qualified presumption of safety framework evolution opens gut-health positioning for specific probiotic strains previously restricted to general wellness claims. Manufacturing in Normandy and Brittany concentrates dairy-based formula production with backward integration into whey protein concentrates.
Brazil
São Paulo metro parents favor purees for transitional feeding stages between breast milk and solids, with high-pressure processing retaining texture integrity. ANVISA registration requirements filter cross-border entrants while domestic brands source rice and oat substrates from local milling cooperatives. Manufacturing clusters in Minas Gerais and Rio Grande do Sul concentrate affordable fortified cereal production for price-sensitive segments.
Fortified Baby Food Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label specialization and direct-to-parent digital channels. Market structure consolidates around three to five multinational manufacturers with captive micronutrient premix capabilities and regulatory compliance infrastructure. Strategic archetypes include science-backed pediatric nutrition specialists, organic supply chain integrators, and private-label contract manufacturers. Competitive moves concentrate on aseptic filling line retrofits exceeding $12 million per site and multi-year supply agreements with incumbent film converters.
Among Swiss and Dutch dairy-anchored corporations, Nestle and FrieslandCampina exemplify backward integration into whey operations and micronutrient stability engineering. Danone occupies a position within the organic tier through specialized supply chains in France and Germany. Mead Johnson Nutrition represents the clinical-channel archetype with pediatric nutrition science credentials sustaining premium positioning. These three manufacturers anchor the competitive set through distinct procurement and channel strategies rather than convergent imitation.
| Leading Market Players |
|---|
| Nestle |
| Danone |
| Abbott Laboratories |
| Hipp |
| Mead Johnson Nutrition |
| Hero Group |
| Kraft Heinz Company |
| FrieslandCampina |
| Earth's Best |
| Others |
Supply Flow & Price Mechanics
EU Green Deal compliance requirements gate qualified organic dairy supply and premium-tier pricing access for fortified baby food manufacturers seeking European market entry. SAMR GB standard alignment in China simultaneously filters compliant from non-compliant supply bases, concentrating pricing power among manufacturers with backward-integrated micronutrient premix operations.
Pricing Analysis
Input-cost pass-through from certified organic milk powder premiums flows directly to shelf pricing, with 40-60% markups over conventional dairy squeezing margin structures for formula-dependent manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates clinical-channel pediatric nutrition credentials from private-label contract manufacturing. Pricing pressure stems from European Commission heavy metal threshold tightening forcing reformulation cycles. Emerging market buyers in Nigeria and Kenya exhibit highest price sensitivity, while dual-income Shanghai households absorb premium pouch-format pricing.
Supply Chain Analysis
Organic dairy input rests on New Zealand and Dutch cooperative networks, with whey protein concentrate supply anchored in Ireland and France manufacturing clusters. Microencapsulation-grade modified starch and gum arabic feed from German and Japanese specialty chemical producers. Single-source vulnerability concentrates in Swiss and German commercial lyophilization infrastructure for freeze-dried clean-label claims. Distribution runs through direct-to-parent subscription platforms bypassing retail slotting fees in Los Angeles, Shanghai, and London metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SAMR GB standard alignment in China drives demand consolidation toward compliant multinational portfolios.
For Market Incumbents: Acquire aseptic filling line capacity in Jiangsu and Zhejiang provinces to localize production for SAMR-compliant portfolios. Lock multi-year supply agreements with incumbent German and Japanese film converters before REACH migration testing timelines extend further. Pediatric nutritionist talent scarcity threatens R&D velocity; secure formulation science capabilities through targeted recruitment in Wisconsin and California thermal processing clusters. For New Entrants and Emerging Players: EFSA's evolving qualified presumption of safety framework for specific Lactobacillus and Bifidobacterium strains opens a window for gut-health positioning in European markets previously restricted to general wellness claims. Sub-Saharan Africa underpenetration in Nigeria, Kenya, and Ethiopia offers whitespace for affordable fortified cereal formats adapted to local grain preferences. Pursue direct-to-parent digital channels with developmental milestone content bundling to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Roll-up economics work for private-label contract manufacturers with aseptic filling capabilities because freeze-drying capacity concentration in Switzerland and Germany creates acquisition scarcity value. Target mid-tier players facing disproportionate European contaminant compliance cost burdens. Watch EFSA novel ingredient approval velocity as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Line Retrofit | $12 million per-site capital outlays consolidate investment capacity among scaled players with SAMR compliance infrastructure. |
| Backward Integration into Dairy | Captive whey protein concentrate supply from New Zealand cooperatives secures formula stability against organic input volatility. |
| Subscription Platform Launch | Direct-to-parent digital channels in Shanghai and São Paulo capture first-party data for personalized nutrition recommendations. |
| Probiotic Strain Regulatory Investment | EFSA qualified presumption of safety submissions open gut-health positioning previously restricted to general wellness claims. |
| Sub-Saharan Africa Market Entry | Commercial infant food access below 15% in Nigeria and Ethiopia creates whitespace for locally-adapted fortified cereal formats. |
Methodological Framework
Bottom-up dual-income household demand modeling reconciled against top-down aseptic filling capacity tracking forms the analytical core of this study. Primary interviews with pediatric nutrition formulation scientists, SAMR regulatory affairs leads, supermarket category buyers, and pouch film procurement managers combined with secondary validation from FDA infant formula nutrient specifications, EFSA novel ingredient approval databases, SAMR GB standard filings, and Nielsen retail audit data. Triangulation between consumption endpoint estimates and manufacturing capacity registers ensures coherence across the analysis window.
Input-output matrices map iron-fortified cereal repeat purchase frequency, DHA-enriched formula premium positioning, and pouch-format adoption velocity against spray-drying capacity in Jiangsu province, lyophilization infrastructure in Switzerland, and microencapsulation capabilities in Germany and Japan. Segmentation dimensions span product type, ingredient sourcing strategy, packaging format, and distribution channel with regional regulatory cluster overlays. CAGRs derive from weighted average of bottom-up demand build and top-down supply constraint assessment across pediatric nutrition science investment cycles.
Revisions become necessary when SAMR GB standard enforcement intensity shifts, European Commission heavy metal thresholds tighten beyond current baselines, or freeze-drying capacity expansion in non-traditional geographies accelerates. Forecasts reflect documented assumptions regarding dual-income household formation rates, urban parent commute time thresholds, and pediatrician recommendation platform consolidation. A small set of named triggers—EFSA probiotic strain approval velocity, REACH authorization timeline extensions for biodegradable films, and ANVISA registration pathway changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Calcium-Fortified Bread Market