
 Lignin Market | 2026-2036
Lignin Market Size, Share, and Industry Trends Forecast 2026-2036
Lignin Market Intelligence
Asset-light toll-processing agreements is reconfiguring competitive entry in lignin valorization, allowing specialty chemical firms to access biorefinery capacity without owning pulp mill assets. Borregaard AS leverages its Norwegian soda lignin infrastructure to dominate pharmaceutical-grade outputs. Stora Enso anchors European supply through its Sunila biorefinery integration. UPM Biochemicals positions its Leuna operation as a downstream hub for lignin-derived biochemicals.
Lignin is a complex phenolic polymer comprising methoxylated phenylpropane units, constituting 15-30% of lignocellulosic biomass and serving as nature's primary aromatic resource for industrial chemical replacement. Kraft lignin currently leads volume flows due to established recovery infrastructure at pulp mills, while organosolv lignin captures premium positioning in carbon fiber precursor applications where low ash and narrow polydispersity command price premiums. Native lignin from novel fractionation routes is gaining traction in bioplastics compounding as processors seek unaltered macromolecular architecture.
EPA biofuel pathway approvals and EU REACH registration requirements for lignin-based substances are shaping product qualification timelines for North American and European suppliers. BIS certification protocols in India are creating compliance thresholds for imported lignin derivatives used in construction admixtures. Stakeholders must monitor evolving pyrolysis oil co-product classifications, as regulatory re-categorization could redirect lignin feedstock economics toward renewable fuel pools or preserve material-use premiums.
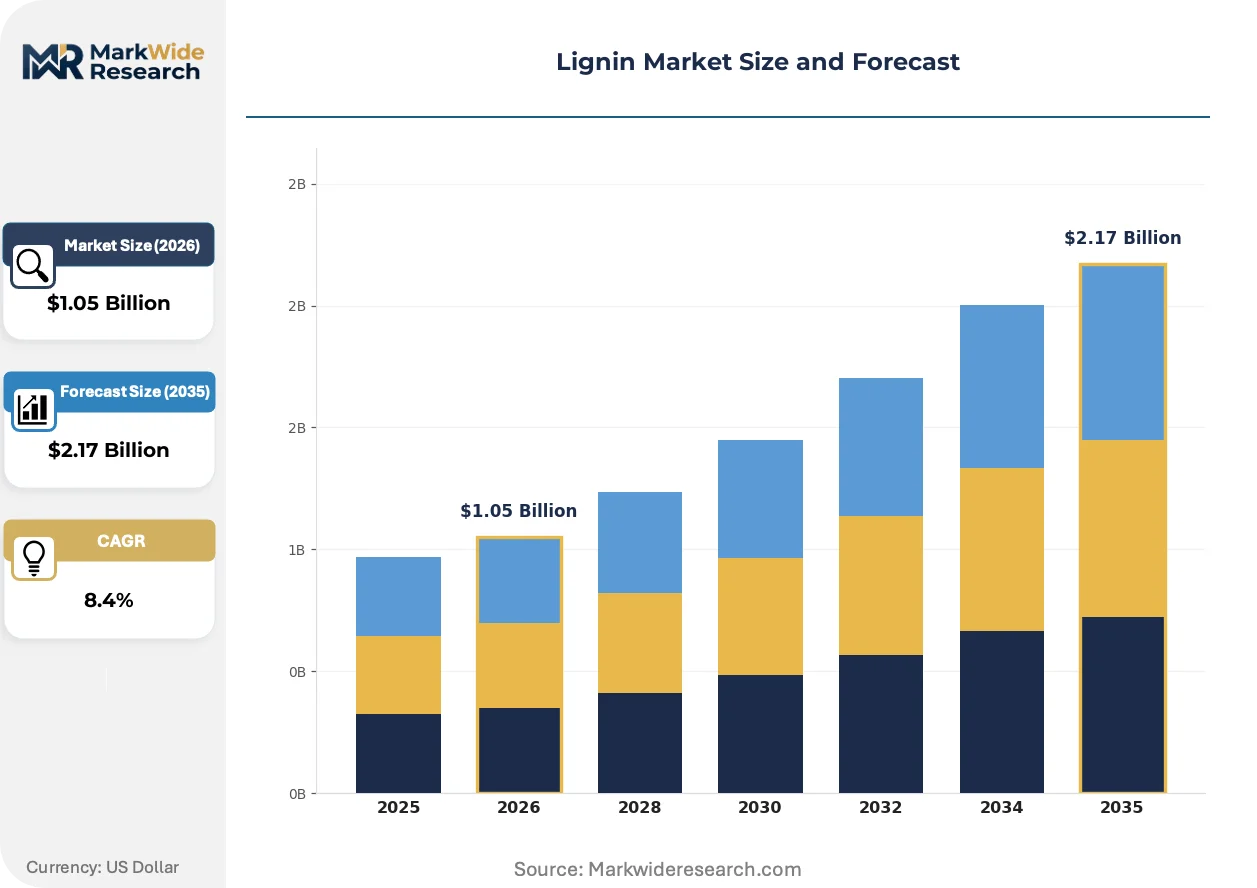
Market Dynamics
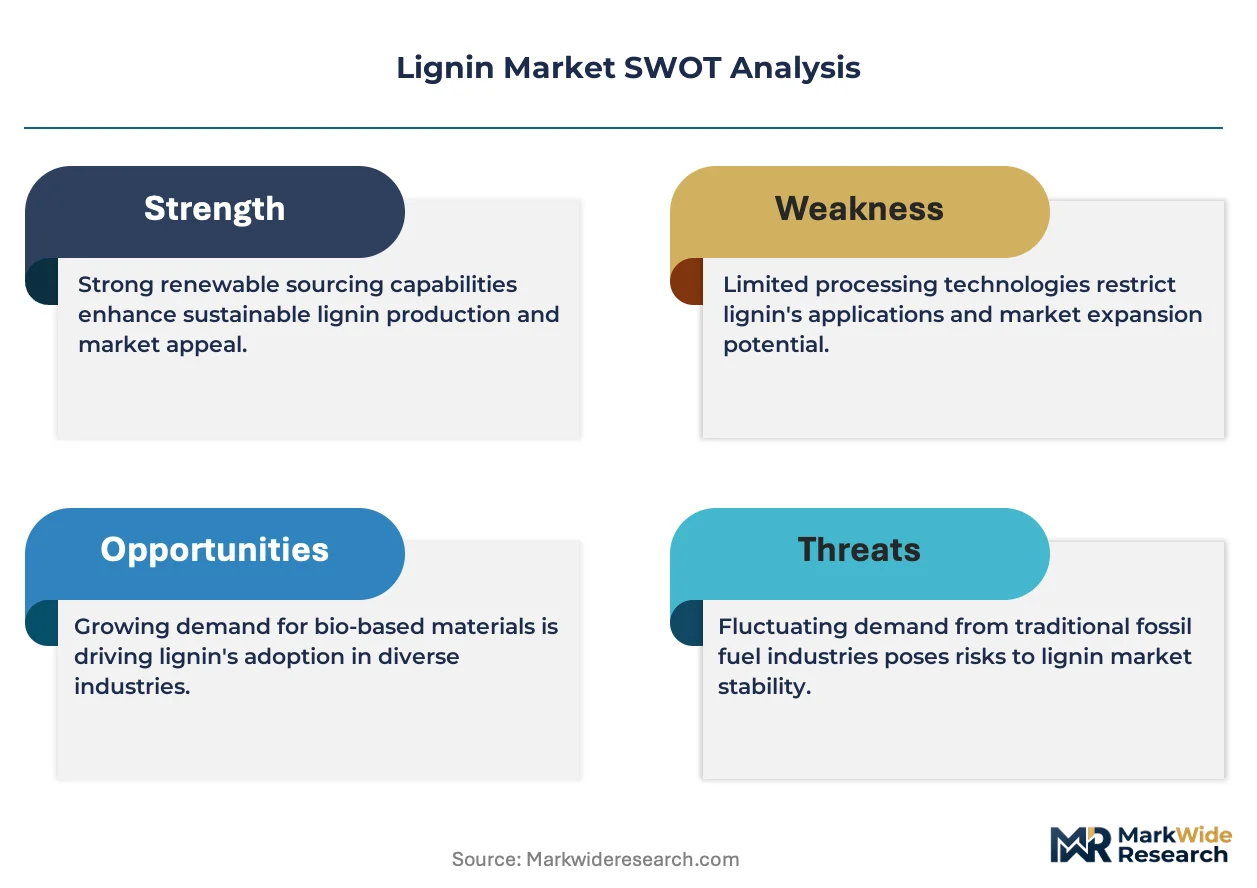
Integrated biorefinery economics are compressing lignin valorization timelines as black liquor processing shifts from energy recovery to material extraction, forcing pulp operators to choose between power generation margins and specialty chemical premiums.
Growth Catalysts
- EU Green Deal petrochemical restrictions:Germany's bioplastics sector is accelerating lignin-derived polymer qualification to meet tightening feedstock rules on fossil-based inputs.
- Carbon fiber precursor demand:Organosolv lignin with low ash content and narrow polydispersity is capturing premium positioning in aerospace and automotive composite applications.
- Nordic pulp cluster concentration:Finnish and Swedish integrated biorefineries are converting black liquor into high-purity lignin grades at scale, anchoring European supply security.
Market Restraints
- Process energy intensity:Kraft lignin recovery requires substantial thermal input, tying production economics to regional natural gas and biomass power pricing volatility.
- Feedstock concentration risk:Over 70% of technical lignin originates from sulfate pulp mills in Scandinavia and North America, creating geographic supply vulnerability.
- Petroleum-derived aromatic competition:BTX (benzene-toluene-xylene) streams from refineries maintain cost advantages in bulk chemical applications, pressuring lignin substitution economics.
Strategic Opportunities
- Indian construction admixtures:BIS certification protocols for imported lignin derivatives are creating compliance thresholds that early-qualifying suppliers can exploit for market establishment.
- Native lignin bioplastics compounding:Novel fractionation routes preserving unaltered macromolecular architecture are opening food-contact and medical-grade applications previously closed to processed lignins.
- Pyrolysis oil co-product reclassification:Regulatory uncertainty around renewable fuel pool eligibility versus material-use premiums is creating arbitrage windows for flexible biorefinery operators.
Industry Challenges
- Pharmaceutical-grade purification expertise:The talent pool for soda lignin refinement to GMP standards remains concentrated at Borregaard's Norwegian facilities, constraining capacity expansion.
- REACH registration timelines:EU chemical substance dossier preparation for novel lignin derivatives extends product qualification cycles by 18-36 months, delaying revenue realization.
- Black liquor integration complexity:Retrofitting existing pulp mill chemical recovery systems for lignin extraction without compromising energy balance requires substantial process engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignin Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Lignin, Lignin Sulfonates, Kraft Lignin, Organosolv Lignin Application: Adhesives, Carbon Fibers, Pharmaceutical Intermediates, Bioplastics End User: Construction, Agriculture, Automotive, Pulp & Paper Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Borregaard AS, Stora Enso, Domtar Corporation, Nippon Paper Industries Co., Ltd., Sappi Ltd, UPM Biochemicals, Ingevity, Rayonier Advanced Materials, Lenzing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignin Market Strategic Shifts & Innovations
Process analytical technology and closed-loop control systems are transforming lignin fractionation from batch art to continuous manufacturing, enabling specification-grade output at pulp mill scale.
Continuous flow organosolv processing is digitizing lignin quality control through real-time molecular weight monitoring and automated solvent recovery loops. Carbon fiber precursor manufacturers in Japan and Germany are adopting these systems to secure batch-to-batch consistency for PAN co-polymer substitution. The technology is digitizing specification negotiation between biorefinery operators and downstream polymer compounders, compressing qualification timelines from years to months.
EPA biofuel pathway approvals for pyrolysis-derived intermediates are redirecting lignin feedstock economics toward renewable fuel credit markets. The agency's RFS2 qualification criteria for cellulosic diesel intermediates are creating competing offtake demand against material-use applications. Biorefinery operators in the US Midwest are responding by developing dual-product flexibility, with real-time switching capability between fuel pool and chemical market pricing.
Specialty chemical firms are consolidating procurement through toll-processing agreements rather than asset ownership. This model allows European and North American compounders to access Nordic and Brazilian biorefinery capacity without pulp mill capital deployment. The shift is most visible in pharmaceutical-grade lignin sourcing, where GMP-certified toll processors are displacing in-house extraction investments among mid-scale API manufacturers.
Lignin Market Segmentation
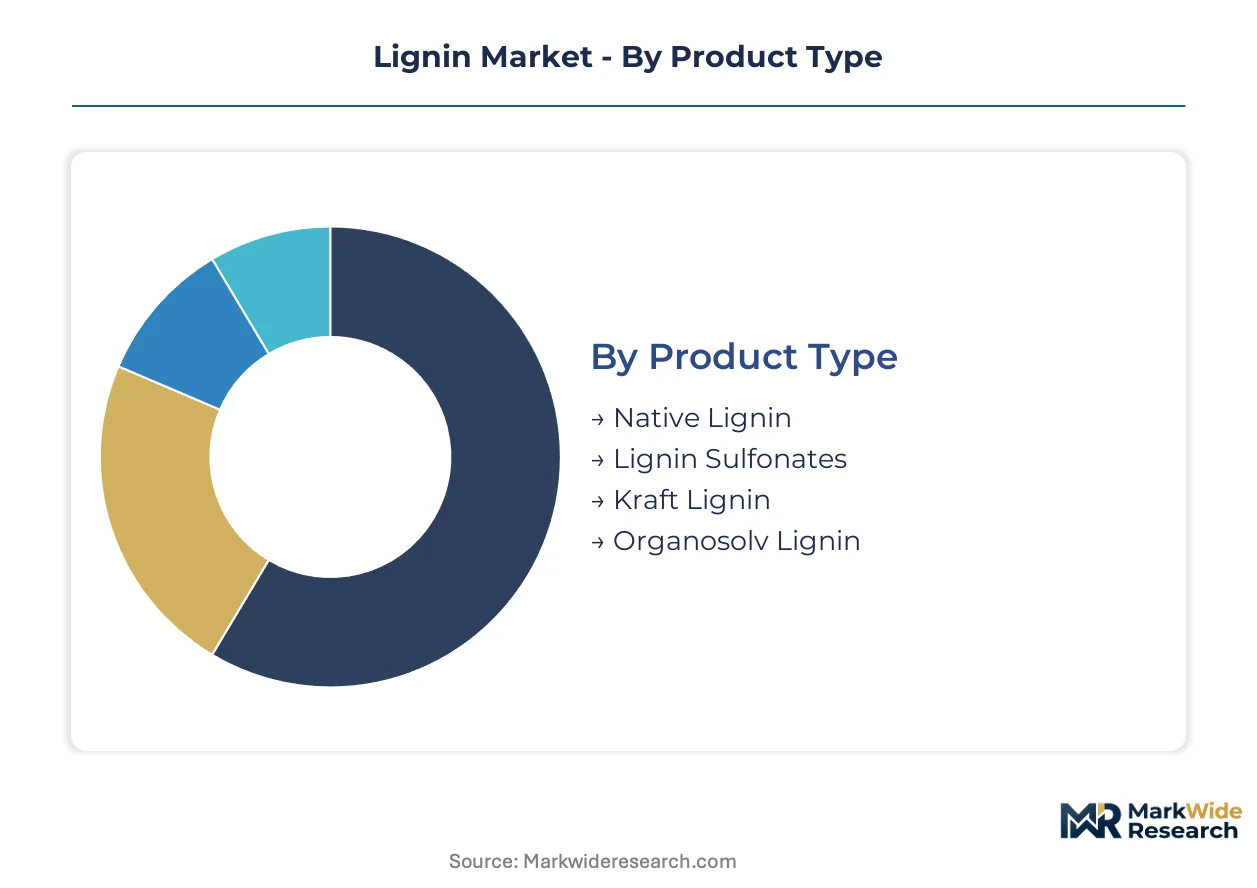
Lignin valorization pathways diverge sharply by chemical architecture and purity grade, with each product type commanding distinct specification regimes and customer qualification timelines. Application-driven demand is fragmenting procurement patterns as aerospace, pharmaceutical, and bioplastics sectors impose incompatible purity thresholds on suppliers.
Product Type:
Cost tier separation between commodity energy recovery and specialty chemical feedstock determines margin architecture across lignin grades.
- Kraft Lignin:Recovered from black liquor via acid precipitation, this sulfate-derived grade carries elevated ash content and broad molecular weight distribution. Pulp mills in Finland and Sweden anchor volume supply as integrated biorefineries retrofit recovery boilers for material extraction rather than combustion. Regional natural gas pricing volatility directly compresses purification economics.
- Organosolv Lignin:Solvent fractionation yields low-ash product with narrow polydispersity suited to carbon fiber precursor applications. German and Japanese aerospace compounders are qualifying these grades for PAN co-polymer substitution in pressure vessel manufacturing. EPA biofuel pathway approvals for pyrolysis intermediates are creating competing offtake demand from renewable diesel pools.
- Lignin Sulfonates:Sulfite pulping by-product with inherent water solubility from sulfonate functional groups. Construction admixture formulators in India leverage BIS-certified imports for concrete plasticizer applications.
- Native Lignin:Novel fractionation preserves unaltered phenylpropane macromolecular architecture. Food-contact and medical-grade bioplastics processors are pursuing REACH-registered grades for compounding applications.
Kraft lignin commands the established base. The steepest expansion runs through organosolv lignin.
Application:
End-use performance requirements are forcing specification-grade segmentation that fragments supplier qualification pathways.
- Carbon Fibers:Aerospace and automotive composite manufacturers demand sub-500 ppm ash content and polydispersity indices below 2.5 for melt-spinning compatibility. Japanese carbon fiber producers are integrating continuous flow organosolv systems with real-time molecular weight monitoring to secure batch-to-batch consistency.
- Bioplastics:Compounding applications require unmodified macromolecular structure achievable only through native lignin fractionation. EU Green Deal petrochemical restrictions are accelerating polymer qualification timelines for German packaging converters.
- Adhesives:Phenol-formaldehyde replacement in wood panel binders leverages lignin's aromatic hydroxyl density. Formaldehyde emission regulations in multiple jurisdictions are displacing petroleum-derived resins.
- Pharmaceutical Intermediates:GMP-grade soda lignin refinement for active pharmaceutical ingredient carriers concentrates expertise at Norwegian facilities. REACH registration dossiers for novel derivatives extend qualification cycles substantially.
Adhesives applications command the established base. Carbon fiber precursor demand is climbing the fastest.
End User:
Customer type concentration in Nordic pulp clusters and German manufacturing belts is shaping regional supply security priorities.
- Construction:Concrete admixture and wood adhesive formulators represent volume offtake for lignin sulfonate and kraft grades. Indian infrastructure investment is driving BIS certification requirements for imported derivatives.
- Pulp & Paper:Integrated biorefinery operators are the primary extraction source, with black liquor processing economics dictating energy-versus-material allocation decisions. Finnish and Swedish mills dominate technical lignin origination.
- Agriculture:Controlled-release fertilizer coatings and soil amendment applications leverage lignin's humic acid mimicry and chelating properties.
- Automotive:Interior panel adhesives and carbon fiber structural components are qualifying lignin-derived inputs for lightweighting initiatives under EU fleet emission regulations.
Pulp and paper integration commands the established base. Automotive qualification is gaining share fastest.
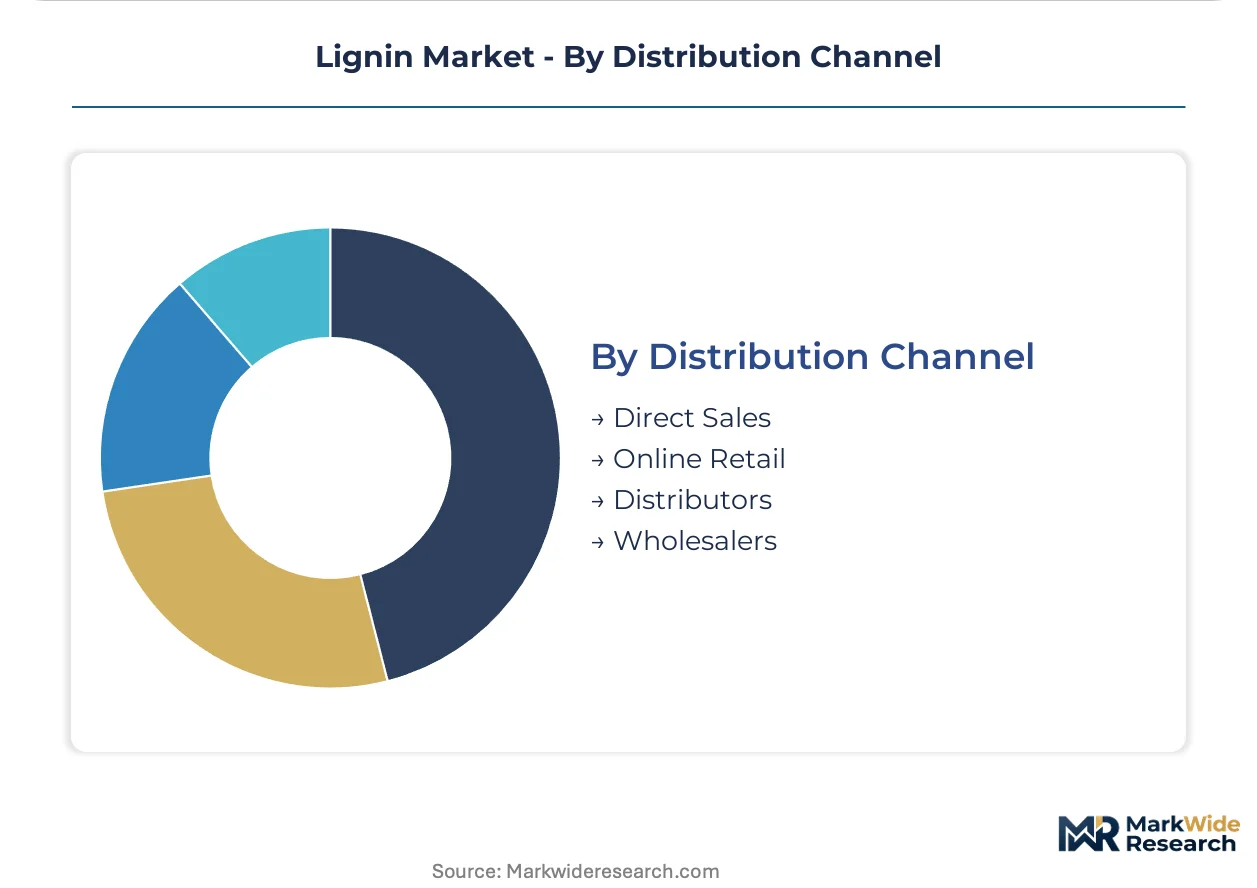
Distribution Channel:
Supply chain configuration reflects the tension between asset-heavy biorefinery control and specialty chemical firm flexibility requirements.
- Direct Sales:Pharmaceutical-grade and carbon fiber precursor contracts run through long-term offtake agreements with integrated Nordic producers. GMP certification and REACH registration transferability lock customers into incumbent relationships.
- Distributors:Construction admixture and agricultural applications rely on regional chemical distributors for formulation technical service and inventory pooling.
- Online Retail:Research-grade and small-volume specialty grades for university and pilot-scale biorefinery testing are migrating to B2B platform procurement.
- Wholesalers:Commodity lignin sulfonates for bulk concrete applications flow through construction material wholesalers with logistics integration into ready-mix supply chains.
Direct sales contracts command the established base. Toll-processing facilitation through distributors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp mills in Finland and Sweden command pricing leverage through integrated biorefinery conversion, while German compounders absorb transport premiums to secure pharmaceutical-grade supply chains. This geographic asymmetry concentrates margin capture upstream in Nordic clusters.
United States
Midwest biorefinery operators are developing dual-product flexibility between EPA RFS2 fuel pools and material-use applications. The EPA's cellulosic diesel pathway approvals for pyrolysis intermediates are redirecting lignin economics toward renewable credit markets. Wisconsin and Minnesota pulp clusters anchor domestic organosolv capacity expansion for carbon fiber precursor qualification.
Germany
Leuna's biochemical hub positions UPM downstream integration for lignin-derived polymer compounding under EU Green Deal petrochemical restrictions. ECHA REACH registration dossiers for novel derivatives extend product qualification timelines by 18-36 months. Bavarian packaging converters are accelerating polymer qualification to meet tightening fossil-based input rules.
Japan
Carbon fiber manufacturers in Nagoya and Osaka are qualifying low-ash organosolv grades for PAN co-polymer substitution in pressure vessel applications. METI industrial decarbonization programs are subsidizing biorefinery retrofit investments. Continuous flow organosolv systems with real-time molecular weight monitoring are securing batch-to-batch consistency for aerospace compounders.
India
Construction admixture formulators in Maharashtra and Gujarat are driving BIS certification requirements for imported lignin sulfonate derivatives. The Bureau of Indian Standards protocols are creating compliance thresholds for concrete plasticizer applications. Infrastructure investment in Delhi-Mumbai Industrial Corridor is expanding volume offtake for certified imports.
Brazil
Eucalyptus pulp mills in São Paulo and Minas Gerais are scaling organosolv fractionation for export-grade lignin production. ANVISA pharmaceutical-grade registration pathways remain underdeveloped, constraining high-value derivative development. Toll-processing agreements are allowing European compounders to access biorefinery capacity without pulp mill capital deployment.
Lignin Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in extraction and purification. The vendor base stratifies between asset-heavy Nordic pulp operators and asset-light toll processors. Three archetypes dominate: integrated biorefinery operators with captive black liquor supply, specialty chemical firms accessing capacity through processing agreements, and regional distributors managing formulation technical service. Capacity expansion and strategic partnerships represent the dominant competitive moves, with retrofit investments competing against greenfield biorefinery development.
Among Nordic integrated operators, Borregaard AS and Stora Enso exemplify the upstream concentration of pharmaceutical-grade purification expertise. Borregaard's Norwegian soda lignin infrastructure anchors GMP-standard output, while Stora Enso's Sunila biorefinery integration secures European supply chain continuity. UPM Biochemicals occupies a downstream hub position at Leuna, representing the toll-processing facilitation model that allows specialty chemical firms to access biorefinery capacity without pulp mill asset ownership.
| Leading Market Players |
|---|
| Borregaard AS |
| Stora Enso |
| Domtar Corporation |
| Nippon Paper Industries Co., Ltd. |
| Sappi Ltd |
| UPM Biochemicals |
| Ingevity |
| Rayonier Advanced Materials |
| Lenzing |
| Others |
Cost & Logistics Intelligence
Finnish and Swedish biorefinery undercapacity signals are tightening pharmaceutical-grade lignin premiums as black liquor diversion to material extraction competes with energy recovery obligations. Pulp operators with integrated extraction capability command pricing leverage over German compounders absorbing transport premiums for GMP-certified supply chains.
Pricing Analysis
Configured-to-order pricing for GMP-grade soda lignin carries substantial premiums over standard kraft lignin spot transactions. Three-tier pricing structure across pharmaceutical-grade, carbon fiber precursor, and commodity construction tiers reflects REACH registration transferability and ash content thresholds. Pricing pressure stems from EPA biofuel pathway approvals redirecting pyrolysis intermediates toward renewable diesel pools. Construction admixture formulators exhibit highest price sensitivity, while aerospace compounders prioritize batch consistency over unit economics.
Supply Chain Analysis
Extended payment terms from Nordic integrated biorefineries are squeezing toll-processor working capital requirements across European distribution channels. Supply concentrates in Finland, Sweden, and the United States as sulfate pulp mill clusters anchor technical lignin origination. Feedstock draws from eucalyptus plantations in Brazil and softwood forests in Scandinavia and North America. Single-source vulnerability runs through Borregaard's Norwegian GMP purification infrastructure. Distribution runs through long-term offtake agreements for pharmaceutical and carbon fiber grades, with regional distributors managing construction admixture logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards scarce GMP purification expertise and integrated black liquor access, with capability gaps concentrated in pharmaceutical-grade refinement and continuous flow organosolv scale-up. Incumbents must pre-emptively secure these assets before regulatory timelines compress further.
For Market Incumbents: Pre-empt capacity constraints by locking long-term black liquor supply agreements with Finnish and Swedish pulp operators before EU Green Deal enforcement tightens feedstock competition. Backward integration into continuous flow organosolv systems defends margin position against Japanese carbon fiber precursor qualification demands. Prioritize REACH registration dossier preparation for novel derivatives to compress 18-36 month qualification cycles. For New Entrants and Emerging Players: Pursue toll-processing facilitation models that access Nordic biorefinery capacity without pulp mill capital deployment, targeting Indian construction admixture markets where BIS certification creates first-mover compliance advantages. Native lignin bioplastics compounding offers penetrable white space as food-contact and medical-grade processors seek unaltered macromolecular architecture. Lead with formulation technical service capabilities rather than asset-heavy extraction investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across toll-processing facilitation models as asset-light agreements displace greenfield biorefinery development. Long-term viability favors platform integrators with captive Nordic supply access and GMP certification transferability. Acquisition targets include regional distributors with BIS qualification progress in India and continuous flow technology specialists serving Japanese aerospace compounders. Signal to watch: EPA reclassification of pyrolysis oil co-products between renewable fuel pools and material-use premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Black Liquor Supply Agreement | Secures upstream feedstock access for German bioplastics compounders facing EU Green Deal restrictions. |
| Continuous Flow Organosolv Scale-Up | Enables real-time molecular weight monitoring for Japanese carbon fiber precursor qualification. |
| REACH Registration Dossier Investment | Compresses product qualification timelines for novel lignin derivatives in European markets. |
| BIS Certification Facilitation | Creates compliance threshold exploitation for Indian construction admixture market establishment. |
| Toll-Processing Platform Expansion | Allows specialty chemical firms to access Nordic biorefinery capacity without pulp mill ownership. |
Research Approach
The analysis maps kraft lignin, organosolv lignin, lignin sulfonates, and native lignin sub-sectors, each validated through biorefinery operations directors, downstream polymer compounder procurement leads, pharmaceutical API manufacturer technical directors, and construction admixture formulator R&D heads. Secondary sources include ECHA REACH registration databases, EPA biofuel pathway approval records, BIS certification protocols, customs and trade flow data, and integrated pulp mill sustainability disclosures. Bottom-up capacity assessments and top-down demand modeling were triangulated across extraction technology routes and application-grade specifications.
Assumption sets held Nordic pulp cluster integration rates and EU Green Deal enforcement timelines fixed while varying natural gas pricing volatility, pyrolysis oil co-product reclassification scenarios, and Indian infrastructure investment trajectories. The analytical framework segments by product type, application, end user, and distribution channel across the projection horizon. CAGRs were derived from volume-weighted capacity expansion schedules and price elasticity estimates for pharmaceutical-grade versus commodity tiers. Industry-specific inputs included black liquor processing economics and carbon fiber precursor qualification timelines.
Sensitivities concentrate around EPA regulatory reclassification of pyrolysis intermediates, EU REACH timeline compression, and Nordic biorefinery energy-versus-material allocation decisions. Forecasts reflect documented assumptions on pulp mill retrofit rates and downstream polymer substitution economics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Soil Hardening Agent Market