
 Soap Noodles Market | 2026-2036
Soap Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Soap Noodles Market Analysis
RSPO certification is rotating competitive access in the soap noodles industry, filtering out uncertified palm oil processors from premium supply chains. KLK Oleo leverages its Malaysian plantation base to sustain integrated feedstock security from crude palm oil to finished soap noodles. Wilmar International Ltd. anchors volume throughput across Southeast Asian oleochemical hubs with multi-country refining footprints. IOI Oleochemicals differentiates through specialty-grade production serving European personal care brands with strict traceability requirements.
Soap noodles are intermediate alkali-treated fatty acid pellets, typically containing 78-82% total fatty matter, manufactured via saponification or neutralization of vegetable oils and animal fats for downstream bar soap production. Transparent Soap Noodles command premium positioning in Southeast Asian retail channels where visual clarity signals glycerin enrichment and perceived quality. Sodium Palmate formulations dominate bulk industrial procurement due to cost-efficient palm oil feedstock availability, though Organic Soap Noodles are gaining fastest traction among European personal care brands seeking COSMOS-compliant inputs.
Malaysia's MEE enforces wastewater discharge standards on oleochemical plants that elevate capital costs for soap noodle producers operating near sensitive waterways. Indonesia's SAMR aligns with GB-equivalent import standards that Chinese soap manufacturers must satisfy when sourcing noodle intermediates. REACH registration requirements in Europe restrict certain palm derivative classifications unless full supply chain documentation accompanies shipments. Stakeholders must monitor how emerging deforestation regulations in multiple jurisdictions will cascade into mandatory geolocation verification for every oil palm batch entering soap noodle production.
Market Dynamics
RSPO certification mandates are restructuring feedstock access across Southeast Asian soap noodle supply chains, forcing processors to invest in segregated palm oil sourcing or exit premium personal care procurement channels entirely.
Growth Catalysts
- EU Deforestation Regulation (EUDR):Mandatory geolocation verification for palm oil imports is accelerating RSPO-certified soap noodle adoption among European personal care brands seeking compliant supply chains.
- Glycerin retention technology:Advanced saponification processes enabling higher glycerin content in transparent soap noodles are capturing premium positioning in Southeast Asian retail channels.
- India's BIS fatty acid mandates:Revised import specifications for soap noodle composition are redirecting procurement toward certified Malaysian and Indonesian suppliers with verified laboratory documentation.
Market Restraints
- Crude palm oil price volatility:Feedstock cost swings of 15-30% within single quarters compress margin predictability for soap noodle producers lacking long-term plantation contracts.
- Peninsular Malaysia supply concentration:Over 60% of certified segregated processing capacity clusters within 200km of Port Klang, creating single-point vulnerability for premium-grade procurement.
- Technical limitation in tallow substitution:Vegetable-only formulations struggle to replicate the hardness and lather stability of tallow-palm blends in certain industrial laundry applications.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya present white space for RSPO-certified soap noodle penetration as urban personal care brands formalize supply chain traceability requirements.
- India's PLI scheme for oleochemicals:Production-linked incentives for domestic fatty acid processing are attracting greenfield investment in integrated soap noodle manufacturing.
- COSMOS certification convergence:Organic soap noodles meeting both COSMOS and RSPO standards command 40-60% premiums in German and French natural cosmetics channels.
Industry Challenges
- RSPO segregation audit timelines:Certification body backlogs extending 8-14 months delay market entry for new processing facilities seeking premium supply chain status.
- Legacy saponification equipment retrofit costs:Conventional plants require $2-4 million capital injection to achieve EUDR-compliant traceability systems and wastewater treatment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soap Noodles Market |
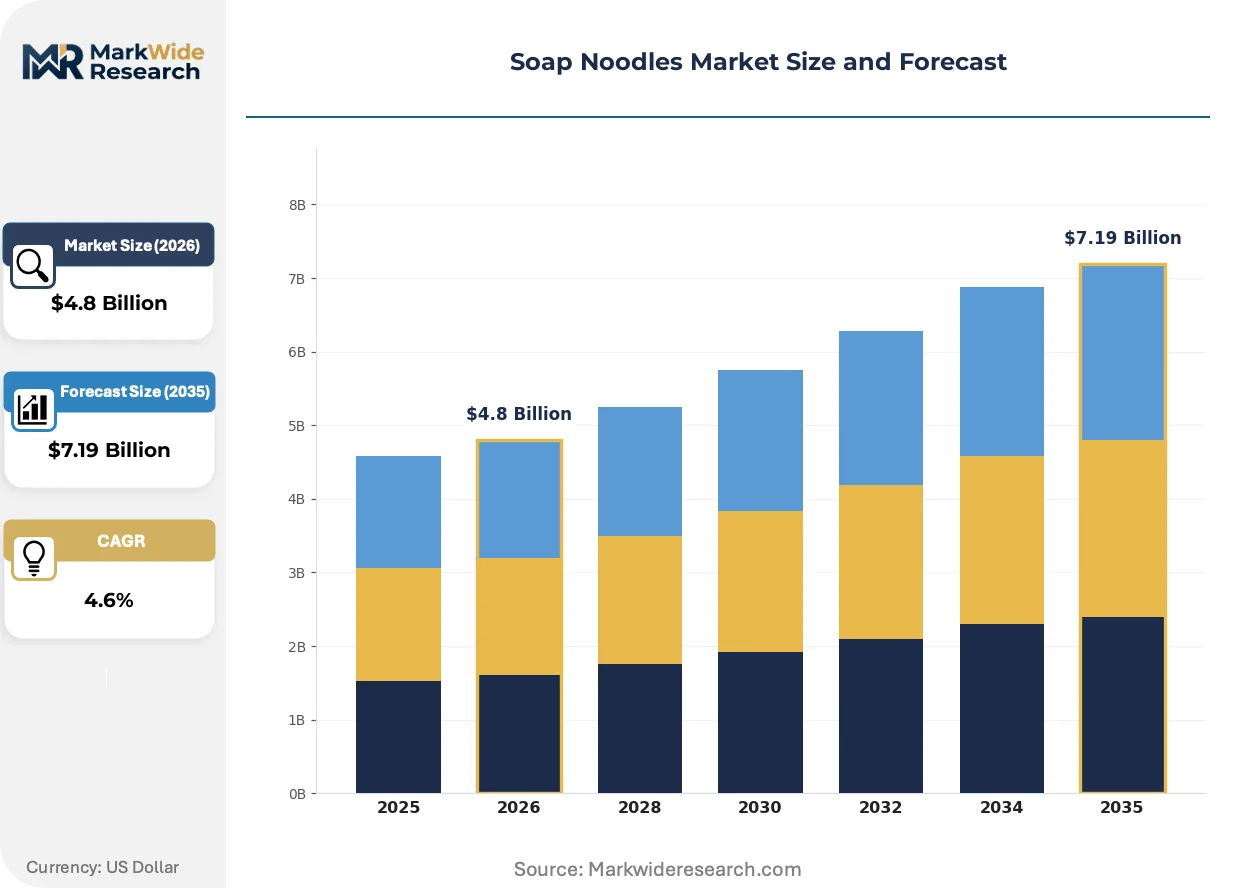
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Soap Noodles, Glycerin Soap Noodles, Organic Soap Noodles, Specialty Soap Noodles Formulation: Free Fatty Acids, Sodium Tallowate, Sodium Cocoate, Sodium Palmate End User: Household, Commercial, Industrial, Personal Care Brands Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | KLK Oleo, Timur Oleochemicals, Wilmar International Ltd., Jocil Limited, Olivia Impex Pvt Ltd, IOI Oleochemicals, Musim Mas Holdings, John Drury & Co Ltd, EVYAP-OLEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soap Noodles Market Emerging Trajectories
Digital traceability platforms and enzymatic processing methods are compressing certification timelines while enabling novel fatty acid compositions previously unattainable through conventional saponification chemistry.
Enzymatic interesterification is miniaturizing the molecular architecture of soap noodle fatty acid profiles, enabling custom-tailored melting points and foam characteristics. Specialty personal care brands in Germany and France are adopting these precision-formulated intermediates for artisanal bar soap lines. The technology is miniaturizing batch-to-batch variation, reducing reformulation cycles from months to weeks.
REACH registration requirements for palm-derived intermediates are tightening documentary burden on non-European suppliers seeking European personal care market access. ECHA's updated guidance on Substance Identity Profiles demands full supply chain disclosure down to plantation coordinates. Small and mid-scale Malaysian processors lacking dedicated regulatory affairs functions are outsourcing compliance to specialized consulting firms.
Brand procurement teams are consolidating supplier relationships from 8-12 vendors to 3-4 strategic partners with integrated RSPO certification and laboratory capabilities. This concentration is compressing spot-market trading volumes in favor of multi-year framework agreements with price adjustment mechanisms. The shift is most visible in Netherlands and UK personal care manufacturing, where sustainability scorecard weighting now exceeds 30% in vendor selection matrices.
Soap Noodles Market Segmentation
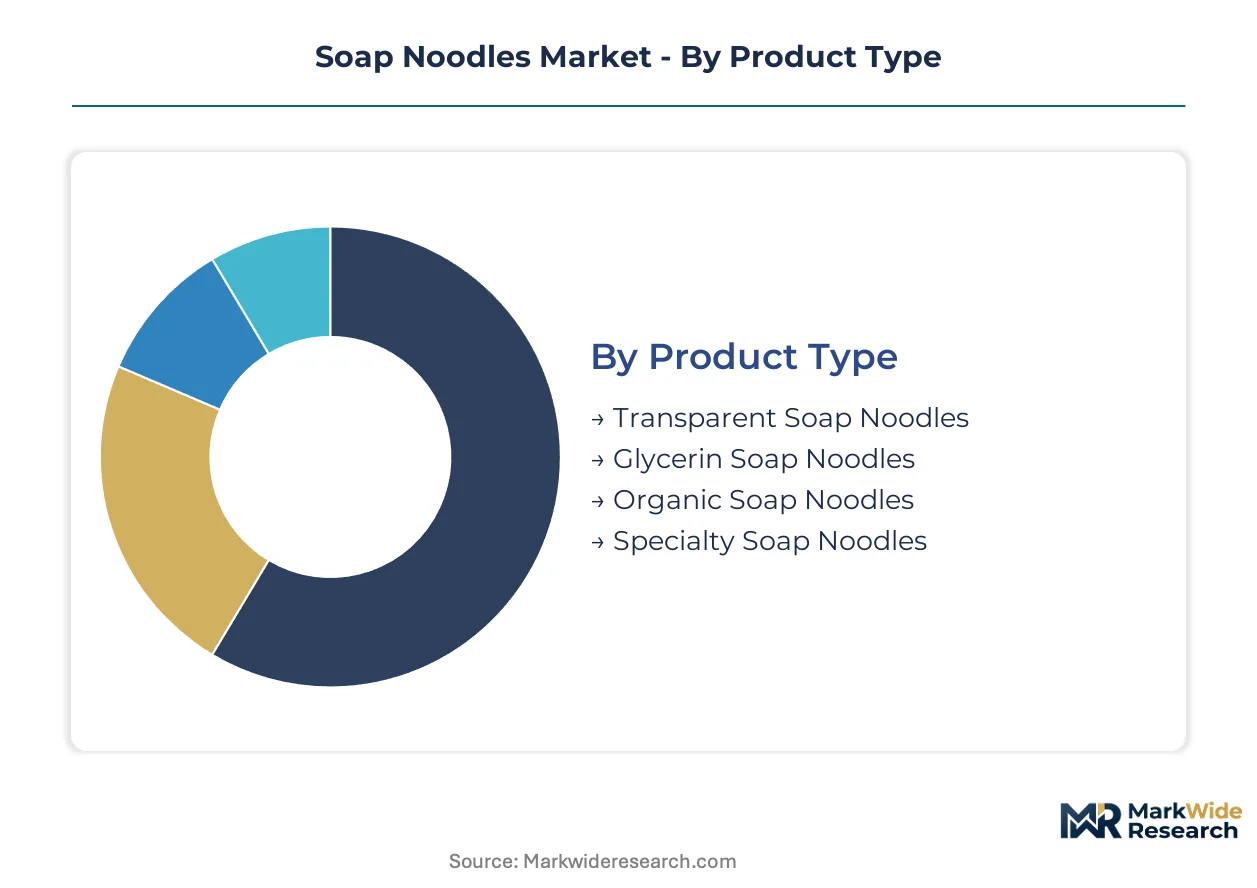
Soap noodle procurement patterns diverge sharply between commodity bulk buyers and specialty personal care formulators, with certification requirements and glycerin content driving tiered pricing structures. Segmentation reveals how feedstock origin and processing technology create distinct competitive battlegrounds across downstream applications.
Product Type:
Transparent Soap Noodles dominate Southeast Asian domestic consumption, while Organic Soap Noodles anchor European export demand tied to RSPO certification requirements.
- Transparent Soap Noodles:These alkali-treated pellets retain 15-20% glycerin content, creating visual clarity that signals premium quality in Thai and Indonesian retail channels. Malaysian processors near Port Klang supply 70% of regional transparent grade volume, though glycerin retention technology upgrades require $2-4 million capital injection per facility.
- Organic Soap Noodles:COSMOS-compliant production restricts synthetic additives and mandates palm oil traceability to plantation coordinates. German and French natural cosmetics brands absorb 60% of global organic grade output, paying 40-60% premiums over conventional noodles.
- Glycerin Soap Noodles:High-humectant formulations serve medicated and moisturizing bar applications in India's urban centers.
- Specialty Soap Noodles:Custom fatty acid profiles target artisanal soapmakers requiring precise melting points.
Transparent Soap Noodles holds the largest share; momentum sits with Organic Soap Noodles.
Formulation:
Cost tiers separate plantation-integrated sodium palmate from tallow-dependent alternatives facing feedstock volatility.
- Sodium Palmate:Palm oil-derived formulations supply 80% of industrial laundry and bulk toilet soap production. Indonesia's Musim Mas and Malaysia's KLK Oleo leverage integrated plantation-to-noodle processing, insulating margin structures from CPO price swings that compress competitors lacking long-term feedstock contracts.
- Free Fatty Acids:Acid-neutralized intermediates enable custom superfatting levels for premium personal care applications. Specialty brands in Netherlands and UK specify FFA grades for artisanal production, though REACH registration burdens disadvantage non-European suppliers lacking dedicated regulatory affairs functions.
- Sodium Tallowate:Animal fat-based hardness and lather stability persist in industrial cleaning segments where vegetable-only substitutes underperform.
- Sodium Cocoate:Coconut oil formulations deliver superior foam volume for facial cleansing bars in Philippines and Vietnam markets.
Sodium Palmate commands volume leadership; Free Fatty Acids climb the fastest on premium personal care demand.
End User:
Customer concentration patterns split between fragmented household procurement and consolidated personal care brand supply chains.
- Personal Care Brands:Unilever, Procter & Gamble, and regional champions like Wipro Consumer Care consolidate supplier relationships from 8-12 vendors to 3-4 strategic partners with integrated RSPO certification. Sustainability scorecard weighting exceeds 30% in vendor selection matrices for Netherlands and UK manufacturing operations.
- Industrial:Laundry soap manufacturers and textile processing facilities prioritize sodium palmate cost efficiency over certification documentation. Nigerian and Kenyan buyers represent white space penetration opportunity as urban formalization accelerates traceability requirements.
- Household:Small-scale bar soap producers in India's informal sector drive spot-market trading volumes.
- Commercial:Hotel and institutional procurement emphasizes bulk pricing with minimal specification variance.
Personal Care Brands concentrate purchasing power; Industrial end users expand most quickly in African markets.
Distribution Channel:
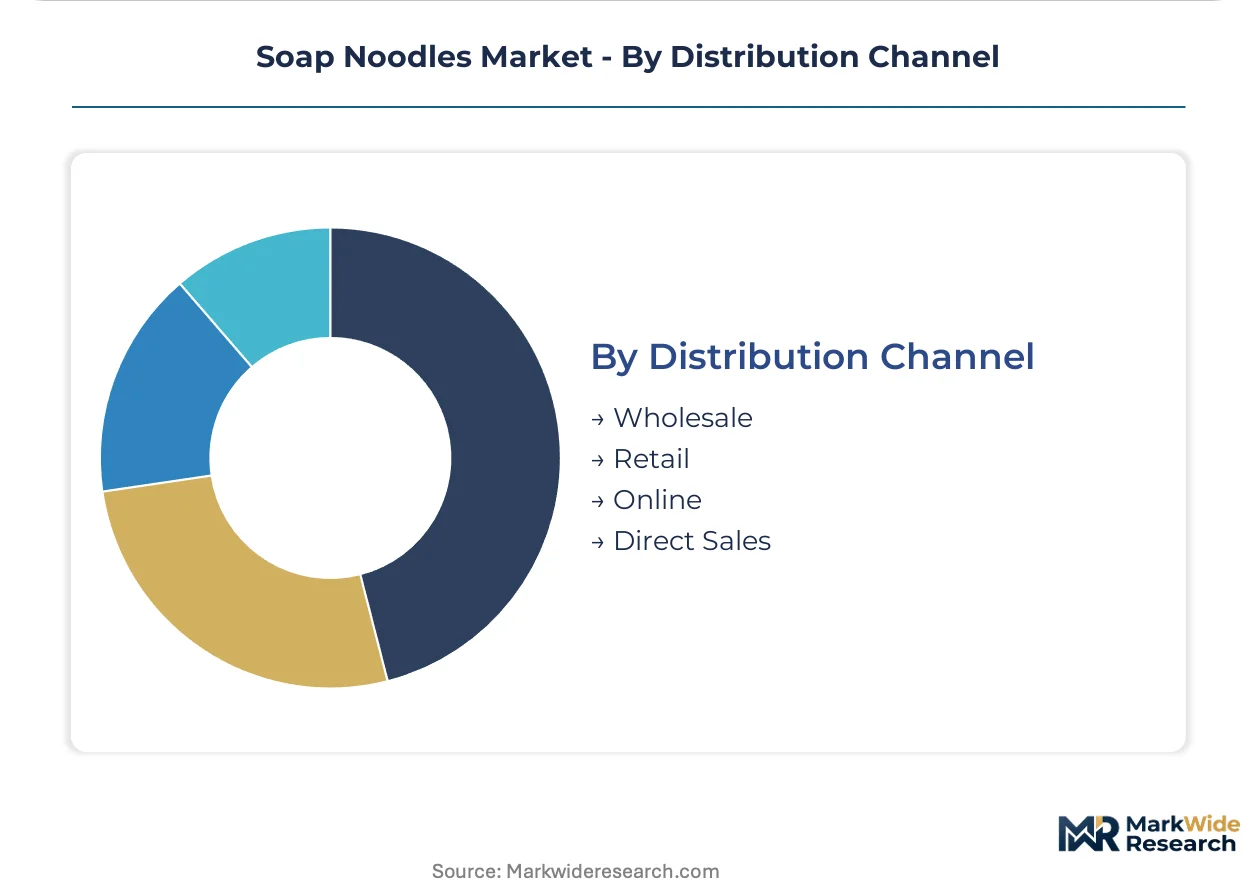
Supply chain configuration shifts from spot-market fragmentation toward multi-year framework agreements with embedded price adjustment mechanisms.
- Direct Sales:Integrated oleochemical producers bypass intermediaries for personal care brand relationships requiring laboratory documentation and batch-specific traceability. KLK Oleo and IOI Oleochemicals anchor volume through direct technical service teams co-located with major customers.
- Wholesale:Commodity-grade sodium palmate moves through Port Klang and Jakarta distribution hubs serving industrial laundry compounders. Spot-market liquidity compresses as certification requirements filter uncertified processors from premium channels.
- Retail:Small-batch specialty noodles reach artisanal soapmakers through chemical supply distributors.
- Online:Digital platforms facilitate sample procurement and technical documentation exchange for new supplier qualification.
Direct Sales captures the highest margin relationships; Wholesale retains volume dominance in commodity grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Personal care brand procurement teams in Germany, India, Indonesia, Malaysia, and the United States drive differentiated sourcing strategies based on certification requirements and feedstock proximity.
Germany
Natural cosmetics manufacturers in Hamburg and Düsseldorf anchor European demand for COSMOS-compliant organic soap noodles. ECHA's REACH registration requirements enforce full supply chain documentation down to plantation coordinates for palm-derived intermediates. Specialty chemical distributors in the Rhine-Ruhr region consolidate procurement relationships with Malaysian RSPO-certified processors.
India
Urban personal care brands in Mumbai and Delhi-NCR expand procurement of certified soap noodles as BIS fatty acid composition mandates reshape import specifications. The PLI scheme for oleochemicals attracts greenfield investment in integrated domestic manufacturing. Gujarat's Mundra port cluster processes rising volumes of Malaysian and Indonesian noodle shipments for northern industrial laundry compounders.
Indonesia
SAMR-aligned import standards position Indonesian processors as compliant suppliers to Chinese soap manufacturers seeking GB-equivalent documentation. Musim Mas Holdings leverages integrated plantation-to-noodle processing in Riau and North Sumatra to insulate margins from crude palm oil volatility. Surabaya's oleochemical corridor attracts capacity expansion targeting premium personal care export channels.
Malaysia
KLK Oleo and IOI Oleochemicals anchor production gravity around Port Klang, where over 60% of certified segregated processing capacity clusters within 200 kilometers. MEE wastewater discharge standards elevate capital costs for facilities operating near sensitive waterways in Selangor and Johor. Penang-based technical service teams co-locate with European brand procurement offices to accelerate RSPO certification documentation.
United States
Industrial laundry compounders in Texas and Ohio prioritize sodium palmate cost efficiency over certification documentation for bulk institutional procurement. FDA cosmetic ingredient regulations shape import documentation requirements for specialty-grade noodles entering personal care manufacturing. California's natural cosmetics formulators in Los Angeles County drive niche demand for transparent and glycerin-enriched grades.
Soap Noodles Market Vendor Landscape
Player mix skews toward plantation-integrated processors with captive feedstock security, creating a tiered structure where certification capability separates premium from commodity supply tiers. Mid-scale independent processors lacking long-term crude palm oil contracts face margin compression during feedstock price swings. Two strategic archetypes dominate: vertically integrated plantation-to-noodle operators and specialty-grade producers with dedicated regulatory affairs functions. Competitive moves concentrate on segregated supply chain investments and multi-year framework agreements with embedded traceability systems.
Within the plantation-integrated tier, KLK Oleo and Wilmar International Ltd. exemplify feedstock security strategies that buffer margin structures from commodity volatility. IOI Oleochemicals occupies a position representing specialty-grade production capabilities serving European personal care channels with stringent documentation requirements. Among Malaysia-based processors, these three entities anchor distinct competitive vectors: integrated upstream control, multi-country refining scale, and precision-formulated output for traceability-sensitive buyers.
| Leading Market Players |
|---|
| KLK Oleo |
| Timur Oleochemicals |
| Wilmar International Ltd. |
| Jocil Limited |
| Olivia Impex Pvt Ltd |
| IOI Oleochemicals |
| Musim Mas Holdings |
| John Drury & Co Ltd |
| EVYAP-OLEO |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day inventory cycles among Malaysian processors amplify pricing power for RSPO-certified segregated supply chains while compressing margins for spot-market dependent competitors. This lead-time band concentrates procurement leverage with plantation-integrated operators who index contracts to crude palm oil futures, leaving independent processors exposed to feedstock volatility.
Pricing Analysis
Cost-plus contracts with monthly crude palm oil indexation dominate procurement relationships between Malaysian processors and European personal care brands. Three-tier pricing structure across premium certified, standard segregated, and economy spot-market levels separates RSPO-compliant noodles commanding premiums from uncertified commodity grades. Pricing pressure stems from CPO futures volatility that compresses margins for processors lacking long-term plantation offtake agreements. Industrial laundry compounders exhibit highest price sensitivity, while German natural cosmetics brands absorb premiums for COSMOS-compliant traceability documentation.
Supply Chain Analysis
Strategic stockpiling of certified segregated palm oil characterizes procurement behavior among European personal care brands preparing for EUDR enforcement, contrasting with just-in-time spot purchasing in industrial segments. Supply concentrates in Malaysia, Indonesia, and India, with over sixty percent of certified segregated processing capacity clustering near Port Klang. Raw material dependencies center on crude palm oil, palm kernel oil, and coconut oil feedstocks. Single-source vulnerability emerges from Peninsular Malaysia's geographic concentration of RSPO-certified facilities. Distribution runs through direct technical service relationships for premium grades and Port Klang wholesale hubs for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as digital traceability systems become the interoperability layer connecting plantation coordinates to finished noodle batches. RSPO certification bodies and EUDR geolocation platforms constitute the emerging ecosystem infrastructure reshaping market access.
For Market Incumbents: Compound certification advantages by extending segregated supply chain investments into enzymatic processing capabilities that miniaturize batch-to-batch variation. Defend against specialty-grade entrants by co-locating technical service teams with European brand procurement offices. Prioritize backward integration into plantation traceability systems that satisfy emerging deforestation regulations.
For New Entrants and Emerging Players: Anchor in African white-space markets where Nigerian and Kenyan urban personal care brands are formalizing traceability requirements ahead of regulatory mandates. Target India's PLI-attracted oleochemical corridor for greenfield integrated manufacturing. Pursue COSMOS-RSPO dual certification as the primary go-to-market credential for German and French natural cosmetics channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from plantation conglomerates seeking to monetize captive oleochemical assets through partial divestiture of noodle processing divisions. Long-term viability favors operators with integrated feedstock security and dedicated regulatory affairs functions capable of navigating REACH documentation burdens. Watch RSPO segregation audit backlogs as the inflection signal indicating certification capacity constraints that will premium-ize compliant assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Segregated Supply Chain Investment | RSPO certification unlocks European personal care procurement channels closed to mass-balance alternatives. |
| Enzymatic Processing Adoption | Precision fatty acid tailoring commands premiums from German artisanal soapmakers requiring custom melting points. |
| Digital Traceability Platform Integration | EUDR-compliant geolocation verification becomes mandatory infrastructure for palm oil-derived intermediate exports. |
| Greenfield Capacity in India | PLI scheme incentives attract integrated manufacturing serving BIS-mandated import substitution requirements. |
| Dual Certification Convergence | COSMOS-RSPO compliance captures forty to sixty percent premiums in French natural cosmetics channels. |
Methodological Framework
The analysis maps transparent, organic, and specialty soap noodle sub-sectors, each validated through procurement directors at personal care brands, oleochemical plant managers, RSPO certification auditors, and European regulatory affairs specialists. Primary interview insights triangulate against customs trade databases, BIS import specification filings, ECHA REACH registration records, and plantation sustainability disclosure reports. Bottom-up capacity modeling and top-down demand estimation converge through cross-referencing processor output data with downstream bar soap production volumes.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation across product type, formulation chemistry, end-user industry, and distribution channel, with regional regulatory cluster as an additional dimension. CAGRs derive from feedstock price trajectory assumptions, certification adoption curves, and substitution elasticity estimates between vegetable and tallow-based formulations.
Material uncertainties — crude palm oil price volatility, RSPO audit backlog durations, EUDR enforcement timing — sit outside the modeled envelope. Forecasts reflect assumptions about certification penetration rates and regulatory harmonization across jurisdictions. Revision becomes warranted when deforestation regulation enforcement intensity crosses thresholds that accelerate supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Europe Isocyanates Market