
 Industrial Explosives Market | 2026-2036
Industrial Explosives Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Explosives Market Intelligence
Project finance tied to long-term offtake agreements is narrowing the field of viable competitors in industrial explosives. Orica Ltd. leverages its integrated manufacturing and distribution network across Australasia to sustain pricing power in bulk emulsion contracts. MaxamCorp International SL anchors its position through deep backward integration into nitrate chemical production, while Solar Industries India Ltd. competes aggressively on government infrastructure and coal mining tenders.
Industrial explosives are chemical formulations designed to release controlled energy through detonation, typically comprising oxidizers such as ammonium nitrate blended with fuels and sensitizers to achieve specific velocity of detonation and bulk strength parameters for rock fragmentation. Their primary commercial purpose is to reduce competent rock and overburden to transportable dimensions in mining, quarrying, and civil excavation. Ammonium nitrate and emulsified explosives dominate volume flows in surface mining, where bulk delivery modes generate the deepest margin pools due to reduced packaging and labor intensity. Packaged explosives retain structural importance in underground and specialized demolition applications where precise initiation timing and confined-space safety override unit cost considerations.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives and Australia's Work Health and Safety regulators enforce stringent licensing, storage, and chain-of-custody rules that elevate compliance costs and favor established distributors with captive security infrastructure. The EU's REACH framework and the UN Recommendations on the Transport of Dangerous Goods further constrain formulation flexibility and cross-border shipment economics. Stakeholders must monitor evolving restrictions on nitrate precursor chemicals while assessing whether on-site manufacturing partnerships can neutralize transport regulatory burdens.
Market Dynamics
Bulk emulsion delivery systems are compressing the economics of surface blasting by eliminating packaged product handling and enabling on-site mixing at Australian and Chilean mine sites. This shift concentrates margin capture with manufacturers possessing integrated distribution infrastructure.
Growth Catalysts
- Pilbara iron ore expansion:Western Australia's high-grade hematite deposits require deep-hole blasting with high-bulk-strength formulations, pulling emulsion volumes upward.
- REACH precursor tracking:The EU's tightened nitrate supply-chain monitoring is formalizing procurement relationships with certified distributors, locking in contract volumes.
- Underground mechanization:Automated loading in Canadian and Swedish metal mines is expanding packaged explosive consumption for precise perimeter control.
Market Restraints
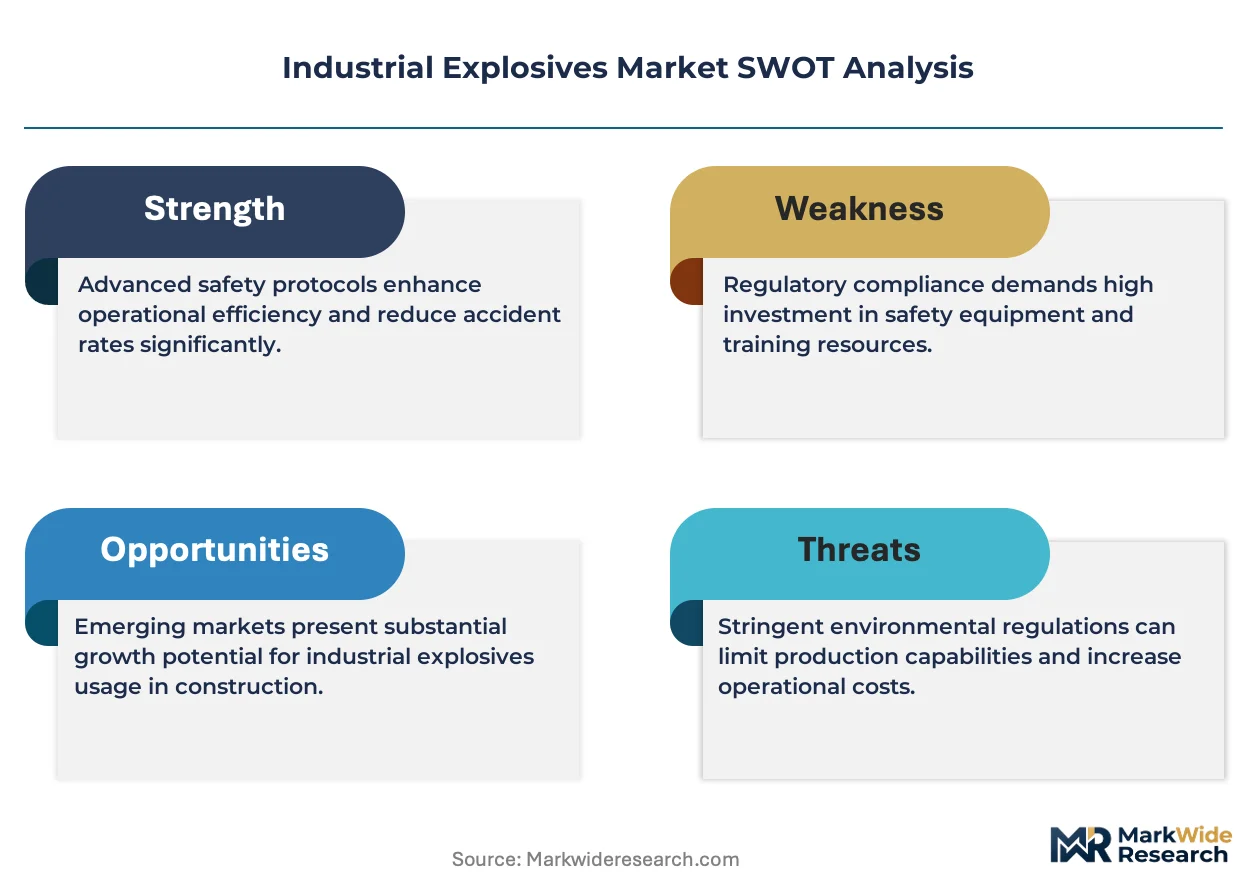
- Ammonium nitrate price volatility:Natural gas feedstock swings and fertilizer market competition compress formulation margins unpredictably.
- Transport regulatory burden:Australia's Work Health and Safety protocols for ammonium nitrate storage and movement impose fixed compliance costs that disadvantage small regional distributors.
- Mechanical rock breaking:Hydraulic hammers and surface miners in European limestone quarries substitute explosives in selective extraction applications.
Strategic Opportunities
- On-site manufacturing partnerships:Mobile emulsion plants at remote Indonesian nickel and copper operations neutralize cross-border shipment restrictions.
- Copper porphyry development:Chilean and Peruvian greenfield projects favor bulk delivery contracts with decade-long offtake structures.
- Digital blasting optimization:Integration of electronic detonators with mine planning software enables precision fragmentation and downstream processing savings.
Industry Challenges
- Shot firer certification pipelines:Australia's state-level licensing requirements create bottlenecks for expanding underground crews at Pilbara and Bowen Basin operations.
- Legacy inventory reconciliation:Tracking packaged product shelf life and lot numbers across dispersed storage depots demands upgraded ERP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Explosives Market |
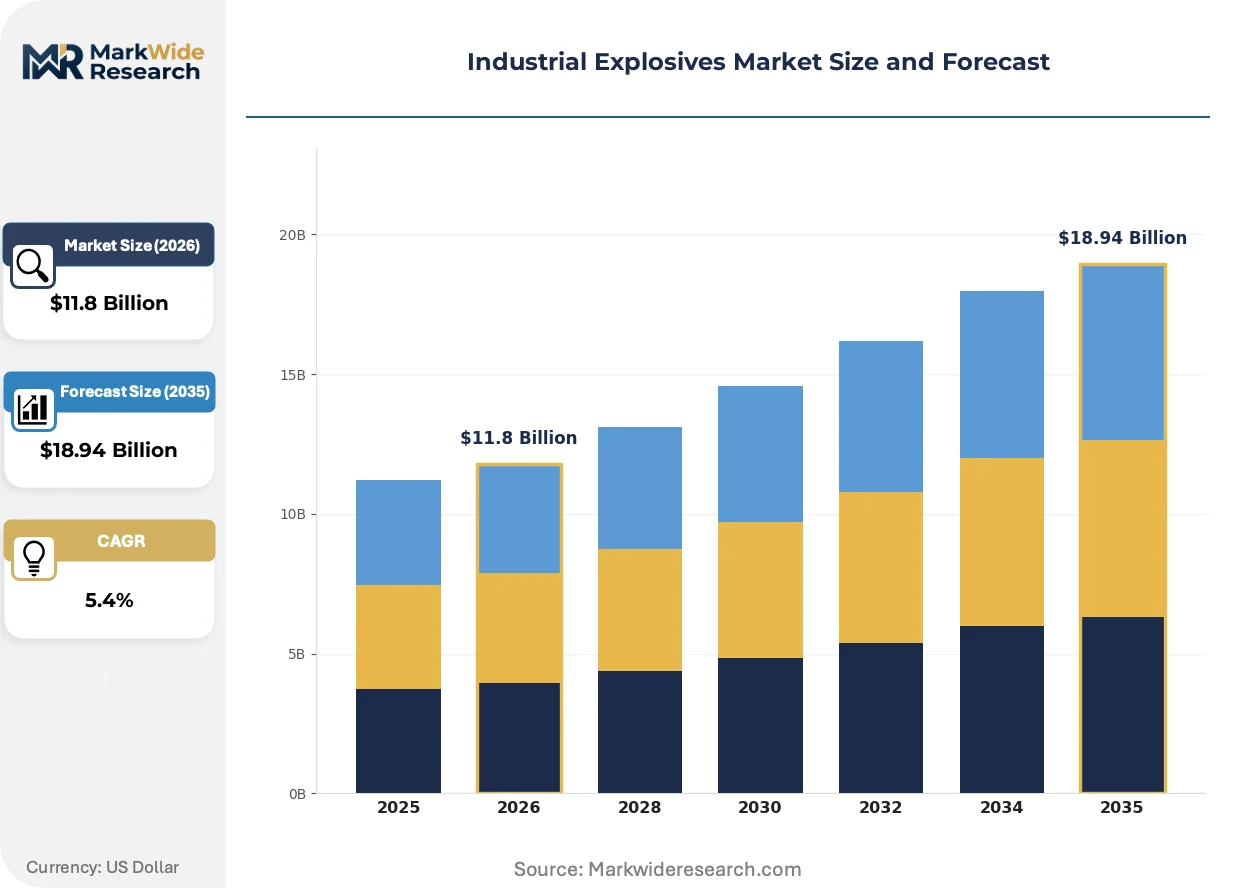
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ammonium Nitrate, Emulsified Explosives, Water Gels, ANFO Application: Mining, Construction, Quarrying, Demolition Delivery Mode: Bulk, Packaged, Pre-Loaded, On-Site End User: Mining Companies, Construction Firms, Oil & Gas, Military |
| Companies Covered | Austin Powder Company, NOF Corporation, Orica Ltd., MaxamCorp International SL, Solar Industries India Ltd., Enaex S.A., Dyno Nobel Inc., Incitec Pivot Limited, AECI Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Explosives Market Strategic Shifts & Innovations
Electronic initiation systems are displacing pyrotechnic detonators across major mining jurisdictions, enabling millisecond-precision timing that reduces vibration and improves fragmentation. This hardware shift is reshaping supplier relationships toward integrated blasting service contracts.
Heavy ANFO blends—combining ammonium nitrate fuel oil with emulsion matrices—are collapsing the cost-per-tonne economics of dry-hole blasting in Australian and Brazilian iron ore operations. Surface miners in the Pilbara and Carajás districts are adopting these formulations for wet-season reliability. The technology is collapsing the historical premium between packaged and bulk product categories.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives has expanded background-check requirements for explosive precursor purchases, extending compliance timelines for new market entrants. Industrial buyers are consolidating supplier relationships to reduce audit exposure. Underground coal operators in Appalachia and the Powder River Basin are prioritizing distributors with captive ATF-compliant security infrastructure.
Long-term offtake contracting is replacing spot procurement in copper and iron ore blasting services, compressing supplier margins in exchange for volume guarantees. Major miners in Chile and Western Australia are unbundling explosives supply from drilling and loading services to capture separate cost lines. This pattern is most pronounced where project finance structures require input cost visibility across multi-year development phases.
Industrial Explosives Market Segmentation
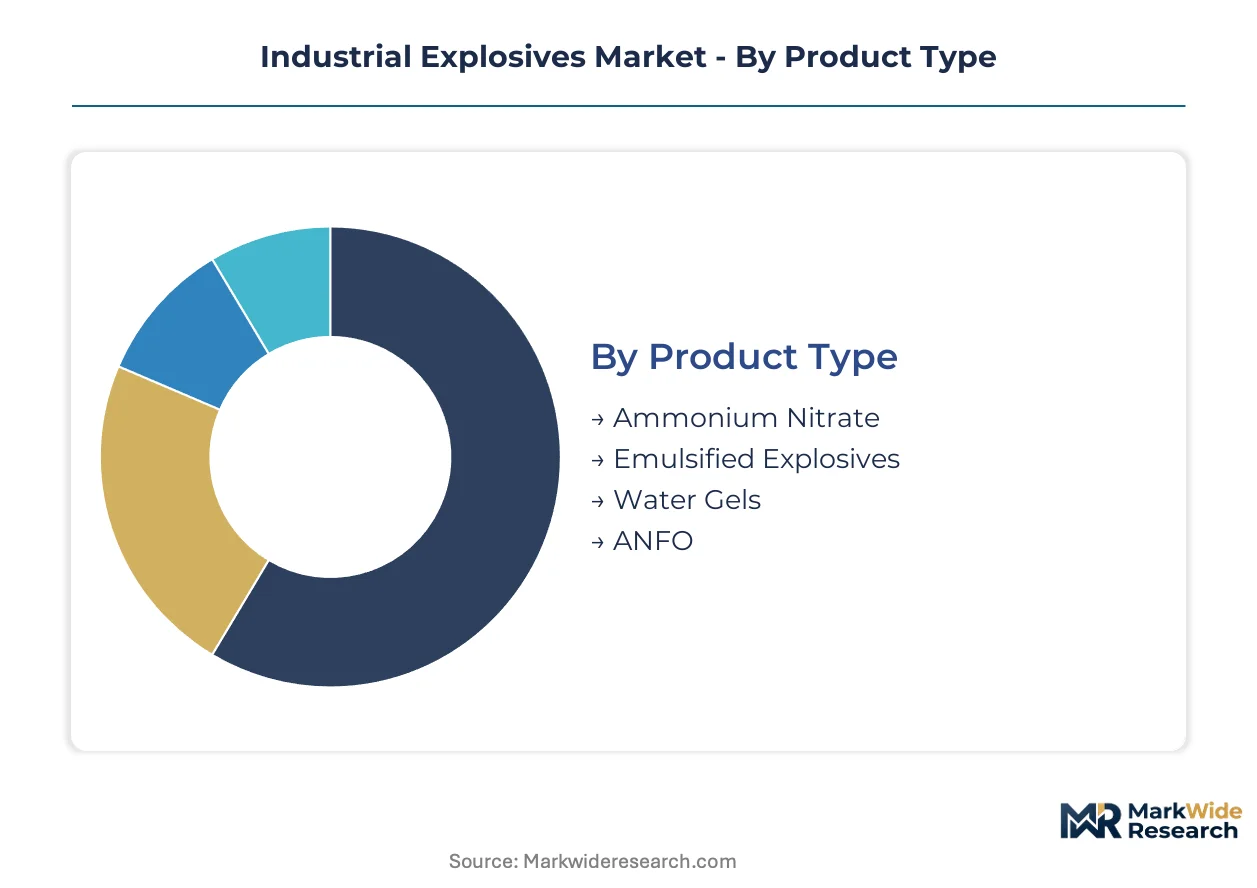
Industrial explosives segment along four critical dimensions that determine margin structure, regulatory exposure, and supplier relationships. Product chemistry dictates storage and transport compliance burdens. Application mix shapes volume predictability and contract duration. Delivery mode separates bulk commodity plays from service-integrated offerings.
Product Type:
Mature commodity formulations dominate volume flows while engineered emulsions capture premium pricing in demanding geologies.
- Ammonium Nitrate:The foundational oxidizer serves as both standalone blasting agent and feedstock for downstream formulations. Western Australia's Pilbara iron ore district pulls substantial volumes for ANFO blending at mine sites, though fertilizer market competition for the same chemical feedstock creates margin compression during planting seasons.
- Emulsified Explosives:Water-in-oil matrix suspensions of ammonium nitrate solution within hydrocarbon fuels achieve superior water resistance and velocity of detonation control. Chilean copper porphyry operations specify these formulations for wet-hole reliability in high-altitude Andean deposits where seasonal rainfall penetrates blast patterns.
- Water Gels:Cross-linked aqueous solutions of ammonium nitrate with gelling agents and aluminum powder sensitizers bridge performance between ANFO and emulsions. Civil tunneling contractors in the Swiss Alps specify these for controlled fragmentation in fractured limestone.
- ANFO:Simple 94/6 ammonium nitrate/fuel oil blends remain the lowest-cost option for dry surface blasting. Powder River Basin coal operators in Wyoming consume substantial volumes where hole conditions permit unsensitized loading.
Emulsified explosives handles the majority of throughput; ANFO is the fastest mover on share as cost pressure intensifies in bulk surface mining.
Application:
Volume concentrates in extraction industries while specialized demolition commands price premiums through technical complexity.
- Mining:Surface and underground hard-rock extraction consumes the dominant share of industrial explosives globally. Western Australia's hematite and Western Canada's potash deposits specify bulk emulsion delivery with electronic initiation for optimized fragmentation.
- Construction:Tunneling, road cuts, and foundation excavation require packaged products with precise timing control. Alpine rail tunnel projects in Austria and Norway drive consumption of water-gel and emulsion cartridges for perimeter blasting.
- Quarrying:Dimension stone and aggregate operations favor ANFO in dry conditions and heavy ANFO blends during wet seasons. Brazilian granite quarries in Minas Gerais state specify these formulations for block recovery.
- Demolition:Structural implosion and precision rock removal demand specialized packaged explosives with millisecond-delay capabilities. Urban renewal projects in Singapore and Dubai drive demand for vibration-controlled solutions.
Mining commands the dominant volume position; construction is expanding most quickly as infrastructure investment accelerates tunneling activity.
Delivery Mode:
Supply chain configuration separates capital-intensive bulk systems from flexible packaged distribution networks.
- Bulk:Unpackaged emulsion and ANFO delivered by pump trucks directly into blastholes eliminates packaging costs and labor. Integrated manufacturers with captive distribution fleets capture margin advantages in Australian and Chilean iron ore and copper districts.
- Packaged:Cartridges, bags, and tubes of sensitised explosives serve underground and specialized applications where precise charging and storage stability matter. Canadian and Swedish metal mines specify these for automated loading systems in mechanized operations.
- Pre-Loaded:Factory-assembled explosive charges with integrated detonators reduce field preparation time. Oil and gas perforating operations in the Permian Basin and North Sea consume these for well completion efficiency.
- On-Site:Mobile manufacturing plants produce emulsion at remote mine locations, neutralizing transport regulatory burdens. Indonesian nickel operations in Sulawesi and Halmahera increasingly specify these partnerships to bypass cross-border shipment restrictions.
Bulk handles the majority of throughput; on-site is gaining share fastest as remote project development accelerates.
End User:
Customer scale and procurement sophistication determine contract structure and supplier relationship intensity.
- Mining Companies:Tier-one diversified miners and single-commodity operators drive volume through multi-year offtake agreements. BHP and Rio Tinto in Western Australia unbundle explosives supply from drilling services to capture separate cost visibility in project finance structures.
- Construction Firms:General contractors and specialized tunneling consortia purchase on project-specific schedules with shorter contract horizons. Alpine base tunnel consortia in Switzerland and Italy negotiate performance-based fragmentation contracts.
- Oil & Gas:Upstream operators consume shaped charges and perforating systems for well stimulation. Permian Basin shale operators specify pre-loaded charges for horizontal completion efficiency.
- Military:Defense procurement of bulk energetic materials and specialized munitions follows distinct security-cleared supply chains. National arsenals in the US, France, and Australia maintain captive manufacturing or sole-source relationships.
Mining companies handle the majority of throughput; construction firms are climbing the fastest on share as infrastructure investment intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian mining conglomerates and Chilean copper operators dominate procurement volumes through decade-long offtake structures. Tier-one miners in Western Australia and the Atacama Desert unbundle explosives supply from drilling services to satisfy project finance transparency requirements.
Australia
Pilbara iron ore expansion and Bowen Basin coal mechanization drive emulsion and packaged explosive consumption. Australia's Work Health and Safety regulations tighten ammonium nitrate storage and transport protocols, elevating compliance costs for regional distributors. Western Australia's Pilbara district concentrates bulk emulsion demand for deep-hole hematite blasting.
Chile
Copper porphyry greenfield developments in the Atacama and Antofagasta regions favor bulk delivery contracts with extended offtake horizons. Chile's national mining regulator enforces strict explosive precursor tracking through licensed distributor networks. The Collahuasi and Escondida clusters anchor high-altitude emulsion consumption for wet-hole reliability.
United States
Appalachian underground coal and Permian Basin oilfield perforating sustain packaged and pre-loaded charge demand. The US Bureau of Alcohol, Tobacco, Firearms and Explosives expanded background-check requirements for precursor purchases, extending compliance timelines. Wyoming's Powder River Basin and West Virginia's Monongahela field concentrate ANFO and cartridge consumption.
Canada
Mechanized underground metal mines in Ontario and Saskatchewan expand packaged explosive use for automated loading systems. Natural Resources Canada coordinates provincial blasting regulations through the Canadian Explosives Research Laboratory certification framework. The Sudbury Basin and Saskatchewan potash belt concentrate precision perimeter control applications.
Indonesia
Remote nickel and copper operations in Sulawesi and Halmahera accelerate on-site mobile emulsion plant partnerships. Indonesia's Ministry of Energy and Mineral Resources restricts cross-border explosive shipments, favoring domestic manufacturing joint ventures. The Weda Bay and Sorowako industrial corridors anchor captive production arrangements for laterite processing.
Industrial Explosives Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Integrated manufacturers with captive distribution fleets capture margin advantages in Australian and Chilean bulk markets, while regional formulators serve construction and quarrying niches. Three archetypes dominate: backward-integrated chemical producers, service-integrated blasting contractors, and regional packaged-product distributors. Capacity expansion in mobile emulsion plants and strategic partnerships for on-site manufacturing represent the primary competitive vectors.
Among Australia-based integrated operators, Orica Ltd. anchors the service-integrated tier through its manufacturing and distribution network across Australasia. Spanish chemical producer MaxamCorp International SL exemplifies backward integration into nitrate feedstock production. Indian manufacturer Solar Industries India Ltd. occupies a position within the government-tender specialist archetype, competing on coal mining and infrastructure contracts.
| Leading Market Players |
|---|
| Austin Powder Company |
| NOF Corporation |
| Orica Ltd. |
| MaxamCorp International SL |
| Solar Industries India Ltd. |
| Enaex S.A. |
| Dyno Nobel Inc. |
| Incitec Pivot Limited |
| AECI Ltd. |
| Others |
Cost & Logistics Intelligence
Undercapacity in Western Australia's bulk emulsion manufacturing base is compressing supplier margins while amplifying pricing power for integrated producers with captive nitrate supply. This utilization squeeze forces regional distributors to absorb fixed compliance costs from Australia's Work Health and Safety protocols without commensurate volume leverage.
Pricing Analysis
Cost-plus contracts indexed to natural gas and ammonium nitrate spot benchmarks dominate procurement structures in Australian and Chilean mining districts. Pricing stratifies across premium emulsion formulations for wet-hole reliability, standard ANFO blends for dry surface blasting, and economy-grade packaged products for civil construction. Cost compression in bulk ANFO is intensifying because fertilizer market competition for the same chemical feedstock creates seasonal margin squeezes. Construction firms exhibit highest price sensitivity due to project-based procurement with limited volume guarantees, while tier-one miners with decade-long offtake structures trade pricing flexibility for supply security.
Supply Chain Analysis
Tariff exposure between Australia and Indonesia dominates supply chain risk as Indonesia's Ministry of Energy and Mineral Resources restricts cross-border explosive shipments. Manufacturing concentrates in Australia, Chile, and the United States for bulk emulsion systems, with nitrate feedstock production anchored in Russia, Ukraine, and the Middle East. Supply chain vulnerability rests on single-source dependency for electronic detonator components sourced from East Asian semiconductor fabricators. Distribution runs through integrated manufacturer fleets in mining districts alongside regional packaged-product distributors serving construction and quarrying niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical rock breaking technologies present a credible substitution threat that explosives incumbents must neutralize through service integration and performance guarantees. Hydraulic hammers and surface miners in European limestone quarries already displace explosives in selective extraction applications.
For Market Incumbents: Pre-empt mechanical substitution by bundling digital blasting optimization with explosives supply, converting transactional product sales into outcome-based fragmentation contracts. Deepen backward integration into ammonium nitrate production to neutralize fertilizer market price volatility. Anchor capacity expansion in Western Australia's Pilbara district to capture volume concentration from iron ore expansion while Australia's Work Health and Safety regulations raise barriers for regional competitors.
For New Entrants and Emerging Players: Pursue on-site manufacturing partnerships in Indonesia's remote nickel corridors where cross-border shipment restrictions create protected market space. Target construction tunneling applications in Alpine Europe where electronic initiation systems and water-gel formulations command technical premiums beyond commodity bulk blasting. Enter through specialized perimeter control products for mechanized underground metal mines in Canada and Sweden rather than competing head-on in bulk surface mining.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mobile emulsion plant deployments as remote project development accelerates. Long-term viability favors service-integrated operators with captive distribution infrastructure over pure-play chemical manufacturers exposed to input cost volatility. Monitor electronic detonator adoption rates as the inflection signal—rapid displacement of pyrotechnic systems indicates successful technology transition and pricing power migration toward integrated blasting service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrate Feedstock | Captive ammonium nitrate supply insulates Orica and MaxamCorp from fertilizer market price swings. |
| Mobile Emulsion Plant Deployment | On-site manufacturing partnerships in Indonesia neutralize cross-border regulatory restrictions for nickel operators. |
| Electronic Initiation System Integration | Millisecond-precision timing from Dyno Nobel and Enaex displaces pyrotechnic detonators across Australian and Chilean mines. |
| Long-term Offtake Contracting | Decade-long volume guarantees with BHP and Rio Tinto compress margins in exchange for project finance visibility. |
| Digital Blasting Optimization Platform | Fragmentation modeling software linked to mine planning systems captures downstream processing savings for copper porphyry operators. |
Research Approach
Operator-level perspectives from mine planning engineers, blasting contractors, procurement leads at diversified miners, and explosives distribution channel partners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC filings from publicly listed chemical producers, and national mining regulator disclosure databases. Bottom-up volume modeling across product chemistry, application mix, delivery mode, and end-user segments triangulated against top-down macroeconomic indicators from mining capital expenditure trackers.
Scenario-bracketing around commodity price volatility, regulatory tightening timelines, and mechanical substitution penetration informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type chemistry tiers, surface versus underground application splits, bulk versus packaged delivery configurations, and mining company scale classifications. CAGRs derived from historical volume trajectories adjusted for project pipeline visibility in Chilean copper and Australian iron ore development. Industry-specific forecast inputs incorporated natural gas price correlation with ammonium nitrate production costs and electronic detonator adoption curves from Canadian and Swedish mechanized mines.
Sensitivities concentrate around ammonium nitrate feedstock price spikes, accelerated mechanical rock breaking adoption in European quarrying, and regulatory delays in Australian shot firer certification pipelines. Forecasts reflect documented assumptions on project development timelines and substitution technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Surface Treatment Chemicals Market