
 Liquid Electrolyte Market | 2026-2036
Liquid Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Electrolyte Market Analysis
The EU Battery Regulation is broadening compliance obligations for electrolyte purity, carbon footprint disclosure, and recycled content thresholds. Mitsubishi Chemical leverages its integrated precursor-to-electrolyte pipeline to sustain cost advantages across European customer qualifications. LG Chem anchors its position through captive supply relationships with Korean cell manufacturers. UBE Industries specializes in high-voltage additive packages that differentiate its portfolio in premium battery segments.
Liquid electrolyte denotes an ion-conducting solution comprising dissolved lithium salts, organic carbonates, and functional additives that facilitate charge transport between battery electrodes at operating voltages typically spanning 2.5 to 4.4 volts. The formulation determines thermal stability, cycle life, and safety margins in lithium-ion cells deployed across transportation and stationary applications. Lithium hydroxide formulations occupy the dominant revenue pool given their indispensability in high-nickel cathode systems. Battery Manufacturing applications lead volume absorption as gigafactory buildouts accelerate procurement of standardized electrolyte blends. Bulk Tanks packaging is gaining preference among tier-one cell producers seeking to minimize handling costs and contamination risk in continuous-flow production environments.
The EU Battery Regulation, REACH, and China's GB standards collectively govern chemical composition limits, transport classification, and recycling obligations for liquid electrolyte formulations. EMA and ECHA oversight in Europe is tightening disclosure requirements for fluorinated additives, while China's SAMR enforces national standards on solvent purity and flash point specifications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and market access barriers as certification regimes harden.
Market Dynamics
Electric vehicle battery manufacturing is pulling lithium hydroxide formulations at unprecedented scale, compressing supplier lead times and forcing electrolyte producers to co-locate with gigafactory corridors. This demand concentration is restructuring competitive positioning around captive supply relationships and integrated precursor-to-electrolyte pipelines.
Growth Catalysts
- EU Battery Regulation mandates:Purity and recycling requirements are tightening disclosure obligations for fluorinated additives, compelling reformulation investments that favor established suppliers with qualification track records.
- High-nickel cathode chemistry penetration:Lithium hydroxide formulations are becoming indispensable in premium battery segments, locking in electrolyte specifications that resist substitution.
- China's gigafactory buildouts:Ningbo Shanshan and Guangzhou Tinci Materials operate integrated production corridors serving domestic cell makers, creating regional supply density that accelerates procurement cycles.
Market Restraints
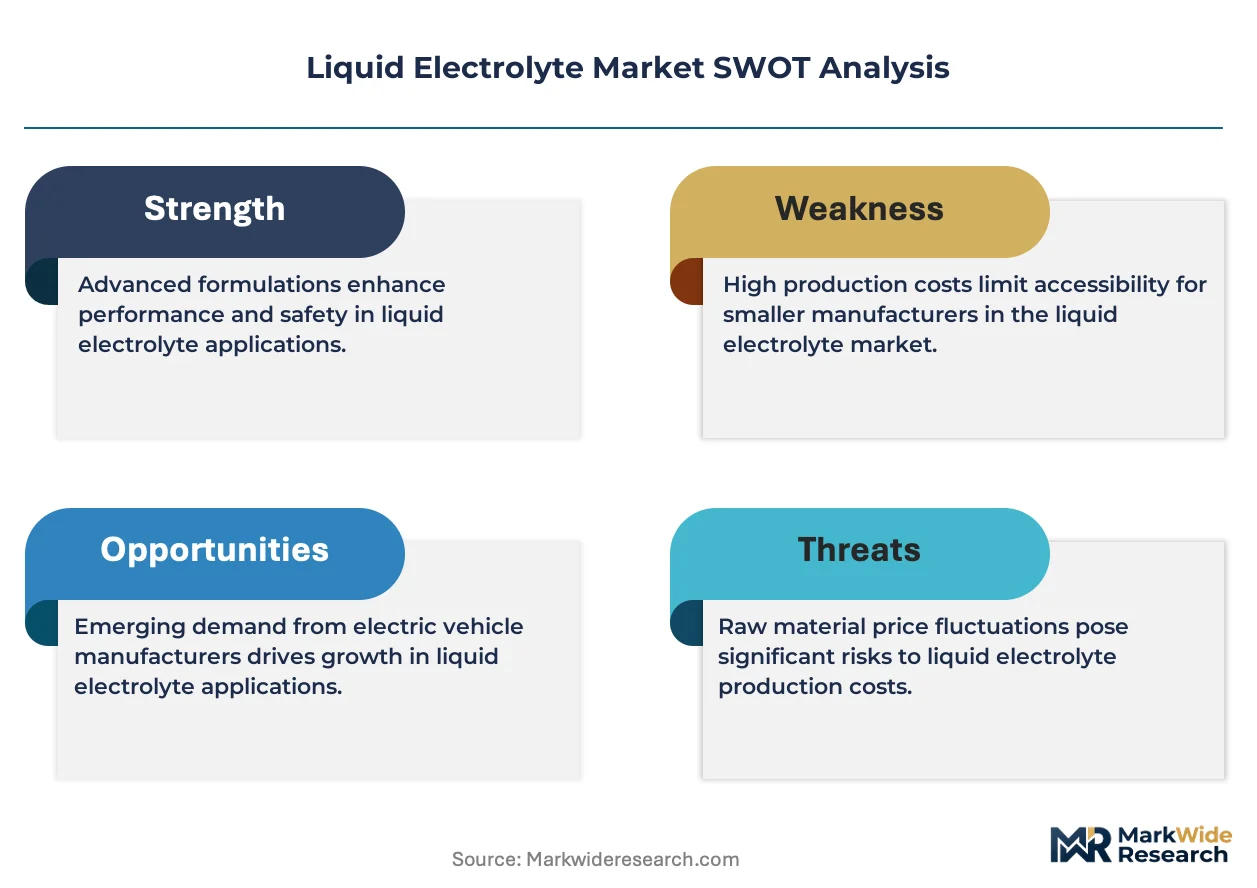
- Carbonate solvent price volatility:Ethylene carbonate and dimethyl carbonate feedstock costs fluctuate with petrochemical spreads, squeezing margin predictability for blenders without backward integration.
- Fluorinated additive supply concentration:LiPF6 and specialty additive production clusters in Japan and South Korea, creating single-source vulnerability for European and North American formulators.
- REACH compliance friction:ECHA disclosure requirements for novel electrolyte salts are extending qualification timelines by 18-24 months, delaying commercialization of next-generation formulations.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Domestic battery production incentives are creating first-mover openings for electrolyte suppliers willing to establish local blending capacity ahead of demand maturation.
- Solid-state electrolyte hybridization:Semi-solid and gel polymer architectures are converging with liquid electrolyte expertise, enabling incumbents to leverage existing formulation knowledge in transitional cell designs.
- Bulk tank logistics innovation:Continuous-flow packaging systems are displacing drum handling at tier-one cell producers, creating service differentiation for suppliers with specialized transport infrastructure.
Industry Challenges
- Electrolyte salt purification expertise scarcity:Battery-grade LiPF6 synthesis requires semiconductor-level contamination control, constraining workforce availability for new market entrants.
- Dual carbon footprint certification complexity:Simultaneous compliance with EU Battery Regulation carbon disclosure and China's SAMR energy intensity standards demands redundant measurement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Electrolyte Market |
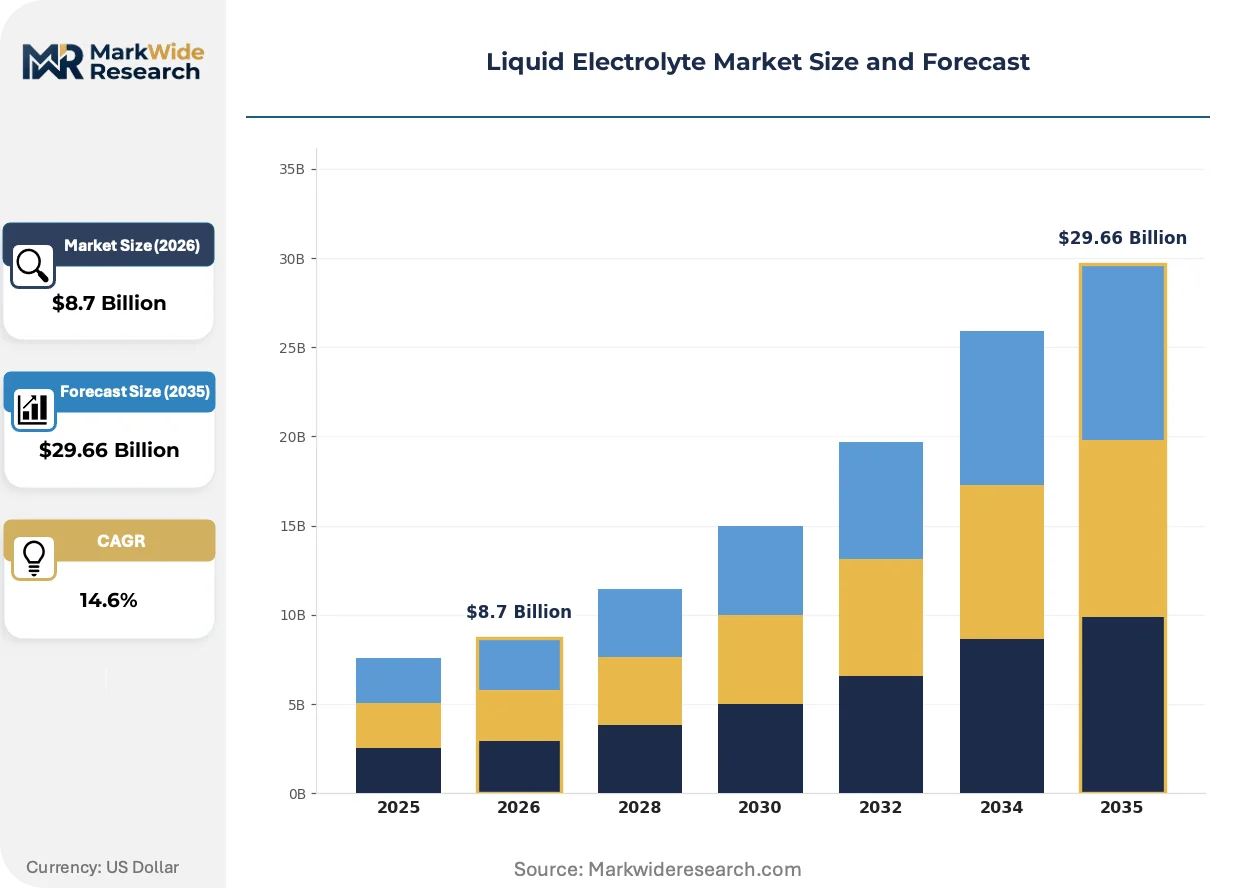
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Sulfate, Lithium Hydroxide, Potassium Nitrate, Calcium Chloride Application: Battery Manufacturing, Energy Storage, Electrochemical Cells, Fuel Cells End User: Automotive, Consumer Electronics, Industrial Equipment, Renewable Energy Packaging Type: Bottles, Drums, IBC Containers, Bulk Tanks |
| Companies Covered | Ningbo Shanshan, Mitsubishi Chemical, LG Chem, BASF, Shenzhen Capchem Technology, Guangzhou Tinci Materials Technology, UBE Industries, ENCHEM, Samsung SDI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Electrolyte Market Emerging Trajectories
Formulation chemistry and regulatory architecture are absorbing the market's innovative capacity, with additive packages and compliance systems becoming the primary vectors of differentiation. Suppliers are racing to embed thermal stability and low-temperature performance into standardized blends.
Localized high-voltage additive packages are absorbing premium segment demand as nickel-rich cathodes push operating voltages toward 4.4 volts. Korean and Chinese cell manufacturers are qualifying these formulations fastest, compressing the supplier base to those with in-house additive synthesis. The technology is absorbing margin from commodity carbonate blending by locking customers into proprietary salt combinations.
REACH and the EU F-Gas Regulation are tightening chemical composition limits for fluorinated electrolyte components. Formulators must now submit extended safety dossiers for novel lithium salts before commercial deployment. European cell producers are responding by dual-sourcing from suppliers with existing ECHA registrations, favoring incumbents over innovative entrants.
Cell producers are consolidating electrolyte procurement around annual framework contracts with volume guarantees, displacing spot purchasing that dominated early gigafactory ramp-ups. This behavior shift is compressing supplier margins while securing supply certainty for buyers. The pattern is most visible in China, where CATL and BYD have established captive blending arrangements with dedicated production lines.
Liquid Electrolyte Market Segmentation
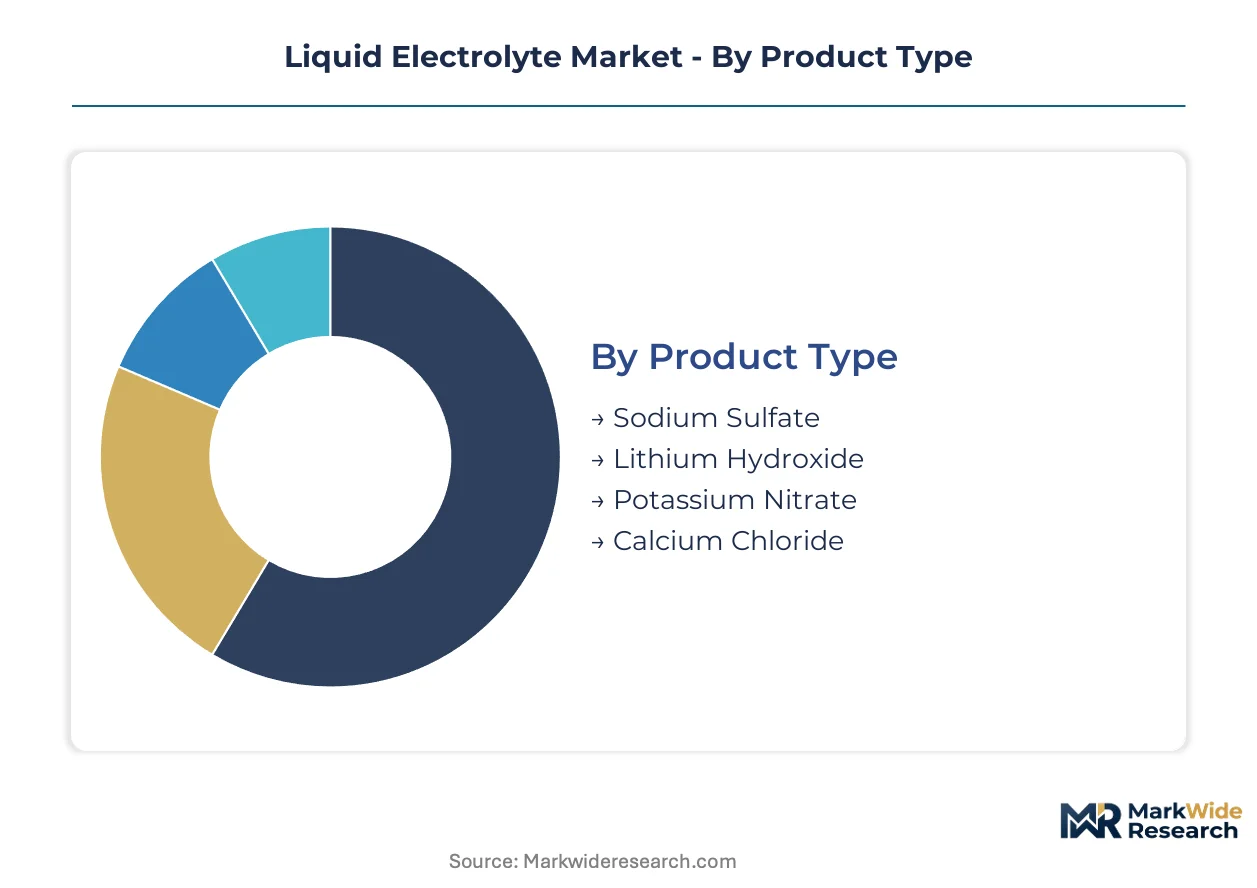
Liquid electrolyte procurement patterns diverge sharply across formulation chemistry, end-use voltage requirements, and logistics infrastructure. Suppliers must align production assets with the specific purity and packaging demands of each segment to avoid stranded capacity.
Product Type:
Buyers in this category differentiate by cathode chemistry compatibility and thermal stability thresholds rather than price alone.
- Lithium Hydroxide:Formulations dissolve lithium salts in carbonate solvents to enable ion transport in high-voltage cells. Battery manufacturers in China and South Korea consume the dominant share as nickel-rich cathodes push operating voltages toward 4.4 volts.
- Sodium Sulfate:Lower-cost electrolyte base for stationary storage and industrial applications where energy density requirements relax. Grid-scale battery deployments in India and Germany absorb growing volumes as sodium-ion chemistry matures.
- Potassium Nitrate:Thermal storage and molten salt applications leverage its high heat capacity and low cost. Concentrated solar power plants in Spain and Morocco specify this chemistry for heat transfer fluids.
- Calcium Chloride:Desiccant and brine applications dominate demand, with limited battery-grade consumption. Industrial dehumidification systems in Japan and chemical processing facilities in the United States represent core end-uses.
Volume sits with Lithium Hydroxide; growth tilts toward Sodium Sulfate as sodium-ion commercialization accelerates.
Application:
Margin structures in this category separate high-specification mobility applications from commoditized stationary storage.
- Battery Manufacturing:Gigafactory procurement of standardized electrolyte blends for lithium-ion cell production. CATL and BYD in China, plus LG Energy Solution in South Korea, command the largest contract volumes with qualification requirements that lock out second-tier suppliers.
- Energy Storage:Grid-scale battery systems require lower-purity formulations with extended cycle life specifications. Utility procurement in Texas, Germany, and Australia is expanding fastest as renewable integration mandates tighten.
- Electrochemical Cells:Industrial and specialty cell production for medical devices, aerospace, and defense applications. Swiss and Japanese manufacturers dominate this segment with small-batch, high-margin contracts.
- Fuel Cells:Proton exchange membrane systems utilize electrolyte membranes rather than liquid formulations, creating limited overlap with conventional battery electrolyte supply chains. Korean and German fuel cell developers source through distinct procurement channels.
Revenue concentrates in Battery Manufacturing; margin expansion favors Energy Storage as utility-scale procurement scales.
End User:
Customer sophistication in this category spans from price-sensitive consumer electronics to specification-captive automotive programs.
- Automotive:Electric vehicle cell producers demand battery-grade formulations with full supply chain traceability and carbon footprint certification. European OEMs through ECHA-registered suppliers and Chinese EV makers through SAMR-compliant domestic producers split the procurement base.
- Consumer Electronics:Smartphone and laptop battery assemblers prioritize cost minimization over performance optimization. Contract manufacturers in Vietnam and Mexico source through regional distributors with limited direct supplier relationships.
- Industrial Equipment:Forklifts, mining vehicles, and backup power systems utilize mid-tier electrolyte specifications. German and Japanese industrial equipment makers maintain dual-source strategies to mitigate supply disruption.
- Renewable Energy:Solar-plus-storage and wind farm developers procure electrolyte indirectly through system integrators. Project developers in Chile, Morocco, and Saudi Arabia specify performance warranties rather than chemical formulations.
Procurement scale favors Automotive; contract flexibility tilts toward Renewable Energy as project finance structures evolve.
Packaging Type:
Logistics economics in this category determine supplier competitiveness as much as formulation chemistry.
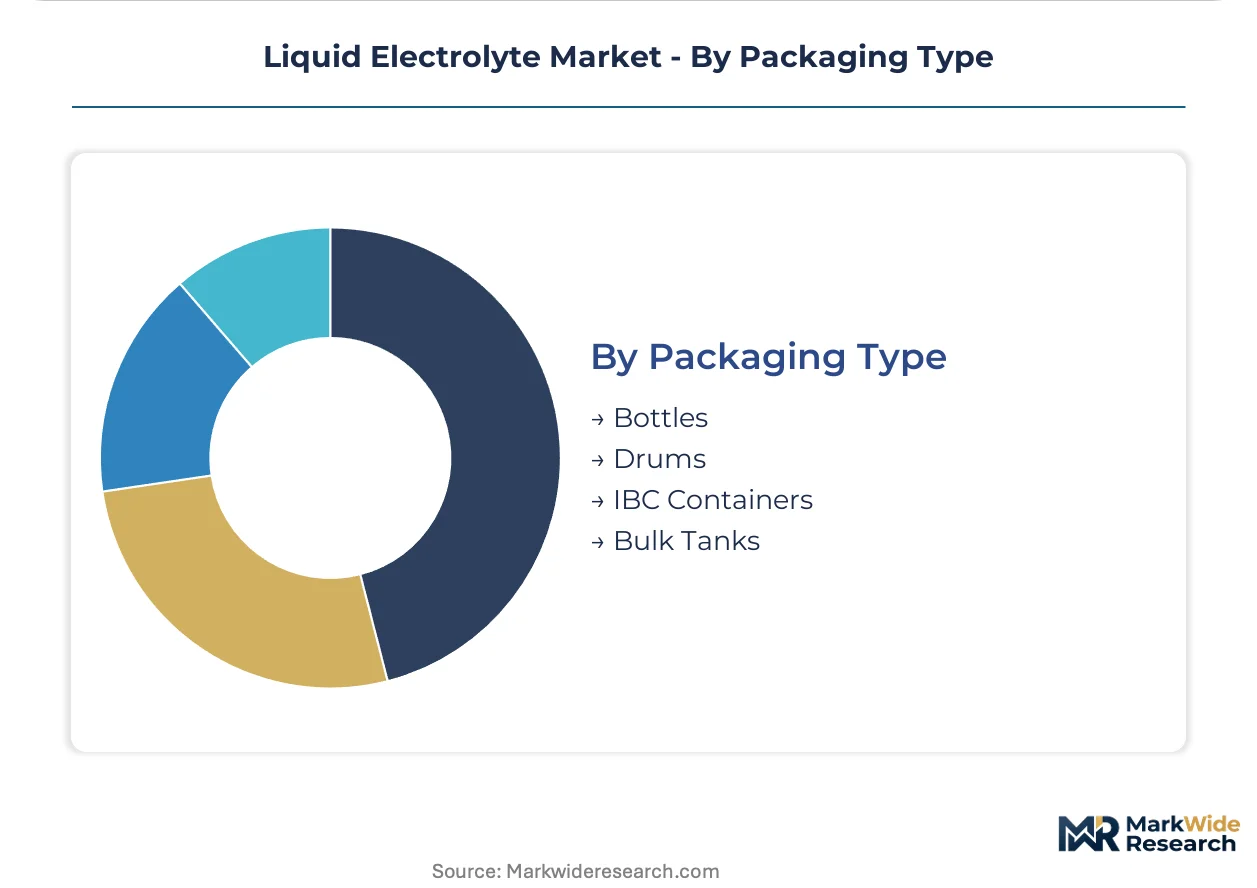
- Bulk Tanks:Continuous-flow delivery systems eliminate handling contamination and reduce labor costs at high-volume cell plants. CATL's Ningde facility and Tesla's Nevada gigafactory operate dedicated bulk tank corridors with supplier co-location.
- IBC Containers:Intermediate bulk packaging serves mid-scale producers and regional blending operations. European and North American cell startups rely on IBC logistics while scaling toward bulk tank thresholds.
- Drums:Standard 200-liter containers remain prevalent for specialty formulations and small-batch qualification runs. Japanese additive suppliers ship LiPF6 and high-voltage packages exclusively in drums to preserve purity.
- Bottles:Laboratory-scale and R&D quantities for formulation testing and customer qualification. Electrolyte producers in South Korea and Germany maintain bottled sample programs for new customer onboarding.
Operational scale concentrates in Bulk Tanks; packaging innovation shifts toward IBC as mid-tier producers expand capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian integrated corridors while European and North American demand outpaces domestic supply capacity. Chinese suppliers serve the bulk of gigafactory procurement through co-located blending facilities. Western cell makers face qualification bottlenecks as they dual-source from Asian producers and nascent regional operations.
China
CATL and BYD absorb the dominant share of lithium hydroxide formulations through dedicated production lines at Ningbo Shanshan and Guangzhou Tinci Materials. SAMR enforces GB standards on solvent purity and flash point specifications that govern domestic procurement. The Yangtze River Delta corridor hosts integrated precursor-to-electrolyte pipelines serving cell makers with continuous-flow bulk tank delivery.
South Korea
LG Energy Solution and Samsung SDI anchor demand for high-voltage additive packages qualified for nickel-rich cathode systems. The country's national chemical regulator aligns with REACH disclosure requirements for fluorinated components under bilateral trade protocols. The Gyeonggi-do cluster houses captive blending operations with backward integration into LiPF6 synthesis.
Germany
European OEMs through ECHA-registered suppliers split procurement between imported formulations and emerging domestic capacity. The EU Battery Regulation and REACH impose carbon footprint disclosure and recycled content thresholds that extend qualification timelines. BASF operates blending assets in Ludwigshafen serving regional cell startups with SAMR-compliant supply alternatives.
United States
Tesla's Nevada gigafactory and emerging cell plants in Texas and the Midwest pull standardized electrolyte blends through bulk tank corridors. EPA and OSHA oversight governs transport classification and workplace exposure limits for carbonate solvents. The Southeast automotive corridor is attracting supplier co-location as domestic battery manufacturing scales under IRA production incentives.
Japan
UBE Industries and Mitsubishi Chemical supply specialty additive packages and semiconductor-grade LiPF6 to premium battery segments. METI coordinates national standards with IEC frameworks for electrolyte salt purity. The Kansai region maintains concentrated expertise in fluorinated additive synthesis that resists geographic relocation.
Liquid Electrolyte Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive precursor supply and qualification track records. Tier-one cell producers have compressed the supplier base through multi-year framework contracts with volume guarantees. Three archetypes dominate: diversified chemical majors with electrolyte divisions, specialized electrolyte pure-plays with additive synthesis capabilities, and battery makers with backward-integrated blending operations. Capacity expansion and geographic co-location with gigafactory corridors represent the dominant competitive moves as procurement shifts from spot purchasing to annual commitments.
Among the integrated chemical majors, Mitsubishi Chemical exemplifies the archetype of suppliers leveraging precursor-to-electrolyte pipelines to sustain cost advantages across customer qualifications. LG Chem occupies a position within the Korean battery ecosystem through captive supply relationships with domestic cell manufacturers. Guangzhou Tinci Materials Technology represents the Chinese pure-play model with integrated production corridors serving the world's largest gigafactory demand concentration. These three anchors illustrate how regional supply density and qualification speed determine competitive positioning.
| Leading Market Players |
|---|
| Ningbo Shanshan |
| Mitsubishi Chemical |
| LG Chem |
| BASF |
| Shenzhen Capchem Technology |
| Guangzhou Tinci Materials Technology |
| UBE Industries |
| ENCHEM |
| Samsung SDI |
| Others |
Supply Flow & Price Mechanics
Semiconductor-grade LiPF6 synthesis expertise concentration in Japan's Kansai region widens pricing-tier spreads between battery-grade formulations and industrial-grade alternatives, as labor-cost differentials between specialty chemists and commodity blenders compound raw material volatility.
Pricing Analysis
Cost-down pressure on standard carbonate blends accelerates as Chinese gigafactory procurement consolidates around annual framework contracts with volume guarantees. Three-tier pricing structure across premium high-voltage additive packages, qualified standard blends, and unqualified economy grades separates suppliers with ECHA registrations from spot-market blenders. Price differentiation hinges on certification tier—REACH-compliant formulations command substantial premiums over GB-standard alternatives—and captive supply relationships with Korean cell manufacturers. Automotive OEMs through ECHA-registered suppliers exhibit lowest price sensitivity; consumer electronics contract manufacturers in Vietnam and Mexico drive hardest bargain.
Supply Chain Analysis
Single-source vulnerability sits with fluorinated additive production clusters in Japan and South Korea, where UBE Industries and Mitsubishi Chemical control semiconductor-grade LiPF6 synthesis. Geographic supply concentration centers on China, South Korea, and Japan, with the Yangtze River Delta and Gyeonggi-do corridors hosting integrated precursor-to-electrolyte pipelines. Raw material dependencies rest on ethylene carbonate and dimethyl carbonate feedstocks from petrochemical complexes, plus lithium hexafluorophosphate salt from specialized fluorine chemistry operations. Tariff exposure on carbonate solvents imported into Europe creates supply chain risk as EU Battery Regulation tightens. Distribution runs through bulk tank corridors for tier-one cell producers, with IBC containers and drums serving mid-scale and specialty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Liquid Electrolyte Market operates as a cost-of-compliance story where REACH and EU Battery Regulation disclosure requirements for fluorinated additives erect barrier-to-entry moats favoring incumbents with existing ECHA registrations.
For Market Incumbents: To counter margin compression from carbonate solvent price volatility, deepen backward integration into precursor synthesis and expand bulk tank logistics infrastructure at European gigafactory corridors. Lock automotive OEMs through dual-carbon-footprint certification investments that extend qualification timelines beyond entrant reach. For New Entrants and Emerging Players: Enter via India's PLI scheme for cell manufacturing, where domestic battery production incentives create first-mover openings ahead of demand maturation. Target sodium-ion stationary storage applications with lower-purity formulations that bypass lithium hydroxide qualification bottlenecks. Pursue additive-package specialization rather than commodity blending to escape incumbent cost structures. For Investors and Strategic Acquirers: Re-rating potential sits with electrolyte pure-plays possessing in-house high-voltage additive synthesis given nickel-rich cathode chemistry penetration. Long-term viability favors suppliers with qualification track records across multiple regulatory jurisdictions. Watch for ECHA registration completion timelines as inflection indicator—accelerated approvals signal competitive entry, extended delays reinforce incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LiPF6 Synthesis | Captive salt production insulates margin from Japanese supplier concentration and REACH compliance friction. |
| Bulk Tank Logistics Infrastructure Expansion | Continuous-flow delivery systems lock in CATL and Tesla procurement with contamination-risk elimination. |
| Dual Carbon Footprint Certification Investment | Simultaneous EU Battery Regulation and SAMR compliance opens automotive OEM and Chinese EV maker channels. |
| High-Voltage Additive Package Development | Proprietary formulations for 4.4-volt nickel-rich cathodes extract premium pricing from Korean cell manufacturers. |
| Regional Blending Capacity in India | PLI scheme alignment positions ahead of domestic cell manufacturing scale-up and sodium-ion commercialization. |
Methodological Framework
SEC filings from electrolyte suppliers, customs and trade data from China and South Korea, and ECHA registration databases formed the secondary backbone. Primary interviews with plant managers at carbonate blending facilities, procurement leads at Korean cell manufacturers, distribution channel partners serving European gigafactories, and technical R&D directors at additive specialists combined with secondary validation. Bottom-up electrolyte volume estimates triangulated against top-down gigafactory capacity announcements across the analysis window.
Historical trendline analysis of lithium hydroxide formulation absorption tracked against nickel-rich cathode penetration rates and gigafactory buildout timelines. Segmentation dimensions modeled include formulation chemistry tier, end-use voltage requirement, packaging logistics format, and regional regulatory cluster. CAGRs derived from electrolyte intensity per gigawatt-hour of cell production capacity, with forecast inputs incorporating SAMR enforcement trajectories and EU Battery Regulation implementation pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden carbonate solvent price spikes or accelerated solid-state electrolyte substitution. Forecasts reflect assumptions around qualification timeline stability and regulatory divergence persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Europe Molecular Sieve Market