
 Carbamate Insecticides Market | 2026-2036
Carbamate Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Carbamate Insecticides Market Outlook
Specialty crop growers is redrawing demand patterns within the carbamate insecticides sector, pulling volume away from broad-acre commodity applications. FMC Corporation anchors its position through deep manufacturing scale in carbofuran derivatives. Bayer AG differentiates via R&D intensity focused on reduced-toxicity analogs. UPL Limited leverages extensive distribution networks across South Asian agricultural markets.
Carbamate insecticides constitute a class of synthetic organic compounds derived from carbamic acid, functioning primarily as acetylcholinesterase inhibitors that disrupt neural transmission in target pests; active ingredients typically contain an N-methyl or N,N-dimethyl carbamate ester linkage with molecular weights ranging from 150 to 300 g/mol. These compounds serve commercial agriculture, public health vector control, and structural pest management through contact, stomach, and limited systemic action. Agricultural Crops remains the dominant application segment, though Indoor Pest Control represents the fastest-growing margin pool as urbanization intensifies. Farmers constitute the largest end-user category by volume, while Commercial Growers command premium pricing through specialized procurement channels.
The EPA governs carbamate registration under FIFRA mandates requiring extensive ecotoxicological data, while REACH classifications in Europe restrict certain methyl carbamate formulations through hazard-based cutoffs. India's CEA and CDSCO jointly oversee residue tolerance setting for food-export compliance, directly shaping formulation choices for manufacturers serving cross-border supply chains. Stakeholders must monitor evolving neurotoxicity assessment protocols across multiple jurisdictions to anticipate product phase-outs and replacement chemistry investments.
Market Dynamics
Cholinesterase-inhibitor re-registration mandates from the EPA are compressing formulation timelines and forcing manufacturers toward reduced-toxicity analog development. Specialty crop procurement channels now demand residue profiles that legacy carbamate derivatives struggle to meet.
Growth Catalysts
- Integrated Pest Management Expansion:Brazil's soybean belt operators are bundling carbamates with biological controls under CEA-mandated resistance management protocols. This pulls volume into precision application equipment.
- REACH Hazard-Based Reformulation:ECHA's revised classification thresholds for methyl carbamate esters are accelerating investment in N,N-dimethyl variants with improved ecotoxicological profiles.
- Vector Control Procurement:India's National Vector Borne Disease Control Programme is expanding carbamate purchases for malaria and dengue suppression in peri-urban corridors.
Market Restraints
- Active Ingredient Concentration Risk:Technical-grade carbofuran production clusters in select Indian and Chinese chemical hubs, exposing formulators to single-source disruption.
- Substitution by Neonicotinoids:Imidacloprid and clothianidin are capturing share in cotton and rice applications where carbamates once dominated.
- Ecotoxicological Data Costs:EPA's FIFRA-mandated pollinator risk assessments impose six-figure study requirements that marginalize smaller registrants.
Strategic Opportunities
- Indoor Structural Pest Control:Urbanization in Southeast Asian megacities is opening demand for low-odor carbamate formulations in residential and commercial building maintenance.
- Seed Treatment Convergence:Coating carbamates with polymer film technologies is extending residual efficacy and opening premium positioning in specialty vegetable markets.
- Drone Application Channels:Brazil's ANVISA is streamlining aerial application permits for carbamate products, enabling precision deployment in topographically complex soybean plots.
Industry Challenges
- Neurotoxicity Assessment Expertise:Registrants face acute shortages of toxicologists trained in cholinesterase inhibition mechanisms required for dossier defense.
- Legacy Equipment Integration:Existing spray infrastructure in Indian cotton-growing states requires recalibration for reduced-volume carbamate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbamate Insecticides Market |
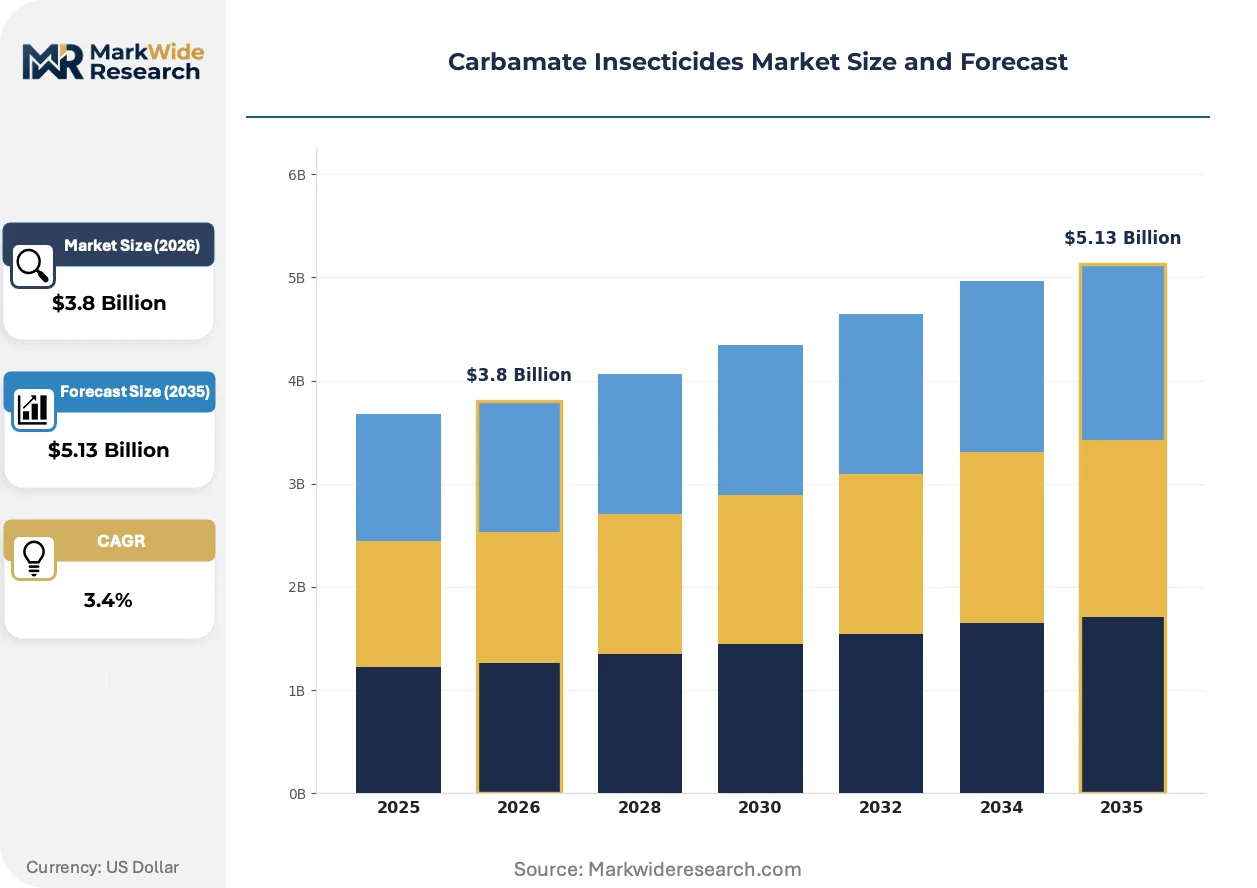
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.13 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbamates, Pesticides, Fungicides, Herbicides Application: Agricultural Crops, Horticultural Plants, Turf Maintenance, Indoor Pest Control End User: Farmers, Gardeners, Commercial Growers, Pest Control Services Distribution Channel: Online Retailers, Agricultural Supply Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | BASF SE, FMC Corporation, Bayer AG, Syngenta Group, UPL Limited, Corteva Agriscience, Nufarm Limited, Sumitomo Chemical, Drexel Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbamate Insecticides Market Strategic Shifts
Formulation chemistry and application technology are converging to extend carbamate utility despite tightening residue standards. Three developments are restructuring competitive advantage.
Encapsulated microsphere delivery systems are decomposing the traditional tradeoff between contact efficacy and worker exposure. Specialty vegetable growers in California's Central Valley are adopting these formulations at accelerating rates. The technology is decomposing price premiums for conventional emulsifiable concentrates.
EPA's 2024 updated ecological risk assessment framework for cholinesterase-inhibiting compounds is mandating expanded field runoff studies. This compresses registration timelines for new carbamate products. Agricultural chemical divisions are responding by pre-submission consultation with the agency's Environmental Fate and Effects Division.
Direct procurement from manufacturers is displacing traditional distributor intermediaries among Brazilian commercial soybean operations. Large cooperatives in Mato Grosso are negotiating volume contracts that bundle technical support with active ingredient supply. This channel compression is most visible in states where credit access for input purchases has tightened.
Carbamate Insecticides Market Segmentation
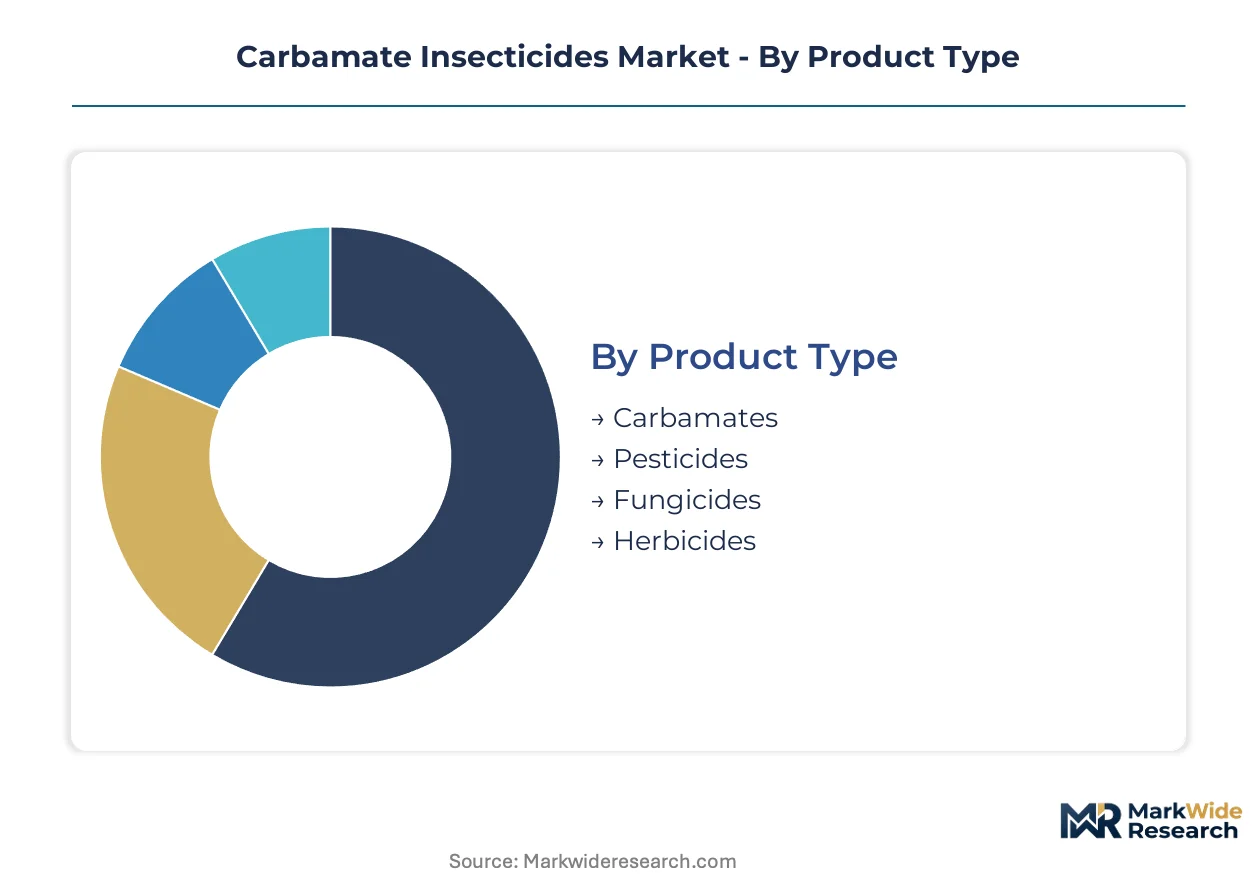
Carbamate insecticide segmentation reveals how regulatory pressure and application technology are splitting demand across incompatible use cases. Manufacturers now optimize formulations for entirely different residue tolerance and exposure profiles rather than pursuing universal chemistries.
Product Type:
EPA's FIFRA re-registration tiers and REACH hazard classifications are fragmenting product portfolios into regulatory risk buckets that dictate R&D allocation and geographic market access.
- Carbamates:N-methyl and N,N-dimethyl carbamate esters function as acetylcholinesterase inhibitors with molecular weights between 150-300 g/mol. India's cotton-growing states and Brazil's soybean belt concentrate procurement for resistance management programs where carbamates rotate with neonicotinoids.
- Pesticides:This broader synthetic category encompasses organophosphates, pyrethroids, and carbamates under unified regulatory frameworks. Commercial growers in California's Central Valley are demanding residue profiles that favor precision-application formulations over broad-spray chemistries.
- Fungicides:Triazole and strobilurin-based compounds for crop protection against fungal pathogens.
- Herbicides:Glyphosate and auxin-based formulations for weed control in row-crop applications.
Carbamates handle the majority of throughput; Indoor Pest Control applications are climbing the fastest on share as urbanization intensifies.
Application:
Application segmentation tracks the divergence between outdoor agricultural volume and indoor structural margins, with each channel demanding incompatible formulation properties.
- Agricultural Crops:Field corn, soybean, cotton, and rice applications dominate tonnage through contact and stomach action. Brazil's ANVISA streamlined aerial permits are pulling carbamate volume into drone-deployed soybean plots in Mato Grosso.
- Horticultural Plants:Specialty vegetable and fruit production requires low-residue formulations with pre-harvest intervals measured in days rather than weeks. California's specialty crop growers are adopting encapsulated microsphere delivery systems at accelerating rates.
- Turf Maintenance:Golf courses and recreational field management for grub and surface-feeding insect control.
- Indoor Pest Control:Residential and commercial building maintenance for cockroach, ant, and termite suppression.
Agricultural Crops commands the volume base; Indoor Pest Control shows the steepest expansion trajectory on margin contribution.
End User:
End-user segmentation separates price-sensitive commodity producers from premium-channel buyers who bundle technical support with chemical procurement.
- Farmers:Broad-acre row-crop operators purchasing through cooperative and distributor channels. Indian cotton-growing states concentrate demand where existing spray infrastructure requires recalibration for reduced-volume formulations.
- Commercial Growers:Specialty vegetable and greenhouse operations commanding premium pricing through direct manufacturer relationships. Large Brazilian cooperatives are negotiating volume contracts that displace traditional distributor intermediaries.
- Gardeners:Residential consumers purchasing small-format products through retail and online channels.
- Pest Control Services:Licensed applicators serving structural and municipal vector control contracts.
Farmers absorb the majority of volume; Commercial Growers is gaining share fastest on value contribution.
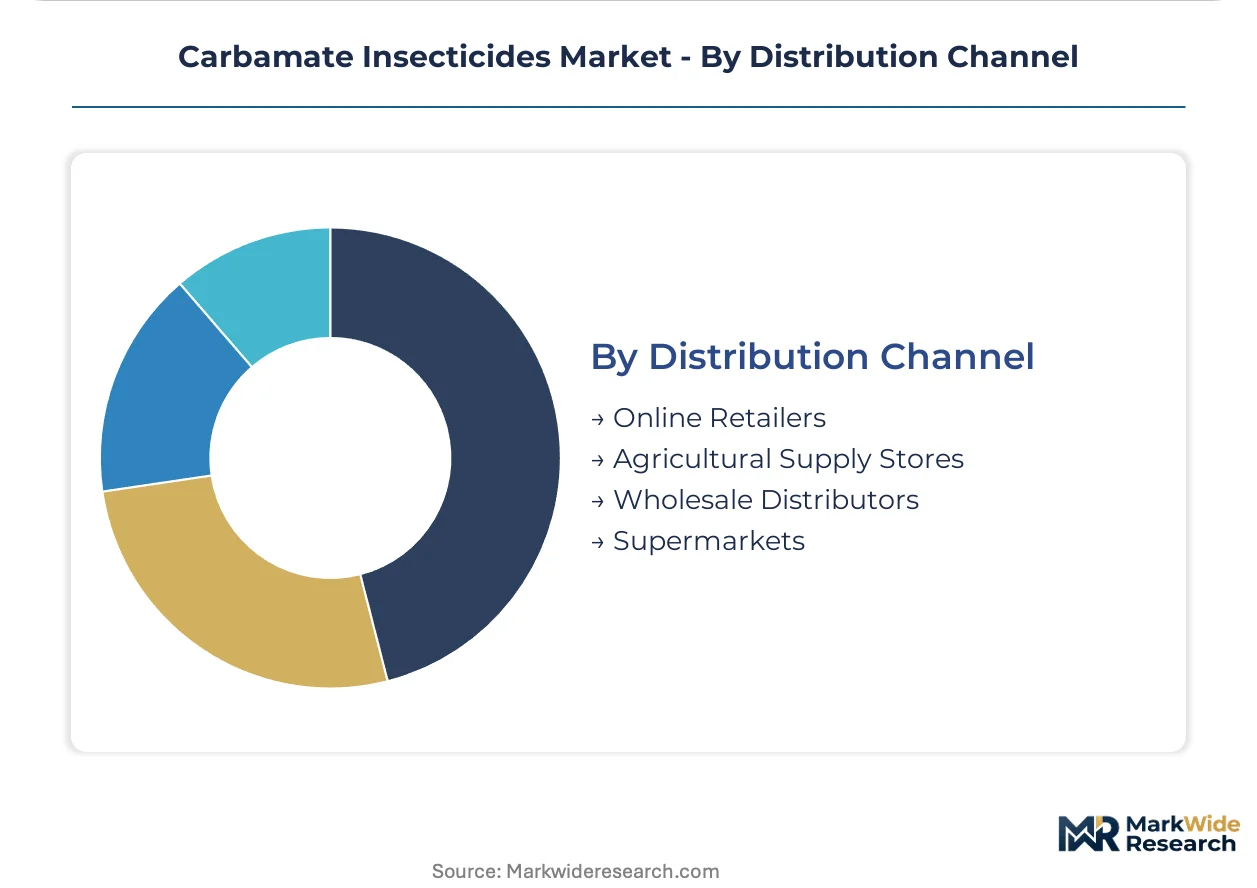
Distribution Channel:
Channel segmentation captures the compression between traditional agricultural supply chains and emerging direct procurement models.
- Online Retailers:E-commerce platforms serving residential gardeners and small-scale producers with expedited fulfillment. Southeast Asian urban corridors are opening demand for low-odor formulations through digital channels.
- Agricultural Supply Stores:Local input retailers providing credit access and technical consultation to row-crop farmers.
- Wholesale Distributors:Regional logistics networks consolidating manufacturer volumes for downstream fragmentation.
- Supermarkets:Mass-market retail for consumer-format garden and home pest control products.
Agricultural Supply Stores still handle the majority of throughput; Online Retailers is expanding most quickly as credit access tightens in key growing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese technical-grade carbofuran production clusters supply formulators across Brazil's soybean belt and India's cotton-growing states. These trade corridors concentrate procurement decisions in Mato Grosso cooperatives and Maharashtra chemical distributors.
United States
California's Central Valley specialty vegetable growers drive demand for encapsulated microsphere carbamate formulations with shortened pre-harvest intervals. EPA's FIFRA re-registration mandates under the 2024 updated ecological risk assessment framework compress approval timelines for new cholinesterase-inhibiting products. Field runoff study requirements now dominate registration dossiers for agricultural chemical divisions.
Brazil
Mato Grosso commercial soybean cooperatives negotiate direct volume contracts that displace traditional distributor intermediaries. ANVISA streamlined aerial application permits enable precision drone deployment across topographically complex plots. Resistance management protocols under CEA mandates pull carbamate volume into integrated pest management bundles with biological controls.
India
Maharashtra and Gujarat cotton-growing states concentrate legacy spray infrastructure requiring recalibration for reduced-volume carbamate formulations. CDSCO and CEA jointly oversee residue tolerance setting for food-export compliance, shaping formulation choices for cross-border supply chains. Technical-grade production clusters in select chemical hubs expose formulators to single-source disruption risk.
Germany
Bayer AG anchors European R&D intensity for reduced-toxicity carbamate analog development from its Leverkusen headquarters. ECHA's revised REACH classification thresholds for methyl carbamate esters accelerate investment in N,N-dimethyl variants with improved ecotoxicological profiles. The country's hazard-based regulatory approach filters product portfolios entering continental markets.
Japan
Sumitomo Chemical exemplifies precision formulation chemistry targeting premium horticultural applications with extended residual efficacy. METI oversight aligns with OECD neurotoxicity assessment protocols for cholinesterase-inhibiting compounds. Domestic greenhouse operations in Chubu and Kansai regions command specialized procurement channels with bundled technical support.
Carbamate Insecticides Market Competitive Environment
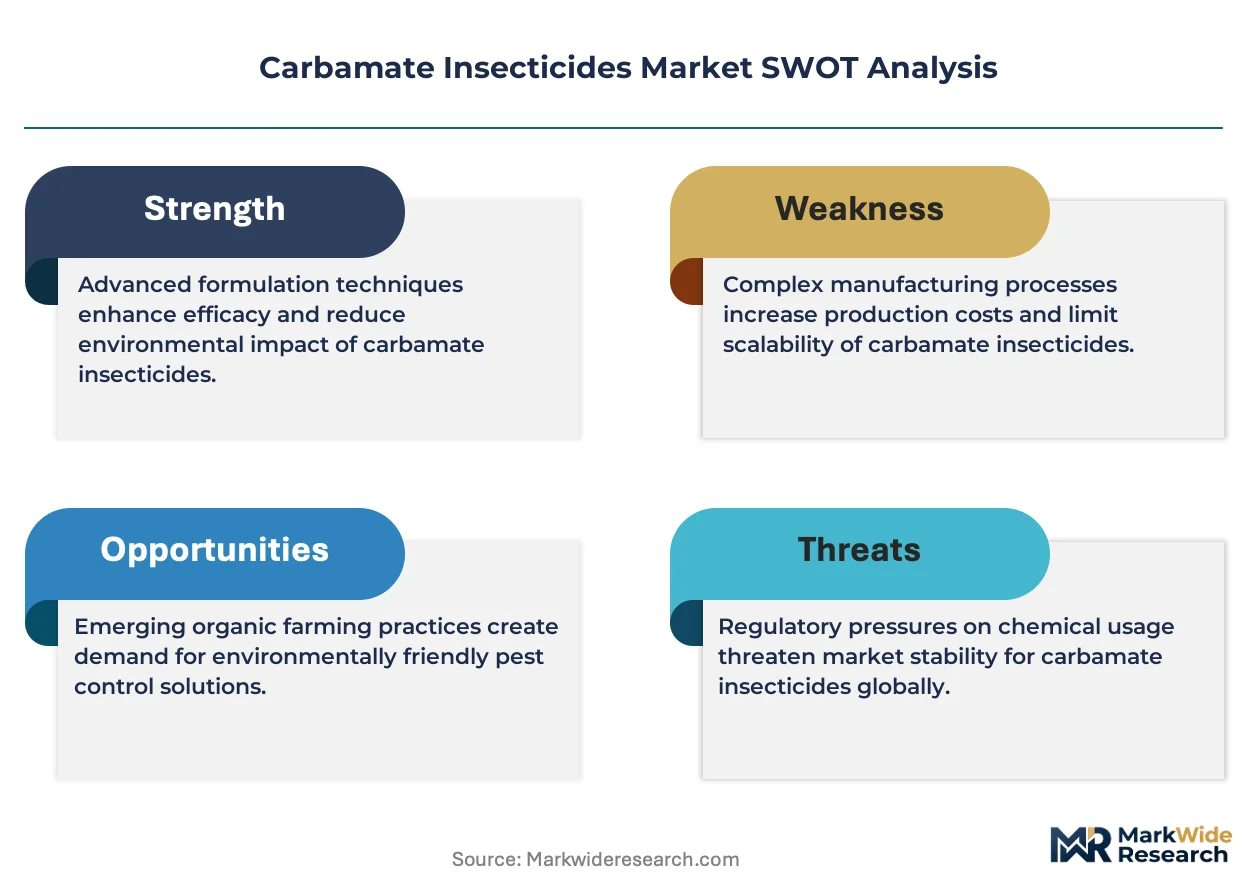
Listed leaders compete with private specialists across regulatory dossier capacity and geographic coverage depth. The vendor base organizes into three tiers: integrated agrochemical conglomerates with full registration infrastructure, regional formulators serving single-country markets, and technical-grade producers supplying active ingredient to downstream blenders. Consolidation pressure intensifies as EPA-mandated ecotoxicological study costs marginalize smaller registrants. Dominant competitive moves include backward integration into technical-grade production and strategic partnerships for distribution network access.
Within the integrated conglomerate tier, BASF SE and Bayer AG exemplify archetypes pursuing reduced-toxicity analog development under tightening European hazard classifications. FMC Corporation occupies a position among North American-listed leaders with manufacturing scale in carbofuran derivatives. UPL Limited anchors the Asia-Pacific specialist vector through extensive distribution networks across South Asian agricultural markets. These three company structures represent divergent responses to cholinesterase-inhibitor re-registration compression.
| Leading Market Players |
|---|
| BASF SE |
| FMC Corporation |
| Bayer AG |
| Syngenta Group |
| UPL Limited |
| Corteva Agriscience |
| Nufarm Limited |
| Sumitomo Chemical |
| Drexel Chemical |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Mato Grosso soybean cooperatives and Indian technical-grade producers lock in carbofuran supply access while capping price volatility for Brazilian formulators. These arrangements concentrate procurement power among large agricultural buyers and compress margins for mid-tier distributors caught between fixed contract terms and spot market fluctuations.
Pricing Analysis
Legacy emulsifiable concentrate formulations trade at a discount to encapsulated microsphere delivery systems, which command premium positioning in California specialty vegetable markets. Three-tier pricing structure across premium, standard, and economy levels separates residue-compliant formulations from conventional chemistries and generic technical-grade supplies. Cost compression in standard-tier products is intensifying because EPA-mandated pollinator risk assessments impose six-figure study requirements that marginalize smaller registrants. Commercial growers in Brazil's soybean belt show least price sensitivity through bundled technical support contracts, while Indian cotton farmers face acute margin pressure from recalibration costs for reduced-volume spray equipment.
Supply Chain Analysis
Container availability constraints on the Shanghai-Mumbai and Shanghai-Santos trade lanes are elevating inbound logistics costs for technical-grade carbamate shipments. Active ingredient production clusters in China and India feed formulators across Brazil and the United States, with methyl carbofuran synthesis anchored in Gujarat chemical hubs. Single-source vulnerability concentrates in select Indian technical-grade facilities, exposing downstream blenders to disruption. Distribution runs through agricultural supply stores in rural growing regions, though direct manufacturer contracts are displacing traditional wholesale intermediaries among large commercial cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of toxicologists trained in cholinesterase inhibition mechanisms constrains dossier defense capacity and elevates regulatory compliance costs for all market participants. This capability gap separates registrants with in-house expertise from those dependent on scarce external consultants.
For Market Incumbents: Shield formulation portfolios through backward integration into technical-grade carbofuran production in India and China, reducing exposure to single-source disruption. Accelerate investment in N,N-dimethyl analog development to preempt REACH hazard-based reclassification of methyl carbamate esters. Channel control through direct procurement contracts with Brazilian cooperatives locks out distributor-dependent competitors. For New Entrants and Emerging Players: Anchor in indoor structural pest control applications across Southeast Asian megacities, where urbanization is opening demand for low-odor formulations with limited incumbent saturation. Drone application channels in Brazil offer penetrable white space as ANVISA streamlines aerial permits. Partner with precision agriculture equipment manufacturers to bundle carbamate supply with application technology. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulators with established EPA registration infrastructure and geographic concentration in high-growth corridors. The five-to-ten year viability window favors assets with demonstrated dossier defense capabilities and backward integration into technical-grade supply. Monitor EPA neurotoxicity assessment protocol revisions as the critical inflection signal for product phase-out timelines and replacement chemistry investment triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Production | Captive carbofuran supply from Indian and Chinese hubs insulates formulators from single-source disruption. |
| Encapsulated Microsphere Formulation Development | California specialty growers adopt these systems to meet shortened pre-harvest interval requirements. |
| Direct Procurement Contracting | Brazilian cooperatives in Mato Grosso negotiate volume deals that displace traditional distributor intermediaries. |
| Drone Application Channel Partnerships | ANVISA streamlined aerial permits enable precision deployment in topographically complex soybean plots. |
| N,N-Dimethyl Analog R&D Investment | ECHA REACH reclassification accelerates shift from methyl carbamate esters to improved ecotoxicological profiles. |
Study Parameters
Operator-level perspectives from formulator plant managers, agricultural cooperative procurement leads, EPA registration consultants, and Indian chemical distributor channel partners anchored the qualitative base. These primary interviews combined with secondary validation from EPA FIFRA registration databases, REACH dossier filings, customs trade data, and SEC 10-K disclosures from listed agrochemical divisions. Bottom-up technical-grade production estimates and top-down agricultural input expenditure patterns were triangulated to constrain volume forecasts.
Sensitivity analysis tested forecast robustness against regulatory phase-out scenarios and raw material cost shocks across the projection horizon. Segmentation dimensions modeled include product type, application channel, end-user archetype, and geographic production hub. CAGRs were derived from fitted growth curves incorporating resistance management protocol adoption rates and substitution dynamics from neonicotinoid competitors. Industry-specific inputs captured encapsulated formulation penetration in specialty crops and drone application permit issuance trends.
Underlying assumptions cover stable EPA re-registration timelines for existing cholinesterase inhibitors, with deviation risk concentrated in accelerated neurotoxicity assessment protocol revisions. Forecasts reflect these conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Europe Bitumen Market