
 Industrial Phenol Market | 2026-2036
Industrial Phenol Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Phenol Market Intelligence
The shift towards project-based financing for new production capacity is fragmenting the competitive landscape for industrial phenol. Major incumbents like INEOS Group Holdings S.A. leverage extensive integrated assets to maintain market share. In contrast, Dow Inc. differentiates through its broad downstream chemical portfolio and application development expertise, while Mitsubishi Chemical Group Corporation competes on technology and specialized resin formulations.
Industrial phenol is an aromatic organic compound with the chemical formula C6H5OH, produced primarily via the cumene process. It serves as a critical chemical intermediate for synthesizing a vast range of commercial products. Demand for Resin C derivatives represents a significant volume segment for phenol producers. Applications in high-performance adhesives and coatings command price premiums due to stringent quality requirements set by end user industries.
Regulatory frameworks, including the EU's REACH, the US EPA's chemical safety rules, and China's GB standards, govern production and use. These regulations mandate strict protocols for handling, transportation, and waste disposal, influencing operational costs. Producers must continuously evaluate the trade-offs between investing in bio-based alternatives and optimizing existing cumene-based production assets to ensure long-term compliance and profitability.
Market Dynamics
The industrial phenol market's central dynamic is the tension between the capital intensity of the cumene production process and the rising cost of compliance with stringent environmental regulations. Producers must balance investments in existing asset optimization against mandates like the EU's REACH and China's GB standards.
Growth Catalysts
- Polycarbonate Resin Demand:The synthesis of polycarbonate, a key material for lightweighting in the automotive and electronics sectors, remains a primary volume driver for phenol consumption, especially for high-clarity and high-impact grades.
- Manufacturing in China:Continued expansion of chemical, automotive, and construction manufacturing hubs across China sustains high-volume, localized demand for phenol as a foundational chemical intermediate.
- High-Performance Formulations:The use of phenol derivatives in specialized adhesives, industrial coatings, and phenolic resins for composite materials creates demand in high-margin, performance-driven application segments.
Market Restraints
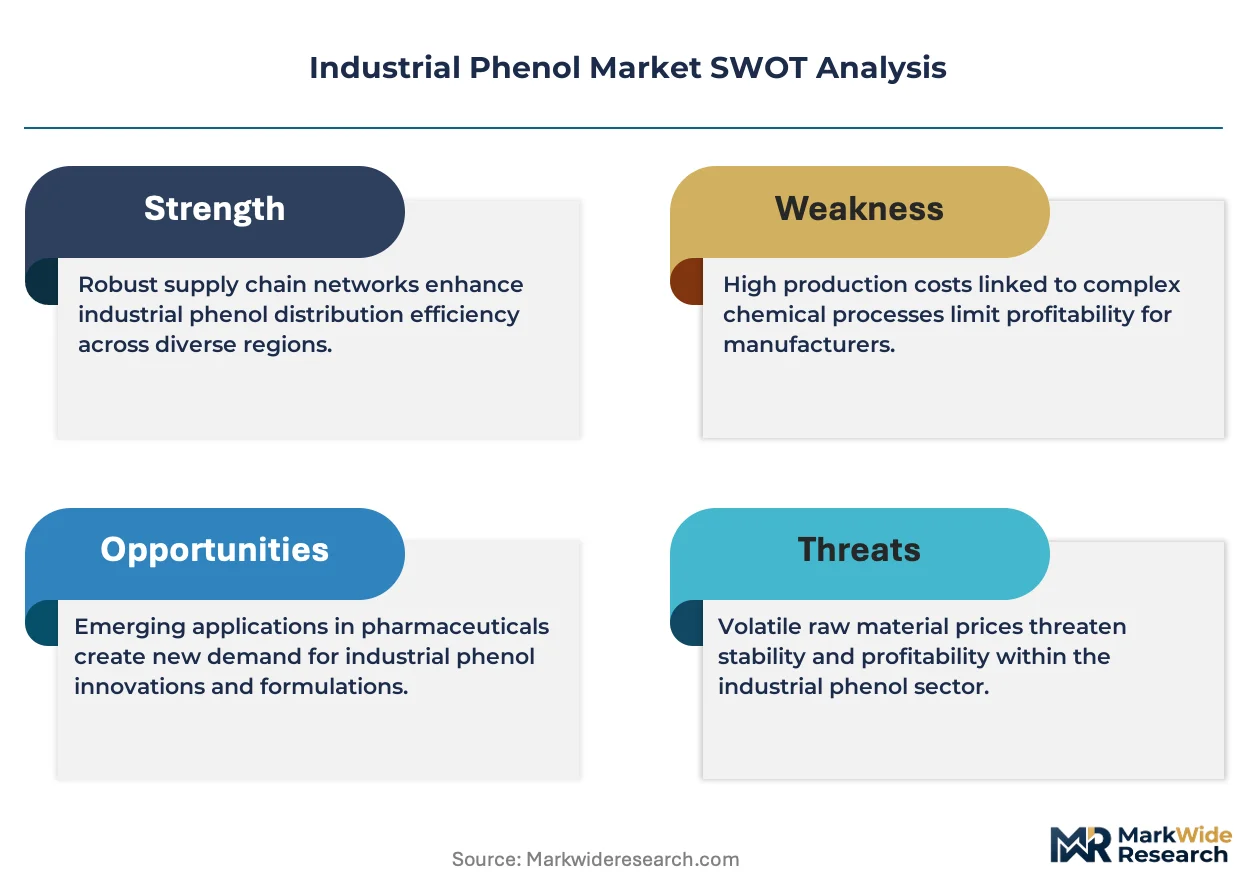
- Feedstock Price Volatility:The cumene process relies on benzene and propylene, petrochemical feedstocks whose prices are subject to significant volatility, directly impacting phenol production costs and margin stability.
- Regulatory Compliance Costs:Adherence to environmental frameworks, including the US EPA's chemical safety rules and the EU's REACH, imposes substantial operational costs related to waste treatment, emissions monitoring, and handling protocols.
- Substitution from Derivatives:Concerns over bisphenol-A (BPA), a major phenol derivative, are encouraging research into alternative, non-phenol-based polymers for applications like food contact materials, posing a long-term substitution risk.
Strategic Opportunities
- Bio-Based Phenol Pathways:Developing commercially viable production routes for phenol from renewable feedstocks like lignin or glucose presents a significant opportunity to meet sustainability mandates and reduce reliance on petrochemicals.
- Demand in India:India's expanding chemical and pharmaceutical manufacturing sectors, supported by policies like the PLI scheme, represent an underpenetrated geography for phenol consumption and potential production investment.
- Advanced Composite Materials:The convergence of phenolic resins with carbon or glass fibers enables the creation of high-strength, fire-resistant composites for demanding applications in aerospace, mass transit, and construction.
Industry Challenges
- Capital Expenditure Intensity:The construction of new world-scale cumene process facilities or the retrofitting of existing plants to meet stricter environmental performance standards requires immense upfront capital investment.
- Evolving Compliance Standards:Navigating the long lead times for process validation and certification to comply with evolving regulations, such as the EU's CSRD, creates operational uncertainty and planning complexity.
- Logistical Network Complexity:Reconfiguring supply chains to align with shifting regional demand centers or to mitigate geopolitical risks involves intricate logistical planning and establishing new transportation and storage infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Phenol Market |
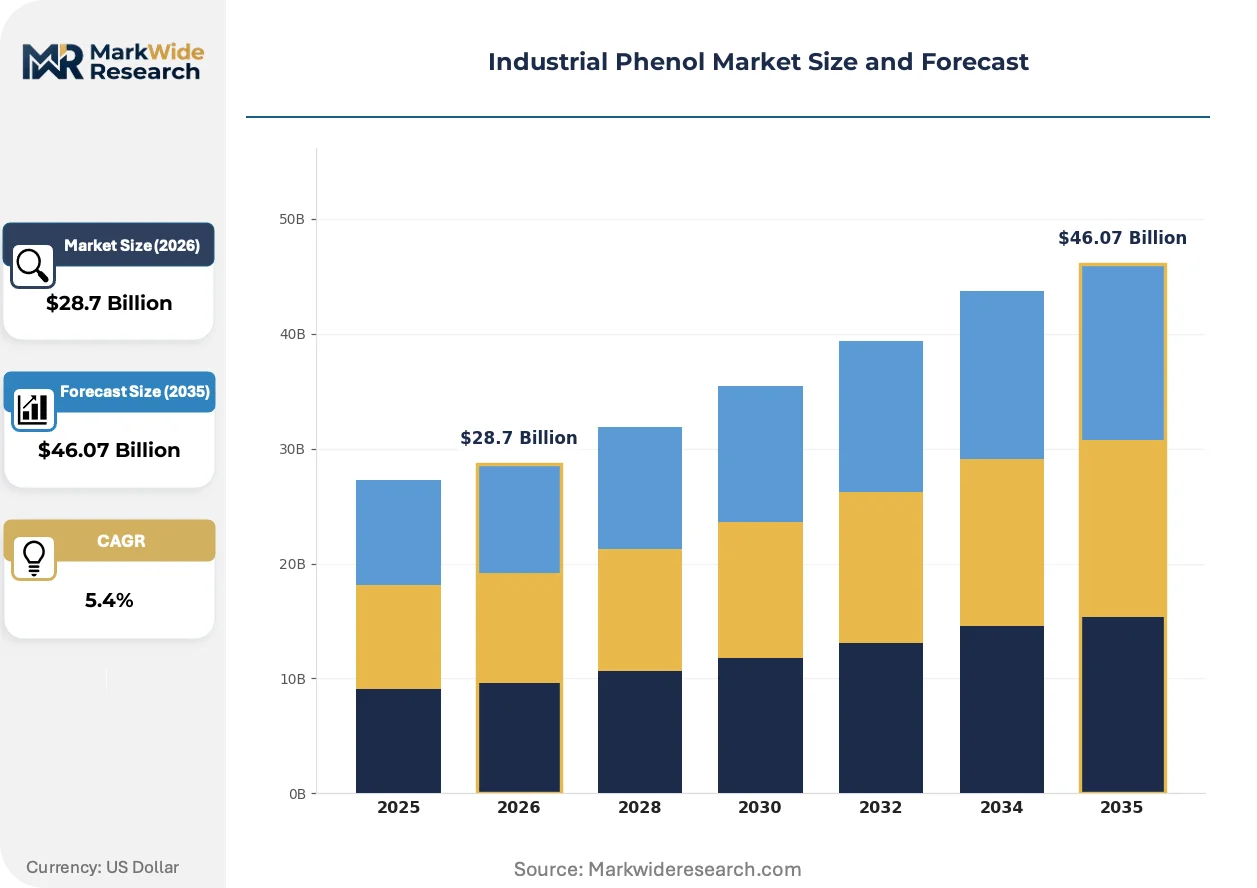
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compound A, Intermediate B, Resin C, Solvent D, Additive E Technology: Catalytic Process, Extraction Method, Distillation Technique, Fractionation System, Polymerization Approach Application: Adhesives, Coatings, Pesticides, Detergents, Flame Retardants End User Industry: Chemical Manufacturers, Paint Producers, Agrochemical Firms, Cleaning Product Companies, Safety Equipment Makers |
| Companies Covered | China Petroleum & Chemical Corporation, Mitsubishi Chemical Group Corporation, INEOS Group Holdings S.A., LG Chem, Formosa Chemicals and Fibre Corp., Dow Inc., Kumho P&B Chemicals Inc., Mitsui Chemicals Inc., Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Phenol Market Strategic Shifts & Innovations
Innovation in the industrial phenol market is bifurcated. Efforts are intensifying to enhance the efficiency and environmental profile of the dominant cumene process, while parallel research accelerates the development of commercially viable bio-based production pathways to meet long-term sustainability goals.
Advanced catalysis for the cumene process is a primary focus, utilizing novel zeolite or solid-acid catalysts to improve reaction selectivity and minimize acetone byproduct formation. Chemical producers are actively adopting these technologies to upgrade existing production units rather than building entirely new plants. This focus on process intensification is hybridizing traditional synthesis with modern catalytic science, extending the economic viability of established assets.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory driver influencing production strategy. This directive compels companies to provide detailed disclosures on their environmental impact, including energy consumption and emissions from chemical synthesis. Producers supplying the European market are most affected, now investing in advanced life-cycle assessment (LCA) and emissions monitoring systems to ensure compliance and maintain market access.
A distinct preference is emerging among downstream customers for chemical intermediates with a documented low-carbon footprint. This behavioral shift disrupts traditional procurement, as buyers in the electronics and automotive sectors increasingly request sustainability data alongside technical specifications. This trend is most visible in North American and European markets, where end-product brands face pressure to decarbonize their entire value chain.
Industrial Phenol Market Segmentation
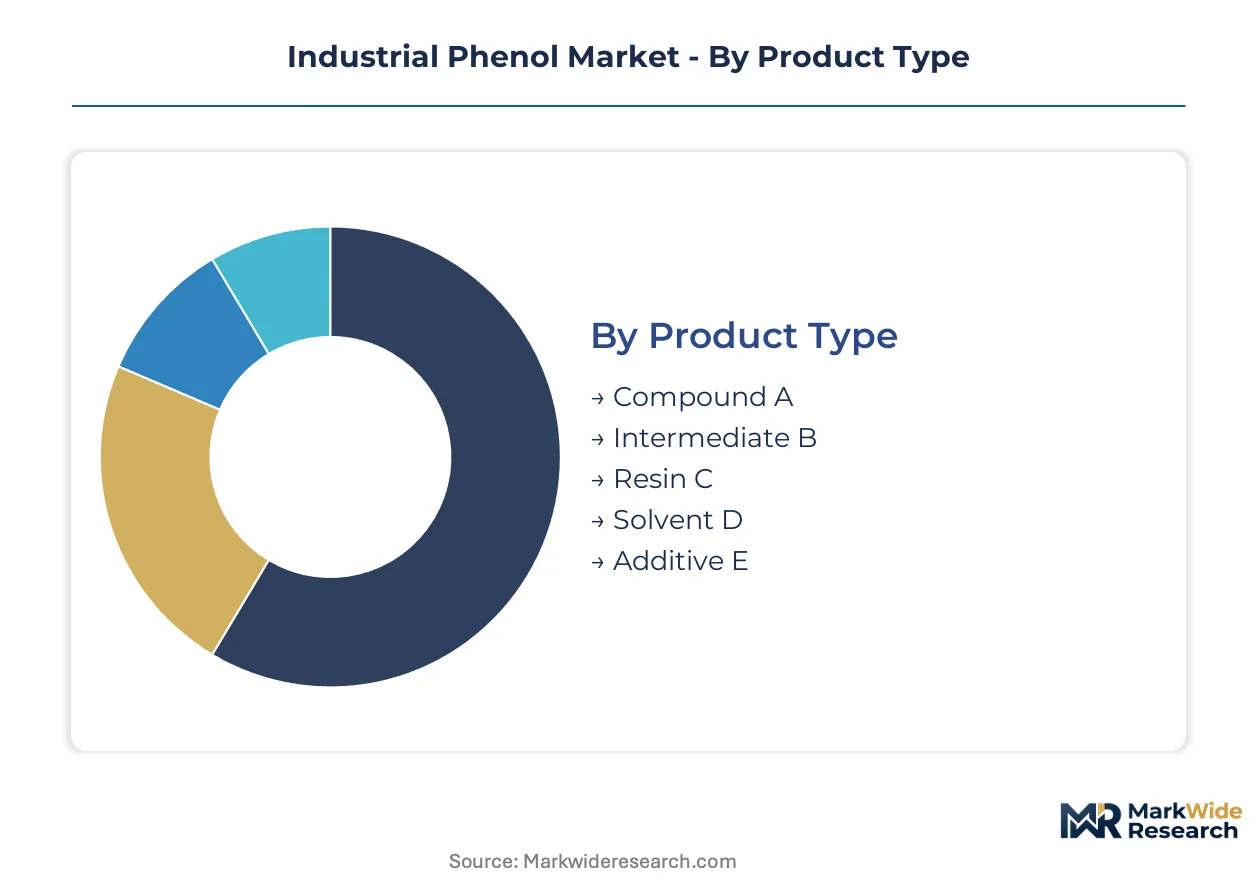
Understanding the diverse segmentation of the industrial phenol market is crucial for identifying specific demand drivers and operational nuances. Phenol's role as a foundational chemical intermediate means its market dynamics are inextricably linked to the performance of various downstream industries and specialized production methodologies. This segmentation analysis provides clarity on the distinct value propositions and growth trajectories across different market dimensions.
Product Type:
The varying purity specifications and formulation requirements across industrial phenol product types necessitate different levels of supplier technical support, reflecting distinct after-sales service intensities.
- Resin C:This product type serves as a critical precursor for high-performance polymers, including polycarbonates and specialized phenolic resins. Demand concentrates in the automotive and electronics sectors across China and Germany, driven by requirements for lightweighting and high-impact applications.
- Compound A:A specialized chemical building block, Compound A finds use in the synthesis of advanced materials and specific pharmaceutical intermediates. Demand is robust in advanced materials manufacturing hubs in Japan and the US, supported by stringent performance standards.
- Intermediate B:This versatile chemical intermediate is broadly employed in diverse synthesis pathways for various organic compounds.
- Solvent D:Utilized in industrial processes requiring powerful organic solvents for dissolution and reaction media.
- Additive E:Incorporated into various formulations to enhance material properties, such as flame retardancy or UV stability.
Resin C holds the largest share; momentum sits with Compound A.
Technology:
The production of industrial phenol relies on distinct technological approaches, each with unique capital expenditure requirements and operational complexities.
- Catalytic Process:This dominant technology utilizes specific catalysts to facilitate chemical reactions, primarily the cumene process for phenol synthesis. Demand concentration occurs in large-scale integrated chemical complexes in China and the US, driven by feedstock availability and economies of scale.
- Polymerization Approach:This method involves linking monomer units to form larger polymer chains, often for specific resin production from phenol derivatives. Demand concentrates among specialized resin manufacturers in South Korea and Germany, focused on high-performance materials.
- Extraction Method:This technique separates phenol from complex mixtures using selective solvents, often employed for purification.
- Distillation Technique:Purifies phenol based on boiling point differences, crucial for achieving various purity grades.
- Fractionation System:This system refines crude phenol streams into distinct purity grades, essential for specialized applications.
The Catalytic Process dominates output volumes, while the Polymerization Approach is expanding most quickly for downstream integration.
Application:
Industrial phenol serves as a versatile intermediate across a broad spectrum of applications, each demanding specific material properties and regulatory compliance.
- Adhesives:Phenol derivatives provide strong bonding characteristics for structural and specialty adhesive formulations in industrial and consumer products. Demand concentrates in the construction and automotive industries in India and Brazil, requiring durable assembly solutions.
- Coatings:Phenolic resins contribute significantly to the hardness, chemical resistance, and thermal stability of industrial coatings. Demand is strong in marine and industrial infrastructure projects in the UAE and Saudi Arabia, driven by harsh environmental conditions.
- Pesticides:Phenol acts as a crucial precursor for various agricultural chemicals and crop protection agents.
- Detergents:Used in the synthesis of surfactants and other active ingredients for industrial and household cleaning products.
- Flame Retardants:Phenolic compounds enhance fire resistance in materials used across construction, electronics, and transportation sectors.
Adhesives and Coatings represent the largest consumption segments, with Flame Retardants showing accelerating adoption in safety-critical materials.
End User Industry:
Different end-user industries procure industrial phenol based on their specific manufacturing scale, product quality needs, and regulatory environments.
- Chemical Manufacturers:These large-scale producers synthesize a wide range of phenol derivatives, including polycarbonates, phenolic resins, and bisphenol A. Demand concentrates in integrated chemical parks in Texas, US, and Jiangsu, China, driven by feedstock integration and downstream processing.
- Paint Producers:These manufacturers incorporate phenol-based resins to enhance the durability, chemical resistance, and adhesion of industrial paints and coatings. Demand is significant among automotive and industrial coating manufacturers in Germany and Japan, focused on high-performance finishes.
- Agrochemical Firms:These companies utilize phenol as a fundamental building block for various crop protection agents and agricultural chemicals.
- Cleaning Product Companies:These firms integrate phenol derivatives into industrial and household cleaning formulations for their disinfectant and surfactant properties.
- Safety Equipment Makers:These manufacturers employ phenolic resins for fire-resistant components in personal protective gear and specialized safety equipment.
Chemical Manufacturers consume the bulk of industrial phenol, while Safety Equipment Makers represent a niche but expanding market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial phenol market exhibits varying regional dynamics, with some nations acting as net exporters while others drive significant import demand for downstream chemical manufacturing. Trade flows influence pricing and supply chain configurations across continents. This balance between local production capacity and consumption shapes regional market structures.
China
China's expansive chemical, automotive, and construction sectors sustain high-volume demand for phenol as a foundational intermediate. China's GB standards govern production and use, influencing operational costs. Jiangsu province, a major chemical park, observes significant investment in new production capacity.
United States
United States demand for industrial phenol originates from robust polycarbonate synthesis and advanced materials manufacturing. The US EPA's chemical safety rules mandate strict handling and waste disposal protocols. Integrated chemical parks in Texas attract capital for feedstock integration and downstream processing.
Germany
German industries require industrial phenol for high-performance polymers, including specialized resin formulations for automotive and electronics. The EU's REACH regulation significantly influences product purity standards and operational compliance. The Rhine-Ruhr region focuses on advanced chemical synthesis and application development.
India
India's expanding chemical and pharmaceutical manufacturing sectors drive increasing consumption of industrial phenol. Policies like the PLI scheme support domestic production and investment in various chemical intermediates. Gujarat state, a prominent chemical hub, sees new capacities emerging to cater to industrial growth.
Japan
Japanese manufacturers utilize industrial phenol for advanced materials and specialized resin formulations in electronics and automotive. METI oversees industrial policy, encouraging innovation in catalytic processes and resource efficiency. The Keihin Industrial Zone near Tokyo remains a critical center for high-tech chemical manufacturing.
Industrial Phenol Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical chemical intermediates like industrial phenol. The market exhibits a tiered structure, with large, integrated chemical companies alongside specialized producers. Strategic archetypes include diversified chemical conglomerates, technology-focused innovators, and regional specialists. Geographic expansion and technology licensing represent dominant competitive moves within this landscape.
Within the diversified chemical conglomerate archetype, INEOS Group Holdings S.A. exemplifies global reach and extensive integrated assets for maintaining significant market share across various chemical value chains. Dow Inc. occupies a position differentiated by its broad downstream chemical portfolio and application development expertise, serving a wide array of end-user industries globally. Mitsubishi Chemical Group Corporation anchors the segment focused on technology and specialized resin formulations, leveraging its R&D capabilities for high-performance applications in advanced materials sectors. These incumbent players collectively shape the market's strategic direction through their scale, technological investments, and established distribution networks.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Mitsubishi Chemical Group Corporation |
| INEOS Group Holdings S.A. |
| LG Chem |
| Formosa Chemicals and Fibre Corp. |
| Dow Inc. |
| Kumho P&B Chemicals Inc. |
| Mitsui Chemicals Inc. |
| Shell plc |
Cost & Logistics Intelligence
Commodity volatility for benzene and propylene determines both pricing tier spreads and the inherent shape of the industrial phenol supply chain. This dependence creates a structural vulnerability for producers relying on petrochemical feedstocks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for phenol. Pricing stratifies across quality grade and volume scale, with specialized resin formulators often requiring additional after-sales service. Upward pricing pressure stems from the inherent volatility of petrochemical feedstock costs. Chemical manufacturers exhibit lower price sensitivity due to their integrated operations, while smaller downstream formulators prove more sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive nature of phenol production. Supply concentrates in large chemical complexes across China, the United States, and Germany. The production process requires significant inputs of benzene and propylene. Logistics chokepoints present a structural risk due to the global movement of feedstocks and finished product. Distribution relies on direct sales to large chemical manufacturers and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial phenol market is experiencing a buyer-power shift, driven by increasing consolidation among downstream chemical manufacturers.
For Market Incumbents: Pre-empt margin erosion from emerging bio-based alternatives by investing in advanced catalysis for existing cumene processes. Secure long-term feedstock contracts to mitigate price volatility, ensuring supply stability against geopolitical risks. Expand strategically into high-growth geographies like India, leveraging established distribution networks. Focus R&D on enhancing process efficiency to meet evolving compliance standards like the EU's CSRD.
For New Entrants and Emerging Players: Pursue white-space opportunities in bio-based phenol pathways, targeting sustainability mandates from European and North American customers. Penetrate specialized derivatives segments like Compound A and Flame Retardants, where performance commands price premiums. A go-to-market angle focused on documented low-carbon footprint and specialized technical support can differentiate offerings. India's expanding chemical sector offers significant potential for new production investment.
For Investors and Strategic Acquirers: Specialized resin formulators leveraging advanced materials technology represent attractive acquisition targets for long-term viability. These firms often possess unique R&D capabilities and established customer relationships in high-margin applications. The signal to watch is the successful commercialization of bio-based phenol production at scale, indicating a significant shift in feedstock economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production scale to meet growing demand in Asia, particularly China and India. |
| Green Manufacturing Transition | Reduces environmental footprint and aligns with global sustainability mandates like the EU Green Deal. |
| Long-term Supply Agreement | Secures stable feedstock supply and mitigates price volatility for petrochemical derivatives. |
| Joint Venture | Facilitates market entry into complex regions or accelerates R&D in bio-based technologies. |
| Technology Licensing | Enables rapid adoption of advanced catalysis for improved cumene process efficiency and yield. |
Research Approach
Initial hypotheses were tested against primary input from plant managers, procurement leads at chemical manufacturers, R&D directors, and regulatory compliance officers, then refined through iterative analysis. Secondary validation drew from customs/trade data, ACC and Cefic reports, EU REACH filings, and China GB standards. This approach facilitated bottom-up and top-down triangulation for robust market sizing.
The demand-supply-balance framing guided the analytical framework across the analysis window. Segmentation dimensions modeled included product type (Resin C, Compound A), technology (catalytic process, polymerization approach), application (adhesives, coatings), end-user industry (chemical manufacturers, paint producers), and regional production hubs. Compound annual growth rates were derived through historical trend analysis and future demand projections, incorporating petrochemical feedstock prices and regulatory compliance costs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-focused innovators or large chemical conglomerates would shift outcomes. Forecasts reflect underlying assumptions regarding geopolitical events and rapid technological breakthroughs in bio-based production. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Commercial Electronic Detonator Market