
 Soil Hardening Agent Market | 2026-2036
Soil Hardening Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Hardening Agent Market Outlook
Multi-source procurement for polymeric binders is repositioning supply relationships across the soil hardening agent value chain. Dow Chemical Company leverages its polyurethane expertise to anchor North American infrastructure contracts. Evonik Industries AG specializes in organosilane modifiers that differentiate its portfolio for geotechnical applications. Wanhua Chemical Group Co., Ltd. dominates Asian supply through captive isocyanate production and direct sales to state-owned construction enterprises.
Soil hardening agents encompass chemical formulations—typically acrylic polymers, Portland cement blends, or lignosulfonate compounds applied at 0.5–3.0% by soil weight—that reduce permeability and increase California Bearing Ratio values for load-bearing surfaces. Their primary purpose is to transform marginal or loose substrates into traffic-ready foundations without full-depth reconstruction. Polymer-type formulations command premium pricing in airport and military runway specifications where ultra-low dust emission is mandatory. Soil stabilization applications absorb the largest volume share, though landscaping-grade emulsions represent the fastest-expanding margin pool as drought-prone municipalities mandate water-efficient ground preparation.
EPA stormwater regulations and FAA airfield pavement standards constrain product selection for U.S. federal projects, while REACH compliance governs polymer imports into European construction supply chains. India's BIS certification requirements for road-building chemicals create a two-tier market split between certified imports and domestic formulations. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these compounds appear in some legacy dust-suppression chemistries and face phased elimination under multiple national frameworks.
Market Dynamics
Polymer-based soil hardening formulations are displacing Portland cement blends in federal infrastructure contracts as emission thresholds tighten across transportation agencies. This substitution dynamic is compressing traditional supply relationships while elevating specialty chemical producers with captive resin capacity.
Growth Catalysts
- India BIS Certification Mandate:Road construction contractors face mandatory compliance for dust-suppression chemicals under Ministry of Road Transport and Highways protocols, accelerating procurement of certified polymer stabilizers.
- Airport Runway Specifications:FAA ultra-low dust emission standards for military and civilian airfield pavements drive specification upgrades toward acrylic polymer systems with sub-5% permeability ratings.
- Desertification Control Projects:China's state-owned construction enterprises deploy synthetic hardening agents across Inner Mongolia and Xinjiang stabilization corridors under dual carbon goal implementation timelines.
Market Restraints
- Isocyanate Feedstock Concentration:Asian supply chains depend on Wanhua Chemical Group and limited regional producers for MDI precursors, creating vulnerability to upstream petrochemical volatility.
- REACH Compliance Friction:European polymer imports face extended registration timelines through ECHA, delaying product qualification for geotechnical tenders in Germany and France.
- Legacy PFAS Contamination Liability:Phased elimination of per- and polyfluoroalkyl substances under EPA and state-level frameworks threatens existing dust-suppression chemistries with stranded asset risk.
Strategic Opportunities
- Municipal Landscaping Emulsions:Drought-prone municipalities in Arizona, California, and Texas mandate water-efficient ground preparation for public parks and median strips, opening specification windows for lignosulfonate-polymer hybrid grades.
- Organosilane-Modified Binders:Evonik's geotechnical specialty chemistry converges with polyurethane backbone systems to create premium positioning for coastal infrastructure exposed to saline degradation.
- Direct State-Enterprise Distribution:Bypassing traditional construction chemical distributors through captive sales teams targets China's Ministry of Transport procurement portals with volume-locked contracts.
Industry Challenges
- California Bearing Ratio Certification Lag:Third-party geotechnical validation for polymer-stabilized soils requires 90-180 day laboratory cycles, compressing project bidding windows and locking out speculative formulations.
- Cross-Functional Formulation Expertise:Product development teams must synthesize soil mechanics, polymer chemistry, and construction methodology knowledge bases that rarely coexist within single hiring pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Hardening Agent Market |
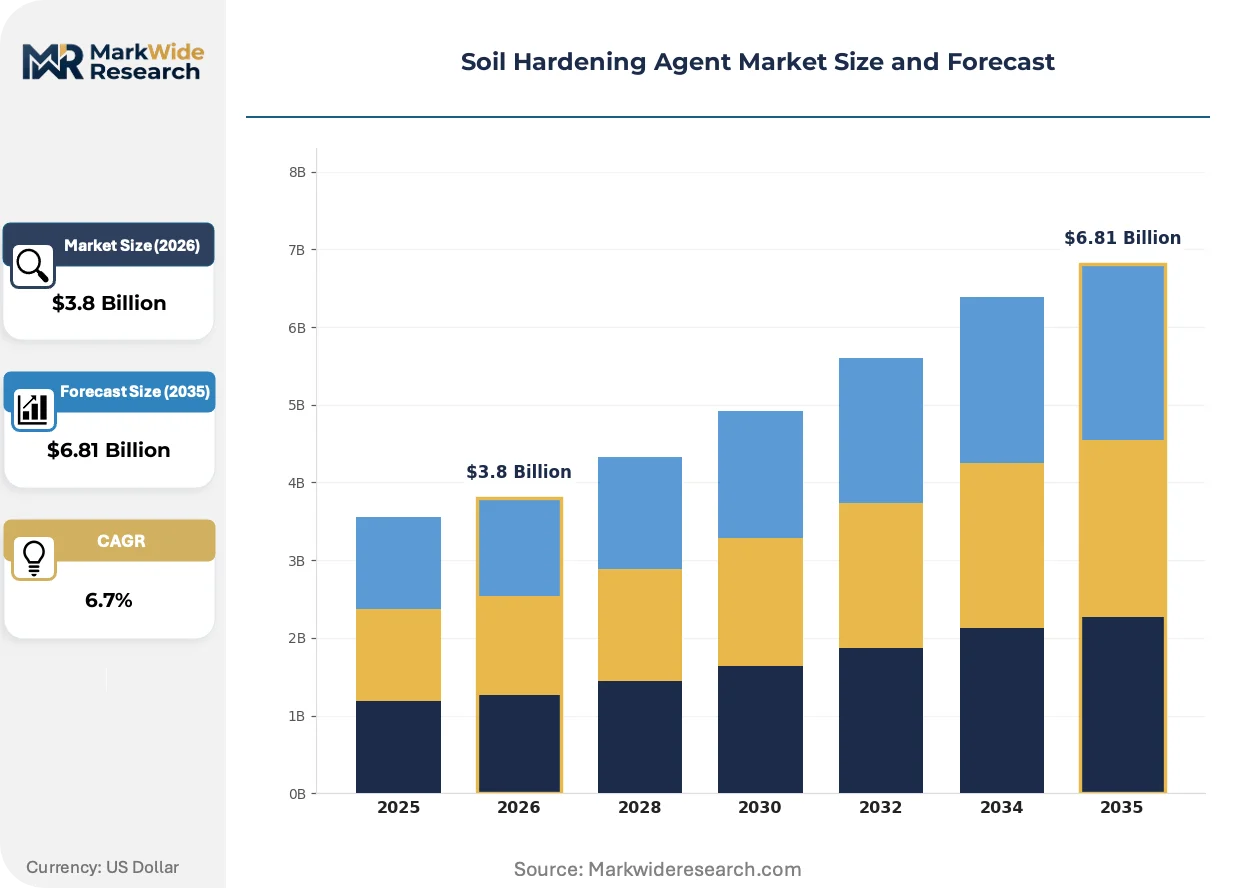
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Organic Compounds, Inorganic Salts, Polymers, Synthetic Agents Application: Construction, Agriculture, Landscaping, Soil Stabilization End User: Contractors, Farmers, Landscapers, Engineers Form: Liquids, Powders, Granules, Emulsions |
| Companies Covered | Dow Chemical Company, Akzo Nobel N.V., Evonik Industries AG, The Chemours Company, Clariant AG, Solvay S.A., Wanhua Chemical Group Co., Ltd., Nouryon, Sinopec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Hardening Agent Market Strategic Shifts
Biopolymer feedstocks and nanoscale additive systems are actively reconfiguring formulation economics. Material science advances now enable performance parity with synthetic polymers at reduced regulatory liability exposure.
Acrylic-epoxy hybrid polymers is integrating into airport runway specifications through Dow Chemical's polyurethane infrastructure contracts. Military aviation authorities in the United States specify these systems for rapid-deployment airfield hardening where cure time compression below 24 hours is mandatory. The technology is integrating performance thresholds previously reserved for Portland cement overlays while eliminating particulate emission during construction phases.
REACH Annex XVII restrictions on microplastic-releasing products are forcing reformulation of legacy dust-suppression emulsions across European construction supply chains. German road-building consortia now require polymer biodegradability certifications from ECHA-registered laboratories prior to tender submission. French infrastructure agencies have accelerated procurement of lignosulfonate-based alternatives in anticipation of 2027 enforcement milestones.
Consolidated procurement through state-owned construction enterprises is displacing fragmented contractor-level purchasing across Asian markets. China's Ministry of Transport centralized tender platforms now specify multi-year volume commitments with price adjustment clauses tied to isocyanate indices. This concentration is visible most acutely in Sichuan and Yunnan provincial highway corridors where polymer stabilizer contracts exceed 10,000-tonne annual minimums.
Soil Hardening Agent Market Segmentation
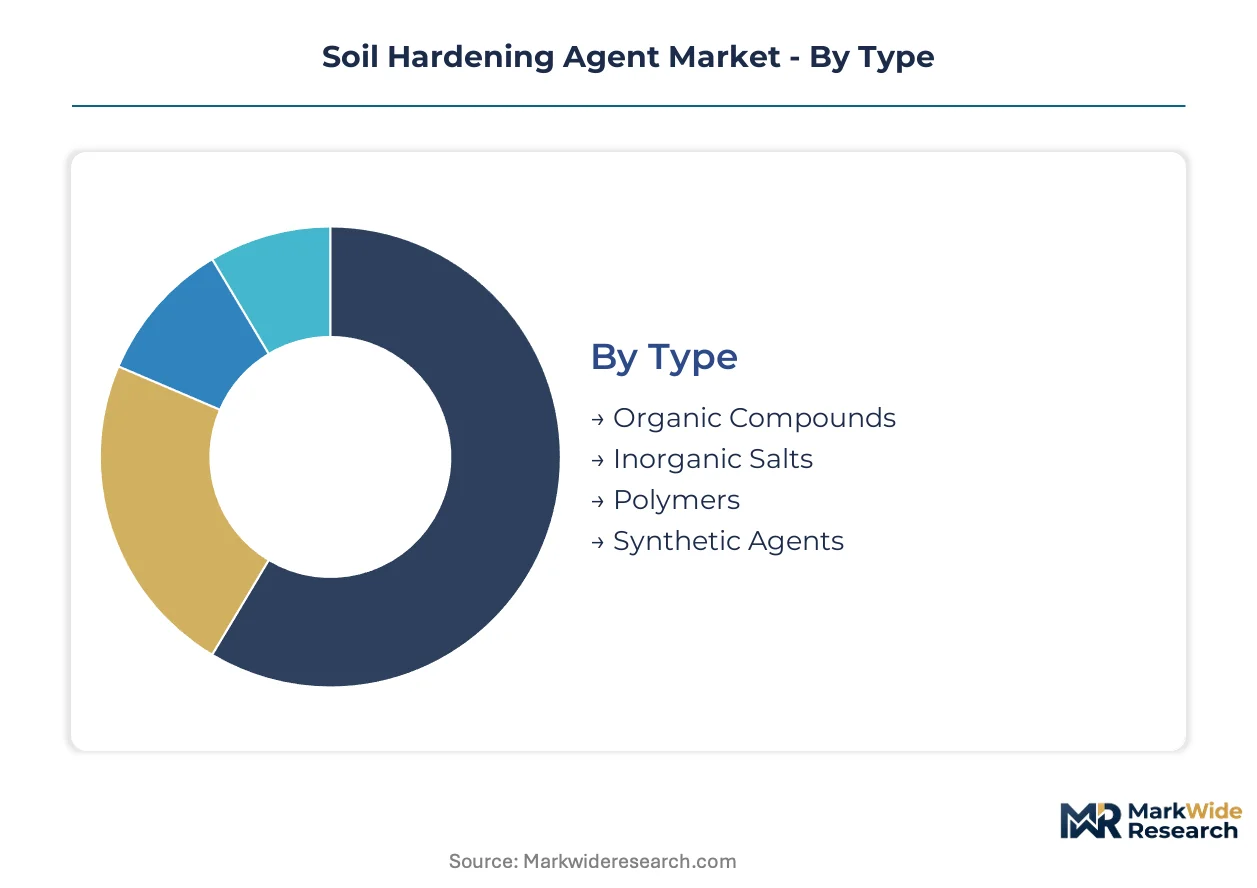
Product differentiation in soil hardening agents determines specification pathways across federal infrastructure, commercial construction, and agricultural land management. Segmentation reveals how formulation chemistry, physical state, and buyer type create distinct margin pools and regulatory exposure profiles.
Type:
Volume concentration favors commodity-grade inorganics, while premium capture concentrates in specialty polymers with certified performance thresholds.
- Organic Compounds:Lignosulfonate and tannin-based formulations derived from forestry byproducts. Demand clusters in European road-building tenders where REACH biodegradability certifications are mandatory for dust-suppression contracts.
- Inorganic Salts:Calcium chloride and magnesium chloride compounds applied at 1-2% soil weight. Procurement concentrates with municipal highway departments in Arizona and Texas seeking low-cost stabilization for unpaved county roads.
- Polymers:Acrylic and polyurethane systems commanding specification premiums. Airport runway hardening under FAA ultra-low dust emission standards drives adoption across military and civilian airfield contracts.
- Synthetic Agents:Organosilane-modified binders engineered for saline degradation resistance. Coastal infrastructure projects in Florida and the Netherlands specify these for seawall-adjacent stabilization corridors.
Mature deployment sits with Inorganic Salts. Newer deployment is concentrated in Synthetic Agents.
Application:
Cost tier separation runs from high-specification federal contracts to price-sensitive agricultural field preparation.
- Construction:Load-bearing foundation treatments for commercial and residential building pads. Indian road contractors under BIS certification mandates are expanding procurement of polymer stabilizers for National Highway widening projects.
- Agriculture:Field hardening for mechanized harvesting access and erosion control. Dust suppression on California Central Valley almond orchards drives seasonal demand spikes during pre-harvest ground preparation.
- Landscaping:Water-efficient ground preparation for public parks and median strips. Drought-prone municipalities in Texas and Arizona mandate these emulsions for xeriscape installations, representing the steepest expansion trajectory among application segments.
- Soil Stabilization:Subgrade modification for heavy-haul surfaces and desertification control. China's state-owned construction enterprises deploy synthetic agents across Inner Mongolia stabilization corridors under dual carbon goal timelines.
Revenue concentration favors Construction. Margin expansion concentrates in Landscaping.
End User:
Customer type determines procurement channel structure, from centralized state-enterprise tenders to fragmented contractor spot purchasing.
- Contractors:Road-building and commercial construction firms with multi-project chemical requirements. India's Ministry of Road Transport and Highways certification protocols force these buyers toward BIS-approved polymer imports or domestic formulations.
- Farmers:Individual agricultural operators and cooperative associations. Price sensitivity drives preference for bulk inorganic salts applied through irrigation systems or surface spray rigs.
- Landscapers:Municipal maintenance crews and commercial groundskeeping services. Specification authority varies—city procurement departments set emulsion standards while contractors execute application.
- Engineers:Geotechnical consultants and design firms influencing specification at the tender stage. California Bearing Ratio certification requirements create 90-180 day validation cycles that these stakeholders navigate for polymer-stabilized soil approvals.
Procurement scale concentrates with Contractors. Specification influence concentrates with Engineers.
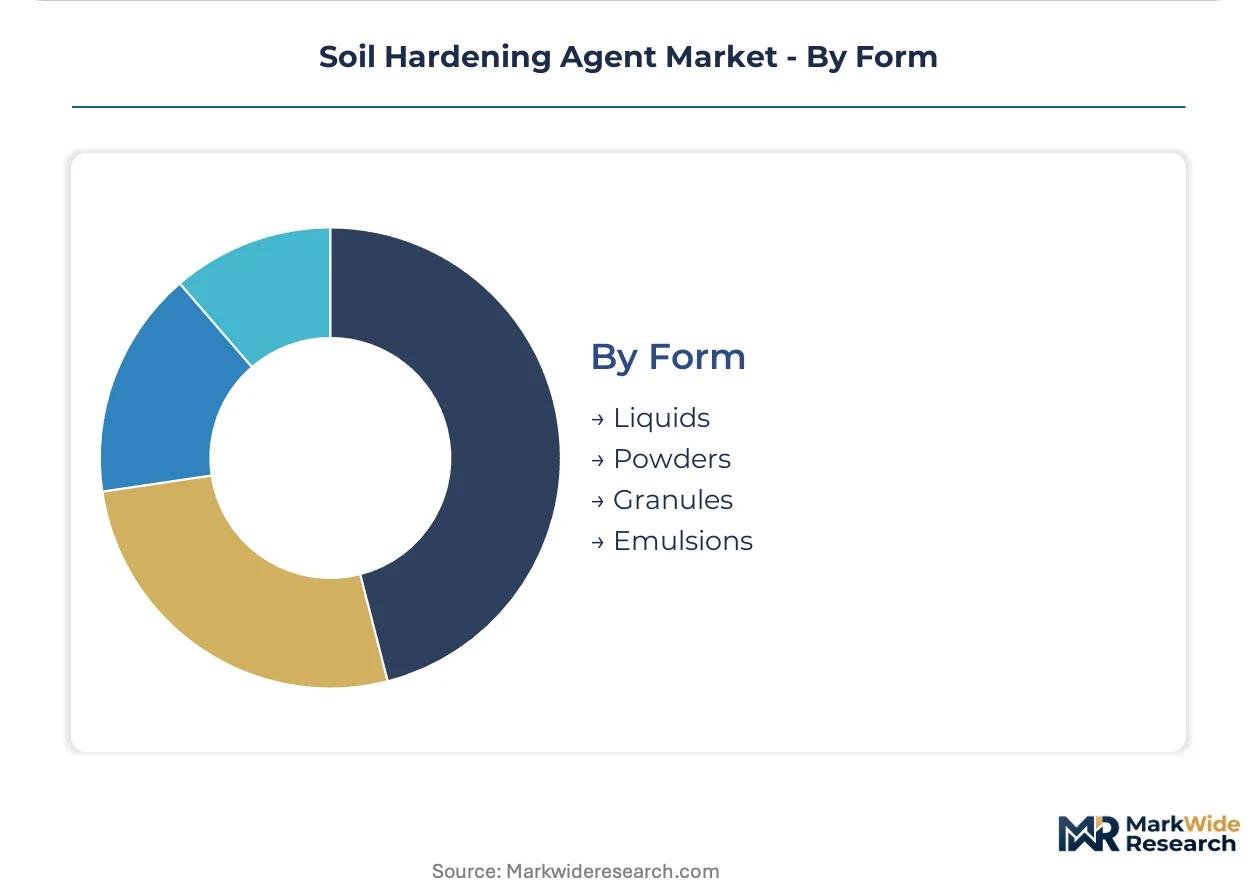
Form:
Physical state dictates application equipment compatibility and logistics economics across dispersed project sites.
- Liquids:Ready-to-spray emulsions requiring minimal site preparation. Airport runway contractors favor these for rapid-deployment hardening where cure time compression below 24 hours is mandatory.
- Powders:Cementitious blends and dried polymer concentrates. Bulk rail delivery to remote highway corridors in Xinjiang and Sichuan provinces supports China's centralized state-enterprise procurement model.
- Granules:Slow-release formulations for extended dust suppression. Agricultural access road maintenance in Australia's wheat belt employs these for seasonal reapplication reduction.
- Emulsions:Water-based suspensions of polymer or lignosulfonate active ingredients. REACH Annex XVII microplastic restrictions are forcing reformulation of legacy dust-suppression emulsions across German and French supply chains.
Logistics efficiency sits with Powders. Regulatory adaptation pressure concentrates in Emulsions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isocyanate production clusters in Ningbo and Shanghai anchor polymer supply for Asian infrastructure markets. Feedstock proximity shapes procurement economics across desertification corridors and airport hardening projects.
United States
FAA ultra-low dust emission standards for military and civilian airfields drive specification upgrades toward acrylic polymer systems. EPA stormwater regulations constrain product selection for federal infrastructure contracts. Texas and Arizona municipal landscaping departments mandate water-efficient ground preparation emulsions for public parks.
China
State-owned construction enterprises deploy synthetic hardening agents across Inner Mongolia and Xinjiang stabilization corridors under dual carbon goal timelines. The Ministry of Transport centralized tender platforms specify multi-year volume commitments with price adjustment clauses. Sichuan and Yunnan provincial highway corridors concentrate polymer stabilizer procurement exceeding 10,000-tonne annual minimums.
India
Road construction contractors face mandatory BIS certification compliance for dust-suppression chemicals under Ministry of Road Transport and Highways protocols. National Highway widening projects expand procurement of certified polymer stabilizers. Western and southern state highway departments accelerate tender submissions for geotechnical applications.
Germany
REACH Annex XVII restrictions on microplastic-releasing products force reformulation of legacy dust-suppression emulsions. ECHA registration timelines delay product qualification for geotechnical tenders. German road-building consortia now require polymer biodegradability certifications prior to tender submission.
France
French infrastructure agencies accelerate procurement of lignosulfonate-based alternatives in anticipation of 2027 REACH enforcement milestones. ANSM and CNIL oversight intersects with construction chemical compliance frameworks. Provincial highway authorities in Auvergne-Rhône-Alpes pilot organosilane-modified binders for saline degradation resistance.
Soil Hardening Agent Market Competitive Environment
Capacity expansion dominates the current landscape as specialty chemical producers build captive resin capacity to displace traditional Portland cement relationships. The market structure concentrates around three tiers: multinational diversified chemical conglomerates with polyurethane expertise, regional specialists in organosilane and acrylic formulations, and state-backed Asian producers with vertical feedstock control. Strategic archetypes include premium polymer innovators, commodity inorganic salt suppliers, and direct-distribution state enterprise partners. M&A activity and geographic expansion through state procurement portals represent the dominant competitive moves reshaping supply relationships.
Among multinational chemical conglomerates, Dow Chemical Company and Evonik Industries AG exemplify divergent specialization strategies within the premium tier. Dow anchors North American infrastructure positioning through polyurethane backbone systems, while Evonik occupies a specialist position in organosilane modifiers for geotechnical applications. Wanhua Chemical Group Co., Ltd. represents the state-backed Asian archetype, leveraging captive isocyanate production and direct sales channels to state-owned construction enterprises. These three players collectively illustrate how feedstock control, regulatory compliance expertise, and distribution channel configuration determine competitive positioning across federal, municipal, and state-enterprise procurement segments.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Akzo Nobel N.V. |
| Evonik Industries AG |
| The Chemours Company |
| Clariant AG |
| Solvay S.A. |
| Wanhua Chemical Group Co., Ltd. |
| Nouryon |
| Sinopec |
| Others |
Value Chain & Pricing Dynamics
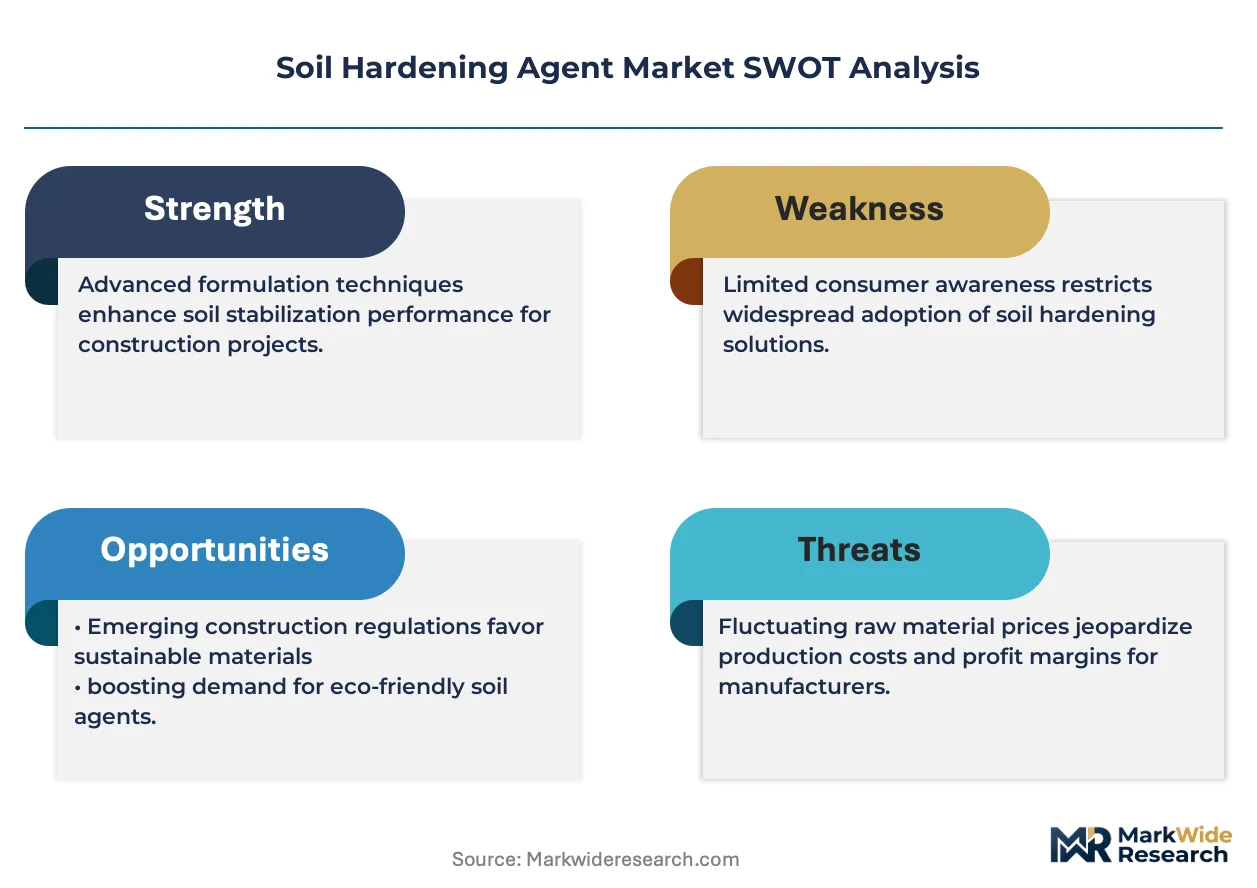
Isocyanate feedstock costs originating from Ningbo and Shanghai petrochemical clusters cascade through polymer-grade pricing tiers, with MDI precursor volatility compressing margins for non-integrated formulators while anchoring premium positioning for producers with captive resin capacity.
Pricing Analysis
Warranty-backed California Bearing Ratio certification bundled with polymer stabilizer sales commands 15-25% premiums over unbundled commodity formulations. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified acrylic systems from BIS-compliant road-grade polymers and bulk inorganic salts. Cost compression in standard-tier road construction chemicals is intensifying because Indian contractors face mandatory certification outlays without corresponding specification premiums. Farmers and agricultural cooperatives exhibit the highest price sensitivity, while airport authorities and military procurement offices demonstrate minimal elasticity due to emission-mandated performance floors.
Supply Chain Analysis
Single-source vulnerability sits with Chinese MDI precursor production concentrated in Wanhua Chemical's Ningbo facilities. Manufacturing gravity centers on China, Germany, and the United States for specialty polymer synthesis, while India and Brazil host blending operations for regional road construction markets. Feedstock dependencies include isocyanate resins, organosilane modifiers, and lignosulfonate derivatives from forestry processing. Tariff exposure on European polymer imports into India threatens to disrupt BIS certification timelines for geotechnical tenders. Distribution runs through state-owned construction enterprise procurement portals in China, fragmented contractor networks in India, and specification-influenced engineer channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH Annex XVII microplastic restrictions and EPA PFAS elimination timelines will force smaller formulators without biodegradability certifications into distressed exits or acquisition.
For Market Incumbents: To counter REACH-driven reformulation costs eroding legacy dust-suppression margins, Dow Chemical and Evonik should deepen backward integration into biopolymer feedstocks and accelerate ECHA-registered laboratory partnerships for biodegradability certification. Capacity addition in India's western and southern state highway corridors captures BIS-mandated procurement windows before domestic formulation rivals achieve certification parity. For New Entrants and Emerging Players: Begin with municipal landscaping emulsions in Arizona, California, and Texas drought-prone municipalities where water-efficient ground preparation mandates create specification openings without entrenched incumbent relationships. Agricultural field hardening for California Central Valley almond orchards offers seasonal demand spikes with lower certification barriers than federal infrastructure contracts. Direct sales to municipal procurement departments bypasses distributor margin extraction. For Investors and Strategic Acquirers: Wanhua Chemical's volume-locked state enterprise contracts exceeding 10,000-tonne annual minimums are the leading indicator that captive isocyanate capacity with direct distribution channels commands durable competitive moats. Acquisition targets should prioritize mid-tier polymer formulators with pending BIS or REACH certifications and established geotechnical validation relationships, viewed through a decade-long infrastructure replacement cycle. Monitor ECHA registration timeline delays as the signal for European market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Feedstocks | Reduces REACH regulatory liability exposure for European dust-suppression contracts. |
| ECHA-Registered Laboratory Partnership | Accelerates polymer biodegradability certification for German and French road-building tenders. |
| Direct State-Enterprise Distribution | Bypasses fragmented contractor networks to capture China's Ministry of Transport volume commitments. |
| California Bearing Ratio Certification Investment | Unlocks FAA ultra-low dust emission airport runway specifications with 90-day validation cycles. |
| Organosilane-Modified Binder Development | Targets coastal infrastructure in Florida and the Netherlands with saline degradation resistance. |
Study Parameters
Independent corroboration across construction chemical procurement managers, geotechnical consulting engineers, and polymer R&D directors underwrites the qualitative findings. Primary interviews with road-building contractors in India, airport runway specification officers in the United States, and state-owned enterprise supply chain leads in China were validated against secondary sources including BIS certification registries, ECHA substance databases, FAA pavement standards documentation, and customs trade data for isocyanate precursor flows. Bottom-up segment sizing and top-down market triangulation were reconciled across the analysis window.
Historical reference periods spanning pre-pandemic infrastructure investment baselines through emission regulation implementation phases anchored the projection horizon. The analytical framework modeled formulation chemistry tiers, application segments from soil stabilization to landscaping, end-user procurement channels, and physical form factors across regional production hubs. CAGRs were derived from volume-demand elasticity functions tied to highway construction budgets and airport capital expenditure disclosures, with isocyanate price indices and certification timeline assumptions as key forecast inputs.
Feedstock price volatility, regulatory enforcement timeline delays, and geotechnical validation bottlenecks are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about BIS certification adoption rates and REACH Annex XVII implementation phasing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market