
 Brazil Bioplastics Market | 2026-2036
Brazil Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Bioplastics Market Insights
A shortage of polymer chemists trained in fermentation-based processing is unwinding capacity expansion timelines across Brazilian bioplastics producers. Braskem leverages its petrochemical infrastructure to anchor integrated biopolymer production at its Triunfo complex. Novamont SpA sustains technology leadership in starch-based formulations through dedicated R&D partnerships with Brazilian agricultural institutes. Natureworks LLC competes via its global PLA expertise, positioning imported resin grades for premium packaging applications in southeastern Brazil.
Brazil bioplastics comprise renewable-derived polymers engineered to biodegrade or compost under specified conditions, typically synthesized from sugarcane ethanol, corn starch, or microbial fermentation of plant sugars, with melt flow indices and tensile properties tailored to extrusion and injection molding processes. These materials serve primarily as drop-in replacements for fossil-based plastics in applications demanding end-of-life environmental performance. PLA dominates current volume flows due to mature supply chains and processing familiarity among Brazilian converters, while PHA occupies a nascent but high-margin niche in agricultural mulch films where soil biodegradability commands price premiums. Starch-based blends anchor the economy tier, competing on cost parity with conventional plastics for short-life packaging in retail and food service channels.
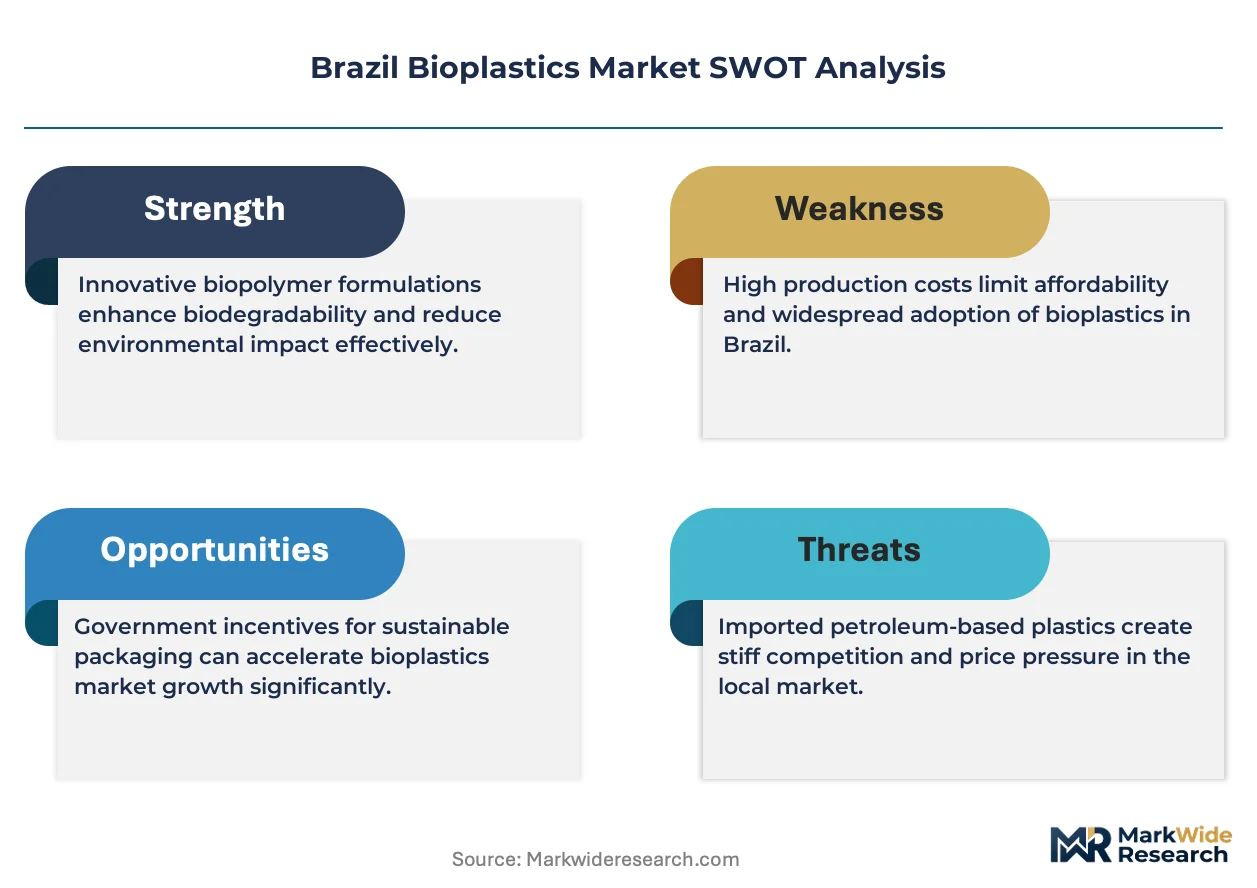
ANVISA governs food-contact bioplastic safety standards, while the National Solid Waste Policy establishes extended producer responsibility frameworks that shape collection and composting infrastructure investments. State-level environmental agencies in São Paulo and Minas Gerais enforce plastic restriction statutes that directly pull bioplastic substitution demand from municipal procurement specifications. Stakeholders must monitor pending federal bioplastic certification standards and pre-position compliance capabilities before mandatory labeling requirements take effect.
Market Dynamics
São Paulo municipal single-use plastic ordinances are forcing packaging converters to retool extrusion lines for compostable films, creating a demand pull that outpaces domestic biopolymer fermentation capacity and concentrates procurement power among agricultural feedstock suppliers.
Growth Catalysts
- ANVISA food-contact safety standards:Clear certification pathways for PLA and starch-based food packaging reduce regulatory uncertainty for converters serving retail chains.
- Sugarcane ethanol feedstock abundance:Brazilian sugarcane mills provide cost-advantaged sugar streams that lower lactic acid production costs versus corn-based North American supply chains.
- Extended Producer Responsibility frameworks:The National Solid Waste Policy mandates post-consumer collection infrastructure, creating guaranteed offtake channels for certified compostable packaging.
Market Restraints
- Polymer chemist shortage:Brazilian universities graduate fewer than fifty fermentation-process specialists annually, stretching R&D timelines at domestic producers.
- PLA import dependency:Natureworks LLC controls premium resin supply for southeastern Brazil, exposing converters to currency volatility and ocean freight delays.
- Conventional polyethylene price compression:Braskem's petrochemical complexes at Triunfo and Camaçari maintain fossil-based resin at cost parity that undercuts bioplastic premiums in non-mandated applications.
Strategic Opportunities
- Minas Gerais agricultural mulch films:Coffee and soybean cooperatives seek soil-biodegradable alternatives to polyethylene sheeting, opening high-margin PHA demand.
- Federal bioplastic certification standards:Pending mandatory labeling requirements will advantage early compliance investments by domestic compounders.
- Supermarket private-label packaging:Carrefour and GPA consolidation creates volume commitments that justify dedicated bioplastic film production lines.
Industry Challenges
- Fermentation scale-up engineering:Translating pilot PHA yields to industrial bioreactors demands process engineers scarce in Brazilian labor markets.
- Composting infrastructure certification:Industrial composting facilities must secure ANVISA and state environmental agency approvals before accepting food-contact bioplastic waste streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Bioplastics Market |
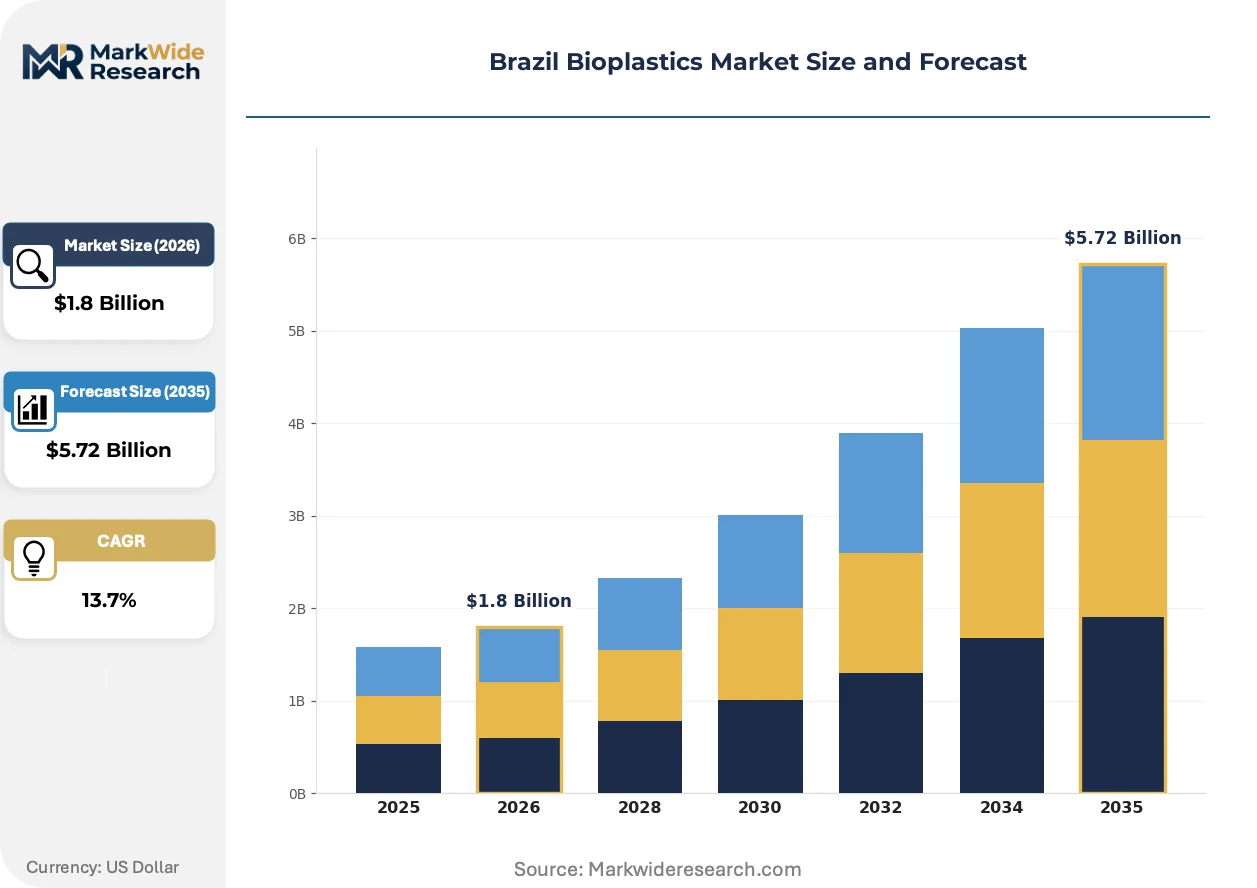
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, Starch-Based, PHA, Cellulose-Based Application: Packaging, Agriculture, Automotive, Consumer Goods End User: Food Industry, Retail, Healthcare, Electronics Distribution Channel: Online Retail, Direct Sales, Wholesale, Exports |
| Companies Covered | Braskem, Novamont SpA, Natureworks LLC, Bioreset Biotecnologia Ltda, Cardia Bioplastics, BASF SE, Dow Inc., Total Corbion PLA, Versalis S.P.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Bioplastics Market Trends and Innovations
Bioplastic processing technologies are converging with Brazilian agricultural supply chains to reshape material specifications and converter capabilities across the packaging value chain.
PHA fermentation platforms are displacing imported PLA in agricultural applications where soil biodegradability commands functional premiums. Coffee cooperatives in Minas Gerais pilot PHA mulch films that eliminate retrieval labor costs. The technology is displacing conventional polyethylene in crop protection films where mechanical collection proves uneconomical.
State environmental agencies in São Paulo and Minas Gerais enforce plastic restriction statutes that mandate bioplastic substitution in municipal procurement. These statutes compress compliance timelines for packaging converters serving retail and food service channels. Food-contact bioplastic grades face accelerated safety review queues at ANVISA as converter applications multiply.
Food industry buyers now specify compostable packaging certifications as mandatory bid criteria rather than preferred attributes. Large retail chains consolidate supplier panels around converters with validated industrial composting partnerships. This specification shift concentrates volume among southeastern Brazil compounders with established certification track records.
Brazil Bioplastics Market Segmentation
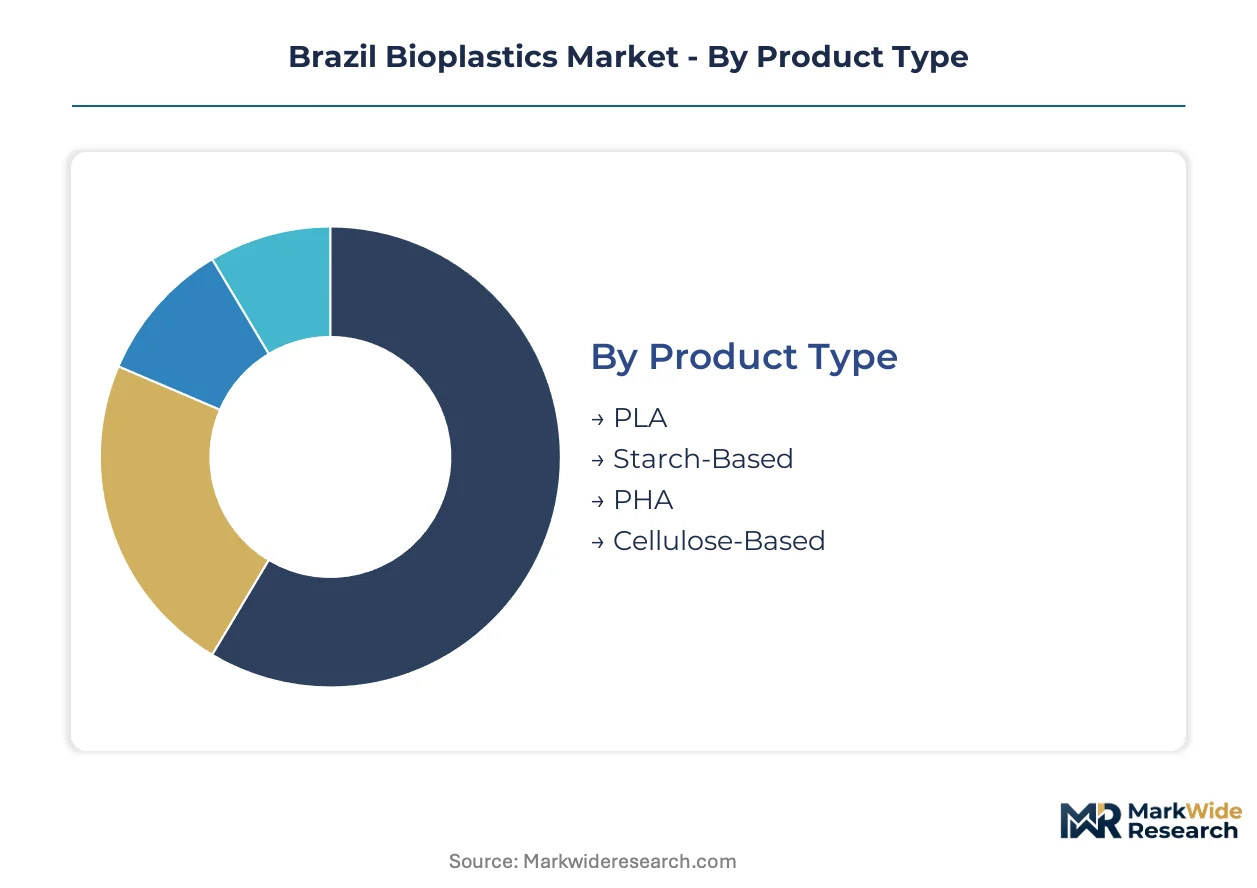
Bioplastic purchasing patterns in Brazil diverge sharply across product chemistry and end-use specifications. ANVISA food-contact certifications and state-level plastic ordinances create tiered demand profiles that reward early compliance investments by compounders and converters.
Product Type:
ANVISA certification pathways favor PLA and starch-based formulations with established safety dossiers, while PHA and cellulose derivatives navigate longer review queues for novel polymer approvals.
- PLA:Polylactic acid derived from sugarcane ethanol dominates Brazilian bioplastic volumes through mature fermentation infrastructure at domestic mills. São Paulo packaging converters specify PLA for food-contact films under municipal single-use plastic bans. Braskem's Triunfo complex and imported Natureworks resin anchor supply security for premium extrusion grades.
- Starch-Based:Thermoplastic starch blends from cassava and corn feedstocks compete on cost parity with conventional polyethylene in short-life applications. Retail chains in southeastern Brazil specify starch-based bags for private-label compliance with extended producer responsibility mandates. Novamont SpA technology licenses sustain formulation leadership through agricultural institute partnerships.
- PHA:Polyhydroxyalkanoates from microbial fermentation serve high-margin agricultural mulch films where soil biodegradability eliminates retrieval labor.
- Cellulose-Based:Regenerated cellulose and cellulose acetate derivatives target specialty packaging with moisture-barrier requirements.
PLA handles the majority of throughput; PHA is gaining share fastest on agricultural premium pricing.
Application:
Volume concentration tracks state environmental enforcement intensity, with packaging mandates in São Paulo and Minas Gerais pulling disproportionate compounder capacity.
- Packaging:Flexible films and rigid containers absorb the bulk of Brazilian bioplastic resin flows. Supermarket chains Carrefour and GPA consolidate procurement around certified compostable specifications. Extrusion line retrofits for PLA and starch-based films accelerate across São Paulo state converter bases.
- Agriculture:Coffee and soybean cooperatives in Minas Gerais pilot soil-biodegradable mulch films that displace polyethylene sheeting. PHA formulations command functional premiums where mechanical collection proves uneconomical on sloped terrain.
- Automotive:Interior trim and under-hood applications specify bio-based polyamides and polyesters for OEM sustainability scorecards.
- Consumer Goods:Disposable cutlery and food service items face municipal procurement mandates driving starch-based substitution.
Packaging commands the dominant share of resin offtake; agriculture posts the steepest expansion trajectory on cooperative volume commitments.
End User:
Buyer sophistication varies by sector certification requirements, with food industry procurement teams leading technical specification development.
- Food Industry:Processors and brand owners mandate compostable packaging certifications as mandatory bid criteria rather than preferred attributes. ANVISA safety reviews for food-contact grades face accelerated queues as converter applications multiply.
- Retail:Large chains consolidate supplier panels around converters with validated industrial composting partnerships. Private-label packaging specifications concentrate volume among southeastern Brazil compounders with established certification track records.
- Healthcare:Medical device and pharmaceutical packaging face stringent sterility and barrier property requirements that limit current bioplastic penetration.
- Electronics:Consumer electronics brands specify bio-based housing materials for sustainability marketing differentiation.
Food industry buyers drive the largest volume commitments; retail procurement is expanding most quickly on consolidation-driven standardization.
Distribution Channel:
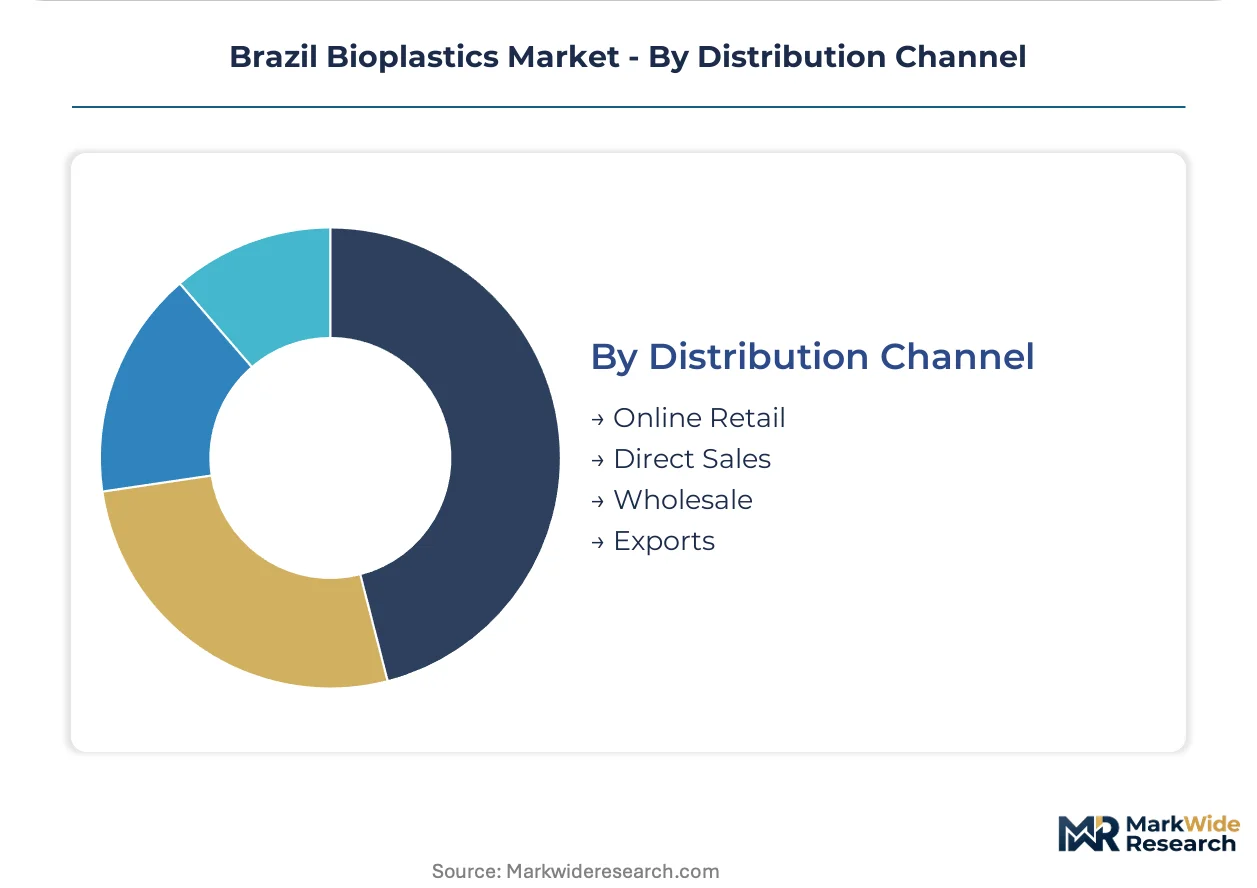
Channel selection reflects buyer scale and technical support requirements, with large converters bypassing intermediaries for direct mill relationships.
- Direct Sales:Braskem and major compounders maintain dedicated technical service teams for high-volume packaging converters. Direct relationships enable custom formulation development for proprietary film specifications.
- Wholesale:Regional distributors stock standard PLA and starch-based grades for small and mid-tier converters lacking volume commitments for mill-direct purchasing.
- Online Retail:E-commerce platforms serve specialty buyers and research institutions requiring small-batch experimental formulations.
- Exports:Brazilian sugarcane-derived bioplastics target Mercosur trade partners with aligned regulatory standards.
Direct sales capture the dominant share of resin volume; wholesale channels are climbing the fastest on mid-tier converter expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian bioplastic consumption concentrates in southeastern states where municipal plastic bans intersect with sugarcane ethanol infrastructure, while northern and northeastern regions lag on converter capacity and composting logistics.
São Paulo
Metropolitan packaging converters drive the majority of PLA and starch-based film demand following municipal single-use plastic ordinances. ANVISA maintains accelerated safety review queues for food-contact bioplastic grades from facilities in the Greater ABC industrial corridor. Campinas anchors fermentation-based biopolymer R&D partnerships between agricultural institutes and compounders.
Minas Gerais
Coffee and soybean cooperatives generate premium-priced PHA demand for soil-biodegradable mulch films on sloped terrain where mechanical polyethylene retrieval proves uneconomical. State environmental agencies enforce plastic restriction statutes that mandate bioplastic substitution in agricultural procurement specifications. Uberlândia hosts pilot-scale PHA fermentation platforms serving regional cooperative volume commitments.
Rio de Janeiro
Petrochemical infrastructure at the Campos Basin supports Braskem's integrated biopolymer production alongside conventional polyethylene output. State-level extended producer responsibility frameworks shape post-consumer collection infrastructure investments across the metropolitan region. Duque de Caxias converter clusters retool extrusion lines for compostable film specifications serving retail distribution networks.
Rio Grande do Sul
Soybean processing residuals supply starch-based bioplastic feedstocks to compounders serving southern Brazil retail chains. State environmental statutes align with federal National Solid Waste Policy mandates on packaging waste collection targets. Porto Alegre packaging clusters specialize in short-life food service items for private-label supermarket compliance programs.
Paraná
Sugarcane ethanol mills in the northern region provide cost-advantaged sugar streams that lower lactic acid production costs for PLA compounders. State agricultural extension services promote soil-biodegradable mulch film trials among corn and wheat cooperatives. Londrina hosts mid-tier converters purchasing standard PLA grades through wholesale distribution channels.
Brazil Bioplastics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Brazilian bioplastics. Petrochemical conglomerates leverage existing fermentation infrastructure and feedstock integration to dominate volume production, while agricultural technology specialists and global PLA pure-plays occupy premium niches. The market rewards backward integration into sugarcane ethanol supply chains and penalizes converters dependent on imported resin grades. Capacity expansion and strategic technology licensing represent the dominant competitive moves as domestic fermentation scale-up accelerates.
Among the integrated petrochemical leaders, Braskem anchors biopolymer production at its Triunfo complex with captive sugarcane ethanol supply. Novamont SpA and Natureworks LLC exemplify contrasting international entry modes—technology licensing partnerships versus direct resin import positioning. BASF SE and Total Corbion PLA represent multinational compounders navigating ANVISA certification pathways for food-contact grades. Bioreset Biotecnologia Ltda occupies a position among domestic fermentation specialists targeting agricultural mulch film applications.
| Leading Market Players |
|---|
| Braskem |
| Novamont SpA |
| Natureworks LLC |
| Bioreset Biotecnologia Ltda |
| Cardia Bioplastics |
| BASF SE |
| Dow Inc. |
| Total Corbion PLA |
| Versalis S.P.A |
| Others |
Pricing and Supply Chain Analysis
Braskem's Triunfo complex leverages captive sugarcane ethanol supply to anchor domestic PLA production at scale, compressing price floors for southeastern Brazil converters while forcing import-dependent competitors into premium positioning. This scale concentration simultaneously elevates procurement power among agricultural feedstock suppliers and fragments margin capture across fermentation-based specialists lacking backward integration.
Pricing Analysis
Long-term offtake contracts dominate bioplastic resin procurement between Braskem and high-volume São Paulo packaging converters, insulating domestic compounders from currency volatility while spot markets govern imported Natureworks PLA grades. Price differentiation rests on ANVISA certification tier and volume scale, with food-contact certified PLA commanding substantial premiums over industrial grades. Cost compression in starch-based formulations is intensifying because cassava feedstock competition from food processors is tightening agricultural supply. Small and mid-tier converters exhibit highest price sensitivity, lacking volume commitments for mill-direct purchasing and exposed to wholesale distributor markups.
Supply Chain Analysis
Brazil and the United States anchor bioplastic resin supply, with Brazilian sugarcane ethanol infrastructure feeding domestic PLA fermentation and American corn-based lactic acid production supporting Natureworks import flows. The supply chain draws from sugarcane mills, cassava processors, and microbial fermentation platforms as core inputs. Single-source vulnerability concentrates in premium PLA grades where Natureworks controls southeastern Brazil supply. Distribution runs through direct mill relationships for high-volume converters and regional wholesale channels for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian bioplastics fragmentation creates entry niches as municipal plastic ordinances splinter demand across state-level enforcement regimes and certification tiers. ANVISA's pending mandatory labeling standards will advantage early compliance investments by domestic compounders.
For Market Incumbents: Secure captive sugarcane ethanol supply through mill partnerships or equity stakes to defend margin position against import-dependent competitors exposed to currency swings. Accelerate ANVISA pre-certification for pending federal bioplastic labeling mandates before compliance windows compress. Braskem's Triunfo integration model demonstrates how backward integration into agricultural feedstock insulates pricing power.
For New Entrants and Emerging Players: ANVISA fast-track certification for food-contact PLA grades opens immediate revenue channels as converter applications multiply and review queues lengthen. Target Minas Gerais agricultural mulch films where PHA soil-biodegradability commands functional premiums and mechanical polyethylene retrieval proves uneconomical. Partner with coffee cooperatives for pilot-scale volume commitments that justify dedicated fermentation capacity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with validated industrial composting partnerships and multi-year supermarket private-label contracts. Five-to-ten year viability favors domestic fermentation specialists with agricultural institute R&D ties and state environmental agency compliance track records. Watch federal bioplastic certification standard promulgation as inflection indicator for mandatory labeling-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugarcane Ethanol | Captive feedstock supply locks in cost advantage against import-dependent PLA competitors. |
| ANVISA Pre-Certification Investment | Early compliance with pending federal labeling mandates secures converter procurement preference. |
| PHA Fermentation Scale-Up | Agricultural mulch film premiums in Minas Gerais justify capital deployment for soil-biodegradable grades. |
| Industrial Composting Partnership | Validated waste-stream offtake channels satisfy extended producer responsibility mandates for retail chains. |
| Agricultural Institute R&D Alliance | Novamont-style technology licensing partnerships accelerate starch-based formulation development. |
Research Methodology
A standing panel of polymer chemists, packaging converter procurement managers, sugarcane mill operations directors, and ANVISA regulatory affairs specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from customs trade data, National Solid Waste Policy implementation reports, ANVISA food-contact safety filings, and state environmental agency enforcement records. Bottom-up resin volume estimates triangulated against top-down market sizing from agricultural feedstock availability models.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeling across product chemistry, application vertical, end-user sophistication tier, and regional enforcement intensity. CAGRs derived from feedstock cost trajectory analysis and converter capacity expansion timelines, incorporating sugarcane ethanol price elasticity and municipal ordinance compliance deadlines as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside ANVISA certification pathway timelines, state-level plastic ordinance enforcement consistency, or sugarcane harvest yield assumptions would require recalibration. Forecasts reflect documented assumptions on fermentation scale-up engineering availability and industrial composting infrastructure deployment rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Europe Bioplastics Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Bio-PET Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Biopolymers Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market