
 Backing Material Market | 2026-2036
Backing Material Market Size, Share, and Industry Trends Forecast 2026-2036
Backing Material Market Analytics
Preventive maintenance contracts for adhesive film conditioning equipment is restructuring how backing material suppliers monetize long-term relationships. 3M leverages its coating technology leadership to sustain premium positioning across industrial tape applications. Tesa SE anchors European supply chains through specialized automotive interior bonding solutions.
Backing materials comprise substrates—typically paper, woven or non-woven fabrics, polymer films, or foam layers ranging from 0.05 mm to 3.0 mm thickness—that receive functional coatings to enable adhesion, protection, or structural support in finished goods. These materials serve as the foundational carrier in pressure-sensitive adhesive constructions, carpet tiles, medical dressings, and electronic device assembly, where peel strength and dimensional stability determine performance. Non-woven fabrics occupy the fastest-expanding product tier as medical device and hygiene manufacturers shift toward breathable, single-use substrates with controlled fiber density. Foam materials dominate margin pools in automotive interiors, where NVH (noise, vibration, harshness) specifications and thermal insulation requirements justify specialized acrylic or polyethylene formulations.
EPA guidelines on volatile organic compound emissions from coating operations and NHTSA flammability standards for vehicle interiors directly shape formulation choices and capital allocation across North American backing material producers. Japan's METI enforces JIS standards for electronics-grade adhesive tapes, creating compliance thresholds that filter supplier participation in precision coating segments. Stakeholders must monitor how evolving automotive lightweighting mandates and medical device biocompatibility certifications redistribute volume across substrate technologies and regional manufacturing footprints.
Market Dynamics
Automotive lightweighting mandates and electronics miniaturization are compressing substrate thickness tolerances while expanding functional requirements for thermal management and electromagnetic shielding across precision coating operations.
Growth Catalysts
- EPA VOC emission limits:Pressure-sensitive adhesive manufacturers in the United States are reformulating solvent-based coatings toward hot-melt and UV-curable alternatives, expanding demand for heat-resistant polyester and polypropylene film backings that withstand elevated processing temperatures.
- Japan electronics assembly clusters:METI-enforced JIS standards for cleanroom-grade adhesive tapes are filtering supplier participation toward precision coaters with sub-micron thickness control, consolidating procurement around certified substrate providers in Osaka and Nagoya manufacturing corridors.
- Polyimide film substrates:Flexible circuit board manufacturers are adopting ultra-thin polyimide backings for 5G antenna modules and foldable display bonding, displacing traditional PET films in high-frequency signal transmission applications.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyethylene formulations depend on propylene and ethylene derivatives, with price swings in Asian spot markets compressing margin predictability for foam backing producers serving automotive NVH specifications.
- East Asian coating concentration:Precision adhesive tape manufacturing clusters in Japan and South Korea control critical slit-and-spool capabilities, creating supply vulnerability for European and North American converters lacking captive metallization or silicone release coating assets.
- Fluoropolymer release liner dependence:Medical and electronics-grade pressure-sensitive adhesives require silicone-free release surfaces, with limited qualified suppliers of fluorinated ethylene propylene films creating procurement bottlenecks for sterile dressing manufacturers.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO serialization mandates for track-and-trace labeling are expanding demand for tamper-evident holographic label stocks with specialized paper and film backings, with domestic converters building coating capacity in Ahmedabad and Hyderabad.
- EU Green Deal chemical restrictions:REACH candidate list expansion for persistent organic pollutants is accelerating substitution of halogenated flame retardants in automotive interior foams, opening formulation partnerships between backing suppliers and bio-based additive developers.
- Direct-to-OEM digital platforms:Automotive tier suppliers are bypassing traditional distribution through integrated procurement portals, enabling real-time specification matching for customized foam laminates with embedded RFID authentication tags.
Industry Challenges
- Precision coating technician scarcity:Slot-die and micro-gravure coating operations require operators with rheology and web-handling expertise, with training programs at German and Japanese technical institutes failing to match retirement-driven attrition in specialized workforce pools.
- Biocompatibility certification timelines:ISO 10993 testing protocols for medical device backings extend 18-24 months, delaying market entry for novel antimicrobial non-woven substrates targeting advanced wound care applications.
- Multi-substrate lamination complexity:Automotive interior assemblies combining foam, fabric, and film layers with divergent thermal expansion coefficients generate delamination failures during climate cycling validation, requiring iterative adhesive matching that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backing Material Market |
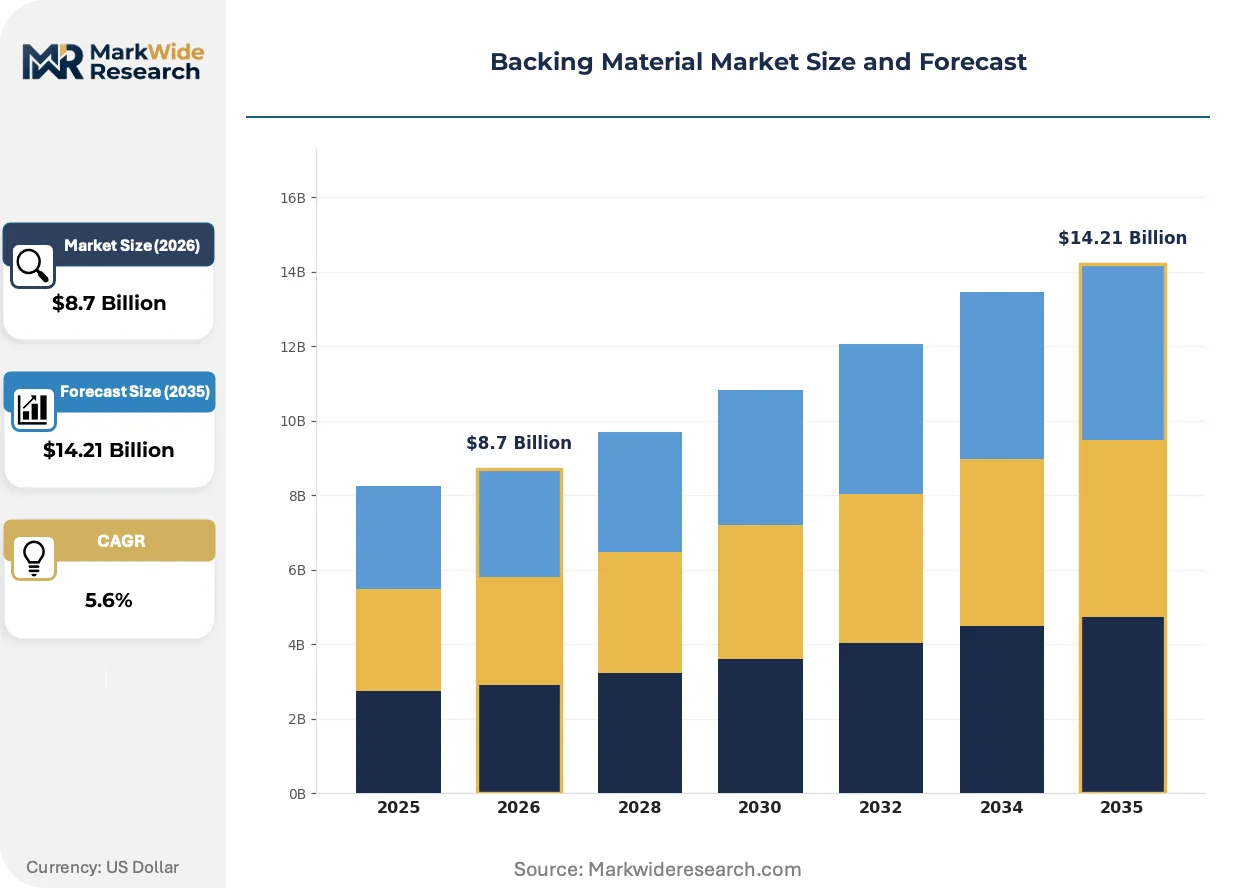
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Films, Foam Materials, Non-Woven Fabrics, Paper Application: Automotive Interiors, Construction, Electronics, Medical Devices End User: Manufacturers, Distributors, Retailers, Service Providers Technology: Coating, Layering, Printing, Laminating |
| Companies Covered | 3M, Interface, Inc., Mohawk Industries, Shaw Industries, Avery Dennison, Nitto Denko Corporation, Tesa SE, Intertape Polymer Group, Freudenberg Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backing Material Market Evolving Landscape
Substrate functionality is migrating from passive carrier roles toward active performance contributions, with surface engineering and embedded sensing capabilities redefining value capture in bonding and protection applications.
Water-based acrylic pressure-sensitive adhesives are overtaking solvent-borne systems in industrial tape manufacturing. Automotive interior suppliers in Germany and the United States are adopting these formulations to meet EPA emission thresholds without sacrificing shear strength on low-surface-energy plastics. The shift is compressing capital requirements for coating lines while disqualifying legacy solvent-recovery equipment from new facility investments.
Japan's METI has tightened JIS C 2107 standards for electronics-grade adhesive tape dimensional stability under humidity cycling. Precision coating operations serving semiconductor packaging and display assembly must now demonstrate sub-0.5% elongation variation across 85°C/85% RH test conditions. Suppliers lacking in-house polymer film orientation capabilities are exiting the qualified vendor lists of Tokyo and Seoul-based OEM procurement teams.
Automotive seating and headliner manufacturers are consolidating adhesive purchases through platform-level supply agreements rather than component-specific contracts. Tier suppliers now specify backing substrates across multiple interior modules, replacing discrete procurement for carpet, foam, and trim applications. This concentration is most visible in Michigan and Lower Saxony manufacturing corridors, where Volkswagen and Ford procurement teams have reduced qualified adhesive film vendors by 40% since 2022.
Backing Material Market Segmentation
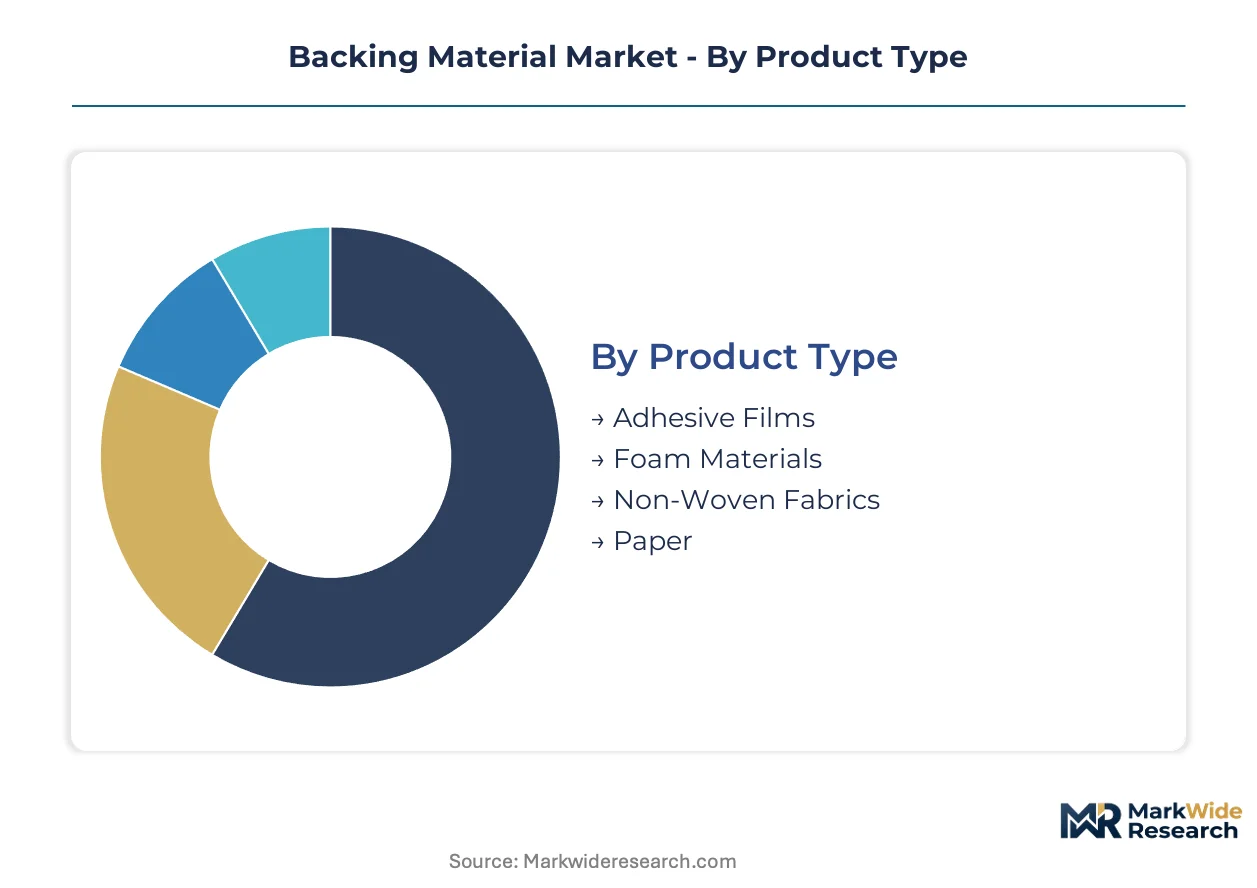
Backing material suppliers configure production assets around substrate thickness tolerances and coating precision requirements. Segmentation reveals where capital commitments concentrate and which technology platforms command premium positioning across adhesive, protective, and structural applications.
Product Type:
Capital intensity escalates with coating line complexity and substrate customization depth. Foam extrusion and precision film orientation demand the heaviest upfront investment.
- Adhesive Films:Polyester and polypropylene films receive silicone or fluoropolymer release coatings for pressure-sensitive tape constructions. Demand clusters in Osaka and Nagoya electronics corridors where METI-enforced JIS standards filter supplier participation toward precision coaters with sub-micron thickness control.
- Foam Materials:Polyethylene and polyurethane foams ranging 0.5 mm to 3.0 mm thickness provide NVH dampening and thermal insulation in automotive seating and headliner assemblies. German and US interior suppliers specify these substrates under EPA emission-compliant water-based acrylic bonding systems.
- Non-Woven Fabrics:Breathable synthetic fiber matrices serve medical dressings and hygiene products with controlled porosity for moisture vapor transmission.
- Paper:Saturated kraft and glassine stocks anchor label stock and tape backing applications where dimensional stability requirements remain less stringent than film alternatives.
Most installed capacity flows through Adhesive Films. Expansion is steepest in Foam Materials.
Application:
End-use specifications determine substrate selection through performance thresholds rather than cost minimization alone.
- Automotive Interiors:Multi-layer laminates combining foam, fabric, and film substrates must survive climate cycling validation from -40°C to 85°C without delamination. NHTSA flammability standards and OEM lightweighting mandates compress thickness tolerances while expanding thermal management requirements.
- Electronics:Flexible circuit board manufacturers specify ultra-thin polyimide backings for 5G antenna modules and foldable display bonding, displacing traditional PET films where high-frequency signal integrity matters.
- Medical Devices:ISO 10993 biocompatibility certification timelines extend 18-24 months for antimicrobial non-woven substrates targeting advanced wound care.
- Construction:Carpet tile manufacturers and waterproofing membrane producers specify heavy-gauge woven or non-woven backings for dimensional stability under mechanical stress.
Volume concentrates in Automotive Interiors. Value capture is expanding most quickly in Electronics.
End User:
Channel structure shapes specification control and pricing leverage across the value chain.
- Manufacturers:Automotive tier suppliers and electronics OEMs dominate procurement through platform-level supply agreements that consolidate adhesive purchases across multiple interior modules rather than component-specific contracts.
- Distributors:Industrial tape converters and medical product assemblers maintain inventory positions across multiple substrate technologies to serve fragmented downstream demand.
- Retailers:Consumer-grade adhesive and mounting product sellers represent lower-specification volume with minimal technical service requirements.
- Service Providers:Installation contractors and maintenance operations purchase backing materials through project-based procurement with irregular volume patterns.
Procurement authority is concentrating in Manufacturers. Distributors retain relevance where technical matching services justify margin capture.
Technology:
Process capabilities determine which suppliers qualify for precision-grade specifications versus commodity volume positions.
- Coating:Slot-die and micro-gravure operations apply functional layers with sub-micron uniformity for electronics and medical-grade adhesives. Technician scarcity in rheology and web-handling expertise constrains qualified capacity expansion.
- Laminating:Multi-substrate bonding combines divergent thermal expansion coefficients into unified assemblies, generating failure modes during climate validation that extend development cycles.
- Layering:Sequential substrate stacking builds composite structures for automotive NVH and protective packaging without full surface adhesion between plies.
- Printing:Surface patterning and identification marking add functional or decorative elements to backing substrates for track-and-trace and branding requirements.
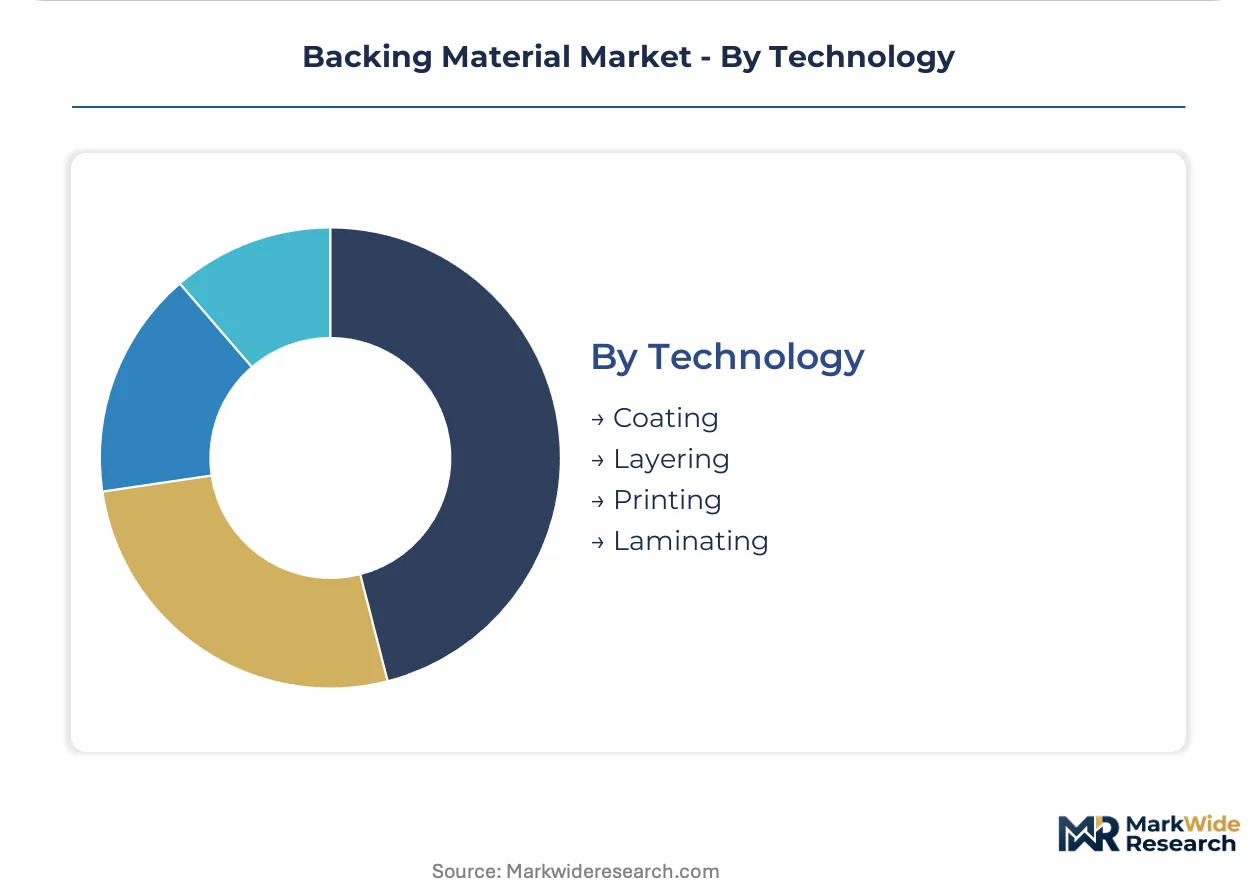
Capability concentration is highest in Coating. Investment flows are shifting toward Laminating as automotive interior complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan command distinctly different positions in backing material demand, with German automotive interiors driving foam laminate specifications while Japanese electronics corridors dictate precision film tolerances for adhesive tape constructions.
United States
Automotive OEMs in Michigan and Ohio specify multi-layer foam laminates for seating and headliner assemblies under NHTSA flammability standards. EPA VOC emission limits from coating operations pressure suppliers toward water-based acrylic systems. Precision coating capacity concentrates in Ohio and Indiana manufacturing belts serving Detroit-area procurement consolidation.
Germany
Volkswagen and BMW procurement teams in Lower Saxony and Bavaria consolidate adhesive purchases across interior modules rather than component-specific contracts. REACH candidate list expansion for persistent organic pollutants accelerates halogenated flame retardant substitution in automotive foams. Freudenberg Performance Materials anchors supply relationships through specialized NVH substrate development in Weinheim.
Japan
METI-enforced JIS C 2107 standards for electronics-grade adhesive tape dimensional stability filter supplier participation toward precision coaters with sub-micron thickness control. Semiconductor packaging and display assembly demand in Osaka and Nagoya corridors requires sub-0.5% elongation variation under humidity cycling. Nitto Denko Corporation maintains qualified vendor status through captive polymer film orientation capabilities.
South Korea
Samsung and LG Display procurement patterns favor precision-coated backing substrates for flexible circuit board and foldable display bonding applications. MFDS medical device regulations extend biocompatibility certification timelines for antimicrobial non-woven substrates targeting wound care exports. Gyeonggi-do manufacturing clusters around Suwon and Yongin host critical slit-and-spool capabilities for electronics-grade adhesive tapes.
India
CDSCO serialization mandates for pharmaceutical track-and-trace labeling expand demand for tamper-evident holographic label stocks with specialized paper and film backings. Domestic converters build coating capacity in Ahmedabad and Hyderabad to serve packaging requirements. Automotive tier suppliers in Pune and Chennai adopt foam laminates for interior assemblies under evolving OEM lightweighting specifications.
Backing Material Market Competitive Landscape
Top-tier vendors anchor premium precision coating segments, while mid-scale specialists occupy regional automotive and medical niches. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive polymer film production, specialized adhesive tape manufacturers with JIS-certified coating lines, and regional foam extruders serving NVH specifications. Archetypes include integrated materials science conglomerates, precision coating specialists, and automotive-focused laminate suppliers. Competitive moves center on platform-level supply agreement consolidation and backward integration into polymer film orientation assets.
Within the integrated materials science tier, 3M and Avery Dennison represent archetypes of coating technology leadership sustained across industrial tape applications. Among European specialists, Tesa SE occupies a position exemplifying automotive interior bonding solutions that anchor regional supply chains. Japanese precision coaters include Nitto Denko Corporation, which sits within the qualified vendor ecosystem serving METI-enforced electronics standards. These three companies illustrate how geographic regulatory alignment shapes competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| 3M |
| Interface, Inc. |
| Mohawk Industries |
| Shaw Industries |
| Avery Dennison |
| Nitto Denko Corporation |
| Tesa SE |
| Intertape Polymer Group |
| Freudenberg Performance Materials |
| Others |
Value Network & Pricing Analysis
Water-based acrylic coating transitions across United States and German manufacturing belts are simultaneously compressing capital requirements for new entrants and redistributing pricing power toward precision coaters with captive polymer film orientation capabilities. This production-method shift tightens margin pools for legacy solvent-recovery operators while expanding premium capture for JIS-certified substrate providers serving Osaka and Nagoya electronics corridors.
Pricing Analysis
Capacity additions in India's pharmaceutical packaging belt are reshaping price floors for tamper-evident holographic label stocks. Contract-based long-term offtake dominates pricing structures, with differentiation hinging on ISO 10993 certification grade and volume scale. Cost compression in standard-grade foam laminates is intensifying because petrochemical feedstock volatility feeds through acrylic and polyethylene formulations. Automotive OEM procurement teams show lowest price sensitivity, while industrial tape converters face acute margin pressure from spot-market resin exposure.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO serialization framework are reshaping sourcing patterns for pharmaceutical-grade paper and film backings. Manufacturing concentrates in Japan, South Korea, and Germany, with precision coating capacity anchored in Osaka-Nagoya and Gyeonggi-do corridors. Supply chains draw from propylene derivatives, ethylene feedstocks, and fluoropolymer release liners. Single-source vulnerability concentrates in qualified fluorinated ethylene propylene film suppliers for medical-grade applications. Distribution runs through platform-level supply agreements consolidating automotive interior procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on water-based formulation transitions that lower compliance costs while opening premium positioning for certified precision coaters.
For Market Incumbents: Deploy backward integration into polymer film orientation assets to defend qualified vendor status against emerging precision coaters from South Korea. Consolidate platform-level supply agreements across multiple automotive interior modules before procurement rationalization accelerates. Threat substitution comes from bio-based foam additive developers capitalizing on REACH halogenated flame retardant restrictions. For New Entrants and Emerging Players: Domestic pharmaceutical converters in Ahmedabad and Hyderabad represent underserved buyers with CDSCO-mandated track-and-trace label demand outpacing local coating capacity. White-space targets include antimicrobial non-woven substrates for advanced wound care and RFID-embedded foam laminates for automotive authentication. Go-to-market leverage rests on ISO 10993 certification partnerships with established testing laboratories. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale precision coating specialists because METI-enforced JIS standards create insurmountable compliance thresholds filtering supplier participation. Long-term viability favors targets with captive slit-and-spool capabilities in electronics manufacturing clusters. Watch for inflection signals in Indian automotive lightweighting mandates redistributing foam laminate specifications toward domestic tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Orientation | Captive supply of sub-micron thickness substrates secures JIS certification for Osaka-Nagoya electronics corridors. |
| Water-Based Coating Line Conversion | EPA-compliant acrylic systems displace solvent-recovery assets in Michigan and Ohio manufacturing belts. |
| Platform-Level Supply Agreement Consolidation | Volkswagen and Ford procurement teams reduce qualified adhesive film vendors across Lower Saxony. |
| ISO 10993 Certification Partnership | Biocompatibility testing alliances accelerate market entry for antimicrobial non-woven wound care substrates. |
| Fluoropolymer Release Liner Qualification | Silicone-free coating capabilities unlock medical and electronics-grade pressure-sensitive adhesive procurement. |
Research Methodology
Direct dialogue with precision coating technicians, automotive tier supplier procurement leads, medical device regulatory affairs managers, and pharmaceutical packaging converters grounded qualitative assessment. Secondary validation drew from EPA enforcement actions, METI JIS standard publications, CDSCO track-and-trace guidelines, and customs trade data for adhesive film imports. Bottom-up capacity modeling triangulated against top-down end-use demand aggregation across automotive, electronics, and medical segments.
Segmentation outputs spanning substrate technology, coating precision tier, application performance threshold, and regional regulatory cluster fed analytical framework construction across the projection horizon. CAGRs derived from iterative convergence between supply-side capacity buildout schedules and demand elasticity parameters calibrated to OEM procurement consolidation patterns. Forecast inputs incorporated water-based formulation adoption curves and biocompatibility certification timeline distributions.
Underlying measurement precision varies by segment; electronics-grade adhesive films with JIS-mandated dimensional stability tolerances carry tighter precision than construction-grade woven backings. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and feedstock price volatility patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Regenerative Thermal Oxidizer Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Defatting Systems Market