
 Ferric Chloride As Etchant Market | 2026-2036
Ferric Chloride As Etchant Market Size, Share, and Industry Trends Forecast 2026-2036
Ferric Chloride As Etchant Market Analysis
REACH is restructuring the cost-of-entry calculus for ferric chloride etchant suppliers seeking European market access. BASF leverages its integrated chlorine chemistry platform to control feedstock quality across production stages. PVS Chemicals anchors North American supply through dedicated merchant distribution channels. Kemira differentiates via water treatment co-product synergies that lower unit manufacturing economics.
Ferric chloride as etchant denotes an aqueous or anhydrous iron(III) chloride formulation, typically 38–42% FeCl3 by weight for liquid grades, deployed to selectively dissolve copper layers in subtractive PCB fabrication. The compound operates at controlled temperatures between 40°C and 55°C to achieve precise track widths below 50 micrometers. Liquid formulations dominate volume throughput due to handling efficiency in high-throughput wet bench operations, while semiconductor fabrication applications command premium positioning through ultra-high-purity specifications. Metal etching segments sustain stable replacement demand from decorative and functional steel processors. Electronics companies as end users increasingly specify drum-to-bulk-container transitions to reduce per-unit packaging waste.
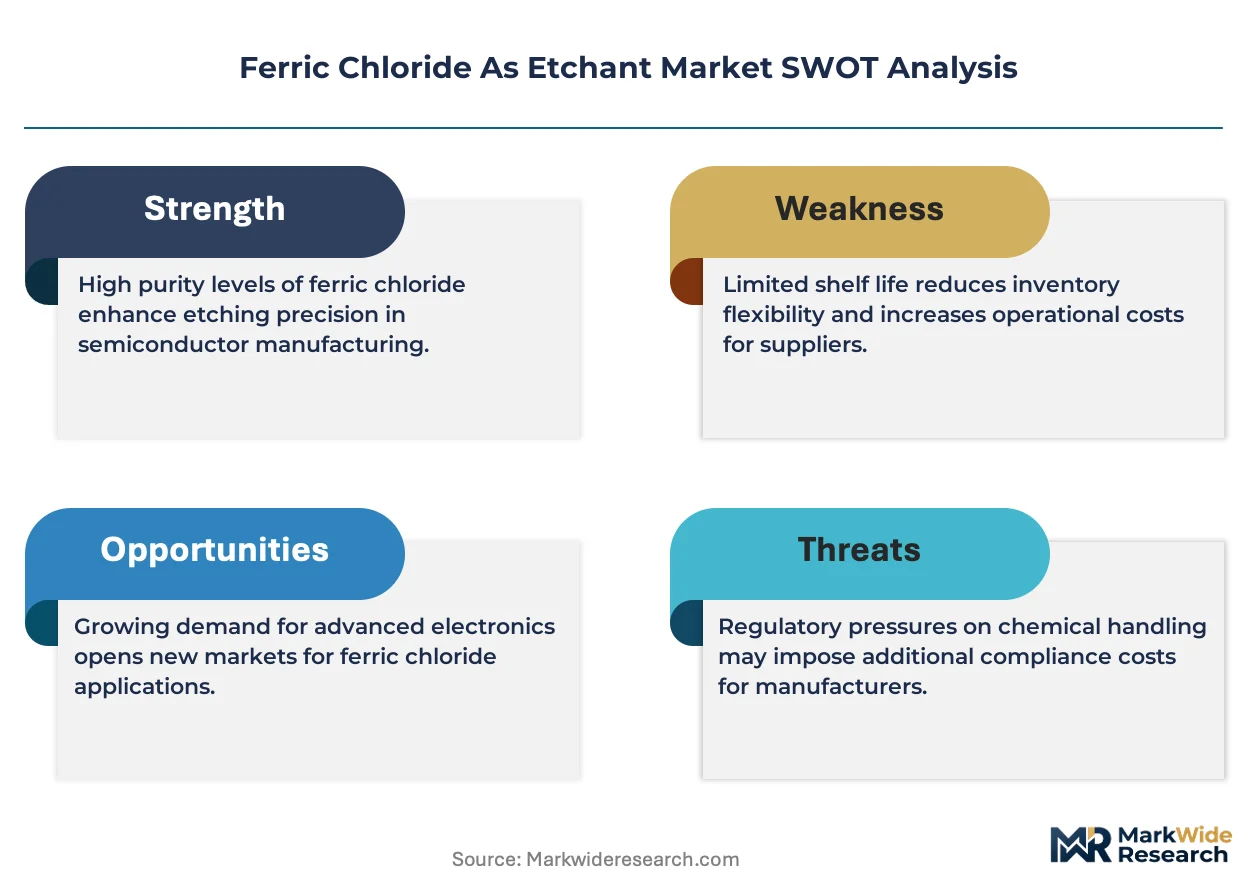
EPA hazardous waste classifications in the United States shape spent etchant recovery economics and cradle-to-grave liability structures. ECHA's harmonized CLP hazard communication mandates in Europe force reformulation investments and extended safety data sheet obligations. China's MEE discharge standards for heavy metal effluents tighten local production compliance thresholds. Stakeholders must monitor regulatory divergence between jurisdictions to optimize manufacturing location and product registration strategies without misallocating capital across incompatible compliance regimes.
Market Dynamics
PCB miniaturization below 50 micrometer track widths is compressing etchant specification windows, forcing reformulation investments and tightening supplier qualification protocols across wet-bench operations.
Growth Catalysts
- REACH chemical registration:European compliance mandates are filtering out marginal suppliers and consolidating viable production capacity among registrants with full dossier submissions.
- Guangdong electronics clusters:Contract manufacturing concentration in China's southern province sustains drum-to-bulk-container transitions that reduce packaging waste per unit processed.
- Subtractive copper etching:The 38–42% FeCl3 liquid grade maintains cost efficiency against plasma alternatives for high-volume multilayer board fabrication.
Market Restraints
- Chlorine feedstock volatility:Integrated chlorine chemistry platforms insulate major producers from merchant caustic-chlorine price swings that squeeze non-integrated formulators.
- Spent etchant recovery economics:EPA hazardous waste classifications in the United States impose cradle-to-grave liability structures that elevate end-of-life handling costs.
- Copper salt precipitation limits:Dissolved copper accumulation above 150 grams per liter degrades etch rate consistency and forces bath replacement cycles.
Strategic Opportunities
- Ultra-high-purity semiconductor grades:Wafer-level packaging applications command specification premiums above standard PCB formulations.
- Water treatment co-product synergies:Ferric chloride producers with adjacent municipal chemical portfolios can arbitrage manufacturing economics across product lines.
- India's electronics manufacturing incentives:PLI scheme subsidies for semiconductor and PCB fabrication are attracting etchant supplier qualification programs.
Industry Challenges
- Wet chemistry process engineering talent:Experienced technicians capable of optimizing etch factor and undercut ratios remain scarce in emerging manufacturing locations.
- Legacy bath monitoring integration:Automated specific gravity and redox potential sensors must interface with decades-old wet bench infrastructure without disrupting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferric Chloride As Etchant Market |
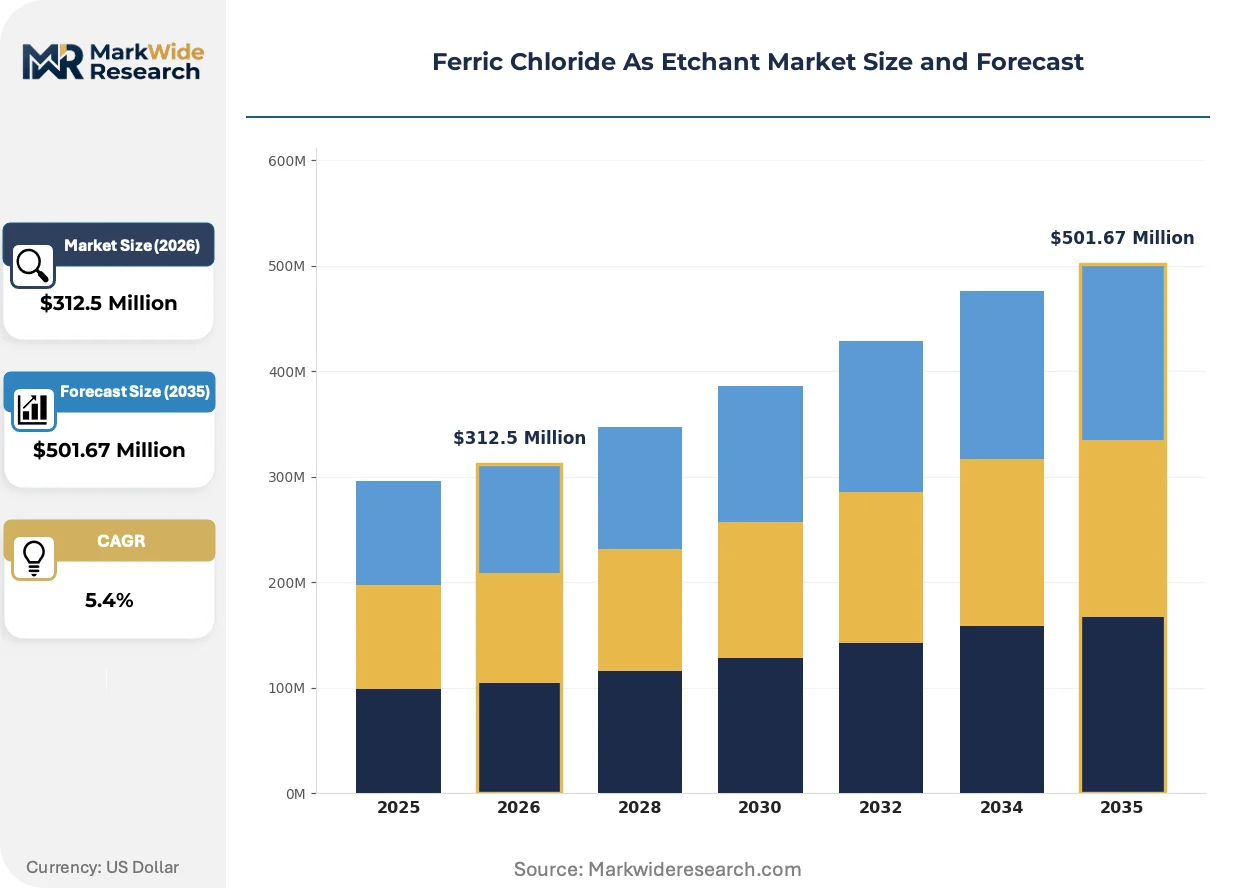
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Paste, Granules Application: Circuit Board Manufacturing, Metal Etching, Photolithography, Semiconductor Fabrication End User: Manufacturers, Laboratories, Research Institutions, Electronics Companies Packaging Type: Bottles, Drums, Bags, Bulk Containers |
| Companies Covered | BASF, PVS Chemicals, Tessenderlo Group, Kemira, Feralco, Akzo Nobel, BPS Products, Asia Chemicals, National Biochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferric Chloride As Etchant Market Emerging Trajectories
Etchant formulation science is converging with closed-loop recovery systems and digital process control, compressing the traditional separation between chemical supply and waste management services.
Regenerative acid recovery technology is unifying spent etchant processing with virgin ferric chloride production. Major PCB fabricators in Taiwan and South Korea are adopting membrane electrolysis units that regenerate etching capacity on-site. This convergence is unifying chemical supplier and equipment vendor relationships into single-source accountability structures.
ECHA's harmonized CLP hazard communication mandates are forcing extended safety data sheet obligations and multilingual labeling investments. Formulators serving pan-European distribution must now maintain 24-language documentation sets. Small-batch decorative metal etching shops in Italy and Spain are consolidating purchases through distributor intermediaries to outsource compliance burden.
Electronics companies are consolidating drum purchases into bulk tanker deliveries with vendor-managed inventory terms. Tier-one PCB manufacturers in China's Jiangsu province now specify supplier-owned storage tanks with telemetry-linked replenishment. This procurement compression is most visible among high-volume consumer electronics contract manufacturers seeking to eliminate packaging waste from sustainability scorecards.
Ferric Chloride As Etchant Market Segmentation
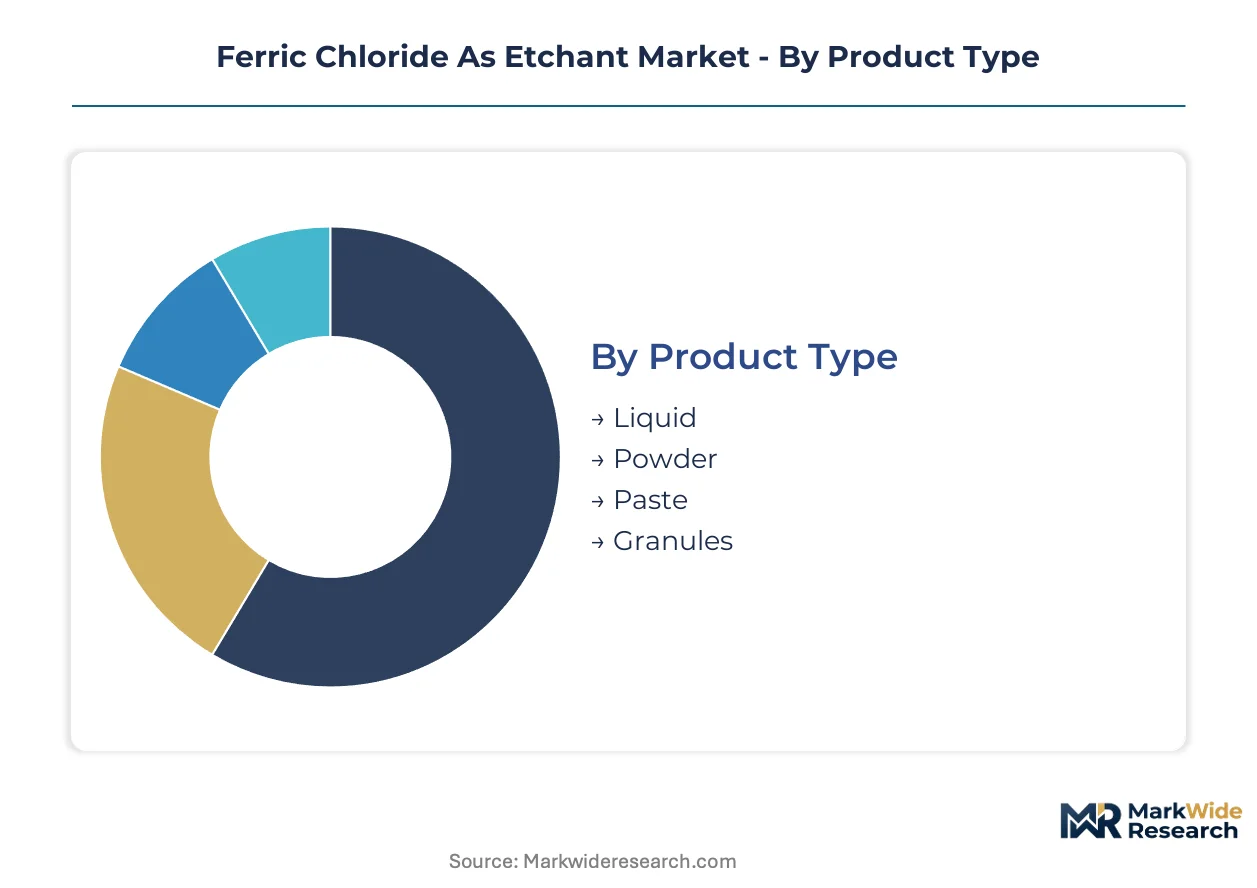
Etchant formulation specifications diverge sharply across end-use applications, with semiconductor fabrication demanding ECHA-registered ultra-high-purity grades while PCB operations prioritize bulk-handling efficiency. Certification burdens and packaging economics create distinct competitive arenas that suppliers must navigate without cross-subsidizing incompatible compliance investments.
Product Type:
REACH dossier completeness requirements split this category between registrants with full toxicological data packages and non-European suppliers limited to non-regulated markets.
- Liquid:38–42% FeCl3 aqueous solutions dominate high-throughput wet bench operations in Guangdong province contract manufacturing clusters. Drum-to-bulk-container transitions accelerate as electronics companies eliminate packaging waste from sustainability scorecards.
- Powder:Anhydrous iron(III) chloride serves remote metal etching operations lacking on-site solution preparation infrastructure. Demand concentrates among decorative steel processors in India's emerging fabrication zones where water treatment co-product synergies remain underdeveloped.
- Paste:Viscous formulations target precision spot-etching applications in artisanal metalworking workshops.
- Granules:Free-flowing solid grades facilitate automated dosing systems in membrane electrolysis regeneration units.
Leading the category by volume: Liquid. Growing fastest: Granules.
Application:
Process temperature windows and copper dissolution rates dictate supplier qualification protocols, with sub-50 micrometer track widths forcing reformulation investments.
- Circuit Board Manufacturing:Subtractive copper etching for multilayer boards sustains the largest absolute demand. Taiwan and South Korea PCB fabricators adopt closed-loop membrane electrolysis to compress chemical supply and waste management services.
- Metal Etching:Decorative and functional steel processing generates stable replacement demand without specification escalation. Italian and Spanish small-batch shops consolidate purchases through distributor intermediaries to outsource ECHA CLP multilingual labeling burdens.
- Photolithography:Precision pattern transfer requires tight particle control and redox potential stability.
- Semiconductor Fabrication:Wafer-level packaging commands premium positioning through ultra-high-purity specifications exceeding standard PCB grades.
Widest margin capture: Semiconductor Fabrication. Steepest volume expansion: Circuit Board Manufacturing.
End User:
Procurement scale and technical staffing depth determine whether buyers qualify direct supplier relationships or rely on distributor intermediaries.
- Manufacturers:High-volume PCB and metal processing operations specify vendor-managed inventory with telemetry-linked replenishment. Jiangsu province tier-one producers now require supplier-owned storage tanks eliminating drum handling entirely.
- Electronics Companies:Consumer electronics contract manufacturers drive sustainability scorecard compliance through packaging waste reduction mandates.
- Laboratories:Analytical and quality control applications demand small-lot flexibility with full documentation.
- Research Institutions:Experimental etching studies prioritize formulation customization over unit economics.
Dominant procurement volume: Manufacturers. Expanding most quickly: Electronics Companies.
Packaging Type:
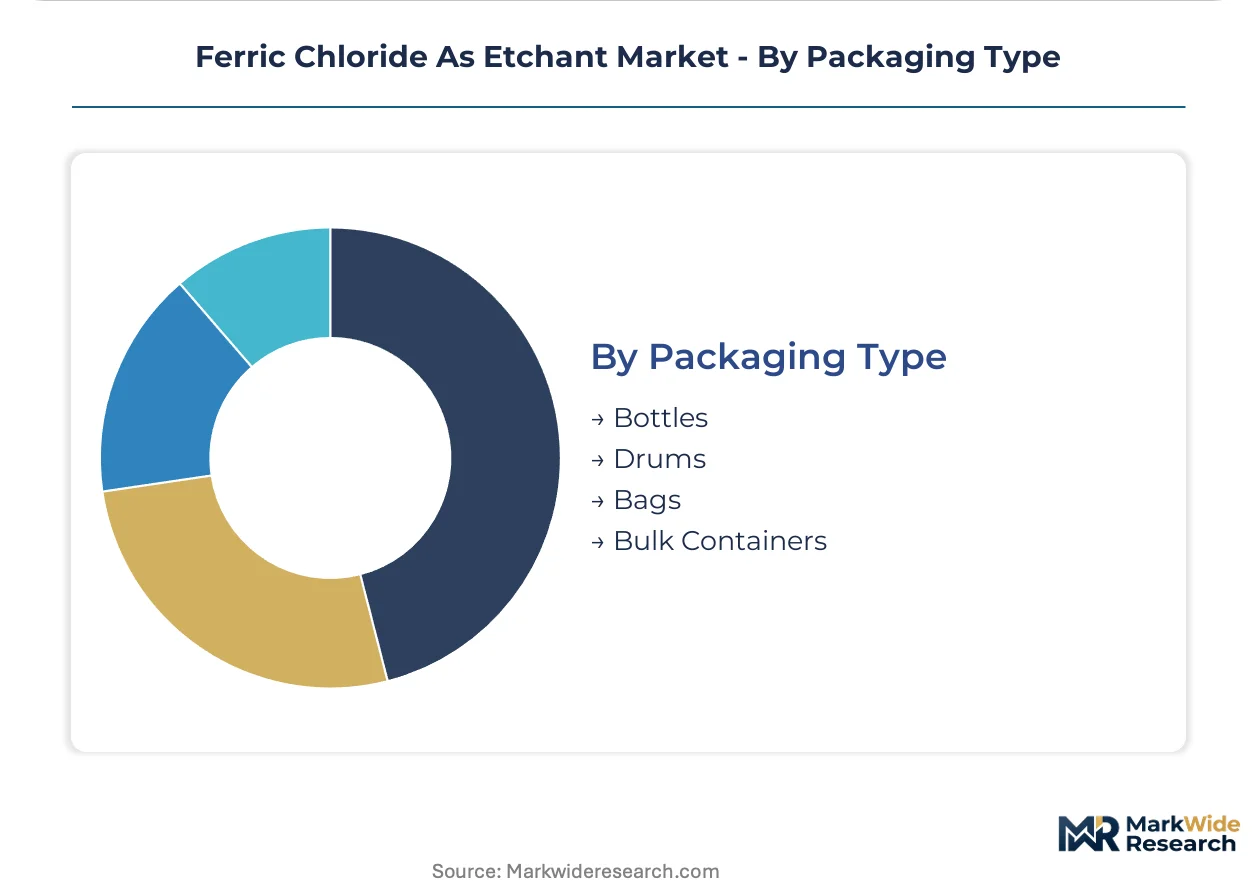
Handling automation compatibility and cradle-to-grave liability exposure shape container selection across EPA-regulated and non-regulated jurisdictions.
- Bulk Containers:Tanker deliveries with telemetry-linked replenishment eliminate per-unit packaging waste. China's MEE discharge standards tighten local production compliance thresholds for spent etchant recovery economics.
- Drums:Intermediate volumes sustain established logistics infrastructure among mid-scale PCB fabricators.
- Bottles:Laboratory-scale applications require chemical-resistant containment with precision dispensing features.
- Bags:Powder and granule formats utilize multi-layer barrier protection against moisture ingress.
Fastest transition trajectory: Bulk Containers. Steady residual demand: Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong's electronics manufacturing special economic zones concentrate ferric chloride etchant demand through dense PCB fabrication clusters serving global consumer electronics brands.
China
Jiangsu province tier-one PCB manufacturers now mandate supplier-owned storage tanks with telemetry-linked replenishment systems. MEE discharge standards for heavy metal effluents tighten compliance thresholds for spent etchant recovery economics. Guangdong's contract manufacturing belt drives drum-to-bulk-container transitions that eliminate packaging waste from sustainability scorecards.
Germany
BASF's integrated chlorine chemistry platform in Ludwigshafen controls feedstock quality across ferric chloride production stages. ECHA's harmonized CLP hazard communication mandates force 24-language safety data sheet maintenance and multilingual labeling investments. Baden-Württemberg's precision engineering fabricators qualify ultra-high-purity etchant grades for automotive electronics.
United States
PVS Chemicals anchors North American supply through dedicated merchant distribution channels spanning the Great Lakes industrial corridor. EPA hazardous waste classifications impose cradle-to-grave liability structures that elevate spent etchant handling costs. Texas and Arizona semiconductor fabrication facilities drive qualification programs for wafer-level packaging specifications.
South Korea
Taiwan and South Korean PCB fabricators adopt membrane electrolysis units that regenerate etching capacity on-site and compress chemical supply with waste management services. METI-aligned industrial standards influence etchant specification protocols across Northeast Asian supply chains. Seoul Capital Area electronics conglomerates consolidate procurement through vendor-managed inventory with telemetry-linked replenishment.
India
PLI scheme subsidies for semiconductor and PCB fabrication attract etchant supplier qualification programs in Karnataka and Tamil Nadu. BIS certification requirements structure import substitution incentives for domestic ferric chloride formulation. Gujarat's emerging chemical processing zones develop water treatment co-product synergies that lower unit manufacturing economics.
Ferric Chloride As Etchant Market Vendor Landscape
European producers anchor one tier through integrated chlorine chemistry platforms; North American specialists hold distribution infrastructure advantages. The vendor base separates between registrants with full REACH dossier submissions and suppliers limited to non-regulated markets. Three archetypes dominate: integrated chemical conglomerates with captive feedstock, regional distributors with logistics density, and water treatment specialists with co-product arbitrage. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Among integrated chemical conglomerates, BASF and Kemira exemplify archetypes leveraging adjacent industrial portfolios. BASF occupies a position representing European registrants with full toxicological data packages. Kemira sits within the water treatment co-product tier, exemplifying manufacturing economics arbitrage across municipal chemical lines. PVS Chemicals anchors North American merchant distribution infrastructure. These three represent the structural positioning visible across the competitive set.
| Leading Market Players |
|---|
| BASF |
| PVS Chemicals |
| Tessenderlo Group |
| Kemira |
| Feralco |
| Akzo Nobel |
| BPS Products |
| Asia Chemicals |
| National Biochemical |
| Others |
Supply Flow & Price Mechanics
Chlorine feedstock costs transmit directly from Ludwigshafen and Rotterdam chemical complexes through merchant caustic-chlorine markets into etchant formulation pricing tiers. Integrated producers with captive chlorine supply command margin insulation that non-integrated formulators cannot replicate when spot chlorine prices spike.
Pricing Analysis
Short-lead-time premiums attach to ultra-high-purity semiconductor grades qualifying wafer-level packaging specifications. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered dossier holders from limited-market suppliers. Cost compression in standard PCB grades intensifies as membrane electrolysis regeneration reduces virgin chemical offtake. Contract manufacturers in Guangdong province exhibit highest price sensitivity; semiconductor fabs in Texas and Arizona show least.
Supply Chain Analysis
Single-source vulnerability sits with merchant chlorine supply from Ludwigshafen and Rotterdam chemical complexes. Ferric chloride production draws from iron ore processing, chlorine gas, and hydrochloric acid inputs. Tariff exposure on chlorine derivatives threatens European formulators serving Asian PCB clusters. Distribution runs through dedicated merchant channels anchored by PVS Chemicals across the Great Lakes corridor and BASF's pan-European logistics network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated chlorine chemistry capacity constitutes the binding constraint propping etchant pricing power. REACH dossier completeness requirements filter marginal suppliers, consolidating viable production among registrants with full toxicological submissions.
For Market Incumbents: Acquire membrane electrolysis regeneration technology to compress chemical supply and waste management services into single-source accountability. Add merchant distribution density in India's PLI-subsidized Karnataka and Tamil Nadu corridors. Defend against closed-loop regeneration substitution by embedding telemetry-linked replenishment systems at Jiangsu province tier-one manufacturers. For New Entrants and Emerging Players: Small-batch decorative metal etching shops in Italy and Spain present underserved buyer archetypes seeking ECHA CLP compliance outsourcing through distributor intermediaries. India's Gujarat chemical processing zones offer white-space manufacturing locations with emerging water treatment co-product synergies. Qualify BIS certification pathways to capture import substitution incentives before domestic capacity matures. For Investors and Strategic Acquirers: Distressed-cycle entries favor water treatment specialists with ferric chloride co-product arbitrage in European municipal chemical portfolios. Five-to-ten year viability hinges on REACH registration asset value as compliance costs escalate. Monitor membrane electrolysis adoption rates at Taiwan and South Korean PCB fabricators as inflection indicator for virgin etchant demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorine Feedstock | BASF's Ludwigshafen complex demonstrates margin insulation against merchant caustic-chlorine volatility. |
| Membrane Electrolysis Partnership | Taiwan PCB fabricators unify chemical supplier and equipment vendor relationships into single-source structures. |
| REACH Dossier Acquisition | Full toxicological data packages filter marginal suppliers and consolidate viable European production capacity. |
| Telemetry-Linked Inventory Systems | Jiangsu province tier-one manufacturers now mandate supplier-owned storage tanks eliminating drum handling. |
| India PLI Corridor Qualification | Karnataka and Tamil Nadu semiconductor subsidies attract etchant supplier programs ahead of domestic capacity. |
Methodological Framework
Multi-period observation of etch rate consistency thresholds, copper salt precipitation limits, and membrane electrolysis adoption rates anchored the trend analysis, supplemented by interviews with PCB plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic sector reports, SEC 10-K filings, and ECHA registration databases. Bottom-up formulation demand modeling triangulated against top-down PCB production capacity estimates.
Segment-weighting across grade tier, end-use industry, packaging format, and regional production hub structured the analytical framework. CAGRs derived from regression against semiconductor wafer starts and multilayer board fabrication indices throughout the forecast period. Industry-specific inputs included REACH registration status by supplier, MEE discharge standard compliance costs, and membrane electrolysis unit deployment rates.
Revisions become necessary when chlorine feedstock price volatility exceeds historical bands, membrane electrolysis adoption accelerates beyond replacement thresholds, or REACH dossier completeness requirements expand. Deviation in spent etchant recovery economics under EPA hazardous waste classifications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Oilfield Scale Inhibitors Market