
 Gypsum Market | 2026-2036
Gypsum Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum Market Outlook
The gap between synthetic and natural gypsum processing costs is narrowing as flue-gas desulfurization capture technologies mature and scale. Knauf leverages captive synthetic gypsum supplies from European power plant partnerships to stabilize raw material costs across its board operations. Saint-Gobain anchors its competitive position through deep vertical integration into plaster formulation and specialty additives for moisture-resistant applications. Georgia-Pacific Gypsum LLC dominates the southeastern United States through concentrated manufacturing scale and direct distribution to national homebuilder accounts.
Gypsum is a soft sulfate mineral composed of calcium sulfate dihydrate (CaSO₄·2H₂O), mined from sedimentary deposits or produced synthetically from industrial flue-gas desulfurization, then calcined to form hemihydrate plaster or pressed into paper-faced boards for interior wall and ceiling systems. Gypsum board occupies the largest value share of product type segments, reflecting its indispensability in residential and commercial fire-rated assemblies, though gypsum plaster is gaining traction in renovation markets seeking smoother finish surfaces. Construction applications command the dominant application position, while agricultural soil amendment represents a structurally smaller but stable demand channel tied to sod farm and almond orchard calcium supplementation programs.
EPA coal combustion residual rules and REACH chemical registration requirements in Europe are elevating compliance costs for synthetic gypsum sourcing and traceability. China's MEE enforces stricter sulfur dioxide emission caps that simultaneously constrain natural gypsum mining permits and expand synthetic gypsum feedstock availability from power sector scrubbers. India's BIS certification mandates for gypsum board dimensional stability and fire resistance are tightening market access for uncertified imports. Stakeholders must monitor how building code harmonization across state and national jurisdictions reshapes product specification requirements and manufacturing location decisions.
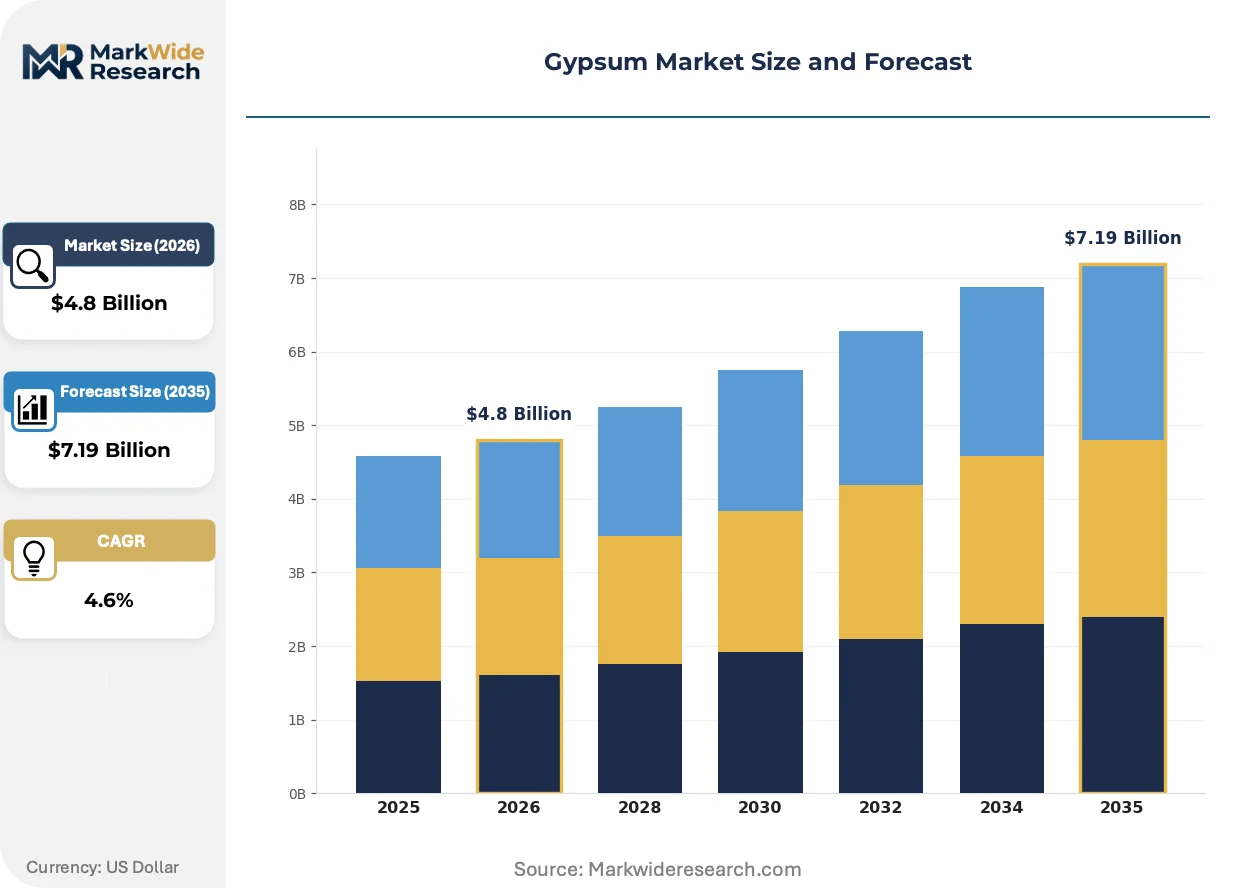
Market Dynamics
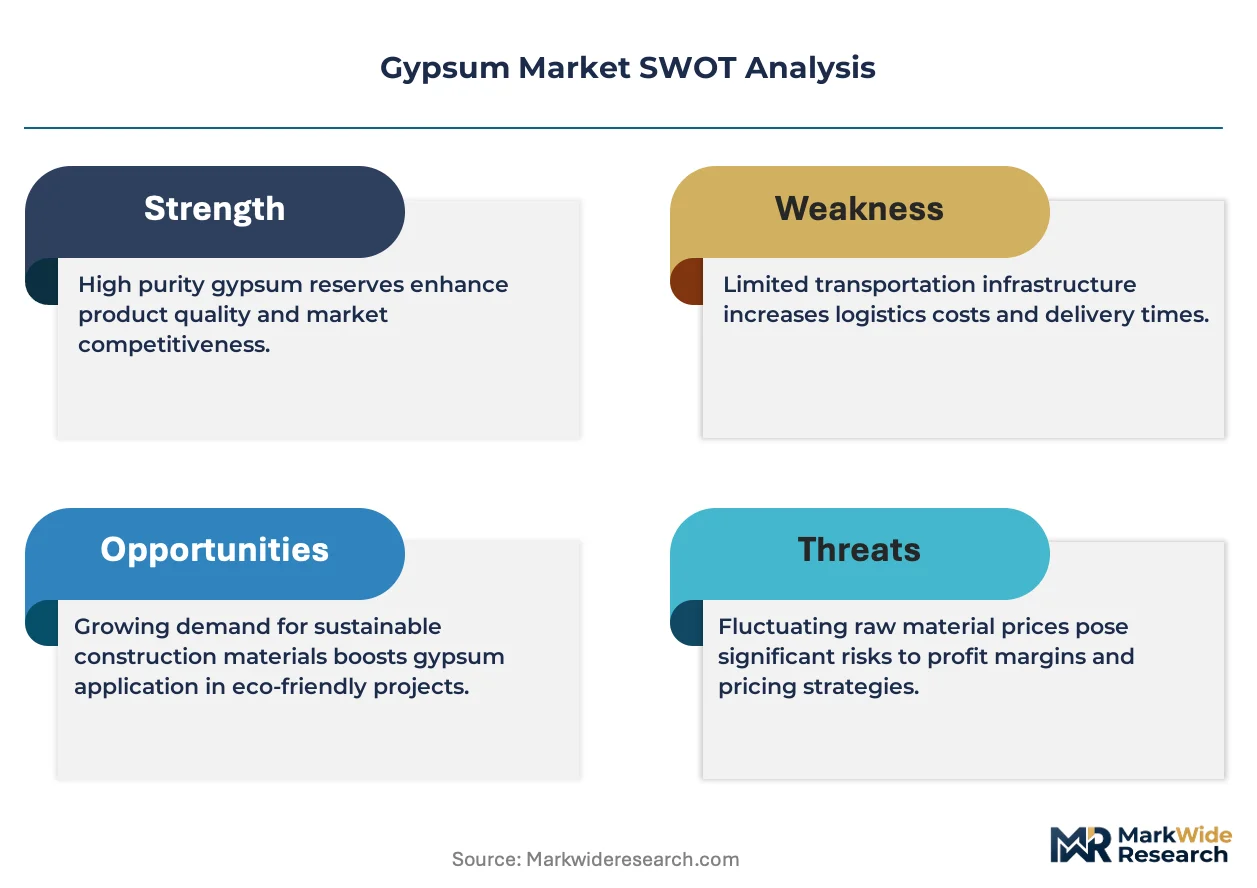
Flue-gas desulfurization capture maturation is compressing synthetic gypsum production costs and eroding the historical cost advantage of natural gypsum mining, forcing capital reallocation toward scrubber-linked manufacturing clusters.
Growth Catalysts
- Building energy codes:China's dual carbon goals and tightening MEE sulfur dioxide emission caps are expanding synthetic gypsum feedstock availability from power sector scrubbers while constraining natural mining permits.
- Fire-rated assemblies:Residential construction activity in the United States is accelerating gypsum board consumption as builders prioritize fire-resistant interior wall systems in multi-family housing.
- Urban housing programs:India's commercial infrastructure expansion and urban housing initiatives are pulling imports and spurring domestic capacity additions across the subcontinent.
Market Restraints
- Compliance cost escalation:EPA coal combustion residual rules and REACH chemical registration requirements in Europe are elevating traceability and sourcing costs for synthetic gypsum processors.
- Input volatility:Natural gypsum extraction faces tightening environmental permits and rising overburden removal costs in sedimentary deposit regions.
- Substitute materials:Magnesium oxide board and cement-bonded particleboard are capturing specification share in moisture-critical applications where gypsum underperforms.
Strategic Opportunities
- Agricultural amendment:Calcium supplementation programs for almond orchards and sod farms represent structurally stable demand channels with premium pricing potential.
- Renovation finish surfaces:Gypsum plaster is gaining traction in European and North American renovation markets seeking smoother aesthetic finishes than board systems provide.
- Recovery technology partnerships:Power plant scrubber operators are forming captive supply agreements with board manufacturers to secure long-term offtake volumes.
Industry Challenges
- BIS certification timelines:India's dimensional stability and fire resistance mandates for gypsum board are tightening market access and extending product approval cycles for uncertified imports.
- Retrofit integration:Moisture-resistant specialty additives require reformulation compatibility with legacy plaster systems, complicating renovation project specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gypsum Board, Gypsum Powder, Gypsum Plaster, Gypsum Blocks Application: Construction, Agriculture, Pharmaceuticals, Industrial End User: Contractors, Farmers, Manufacturers, Builders Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Knauf, Saint-Gobain, Georgia-Pacific Gypsum LLC, National Gypsum Company, Etex Group, Beijing New Building Material, Yoshino Gypsum Co., Ltd., USG Corporation, Holcim Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum Market Strategic Shifts
Process instrumentation and quality control systems are digitizing gypsum calcination and board formation, compressing yield variance and enabling real-time moisture management across continuous production lines.
Sensor-embedded drying kilns are digitizing heat distribution optimization, allowing manufacturers to reduce energy intensity per board unit. Large-scale producers in Germany and the United States are deploying these systems fastest. The technology is digitizing quality assurance workflows and reducing manual inspection headcount.
REACH chemical registration requirements and EPA coal combustion residual rules are elevating documentation burdens for synthetic gypsum traceability. Compliance costs are redirecting procurement toward vertically integrated suppliers with captive scrubber partnerships. European board manufacturers face the steepest compliance gradients and are consolidating supplier panels.
Direct distribution to national homebuilder accounts is compressing regional distributor margins and reshaping channel economics. Southeastern United States markets exhibit this pattern most acutely, where concentrated manufacturing scale enables factory-to-site logistics. Specification decisions are migrating from distributor salesforces to corporate procurement functions.
Gypsum Market Segmentation
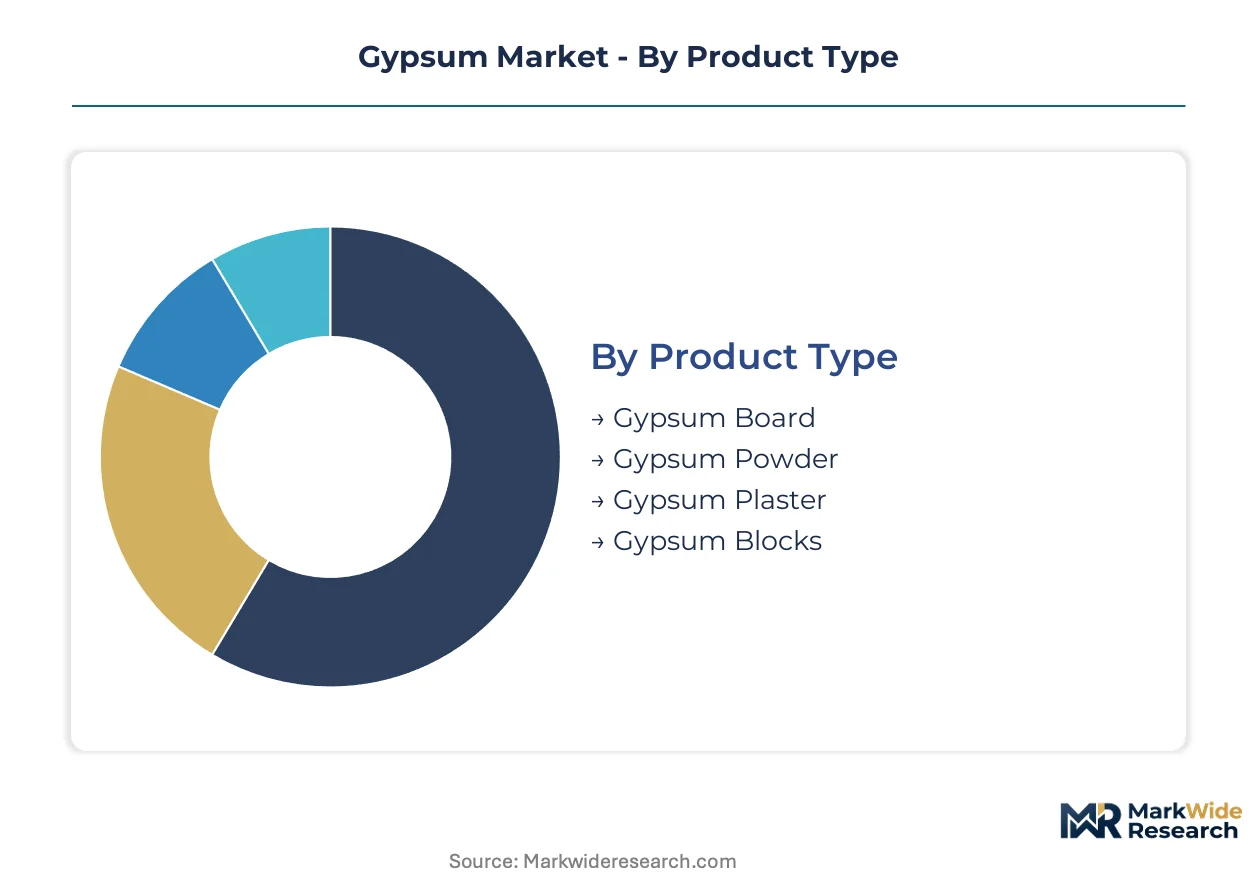
Gypsum market segmentation reveals how product form, application intensity, and channel economics create distinct profit pools. Understanding these divides helps stakeholders align manufacturing scale with specification requirements and route-to-market investments.
Product Type:
Use-case spectrum spans fire-rated wall assemblies to agricultural soil conditioning, with form factor determining processing intensity and margin capture.
- Gypsum Board:Paper-faced calcium sulfate panels dominate residential and commercial fire-rated interior wall systems. Demand concentrates in United States multi-family housing construction, where builders prioritize code-compliant fire resistance ratings.
- Gypsum Plaster:Calcined hemihydrate formulations deliver smoother finish surfaces than board alternatives. European and North American renovation markets are pulling specification share for aesthetic refinement in heritage building restoration.
- Gypsum Powder:Unprocessed or lightly calcined material serves as feedstock for industrial plaster production and specialized cement additives.
- Gypsum Blocks:Solid pre-cast units provide non-load-bearing partition walls with inherent fire resistance and acoustic dampening properties.
The dominant share belongs to Gypsum Board, while Gypsum Plaster is closing the gap fastest.
Application:
Volume concentration tracks construction cycle intensity, with secondary channels offering pricing power through specialized formulation requirements.
- Construction:Interior wall, ceiling, and partition systems consume the majority of processed gypsum output. China's urban housing programs and India's commercial infrastructure expansion are pulling capacity additions across Asia.
- Agriculture:Calcium supplementation for almond orchards and sod farms addresses sulfur-deficient soils. Premium pricing persists due to performance verification requirements and seasonal application windows.
- Pharmaceuticals:High-purity grades serve as excipients in tablet formulation and dental impression materials.
- Industrial:Cement retardation, water treatment, and glass manufacturing utilize lower-purity synthetic sources.
Construction commands absolute volume leadership, though Agriculture offers the steepest expansion trajectory in value terms.
End User:
Procurement sophistication varies sharply between specification-driven builders and price-sensitive agricultural buyers.
- Contractors:Commercial and residential installation specialists drive gypsum board volume through project-based purchasing. Direct distribution relationships with national homebuilder accounts are compressing traditional distributor margins in the southeastern United States.
- Builders:National production homebuilders consolidate specification authority at corporate procurement functions, bypassing regional salesforces.
- Farmers:Almond growers and sod farm operators purchase agricultural-grade material through cooperative buying arrangements.
- Manufacturers:Industrial processors of plaster, cement, and specialty chemicals source synthetic gypsum under long-term power plant scrubber offtake agreements.
Contractors retain the largest procurement footprint, while Manufacturers are consolidating purchasing fastest through captive supply partnerships.
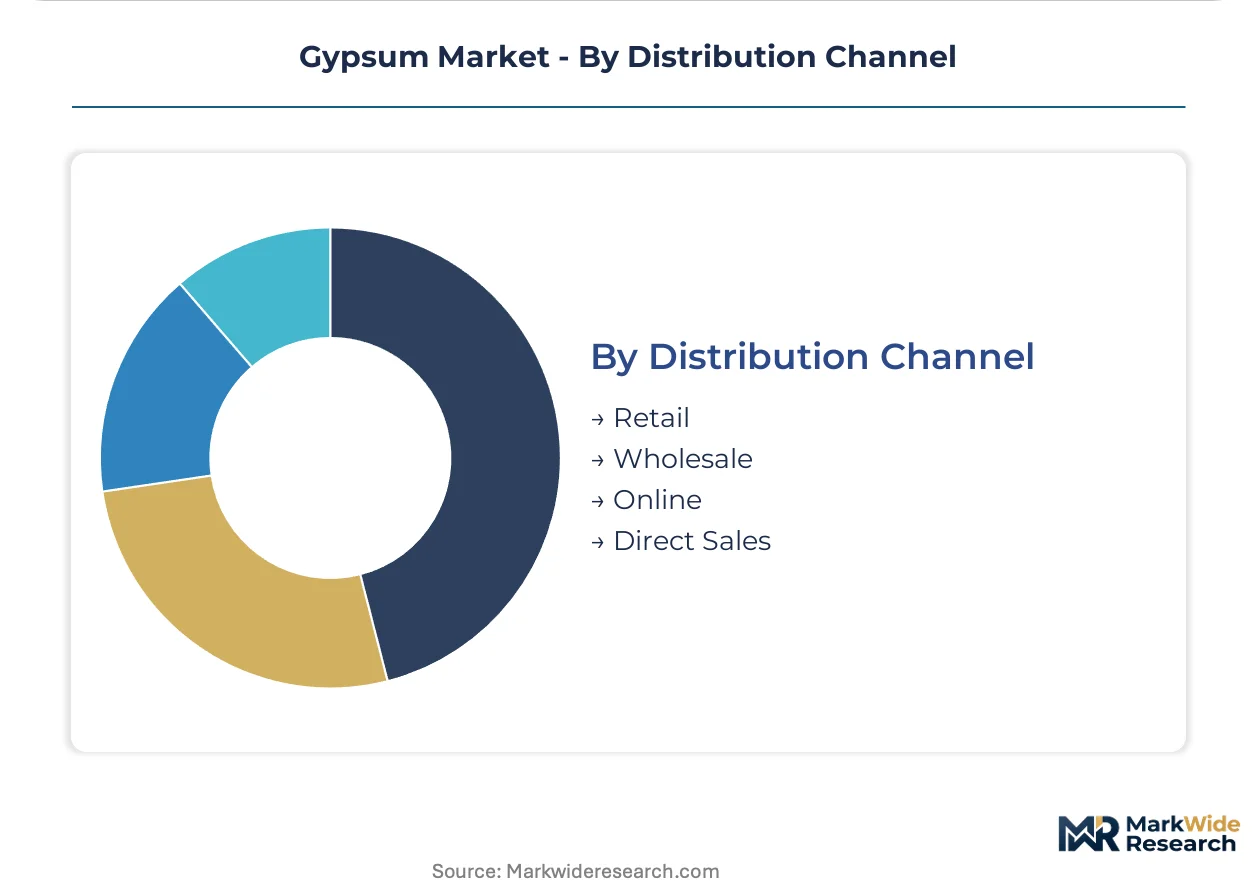
Distribution Channel:
Channel economics reflect shipment density, with direct models gaining ground where manufacturing scale permits factory-to-site logistics.
- Direct Sales:Large board producers bypass distributors to serve national homebuilder accounts with dedicated logistics. Southeastern United States markets exhibit this compression most acutely.
- Wholesale:Regional distributors maintain relevance in fragmented contractor markets and project-based spot purchasing.
- Retail:Big-box home improvement channels serve renovation contractors and DIY consumers with standard board dimensions.
- Online:Digital procurement platforms are emerging for specification-grade plaster and specialty additives in European markets.
Direct Sales captures the dominant value share, while Online channels are expanding most quickly in specialty product niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are shifting as synthetic gypsum availability from power sector scrubbers redraws traditional sourcing patterns. The United States maintains net exporter status in board products while importing specialty plasters. China's synthetic output is displacing seaborne natural gypsum across Southeast Asian construction markets.
United States
Multi-family housing construction and fire-code upgrades in Texas and Florida are accelerating board consumption. EPA coal combustion residual rules elevate traceability costs for synthetic gypsum processors. Manufacturing clusters in the Southeast concentrate factory-to-site distribution networks serving national homebuilder accounts.
China
Urban housing programs in the Yangtze River Delta and Pearl River Delta sustain massive gypsum board demand. MEE sulfur dioxide emission caps simultaneously constrain natural mining permits and expand scrubber-linked synthetic feedstock. Shandong Province hosts the densest concentration of power plant-manufacturer captive supply partnerships.
India
Commercial infrastructure expansion in Maharashtra and Karnataka is pulling imports and spurring domestic capacity additions. BIS certification mandates for dimensional stability and fire resistance tighten market access for uncertified board imports. Gujarat's industrial corridor is attracting greenfield plaster manufacturing investments.
Germany
Renovation markets in North Rhine-Westphalia and Bavaria are pulling gypsum plaster specification for heritage building restoration. REACH chemical registration requirements elevate documentation burdens for synthetic gypsum traceability. The Rhineland's power plant scrubber network anchors captive supply agreements with board manufacturers.
Japan
Seismic retrofit programs in the Kanto region sustain steady board demand for interior wall systems. METI building energy codes tighten fire resistance specifications in multi-story residential construction. Osaka-based manufacturers concentrate moisture-resistant specialty plaster formulation for humid climate applications.
Gypsum Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: multinational integrated producers with captive synthetic feedstock, regional specialists serving renovation and agricultural niches, and power-plant-linked manufacturers securing long-term offtake volumes. Dominant competitive moves include backward integration into scrubber partnerships and direct distribution bypass of traditional wholesale channels.
Within the multinational tier, Knauf and Saint-Gobain exemplify divergent strategic positions—one leveraging European power plant partnerships for feedstock security, the other anchoring competitive position through in-house production of plaster formulation and specialty additives. Georgia-Pacific Gypsum LLC occupies a position as a scale-driven North American producer. Among Asia-Pacific fabricators, Beijing New Building Material and Yoshino Gypsum Co., Ltd. represent regional archetypes with distinct geographic footprints.
| Leading Market Players |
|---|
| Knauf |
| Saint-Gobain |
| Georgia-Pacific Gypsum LLC |
| National Gypsum Company |
| Etex Group |
| Beijing New Building Material |
| Yoshino Gypsum Co., Ltd. |
| USG Corporation |
| Holcim Group |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Shandong Province scrubber-linked manufacturing clusters is compressing supplier margins and forcing price concessions to secure offtake volumes from board producers. Utilization rates below breakeven thresholds are driving consolidation toward vertically integrated power plant partnerships that can cross-subsidize gypsum output.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for synthetic gypsum feedstock. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified board from uncertified imports and agricultural-grade powder. Cost compression in standard-grade board is intensifying because natural mining permits face tightening MEE emission caps. National homebuilders exhibit the lowest price sensitivity due to corporate procurement consolidation, while regional contractors remain most exposed to spot-market volatility.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculus for seaborne natural gypsum shipments. Manufacturing gravity centers on China, the United States, and Germany, with raw material dependencies spanning flue-gas desulfurization output, sedimentary mining concessions, and paper-facing supply. Single-source vulnerability in synthetic feedstock is tethered to coal-power plant scrubber economics. Distribution runs through direct factory-to-site logistics for national homebuilder accounts, bypassing traditional wholesale channels in the southeastern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gypsum board manufacturers are expanding formulation advisory and fire-certification support services that generate recurring revenue independent of commodity board sales. This service-attach layer is accelerating faster than hardware volumes as builders face tightening code compliance requirements.
For Market Incumbents: Pre-empt synthetic gypsum supply consolidation by locking captive scrubber partnerships in Shandong Province and the Rhineland before regional competitors secure exclusivity. Invest in BIS certification infrastructure for Indian market access as uncertified import timelines extend. Channel control through direct distribution relationships with national homebuilders is the critical defensive lever against margin compression.
For New Entrants and Emerging Players: Establish a beachhead in agricultural soil amendment segments where almond orchard calcium supplementation commands premium pricing and faces limited synthetic gypsum competition. Gujarat's industrial corridor offers the most penetrable geography for greenfield plaster manufacturing given infrastructure investment momentum. A go-to-market angle anchored on moisture-resistant specialty additives for humid climate applications bypasses entrenched board competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across scrubber-linked synthetic gypsum processing as FGD capture technologies mature and scale economies emerge. Long-term viability favors producers with backward integration into power sector partnerships rather than pure-play mining operations. Acquisition target archetypes include regional plaster specialists with BIS certification progress and established agricultural distribution. The signal to watch is MEE sulfur dioxide emission cap enforcement velocity, which simultaneously constrains natural mining and expands synthetic feedstock availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrubber Partnerships | Knauf's European power plant alliances stabilize raw material costs against natural gypsum volatility. |
| Direct Distribution Network Expansion | Georgia-Pacific's southeastern factory-to-site logistics compress regional distributor margins and accelerate specification control. |
| Specialty Additive Formulation Investment | Saint-Gobain's in-house plaster chemistry capabilities anchor moisture-resistant product differentiation. |
| BIS Certification Infrastructure Buildout | Uncertified import barriers in Maharashtra and Karnataka create first-mover advantage for compliant domestic capacity. |
| Agricultural Channel Partnership Development | Almond orchard calcium supplementation programs in California and Spain offer premium pricing outside construction cyclicality. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at board manufacturing facilities, procurement leads at national homebuilder accounts, power plant scrubber operators, and agricultural cooperative buying managers. Secondary validation drew from customs and trade data, EPA coal combustion residual filings, BIS certification registries, and MEE emission cap enforcement records. Bottom-up capacity and production estimates were triangulated against top-down construction spending and agricultural acreage data.
Calibration against historical price realizations and capacity utilization rates informed the analytical framework across the analysis window. Segmentation dimensions modeled include product form, application intensity, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from trend extrapolation of construction cycle intensity, synthetic gypsum feedstock availability, and building code harmonization trajectories. Forecast inputs incorporated MEE sulfur dioxide cap enforcement schedules and BIS certification timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, coal-power plant retirement velocity, or agricultural commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding scrubber technology maturation and regulatory enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market