
 Slimicides Market | 2026-2036
Slimicides Market Size, Share, and Industry Trends Forecast 2026-2036
Slimicides Market Analytics
Multi-source procurement for active ingredients is repositioning supply relationships across the slimicides value chain. Lonza Group Ltd leverages its Swiss manufacturing base to sustain long-term contracts with European water treatment operators. BASF SE anchors its position through backward integration into specialty amine intermediates. Albemarle Corporation competes on bromine-derived biocide chemistry, differentiating from chlorine-based alternatives in corrosive environments.
Slimicides are antimicrobial formulations designed to control slime-forming bacteria, fungi, and algae in aqueous industrial systems, typically containing active concentrations of 5-15% biocidal compounds that disrupt microbial cell membranes or enzyme function. Their primary purpose centers on preventing biofilm accumulation that degrades heat transfer efficiency, clogs filtration equipment, and accelerates corrosion in cooling towers, paper machines, and oilfield injection systems. The chlorine-based segment retains volume leadership in municipal water treatment due to low unit cost, while non-chlorine biocides capture expanding share in oilfield applications where corrosion compatibility determines specification. Aqueous formulations dominate industrial channels, though emulsifiable concentrates gain traction in agriculture where tank-mix flexibility with fungicides matters.
The EPA regulates slimicide active ingredients under the Federal Insecticide, Fungicide, and Rodenticide Act, requiring re-registration that elevates compliance costs for legacy chemistries. ECHA administers REACH and the Biocidal Products Regulation in Europe, forcing reformulation away from certain isothiazolinones and driving substitution toward peracetic acid and glutaraldehyde alternatives. China's MEE enforces stricter effluent discharge limits on paper mills, tightening permissible residual biocide concentrations in wastewater streams. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and anticipate which active chemistries will retain multi-region market access.
Market Dynamics
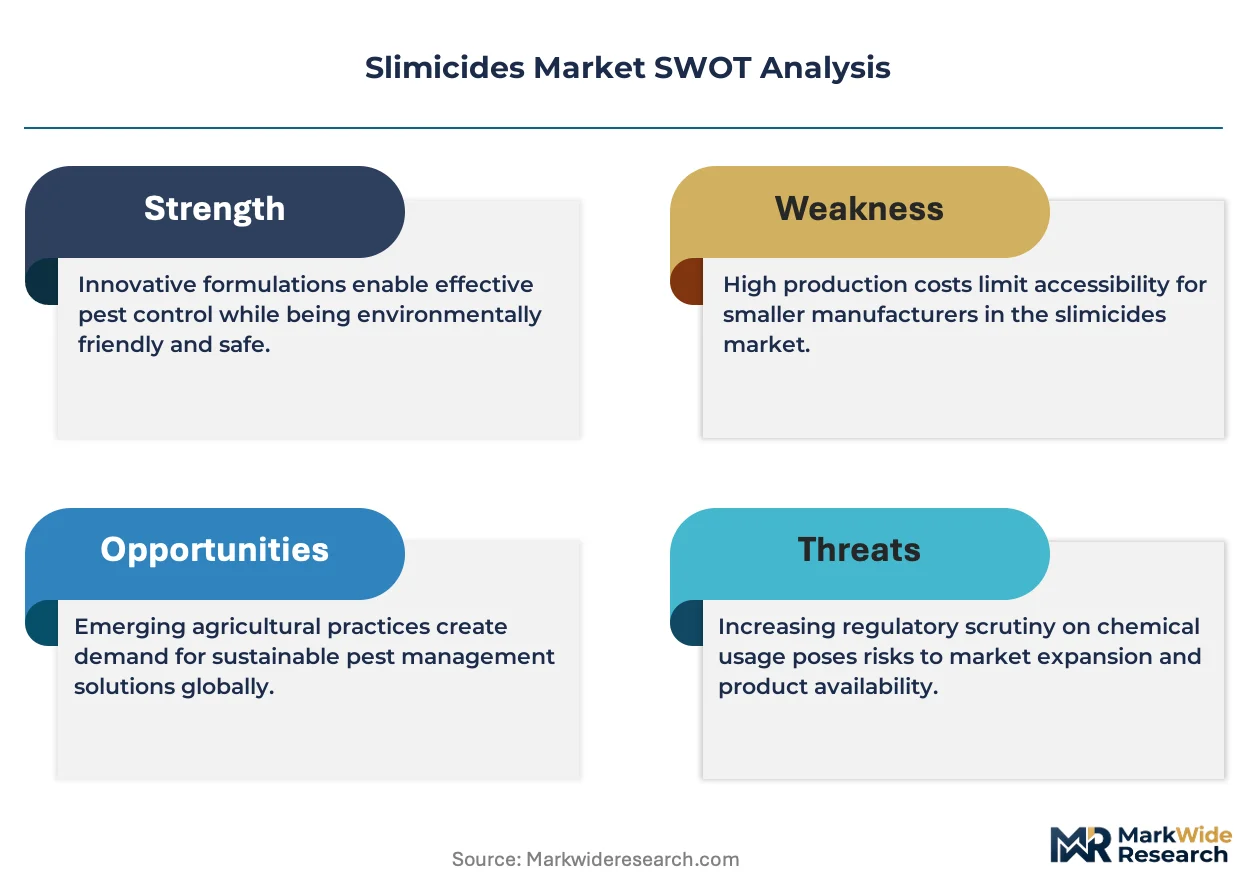
Regulatory divergence between jurisdictions is fragmenting product portfolios and forcing manufacturers to maintain parallel formulation lines for EU Biocidal Products Regulation compliance versus EPA FIFRA registration pathways.
Growth Catalysts
- EU Biocidal Products Regulation:Re-registration deadlines for legacy isothiazolinones are accelerating replacement demand for peracetic acid and glutaraldehyde alternatives across German and French pulp mills.
- Cooling tower efficiency mandates:Heat transfer degradation from biofilm accumulation drives specification of non-chlorine biocides in Middle Eastern desalination facilities where corrosion compatibility determines chemistry selection.
- Oilfield injection systems:Sour gas formation pressures in North American shale plays require continuous slimicide dosing to prevent sulfate-reducing bacterial proliferation and associated hydrogen sulfide generation.
Market Restraints
- Bromine supply concentration:Albemarle Corporation's dominance in Dead Sea bromine extraction creates input cost volatility for bromine-derived biocide formulators when geopolitical friction disrupts Israeli-Jordanian production corridors.
- REACH registration costs:ECHA data requirements for new active substance approvals impose seven-figure compliance burdens that exclude mid-tier chemical suppliers from European market participation.
- Chlorine cost advantage:Municipal water treatment operators retain chlorine-based slimicides despite corrosion trade-offs, compressing margin capture for premium non-oxidizing alternatives in price-sensitive procurement cycles.
Strategic Opportunities
- China's MEE effluent limits:Stricter residual biocide discharge standards for Yangtze River basin paper mills create specification windows for rapid-degradation chemistries that minimize wastewater treatment burden.
- Digital dosing integration:IoT-enabled flow-paced injection systems enable remote monitoring and predictive maintenance contracts that transform slimicide supply from commodity chemical to integrated water management service.
- Peracetic acid convergence:Food-grade sanitation requirements in dairy processing equipment overlap with industrial cooling water specifications, allowing dual-use registration strategies that amortize compliance costs across application segments.
Industry Challenges
- Re-registration timeline compression:EPA FIFRA review backlogs extend active ingredient renewal cycles beyond product expiration dates, stranding inventory and forcing emergency bridging formulations.
- Formulation chemist scarcity:Specialized expertise in halogen-stabilized and synergistic biocide blends concentrates at legacy suppliers, constraining new entrant capability development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slimicides Market |
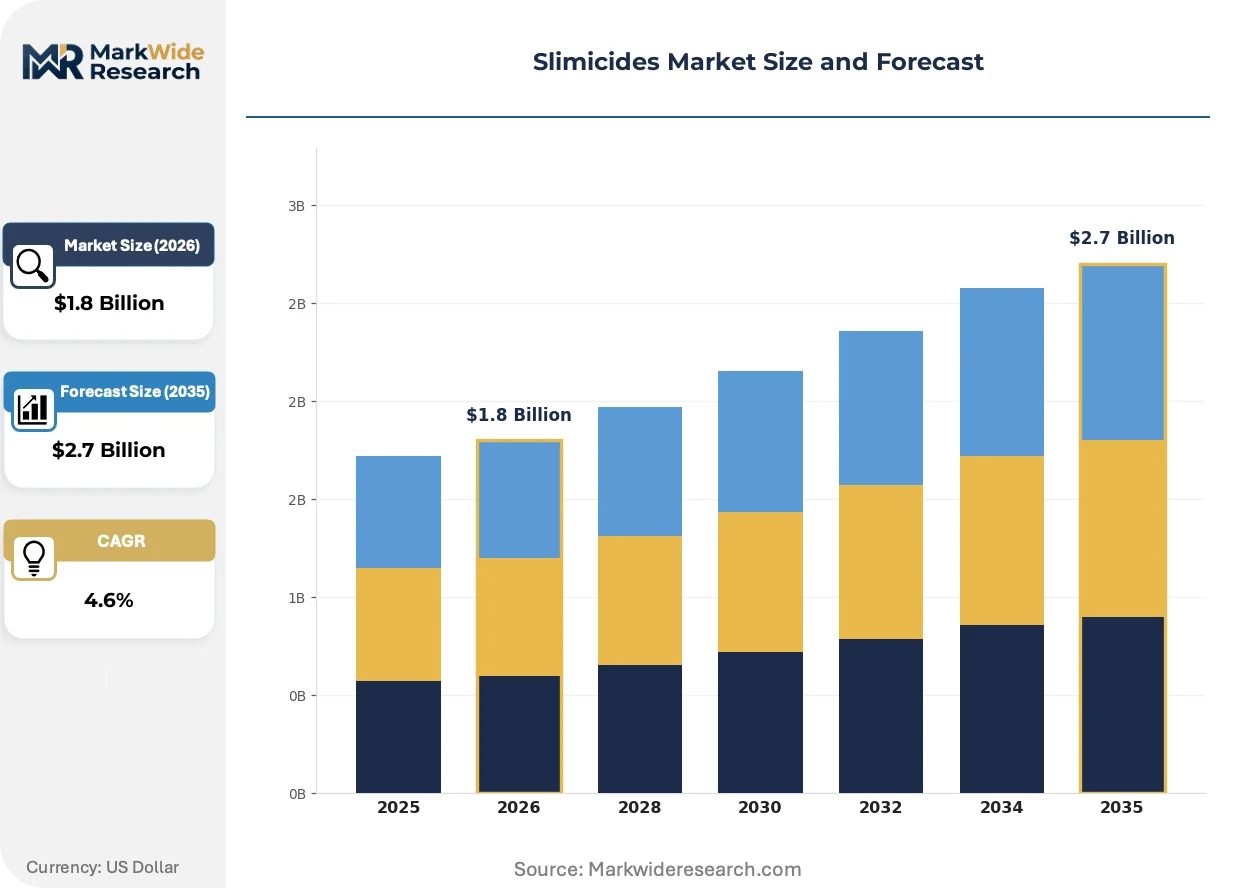
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorine-Based, Non-Chlorine Based, Biocides, Surfactants Application: Water Treatment, Oilfield, Agriculture, Industrial End User: Municipal, Commercial, Residential, Agricultural Formulation: Aqueous, Powder, Emulsifiable Concentrates, Granules |
| Companies Covered | Lonza Group Ltd, LANXESS, BASF SE, The Dow Chemical Company, Albemarle Corporation, Calgon Bio-Organics Pvt. Ltd., Parchem Fine and Specialty Chemicals, Watch Water GmbH, Auchtel Product Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slimicides Market Evolving Landscape
Formulation science is pivoting toward multi-mechanism biocide blends that circumvent single-target resistance development while satisfying divergent regulatory toxicity profiles across export markets.
Peracetic acid-quaternary ammonium hybrid formulations are consolidating technical preference in high-purity water systems where biofilm control must coexist with minimal corrosion contribution. Pharmaceutical-grade manufacturing facilities in Switzerland and Singapore specify these blends for validated clean-in-place protocols. The technology is consolidating supplier relationships around integrated chemical-service providers capable of real-time dosing optimization.
REACH authorization timelines for isothiazolinone derivatives are compressing viable product lifecycles and forcing anticipatory reformulation investments before sunset dates formalize. ECHA's 2024-2027 review queue prioritizes aquatic toxicity endpoints that disadvantage certain methylisothiazolinone concentrations. Paper machine wet-end operators in Nordic countries are responding by qualifying glutaraldehyde-preserved systems that bypass the regulatory uncertainty entirely.
Multi-year chemical management contracts are displacing spot procurement in industrial water treatment channels as facility operators outsource inventory risk and regulatory compliance liability. Third-party water service firms in Texas and Alberta oilfields now bundle slimicide supply with microbiological monitoring and equipment maintenance. This contractual shift concentrates purchasing authority at regional service integrators rather than end-user technical staffs.
Slimicides Market Segmentation
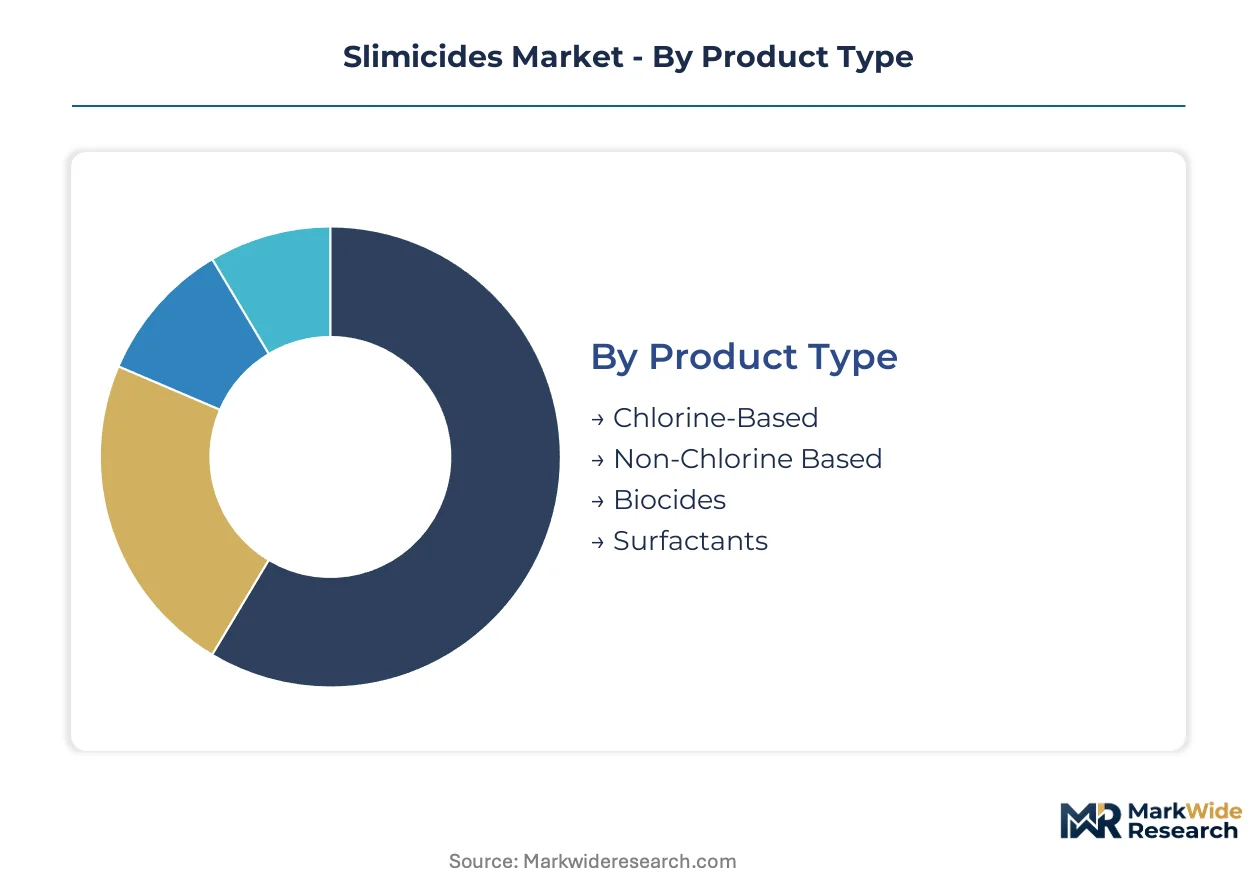
Segmentation in the slimicides market determines which regulatory pathways manufacturers must navigate. Product chemistry dictates EPA FIFRA versus EU BPR registration requirements, while application context shapes corrosion compatibility specifications and dosing protocol complexity.
Product Type:
Chlorine-based formulations carry lighter initial registration burdens under EPA FIFRA but face escalating effluent scrutiny from China's MEE. Non-oxidizing alternatives require more extensive toxicological dossiers for ECHA approval but gain preference in corrosive environments.
- Chlorine-Based:Sodium hypochlorite and chlorine dioxide formulations deliver rapid microbial kill through oxidative cell wall disruption. Municipal water treatment operators in Texas and Florida specify these chemistries for cooling tower biofilm control where procurement prioritizes unit cost over equipment longevity. EPA FIFRA re-registration timelines for legacy chlorinated isocyanurates are compressing viable product lifecycles.
- Non-Chlorine Based:Peracetic acid, glutaraldehyde, and quaternary ammonium compounds operate through non-oxidative protein denaturation and membrane disruption mechanisms. German pulp mills in the Rhine-Ruhr corridor are accelerating qualification of these alternatives ahead of EU BPR sunset dates for isothiazolinone derivatives. ECHA data requirements impose seven-figure compliance costs that favor suppliers with captive toxicology expertise.
- Biocides:Isothiazolinone and bromine-derived actives target specific microbial metabolic pathways with residual efficacy.
- Surfactants:Wetting agents enhance biocide penetration into established biofilm matrices.
Chlorine-Based sits at the top of the volume ranking, with Non-Chlorine Based climbing the fastest.
Application:
Application context determines corrosion compatibility requirements and dosing automation sophistication. Oilfield specifications prioritize sulfate-reducing bacterial control in sour gas formations, while agricultural applications emphasize tank-mix stability with co-applied fungicides.
- Water Treatment:Cooling towers, pulp machine wet-ends, and reverse osmosis systems require continuous or shock-dose slimicide protocols to prevent heat transfer degradation and membrane fouling. Middle Eastern desalination facilities in Saudi Arabia and the UAE specify non-chlorine biocides where salinity accelerates equipment corrosion. Digital dosing integration is transforming supply relationships toward predictive maintenance contracts.
- Oilfield:Produced water injection systems and hydraulic fracturing operations demand slimicides that maintain efficacy under high-pressure, high-temperature reservoir conditions. North American shale plays in the Permian Basin and Bakken Formation require continuous dosing to prevent hydrogen sulfide generation from sulfate-reducing bacterial proliferation. Chemical management contracts bundle supply with microbiological monitoring.
- Agriculture:Irrigation system biofilm prevention and greenhouse water recirculation emphasize rapid biodegradation to minimize crop residue accumulation.
- Industrial:Food processing equipment sanitation and pharmaceutical-grade water systems specify dual-use chemistries that satisfy both industrial and food-grade registration requirements.
Water Treatment commands the largest revenue base, with Oilfield expanding most quickly.
End User:
End-user procurement sophistication ranges from municipal tender processes to agricultural spot purchasing. Contract duration and technical specification authority vary sharply across these customer categories.
- Municipal:City water treatment departments operate under public procurement regulations with extended tender cycles and price-sensitive award criteria. Chlorine-based formulations dominate despite corrosion trade-offs.
- Commercial:Industrial facility operators increasingly outsource water management to third-party service integrators.
- Residential:Swimming pool and spa maintenance represents a fragmented, seasonal demand channel with minimal regulatory complexity.
- Agricultural:Farm operators prioritize tank-mix flexibility and low unit cost over specialized technical support.
Municipal captures the greatest volume concentration, with Commercial gaining share fastest through outsourcing trends.
Formulation:
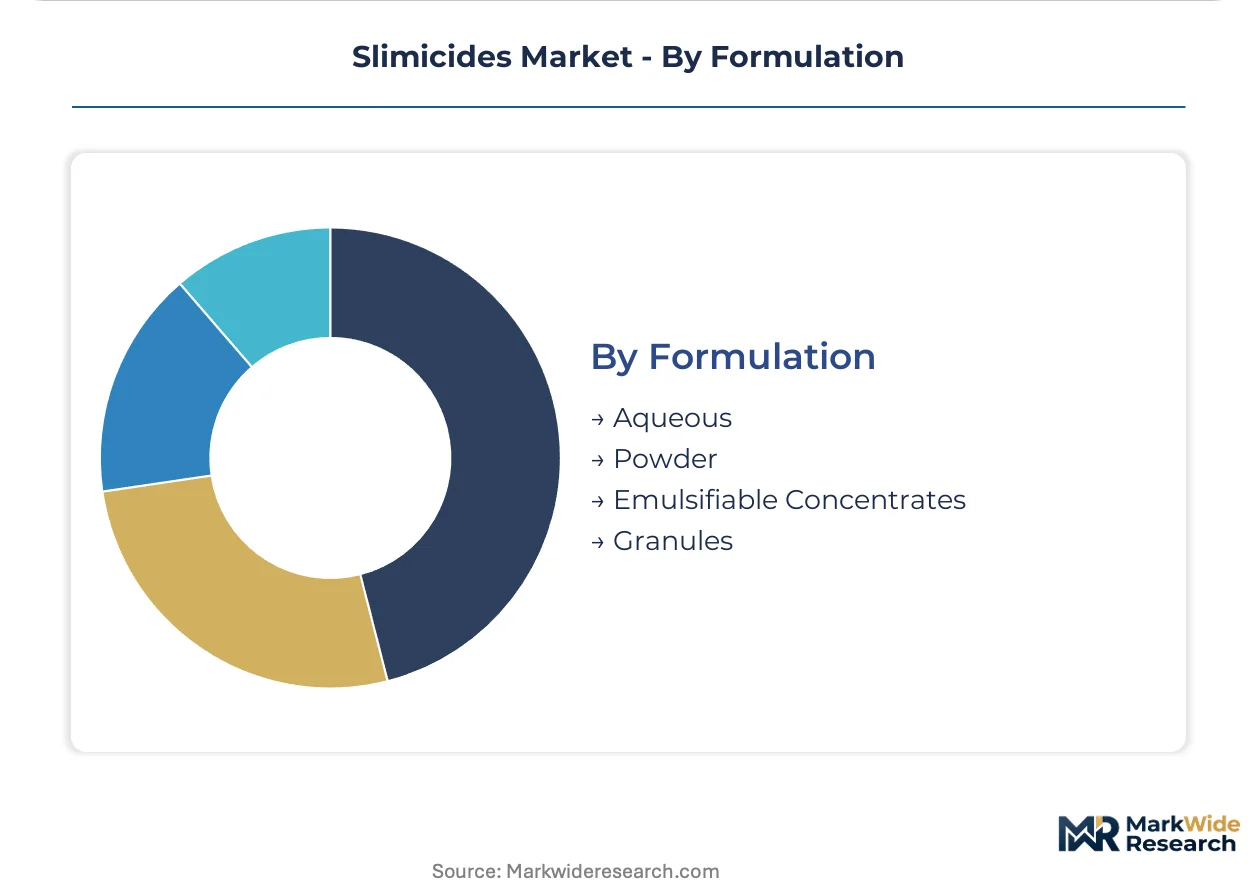
Formulation choice reflects application equipment compatibility and storage stability requirements. Aqueous systems dominate industrial channels, while agriculture favors concentrates that reduce freight cost per active unit.
- Aqueous:Ready-to-use solutions dominate cooling tower and pulp mill applications where automated dosing systems require pumpable, non-viscous feedstocks. Paper machine wet-end operators in Finland and Sweden specify aqueous glutaraldehyde preserved systems to bypass isothiazolinone regulatory uncertainty.
- Powder:Solid chlorine-releasing compounds serve remote agricultural irrigation systems where liquid storage is impractical.
- Emulsifiable Concentrates:Oil-in-water formulations enable tank-mix compatibility with agricultural fungicides and insecticides.
- Granules:Slow-release solid formulations target residential pool maintenance and small-scale agricultural applications.
Aqueous formulations lead by volume, with Emulsifiable Concentrates climbing fastest on agricultural channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pulp and paper mills in the Rhine-Ruhr corridor anchor industrial slimicide consumption, with stringent discharge standards forcing chemistry replacement cycles ahead of EU regulatory deadlines.
United States
Permian Basin oilfield operators demand continuous slimicide dosing to control sulfate-reducing bacteria in sour gas formations. EPA FIFRA re-registration timelines compress viable product lifecycles for legacy chlorinated chemistries. Houston-area chemical service integrators bundle supply with microbiological monitoring under multi-year contracts.
Germany
Rhine-Ruhr pulp mills accelerate qualification of peracetic acid alternatives ahead of EU Biocidal Products Regulation sunset dates for isothiazolinones. ECHA data requirements impose substantial compliance burdens that favor suppliers with captive toxicology expertise. Bavarian pharmaceutical-grade water systems specify dual-use chemistries for validated clean-in-place protocols.
China
Yangtze River basin paper mills face stricter MEE effluent discharge limits on residual biocide concentrations. Rapid-degradation chemistries gain specification windows to minimize wastewater treatment burden. Shandong Province chemical manufacturers expand capacity for glutaraldehyde-based formulations serving domestic industrial channels.
Saudi Arabia
Desalination facilities in Jubail and Yanbu specify non-chlorine biocides where salinity accelerates equipment corrosion. Cooling tower efficiency mandates drive adoption of corrosion-compatible alternatives. Saudi Aramco sour gas operations require continuous microbial control in high-pressure injection systems.
Japan
Kanto region electronics manufacturers specify high-purity water systems with minimal corrosion contribution from biocide residuals. METI industrial efficiency standards penalize heat transfer degradation from biofilm accumulation. Osaka-area chemical formulators develop hybrid peracetic acid-quaternary ammonium blends for validated clean-in-place applications.
Slimicides Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent service integration through digital dosing platforms and predictive maintenance contracts. The vendor base stratifies across Swiss and German chemical conglomerates with backward integration into specialty intermediates, regional water service integrators bundling supply with monitoring, and bromine-focused specialists leveraging captive mineral extraction. Three archetypes dominate: integrated chemical-service providers, captive-intermediate manufacturers, and regional application specialists. Competitive moves concentrate on multi-year chemical management contracts and anticipatory reformulation investments ahead of regulatory sunset dates.
Within the integrated chemical-service tier, Lonza Group Ltd and BASF SE exemplify divergent geographic anchoring strategies. Lonza leverages its Swiss manufacturing base to sustain long-term contracts with European water treatment operators, while BASF anchors position through in-house production of specialty amine intermediates. Albemarle Corporation occupies a distinct position representing bromine-derived biocide chemistry, differentiating from chlorine-based alternatives in corrosive environments. These three entities collectively illustrate how raw material access, regulatory expertise, and service integration determine competitive positioning.
| Leading Market Players |
|---|
| Lonza Group Ltd |
| LANXESS |
| BASF SE |
| The Dow Chemical Company |
| Albemarle Corporation |
| Calgon Bio-Organics Pvt. Ltd. |
| Parchem Fine and Specialty Chemicals |
| Watch Water GmbH |
| Auchtel Product Corp. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap chemical formulators in the Rhine-Ruhr corridor maintain disciplined pricing through long-term tolling arrangements with Swiss and German intermediate producers. This ownership pattern limits price volatility while constraining supply chain flexibility when bromine extraction from the Dead Sea faces geopolitical friction.
Pricing Analysis
Input-cost pass-through from Dead Sea bromine extraction and specialty amine intermediates governs margin structures across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade biocides from industrial cooling tower specifications and commodity municipal treatments. Cost compression in the standard tier is intensifying because municipal procurement prioritizes unit economics over equipment longevity. Municipal water treatment operators exhibit highest price sensitivity, while oilfield chemical management contracts show lowest sensitivity due to bundled service value.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns that position formulated biocides within 48-hour reach of major industrial clusters. Active ingredient production concentrates in Israel, Germany, and China, with formulation blending distributed across regional compounding facilities. The supply chain draws from bromine brine extraction, petrochemical-derived amine intermediates, and peracetic acid feedstocks. Single-source vulnerability at Albemarle's Dead Sea operations creates structural risk during Israeli-Jordanian corridor disruptions. Distribution runs through third-party water service integrators that bundle inventory management with technical dosing support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slimicides market functions as a stable compounder where regulatory-mandated chemistry replacement cycles generate predictable demand irrespective of industrial production volatility.
For Market Incumbents: Anticipate EU Biocidal Products Regulation sunset dates for isothiazolinone derivatives by accelerating peracetic acid and glutaraldehyde qualification programs ahead of formal deadlines. Defensive consolidation through captive toxicology expertise and backward integration into specialty amine intermediates protects margin structures against REACH registration cost escalation. Channel control via multi-year chemical management contracts locks out emerging service integrators in Texas and Alberta oilfields. For New Entrants and Emerging Players: Begin with rapid-degradation biocide formulations targeting Yangtze River basin paper mills under China's MEE effluent tightening, where incumbent qualification lags create specification windows. Agricultural emulsifiable concentrates represent the most penetrable segment due to fragmented spot purchasing and minimal regulatory complexity. A digital dosing platform go-to-market angle transforms commodity supply into predictive maintenance subscriptions with recurring revenue profiles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional water service integrators lacking captive intermediate production but possessing established microbiological monitoring capabilities. Long-term viability over the projection horizon rests on regulatory expertise amortization across multiple jurisdiction registrations rather than single-chemistry dependence. Watch for EPA FIFRA re-registration backlog resolution as the signal indicating whether legacy chlorinated formulations retain market access or accelerate substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Amines | BASF's captive intermediate production insulates margin structures from feedstock volatility in German chemical corridors. |
| Digital Dosing Platform Deployment | IoT-enabled flow-paced injection transforms Lonza's supply relationships toward predictive maintenance subscriptions in Swiss pharmaceutical water systems. |
| Dual-Use Registration Strategy | Peracetic acid convergence across food-grade and industrial specifications amortizes ECHA compliance costs for Bavarian clean-in-place protocols. |
| Multi-Year Chemical Management Contracts | Third-party bundling of slimicide supply with microbiological monitoring concentrates purchasing authority at Houston-area service integrators. |
| Anticipatory Reformulation Investment | Rhine-Ruhr pulp mills qualify glutaraldehyde systems ahead of EU BPR isothiazolinone sunset dates to bypass regulatory uncertainty. |
Research Methodology
Direct dialogue with plant managers at German pulp mills, procurement leads at Middle Eastern desalination operators, technical R&D directors at Swiss pharmaceutical water system providers, and distribution channel partners in Texas oilfields grounded qualitative assessments. Secondary validation drew from EPA FIFRA registration databases, ECHA Biocidal Products Regulation submission records, China MEE effluent discharge filings, and customs trade data on bromine derivative imports. Bottom-up volume modeling across application segments triangulated against top-down chemical consumption indicators from Cefic and ACC industry reports.
Bottom-up segment-level projections across product chemistry tiers, application contexts from cooling towers to oilfield injection systems, and end-user procurement sophistication levels informed the analytical framework throughout the modeling period. CAGRs were derived from replacement cycle timing, regulatory deadline clustering, and industrial capacity expansion patterns in paper and desalination sectors. Forecast inputs incorporated EU BPR re-registration queue priorities and China MEE enforcement intensity variations across provincial environmental bureaus.
Caveats apply where EPA FIFRA review backlog resolution, ECHA aquatic toxicity endpoint revisions, or geopolitical disruption to Dead Sea bromine extraction could materially shift the outlook beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
India Precipitated Silica Market