
 Alpha Olefin Sulfonates Market | 2026-2036
Alpha Olefin Sulfonates Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha Olefin Sulfonates Market Analysis
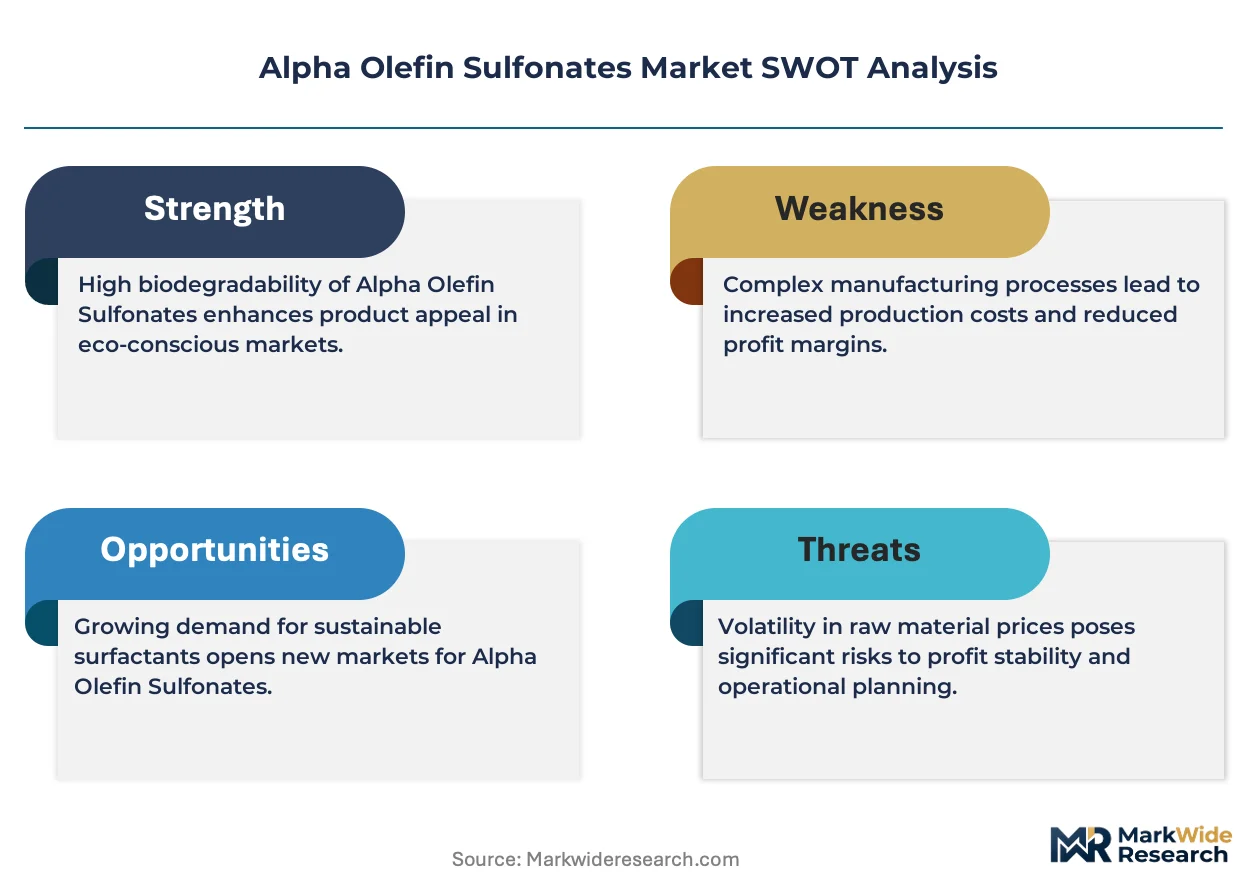
Cosmetic-grade purity specifications is unwinding legacy commodity positioning across the Alpha Olefin Sulfonates landscape. Huntsman Corporation leverages captive ethylene integration to secure linear alpha olefin feedstock economics. Stepan Company anchors North American production through specialized sulfonation reactor networks. Kao Corporation dominates Asian personal care channels with concentrated liquid formulations.
Alpha olefin sulfonates are anionic surfactants produced via sulfonation of linear alpha olefins, typically containing alkene sulfonate and hydroxyalkane sulfonate fractions with active matter ranging from 35% to 95% depending on neutralization chemistry. These compounds function primarily as high-foaming detergents, emulsifiers, and wetting agents across aqueous systems requiring hard-water tolerance and dermatological mildness. The liquid form segment leads volume consumption due to compatibility with automated blending operations in personal care and household cleaning. Sodium alpha olefin sulfonate occupies the dominant product type position, though potassium variants are gaining traction in specialized industrial formulations where enhanced solubility justifies premium positioning.
REACH registration through ECHA governs surfactant biodegradability and ecotoxicity profiles for European market access, while EPA Safer Choice criteria influence North American procurement specifications for institutional cleaning applications. China's MEE enforces wastewater discharge standards that favor alpha olefin sulfonates over less biodegradable alternatives in textile and industrial processing. Stakeholders must monitor regulatory divergence between jurisdictions where carbon chain length restrictions and biodegradability testing protocols are tightening independently.
Market Dynamics
Personal care formulators are expanding procurement of high-foaming anionic surfactants while REACH compliance in Europe tightens biodegradability thresholds, creating simultaneous pull and push forces across the Alpha Olefin Sulfonates landscape.
Growth Catalysts
- Household cleaning concentration:Liquid detergent manufacturers in China are scaling automated blending operations that favor sodium alpha olefin sulfonate compatibility.
- REACH biodegradability mandates:ECHA registration thresholds for surfactant ecotoxicity profiles are disqualifying less biodegradable alternatives in European institutional cleaning procurement.
- Textile processing wastewater standards:China's MEE discharge regulations are elevating alpha olefin sulfonates over conventional chemistries in dyeing and finishing operations.
Market Restraints
- Linear alpha olefin feedstock volatility:Ethylene derivative pricing fluctuations transmit directly to sulfonation economics, compressing margin stability for non-integrated producers.
- Sulfonation capacity concentration:Domestic Chinese reactor networks now supply majority regional demand, limiting import arbitrage opportunities for external manufacturers.
- Alkyl ether sulfate substitution:Personal care formulators in Southeast Asia are piloting alternative anionic surfactants with comparable foaming profiles at lower active-matter costs.
Strategic Opportunities
- Potassium variant industrial penetration:Enhanced solubility positioning in specialized metalworking fluid formulations commands premium pricing in Japanese automotive supply chains.
- EPA Safer Choice procurement:North American institutional cleaning contracts are incorporating biodegradability scoring that favors alpha olefin sulfonate chemistry over legacy alternatives.
- Concentrated liquid formulation channels:E-commerce direct-to-manufacturer distribution is compressing traditional distributor margins in South Korean personal care ingredient sourcing.
Industry Challenges
- Sulfonation reactor engineering expertise:Specialized continuous reactor design and neutralization chemistry knowledge concentrates among retiring technical workforces in European production facilities.
- Carbon chain length certification timelines:Biodegradability testing protocol divergence between ECHA and EPA frameworks extends product registration cycles for multi-jurisdictional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha Olefin Sulfonates Market |
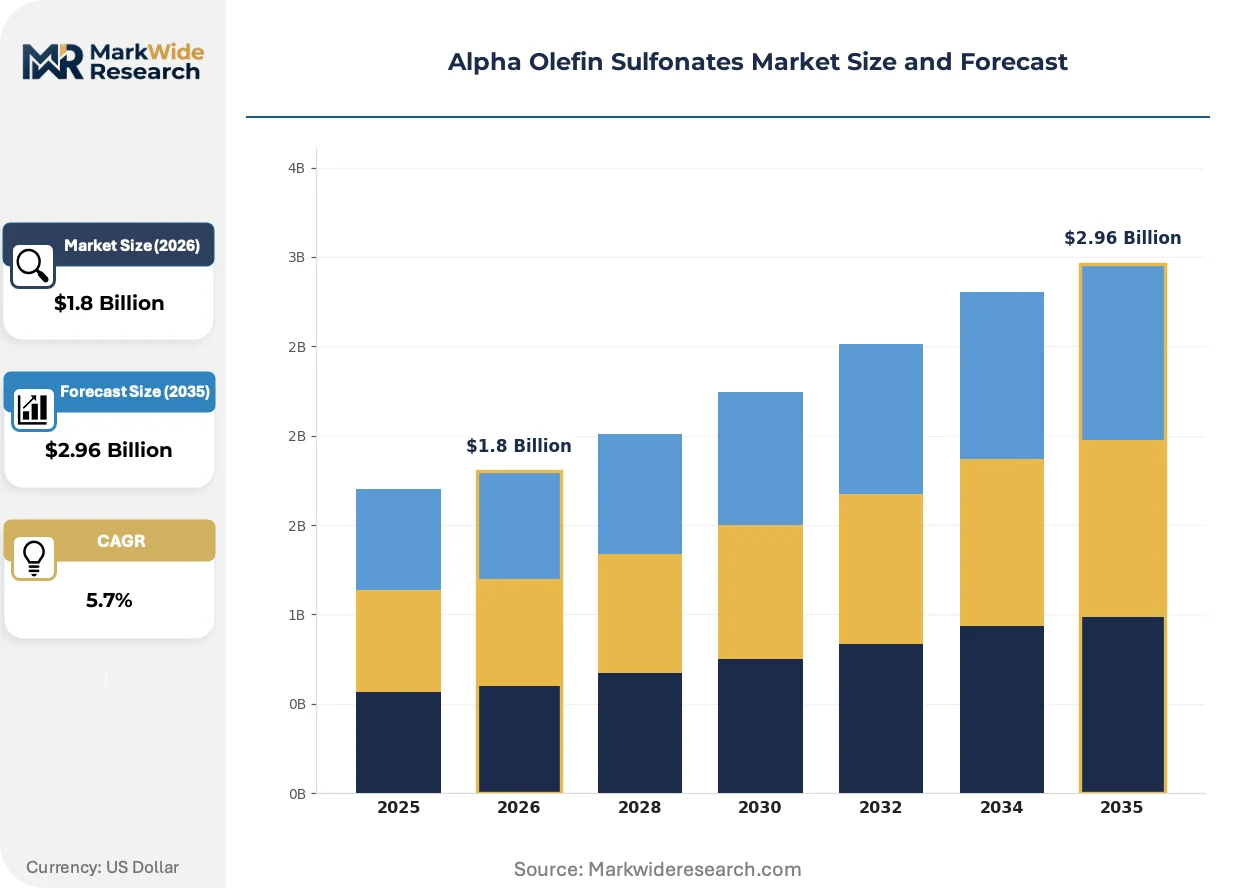
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Alpha Olefin, Sodium Alpha Olefin Sulfonate, Potassium Alpha Olefin Sulfonate, Calcium Alpha Olefin Sulfonate End Use Industry: Personal Care, Household Cleaning, Industrial Cleaning, Agriculture Form: Liquid, Powder, Granule, Paste Application: Detergents, Emulsifiers, Surfactants, Wetting Agents |
| Companies Covered | Nouryon, Huntsman Corporation, Stepan Company, Zanyu Technology Group Co. Ltd., Solvay, Clariant AG, Pilot Chemical Company, Enaspol A.S., Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha Olefin Sulfonates Market Emerging Trajectories
Continuous sulfonation reactor technology is fragmenting legacy batch production economics while regulatory testing protocol divergence and procurement digitization are reshaping competitive access and buyer-supplier relationships across the value chain.
Membrane sulfonation systems are fragmenting established production cost structures by enabling higher active-matter yields with reduced neutralization byproduct formation. Mid-scale personal care compounders in India and Brazil are adopting these systems to bypass capital-intensive legacy reactor investments. The technology is fragmenting regional supply patterns by allowing smaller-batch, higher-purity output that meets cosmetic-grade specifications without integrated petrochemical backing.
REACH registration through ECHA now mandates updated biodegradability dossiers for surfactant substances above 100 tons annual volume. European formulators are reformulating household cleaning lines to preempt registration withdrawal risks. Personal care applications face the tightest compliance timelines, with several suppliers accelerating potassium variant development to diversify substance identity portfolios.
Direct platform procurement between sulfonate producers and personal care brand technical teams is displacing traditional distributor-led ingredient sourcing. Large formulators in Germany and the United States are consolidating approved supplier lists around manufacturers with documented carbon chain length traceability. This channel compression is most visible in premium cosmetic segments where dermatological testing documentation accompanies every active-matter shipment.
Alpha Olefin Sulfonates Market Segmentation
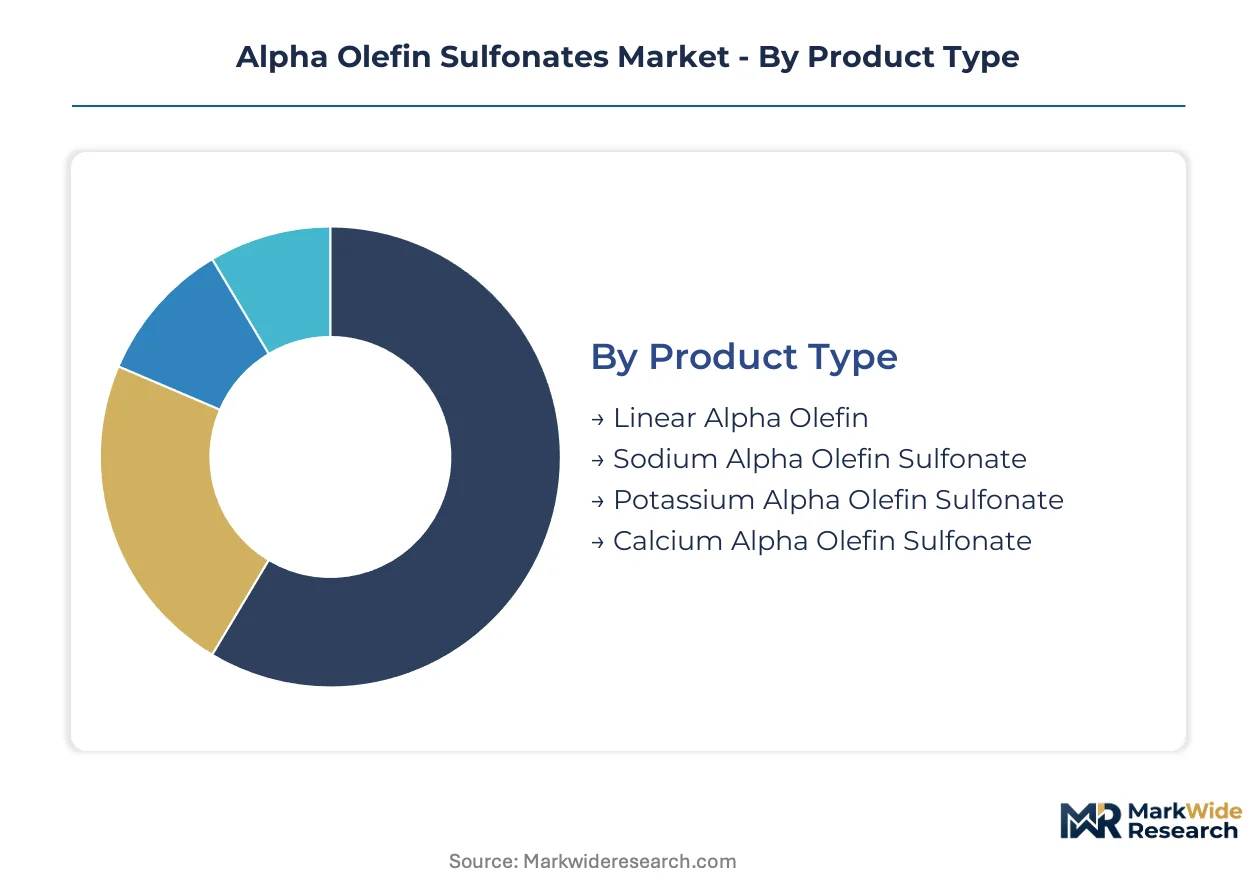
Alpha olefin sulfonate procurement patterns diverge sharply across product chemistry, end-use specifications, and physical form requirements. Formulators prioritize carbon chain precision for dermatological applications while industrial buyers optimize for solubility and active-matter concentration.
Product Type:
Margin pools concentrate in sodium and potassium variants where neutralization chemistry and feedstock integration determine cost competitiveness.
- Sodium Alpha Olefin Sulfonate:Dominant commercial form with 35-95% active matter depending on neutralization endpoint. Chinese liquid detergent manufacturers scale automated blending operations around sodium salt compatibility, while REACH compliance in Europe disqualifies less biodegradable alternatives from institutional cleaning procurement.
- Potassium Alpha Olefin Sulfonate:Enhanced solubility positioning commands premium pricing in specialized metalworking fluid formulations. Japanese automotive supply chains favor potassium variants for hard-water tolerance in precision machining operations, though higher raw material costs limit mass-market penetration.
- Linear Alpha Olefin:Feedstock precursor for downstream sulfonation with carbon chain lengths from C12 to C18 determining final surfactant properties.
- Calcium Alpha Olefin Sulfonate:Niche industrial applications in grease and lubricant formulations where calcium salt stability provides formulation advantages.
The dominant share belongs to Sodium Alpha Olefin Sulfonate, while Potassium Alpha Olefin Sulfonate is gaining share fastest in premium industrial channels.
End Use Industry:
Application requirements range from cosmetic-grade purity thresholds to bulk industrial specifications, reshaping supplier qualification criteria.
- Personal Care:Cosmetic-grade purity specifications with dermatological testing documentation for every active-matter shipment. German and United States formulators consolidate approved supplier lists around manufacturers with documented carbon chain length traceability, while Southeast Asian pilots test alkyl ether sulfate alternatives.
- Household Cleaning:Volume-driven procurement with biodegradability scoring under EPA Safer Choice criteria influencing North American institutional contracts. Chinese MEE wastewater discharge standards elevate alpha olefin sulfonates over conventional chemistries in textile and industrial processing.
- Industrial Cleaning:Hard-water tolerance and emulsification performance specifications for metal degreasing and parts washing operations.
- Agriculture:Wetting agent applications in pesticide and fertilizer formulations requiring field stability across variable water chemistries.
Personal Care commands the dominant revenue share, though Household Cleaning demonstrates the steepest expansion trajectory in absolute volume terms.
Form:
Physical state determines logistics economics, automated handling compatibility, and regional manufacturing infrastructure requirements.
- Liquid:Dominant volume consumption due to compatibility with automated blending operations in personal care and household cleaning. South Korean e-commerce direct-to-manufacturer distribution compresses traditional distributor margins for concentrated liquid sourcing.
- Powder:Spray-dried formulations for solid detergent tablets and powder laundry products with extended shelf stability requirements.
- Granule:Intermediate handling characteristics for industrial compounders requiring controlled dissolution rates.
- Paste:High-viscosity applications in specialized personal care formulations where rheology control is critical.
Liquid form holds the dominant position, with Powder expanding most quickly in solid detergent tablet formats.
Application:
Functional performance requirements vary across foam stability, emulsification efficiency, and wetting speed specifications.
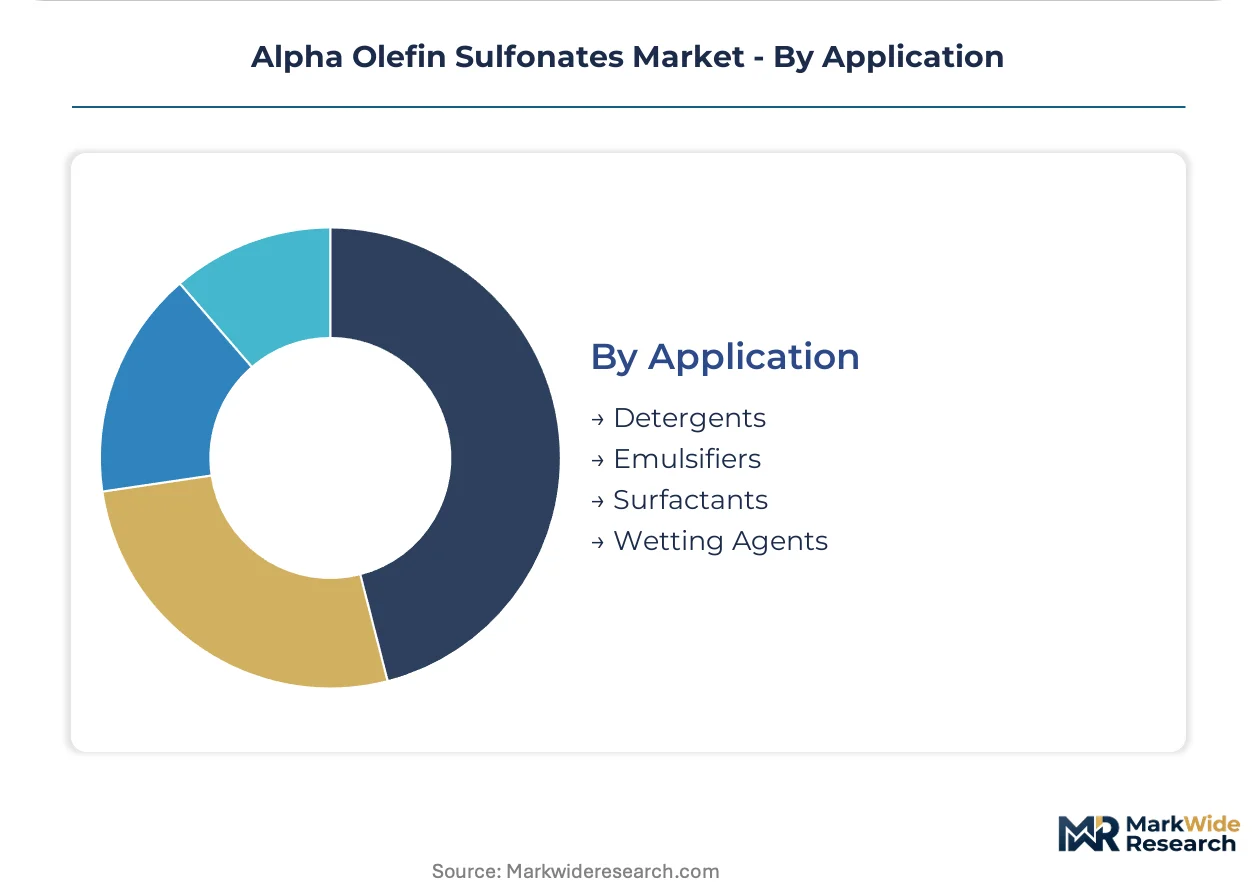
- Detergents:Primary volume application with high-foaming profiles and hard-water tolerance specifications. Chinese domestic sulfonation capacity expansion supplies majority regional demand, limiting import arbitrage opportunities.
- Surfactants:Broad functional category encompassing anionic surface-active chemistry in aqueous systems.
- Emulsifiers:Oil-in-water stabilization for cosmetic and agricultural formulations requiring HLB balance precision.
- Wetting Agents:Surface tension reduction for coating, printing, and textile processing applications.
Detergents represent the dominant application, while Emulsifiers are climbing the fastest in premium cosmetic-grade channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese domestic sulfonation reactor networks now supply the majority of regional demand, compressing import arbitrage windows for external manufacturers while REACH compliance in Europe and EPA Safer Choice criteria in North America reshape procurement specifications.
China
Liquid detergent manufacturers in Zhejiang and Guangdong provinces scale automated blending operations around sodium alpha olefin sulfonate compatibility. MEE wastewater discharge standards elevate these surfactants over less biodegradable alternatives in textile processing. The Yangtze River Delta concentration of sulfonation capacity limits pricing power for imported material.
United States
Institutional cleaning contractors incorporate EPA Safer Choice biodegradability scoring that favors alpha olefin sulfonate chemistry. The Southeast chemical manufacturing corridor hosts specialized sulfonation reactor networks serving personal care formulators. Greater Houston's petrochemical integration secures linear alpha olefin feedstock economics for regional producers.
Germany
Cosmetic-grade purity specifications drive consolidation of approved supplier lists around manufacturers with documented carbon chain traceability. ECHA REACH registration mandates updated biodegradability dossiers for surfactants above 100 tons annual volume. The North Rhine-Westphalia industrial cluster concentrates technical sulfonation expertise among specialized chemical producers.
Japan
Automotive supply chains favor potassium alpha olefin sulfonate variants for hard-water tolerance in precision metalworking fluids. METI industrial standards shape procurement specifications for specialized industrial formulations. The Kansai region's chemical processing infrastructure supports premium surfactant production for domestic personal care channels.
India
Mid-scale personal care compounders adopt membrane sulfonation systems to bypass capital-intensive legacy reactor investments. BIS standards for surfactant quality create compliance barriers for unqualified imports. Maharashtra's chemical manufacturing belt hosts emerging domestic sulfonation capacity serving regional detergent and cosmetic formulators.
Alpha Olefin Sulfonates Market Vendor Landscape
Concentration sits with integrated petrochemical producers and specialized sulfonation technology holders. The market structure spans three tiers: multinational chemical conglomerates with captive ethylene integration, regional specialists with reactor engineering expertise, and emerging Asian manufacturers with cost-optimized membrane systems. Dominant competitive moves include backward integration into linear alpha olefin feedstock and strategic partnerships with personal care formulators seeking documented carbon chain traceability.
Within the multinational tier, Nouryon and Solvay represent integrated chemical producers with broad surfactant portfolios spanning multiple jurisdictions. Huntsman Corporation exemplifies petrochemical-backed positioning through captive ethylene integration. Stepan Company and Pilot Chemical Company occupy specialized sulfonation technology positions in North American markets. Kao Corporation anchors Asian personal care channel access with concentrated liquid formulation capabilities. Zanyu Technology Group Co. Ltd. represents Chinese domestic capacity expansion that has reshaped regional supply patterns.
| Leading Market Players |
|---|
| Nouryon |
| Huntsman Corporation |
| Stepan Company |
| Zanyu Technology Group Co. Ltd. |
| Solvay |
| Clariant AG |
| Pilot Chemical Company |
| Enaspol A.S. |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Chinese liquid detergent manufacturers and domestic sulfonation producers lock in both supply access and price visibility across the alpha olefin sulfonate value chain. These arrangements insulate integrated players from ethylene derivative volatility while exposing non-integrated buyers to margin compression.
Pricing Analysis
REACH registration mandates dictate the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates cosmetic-grade certified material from institutional cleaning grades and bulk industrial specifications. Price differentiation rests on carbon chain length certification and biodegradability dossier completeness. Cost compression in standard-tier sodium variants is intensifying because Chinese domestic capacity expansion erodes import arbitrage windows. Household cleaning formulators exhibit highest price sensitivity, while Japanese automotive metalworking fluid buyers accept potassium variant premiums.
Supply Chain Analysis
Strategic stockpile preferences dominate among German and United States personal care formulators seeking documented carbon chain traceability. Supply concentrates in China, Germany, and the United States, with the Yangtze River Delta, North Rhine-Westphalia, and Greater Houston hosting specialized reactor networks. Raw material dependencies center on linear alpha olefins from ethylene crackers, sulfur trioxide for sulfonation, and neutralizing agents. Single-source vulnerability concentrates in legacy continuous reactor engineering expertise among retiring European technical workforces. Distribution runs through direct platform procurement displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alpha olefin sulfonate demand sits in early-cycle expansion as REACH biodegradability mandates and China's MEE wastewater standards simultaneously displace legacy surfactant chemistries across multiple end-use channels.
For Market Incumbents: Secure captive ethylene integration or long-term linear alpha olefin feedstock agreements to defend margin position against Chinese domestic cost structures. Invest in membrane sulfonation technology to serve mid-scale compounders in India and Brazil seeking cosmetic-grade purity without integrated petrochemical backing. Alkyl ether sulfate substitution pilots in Southeast Asia represent the immediate substitution threat requiring formulation partnership responses.
For New Entrants and Emerging Players: Technical sulfonation reactor engineering expertise gaps among retiring European workforces open acquisition and licensing opportunities for specialized engineering services. Target South Korean e-commerce direct-to-manufacturer distribution channels where traditional distributor relationships are compressing. Lead with carbon chain length traceability documentation to penetrate German and United States personal care formulator approved supplier lists.
For Investors and Strategic Acquirers: Regional specialists with reactor engineering expertise and established ECHA registration dossiers represent the most defensible acquisition targets within a five-to-ten year viability window. Monitor potassium variant development pipelines as signal for portfolio diversification toward premium industrial applications. Inflection becomes visible when Japanese automotive supply chains expand potassium sourcing beyond precision metalworking into broader formulation categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Alpha Olefins | Huntsman Corporation's captive ethylene supply secures feedstock economics against derivative volatility. |
| Membrane Sulfonation Technology Deployment | Mid-scale Indian compounders bypass capital-intensive legacy reactors for cosmetic-grade output. |
| Potassium Variant Formulation Development | Japanese automotive supply chains favor enhanced solubility for hard-water precision machining. |
| Direct Platform Procurement Channel Buildout | South Korean e-commerce distribution compresses traditional ingredient distributor margins. |
| ECHA Biodegradability Dossier Acceleration | European formulators preempt registration withdrawal risks for surfactants above volume thresholds. |
Methodological Framework
Operator-level perspectives from sulfonation plant managers, personal care procurement leads, institutional cleaning formulators, and technical R&D directors anchored the qualitative base. Primary fieldwork combined with secondary validation from ECHA registration databases, Chinese MEE discharge standard filings, EPA Safer Choice criteria documentation, and SEC 10-K disclosures from disclosed chemical producers. Customs and trade data from major exporting jurisdictions provided volume triangulation against bottom-up capacity estimates and top-down end-use consumption models.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios and regulatory implementation timing variations. Segmentation dimensions modeled include product chemistry variants, end-use industry specifications, physical form requirements, and regional production hub classifications. CAGRs were derived from installed capacity utilization rates cross-referenced with end-use demand elasticity parameters. Sulfonation reactor capacity expansion timelines and REACH registration withdrawal schedules served as industry-specific forecast inputs across the projection horizon.
Forecasts assume regulatory continuity in REACH, EPA Safer Choice, and China's MEE discharge regimes; material policy shifts would require re-modeling. Specific risk factors include carbon chain length restriction amendments, biodegradability testing protocol divergence between ECHA and EPA frameworks, and ethylene derivative price shock transmission. Revision becomes warranted when Chinese domestic sulfonation capacity utilization crosses threshold levels that eliminate import arbitrage windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Glycerine Market
Oleochemicals
Stearyl Tartrate Market