
 Process Fluid Market | 2026-2036
Process Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Process Fluid Market Outlook
Direct supply contracts between refiners and original equipment manufacturers is rewriting procurement economics across the process fluid sector. ExxonMobil Corporation leverages its integrated base oil and additive manufacturing to sustain cost advantages in hydraulic fluid supply chains. BASF SE anchors its position through specialty ester and polyalkylene glycol chemistry leadership, while Fuchs Petrolub SE differentiates via application engineering services tied to metalworking and powertrain fluids.
Process fluids are engineered liquid media formulated from mineral oils, synthetic base stocks, or aqueous glycol solutions, designed to transfer thermal energy, transmit mechanical force, or reduce friction in industrial equipment operating between minus forty and three hundred degrees Celsius. Their primary purpose centers on protecting capital-intensive machinery from wear, corrosion, and thermal degradation across continuous-process industries. Lubricants command the largest value share within product type segmentation due to replacement frequency and premium synthetic upgrade cycles, while coolants represent the fastest-expanding category as electric vehicle thermal management and data center liquid cooling diversify demand beyond traditional internal combustion engine applications. Chemical processing and oil & gas applications retain dominant volume positions, though food & beverage grade formulations are gaining traction as sanitary design standards tighten.
EPA toxicity screening protocols and REACH substance authorization requirements in Europe are restricting certain chlorinated and aromatic process fluid chemistries, compelling reformulation investments. FDA food-contact substance notifications and NSF International registration govern lubricant and coolant eligibility in food processing and pharmaceutical manufacturing environments. China MIIT energy efficiency standards for industrial equipment are indirectly mandating higher-performance thermal transfer fluids. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure multi-region product registrations ahead of compliance deadlines.
Market Dynamics
Semiconductor fabrication expansion and electric vehicle thermal management are restructuring demand composition across mineral oil, synthetic, and bio-based process fluid categories, forcing reformulation investments and supply contract renegotiations.
Growth Catalysts
- REACH substance authorization:European chemical restrictions on chlorinated aromatics are redirecting R&D expenditure toward ester and polyalkylene glycol chemistry platforms, accelerating synthetic base stock adoption in metalworking and powertrain applications.
- Data center liquid cooling:Hyperscale computing facilities in Singapore, Ireland, and Virginia are deploying dielectric thermal transfer fluids at scale, creating incremental demand outside traditional industrial machinery segments.
- China MIIT energy efficiency mandates:Industrial equipment performance standards are indirectly requiring higher-grade hydraulic and thermal fluids to meet operational temperature and friction reduction targets in domestic manufacturing.
Market Restraints
- Group III base oil supply concentration:Refinery capacity for high-viscosity index mineral stocks clusters in South Korea, the United States, and the Netherlands, exposing formulators to geographic disruption risk and input cost volatility.
- EPA toxicity evaluation timelines:Extended hazard assessment protocols for per- and polyfluoroalkyl substances are delaying new chemistry introductions and extending legacy product dependence in aerospace and electronics cooling.
- Aqueous glycol substitution:Water-glycol mixtures with corrosion inhibitor packages are capturing share in moderate-temperature hydraulic applications, compressing margins for full-synthetic formulations in price-sensitive industrial segments.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for advanced chemistry cell and semiconductor fabrication facilities are creating localized demand for high-purity thermal transfer fluids with domestic formulation requirements.
- Direct OEM supply contracts:Original equipment manufacturers in wind turbine and industrial robotics sectors are consolidating fluid procurement under single-source agreements, favoring suppliers with captive additive blending capabilities.
- Bio-based ester feedstocks:Agricultural oil derivatives with improved oxidative stability are penetrating food processing and marine applications where NSF registration and biodegradability certifications command price premiums.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in tribology and thermal fluid engineering is concentrated among aging practitioners in Germany, Japan, and the United States, constraining product development velocity at mid-sized blenders.
- Multi-jurisdiction registration synchronization:Divergent EPA, REACH, and China MEE compliance timelines for new additive packages are extending time-to-market and stranding development expenditure when regulatory thresholds shift mid-approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Fluid Market |
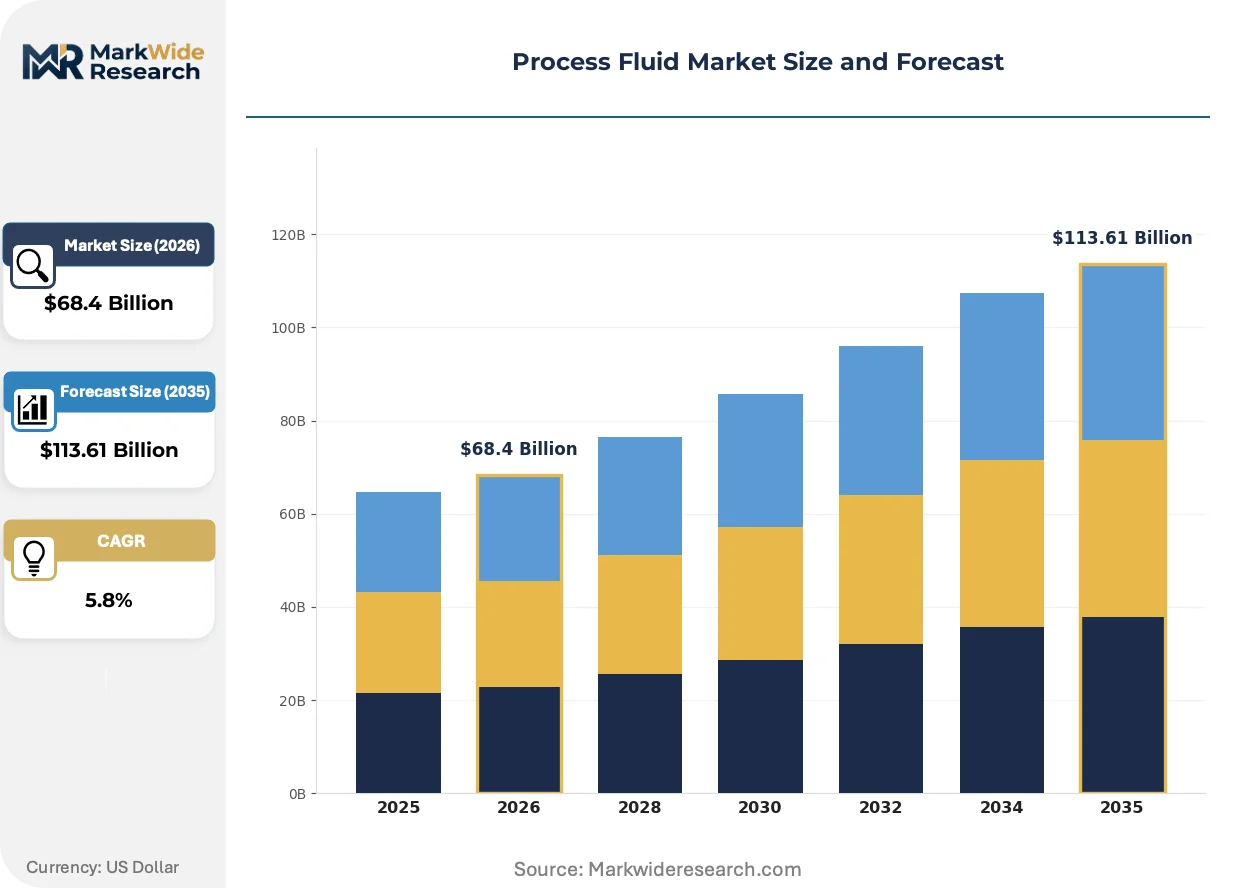
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Antifreeze, Coolants, Lubricants Application: Chemical Processing, Oil & Gas, Power Generation, Food & Beverage End User: Manufacturing, Automotive, Aerospace, Pharmaceuticals Distribution Channel: Retail, Direct Sales, Online, Distributors |
| Companies Covered | TotalEnergies, Royal Dutch Shell, ExxonMobil Corporation, The Chemours Company, Chevron Corporation, Quaker Chemical Corporation, BP plc, BASF SE, Fuchs Petrolub SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Fluid Market Strategic Shifts
Synthetic base stock performance thresholds, regulatory chemistry restrictions, and procurement consolidation are compressing traditional product lifecycles and reshaping competitive differentiation in process fluid supply.
Single-phase immersion cooling using engineered dielectric fluids is collapsing the boundary between thermal management and fire safety specifications in data center construction. Hyperscale operators in Northern Virginia, Frankfurt, and Singapore are specifying fluids with simultaneous heat capacity, electrical insulation, and low global warming potential. This convergence is eliminating the historical separation between HVAC refrigerant and industrial coolant procurement categories, forcing fluid suppliers to certify across previously distinct regulatory frameworks.
EU F-Gas Regulation phase-down schedules are accelerating synthetic refrigerant and thermal fluid chemistry transitions in European industrial equipment. The restriction on hydrofluorocarbon global warming potential values above specific thresholds is compelling heat pump and chiller OEMs to specify hydrofluoroolefin or natural refrigerant-compatible thermal transfer media. Food processing and pharmaceutical manufacturing in Germany, Denmark, and the Netherlands are experiencing the most acute formulation switching pressure due to combined F-Gas and EFSA food-contact substance compliance requirements.
After-sales fluid analysis and condition monitoring are unbundling from equipment maintenance contracts, creating standalone service revenue streams and altering distributor economics. Industrial buyers in automotive stamping and aerospace machining are contracting directly with fluid suppliers for predictive analytics subscriptions, bypassing traditional distributor technical service relationships. This pattern is most developed in the United States and Germany, where ISO 4406 cleanliness code monitoring and additive depletion tracking are standard contractual inclusions in multi-year supply agreements.
Process Fluid Market Segmentation
Process fluid procurement patterns diverge sharply across industrial end-uses, with formulation specifications and compliance requirements creating distinct commercial segments. Understanding these divides clarifies where synthetic upgrade cycles concentrate versus where mineral oil formulations retain cost advantages.
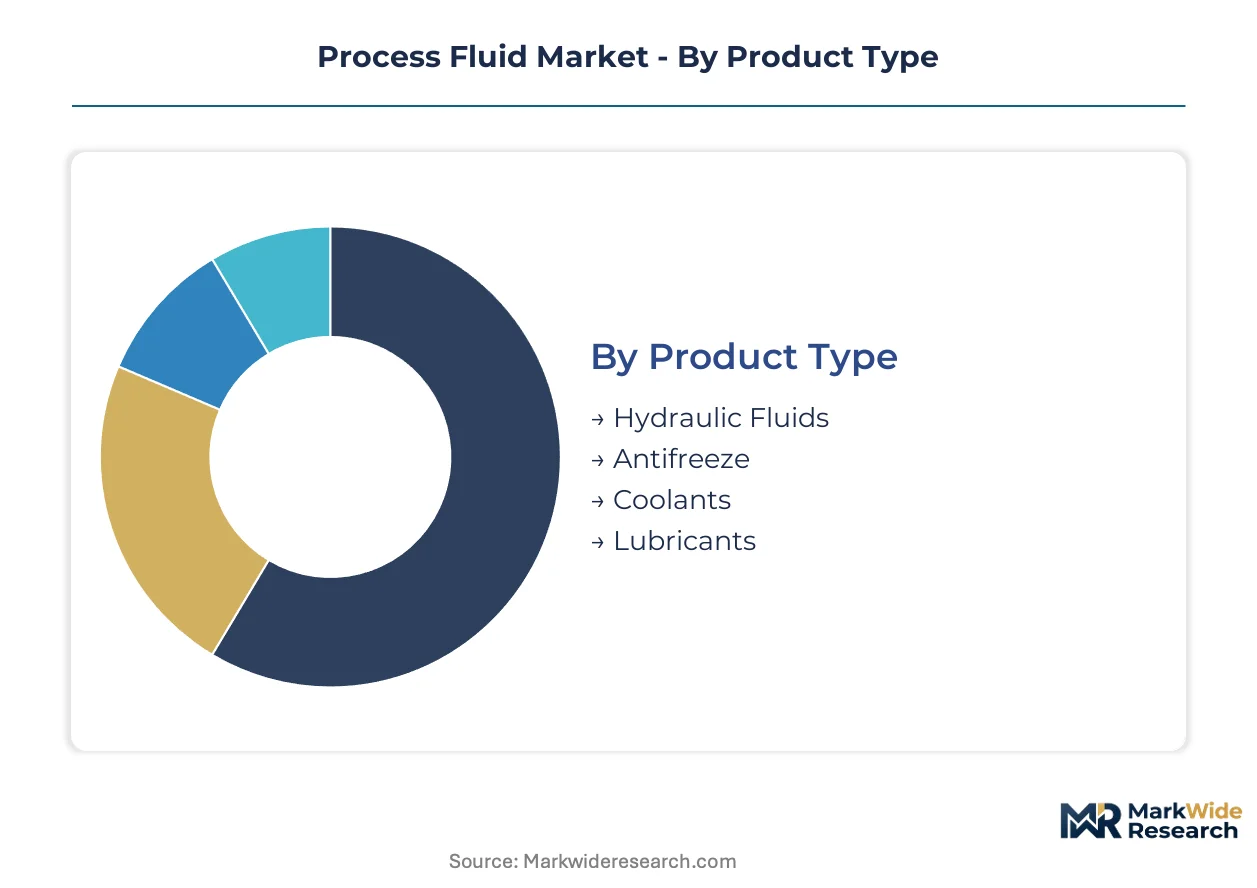
Product Type:
Mature mineral-based categories dominate volume, while synthetic and bio-based alternatives capture expanding share in temperature-extreme applications.
- Lubricants:Formulated from Group I-III mineral oils or synthetic polyalphaolefin and ester base stocks, these fluids reduce friction in rotating equipment across continuous-process industries. Demand concentrates in automotive powertrain manufacturing in Germany and Japan, where OEM specifications mandate extended drain intervals and lower viscosity grades. REACH substance restrictions on chlorinated additives are accelerating reformulation toward sulfur-phosphorus and ashless chemistry platforms.
- Coolants:Aqueous glycol solutions and dielectric thermal transfer fluids manage heat rejection in engines, electric vehicle battery packs, and data center immersion systems. Procurement is accelerating in Northern Virginia and Singapore hyperscale computing clusters, where single-phase immersion cooling with engineered fluorocarbon and silicone fluids is displacing traditional air conditioning infrastructure.
- Hydraulic Fluids:Mineral oil or fire-resistant water-glycol and phosphate ester formulations transmit force in industrial machinery and mobile equipment. Specifications in China MIIT energy efficiency standards are tightening viscosity and oxidation stability requirements for domestic manufacturing equipment.
- Antifreeze:Ethylene glycol and propylene glycol-based engine coolants with corrosion inhibitor packages protect against freeze damage and cavitation. NSF International registration governs food-grade propylene glycol applications in beverage processing equipment.
Lubricants retain volume leadership; coolants hold the steepest expansion curve.
Application:
Process intensity and regulatory exposure determine formulation premium tolerance across industrial verticals.
- Chemical Processing:High-purity thermal transfer fluids and synthetic lubricants withstand aggressive chemistries and continuous operation in petrochemical crackers and specialty chemical reactors. Demand clusters in Texas and Louisiana Gulf Coast complexes, where heat recovery systems require fluids stable above 300 degrees Celsius.
- Oil & Gas:Drilling muds, completion fluids, and subsea hydraulic systems operate in high-pressure, high-temperature reservoirs. North Sea and Permian Basin operators are specifying biodegradable ester-based formulations to satisfy offshore discharge regulations and land-based spill remediation requirements.
- Food & Beverage:NSF H1-registered lubricants and heat transfer fluids meet incidental food contact standards in processing, packaging, and bottling equipment. FDA food-contact substance notifications and 3A sanitary standards compliance create formulation barriers that sustain price premiums for certified suppliers.
- Power Generation:Turbine oils, transformer fluids, and heat transfer media in combined-cycle and renewable energy facilities. Fire-resistant phosphate ester hydraulic fluids are mandatory in steam turbine electro-hydraulic control systems per IEEE and OEM specifications.
Chemical processing commands the largest procurement scale; food and beverage applications generate the highest margin premiums per liter.
End User:
Capital equipment lifecycle and maintenance outsourcing preferences reshape fluid specification authority across buyer categories.
- Manufacturing:Metalworking fluids, industrial lubricants, and hydraulic oils in stamping, machining, and assembly operations. Automotive stamping plants in Michigan and Bavaria are contracting predictive fluid analysis services directly from suppliers, bypassing traditional distributor technical support relationships.
- Automotive:OEM factory-fill lubricants, coolant system requirements, and electric vehicle thermal management fluids. Battery electric vehicle manufacturers in South Korea and California are qualifying dielectric coolants for direct cell contact applications with stringent electrical insulation and material compatibility specifications.
- Aerospace:Military and commercial aviation lubricants, hydraulic fluids, and deicing compounds. Boeing and Airbus supply chains impose AS9100 quality system requirements and extended product traceability that constrain qualified supplier pools.
- Pharmaceuticals:USP-grade mineral oils and white oils in tablet manufacturing, ointment bases, and process equipment lubrication. FDA 21 CFR 172.878 and 178.3620 compliance for direct and indirect food contact creates dedicated supply channels with audited manufacturing controls.
Manufacturing absorbs the greatest fluid volume; aerospace and pharmaceutical segments extract the strictest qualification and documentation requirements.
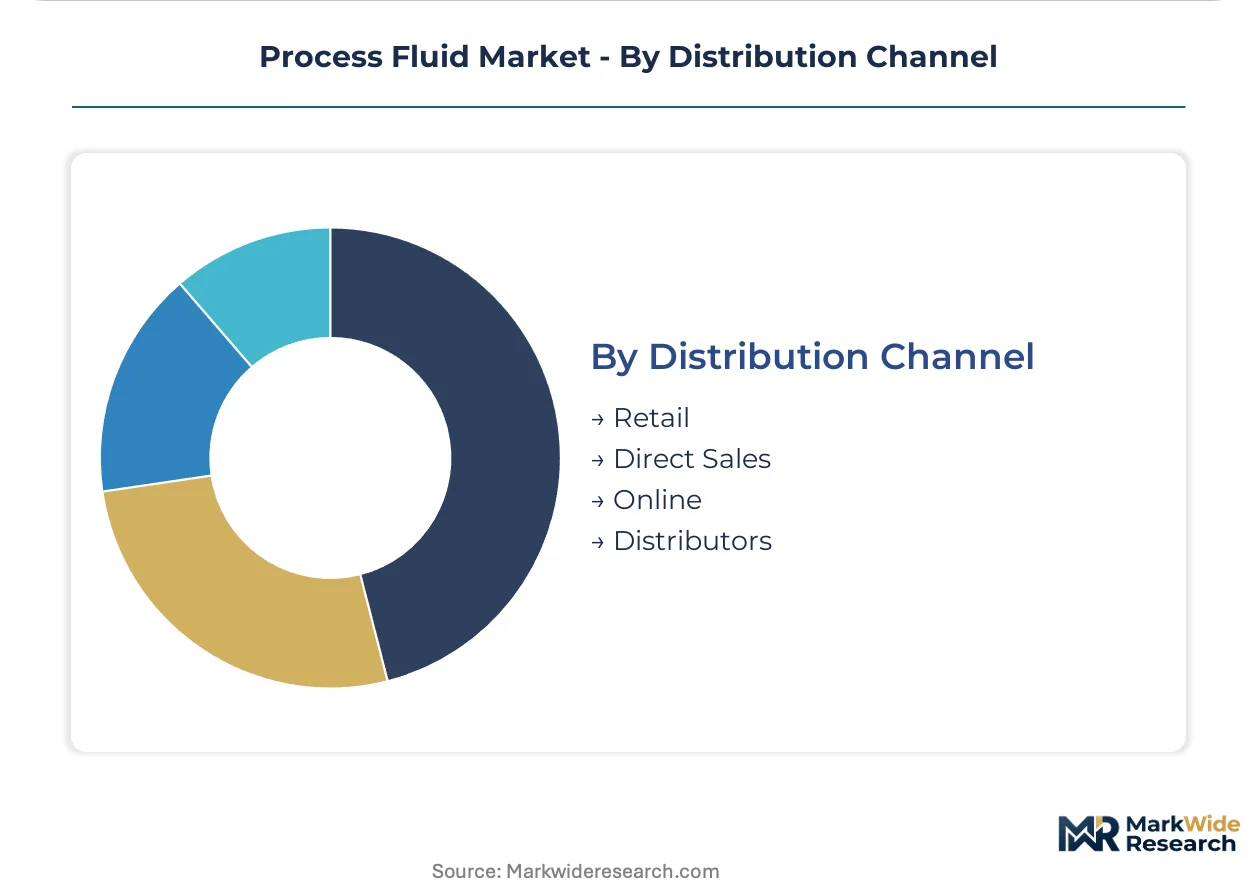
Distribution Channel:
Supply chain configuration determines technical service bundling and price transparency available to different buyer scales.
- Distributors:Independent and captive networks providing local inventory, technical service, and waste fluid management for small and mid-sized industrial accounts. Fuchs Petrolub and comparable specialists leverage application engineering capabilities to defend position against direct OEM contracting trends.
- Direct Sales:Refiner and blender direct relationships with large industrial accounts, wind turbine OEMs, and automotive manufacturers. ExxonMobil and BASF anchor multi-year supply agreements with integrated additive blending and condition monitoring service inclusions.
- Online:E-procurement platforms and distributor web portals for standard-grade hydraulic fluids and automotive aftermarket coolants. Price transparency and bulk purchasing tools appeal to maintenance-repair-operations buyers with predictable specification requirements.
- Retail:Automotive service centers, farm supply stores, and industrial supply houses serving consumer and small commercial vehicle maintenance. Packaged antifreeze and automotive lubricants compete on brand recognition and OEM approval certifications.
Distributors maintain the broadest account coverage; direct sales channels capture the highest contract value and longest duration agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT energy efficiency mandates and PLI scheme incentives are redirecting process fluid procurement toward high-performance synthetic formulations across major manufacturing economies. National industrial policies now directly influence base stock selection and additive package specifications.
China
Petrochemical capacity expansions in Zhejiang and Shandong provinces are accelerating thermal transfer fluid consumption. MIIT industrial equipment standards mandate higher-grade hydraulic fluids for domestic machinery. Yangtze River Delta semiconductor fabs are qualifying high-purity dielectric coolants for advanced node production.
United States
EPA toxicity evaluations for per- and polyfluoroalkyl substances are delaying new chemistry introductions in aerospace cooling. Permian Basin operators are specifying biodegradable ester-based drilling fluids to satisfy land-based spill remediation requirements. Northern Virginia hyperscale data centers are deploying single-phase immersion cooling at scale.
Germany
EU F-Gas Regulation phase-down schedules are compelling heat pump OEMs to specify hydrofluoroolefin-compatible thermal transfer media. REACH substance authorization restricts chlorinated aromatics in metalworking applications. Bavarian automotive stamping plants are contracting predictive fluid analysis services directly from suppliers.
India
PLI scheme incentives for advanced chemistry cell and semiconductor fabrication are creating localized demand for high-purity thermal transfer fluids. BIS standards for industrial lubricants are tightening viscosity and oxidation stability requirements. Gujarat and Maharashtra chemical corridors are expanding process fluid formulation capacity.
South Korea
Group III base oil refinery concentration exposes formulators to geographic disruption risk. Battery electric vehicle manufacturers are qualifying dielectric coolants for direct cell contact applications. Seoul Capital Area semiconductor clusters are expanding high-purity thermal transfer fluid procurement.
Process Fluid Market Competitive Environment
On the supply side, the industry is consolidating around integrated refiners with captive additive blending capabilities and specialty chemical houses with ester and polyalkylene glycol chemistry leadership. Strategic archetypes include vertically integrated oil majors, application engineering specialists, and bio-based feedstock innovators. Dominant competitive moves encompass direct OEM supply contract consolidation and multi-jurisdiction regulatory registration synchronization.
Among integrated oil majors, ExxonMobil Corporation and Royal Dutch Shell anchor positions through base oil manufacturing and additive formulation integration. BASF SE exemplifies specialty chemical leadership in synthetic ester platforms. Fuchs Petrolub SE occupies a position within the application engineering tier, bundling technical services with metalworking and powertrain fluid supply.
| Leading Market Players |
|---|
| TotalEnergies |
| Royal Dutch Shell |
| ExxonMobil Corporation |
| The Chemours Company |
| Chevron Corporation |
| Quaker Chemical Corporation |
| BP plc |
| BASF SE |
| Fuchs Petrolub SE |
| Others |
Value Chain & Pricing Dynamics
Singapore-Johannesburg shipping lane cost volatility amplifies price spreads between Group III base oil hubs in South Korea and synthetic ester blenders in Germany, compressing margins for formulators lacking backward integration into additive manufacturing while rewarding suppliers with captive corrosion inhibitor production.
Pricing Analysis
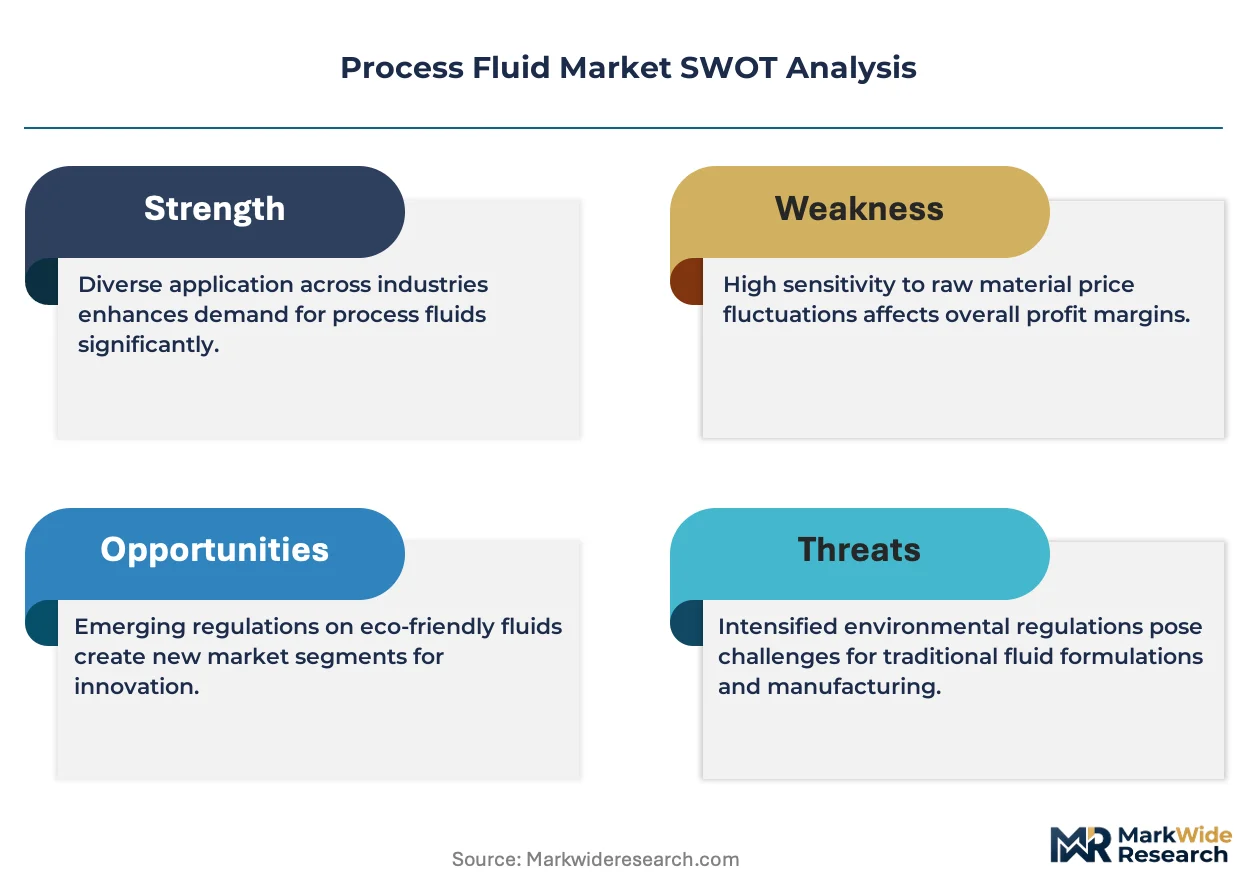
Certification level creates the primary spread between NSF H1-registered food-grade formulations and standard industrial mineral oils. Three-tier pricing structure across premium synthetic esters, mid-grade polyalphaolefins, and economy mineral stocks governs contract negotiations. Pricing pressure stems from aqueous glycol substitution in moderate-temperature hydraulic applications. Maintenance-repair-operations buyers exhibit highest price sensitivity; semiconductor fabs accept steep premiums for dielectric purity guarantees.
Supply Chain Analysis
US Bureau of Industry and Security export controls on fluorinated chemistry precursors constrain dielectric fluid flows to Yangtze River Delta semiconductor clusters. Supply concentrates in South Korea for Group III base oils, Germany for specialty ester synthesis, and the Netherlands for polyalkylene glycol feedstocks. Formulation hinges on adipic acid, trimellitic anhydride, and hydrogenated vegetable oil derivatives. Single-source vulnerability runs through South Korean refinery concentration. Distribution runs through direct OEM contracts consolidating procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle thermal management and data center immersion cooling are disrupting traditional mineral oil economics, with REACH substance authorization and EPA toxicity evaluations accelerating chemistry transitions that favor synthetic and bio-based formulation platforms.
For Market Incumbents: Pre-empt aqueous glycol substitution by qualifying bio-based ester platforms for marine and food processing applications where NSF registration commands premiums. Secure direct supply contracts with wind turbine OEMs before distributor relationships solidify. Backward integration into corrosion inhibitor manufacturing protects margin compression from specialty chemical suppliers.
For New Entrants and Emerging Players: Build out India PLI scheme-aligned formulation capacity in Gujarat and Maharashtra chemical corridors, targeting domestic semiconductor fabs and advanced chemistry cell manufacturers with high-purity thermal transfer fluids. White space concentrates in predictive fluid analysis subscriptions for automotive stamping plants seeking ISO 4406 cleanliness monitoring.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oil majors divesting non-core lubricant blending assets. Five-to-ten year viability favors suppliers with multi-jurisdiction regulatory registration capabilities spanning EPA, REACH, and China MEE compliance timelines. Monitor EPA per- and polyfluoroalkyl substance evaluation outcomes as inflection signal for aerospace cooling chemistry switches.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive corrosion inhibitor production insulates ExxonMobil from specialty chemical supplier pricing power. |
| Direct OEM Supply Contract Consolidation | Wind turbine manufacturers are unbundling fluid procurement from equipment maintenance agreements. |
| Bio-Based Ester Platform Qualification | Agricultural oil derivatives with oxidative stability penetrate marine applications requiring biodegradability certifications. |
| Multi-Jurisdiction Regulatory Registration Synchronization | Simultaneous EPA, REACH, and China MEE approvals prevent stranded inventory from divergent compliance timelines. |
| Predictive Fluid Analysis Subscription Launch | Bavarian automotive stamping plants contract ISO 4406 monitoring directly from suppliers, bypassing distributors. |
Study Parameters
A spread of perspectives from refinery operations managers, OEM procurement leads at wind turbine manufacturers, metalworking fluid technical directors, and distribution channel partners converged on the working assumptions. Primary interview insights triangulated against customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and MIIT equipment standard documentation. Bottom-up volume builds across product type and application segments reconciled with top-down macroeconomic indicators.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation modeling incorporated base stock chemistry tier, end-use industry intensity, thermal operating range, and regional regulatory cluster. CAGRs derived from elasticity-adjusted consumption trajectories tied to semiconductor fab capacity additions, electric vehicle production ramps, and data center construction pipelines.
Practitioners should monitor EPA toxicity evaluation outcomes, EU F-Gas Regulation phase-down schedules, and China MIIT standard revisions for early signals. Forecasts reflect assumptions about base oil refinery operating rates and additive package approval timelines. Material shifts in per- and polyfluoroalkyl substance regulatory thresholds or Group III supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Industrial Biocides Market