
 Hydrogenated Bisphenol a Market | 2026-2036
Hydrogenated Bisphenol a Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogenated Bisphenol a Market Outlook
China's Yangtze River Delta is reshaping competitive dynamics in hydrogenated bisphenol A supply as domestic producers expand hydrogenation capacity for specialty epoxy intermediates. New Japan Chemical leverages proprietary catalytic hydrogenation technology to sustain premium positioning in optical-grade resin feedstocks. Maruzen Petrochemical anchors Japanese automotive coating supply chains through backward integration into cyclohexane-derived bisphenol streams. Puyang Huicheng Electronic Materials specializes in high-purity grades for printed circuit board laminators, occupying a defensible niche in semiconductor packaging substrates.
Hydrogenated bisphenol A denotes the fully saturated derivative of bisphenol A wherein the aromatic rings are converted to cyclohexane structures, yielding a hydrogenation degree typically exceeding 99.5% and a melting point range of 120-130°C for the crystalline solid. This molecular transformation eliminates UV-absorbing chromophores, rendering the compound indispensable for outdoor-durable epoxy coatings and alicyclic polycarbonate precursors where optical clarity and weathering resistance are specified. The coatings segment leads absolute volume consumption owing to infrastructure and automotive refinish demand, while the resins category represents the fastest-growing structural pocket as electronics manufacturers specify hydrogenated grades for low-color, high-Tg laminates. Adhesives applications concentrate margin pools in aerospace and medical device bonding where regulatory scrutiny of estrogenic activity drives substitution away from conventional bisphenol A.
EPA oversight under TSCA Section 5 for new chemical notifications and REACH authorization requirements for bisphenol A derivatives in consumer applications are accelerating reformulation timelines across coating and adhesive value chains. China's MEE enforces GB standards for hazardous chemical production that constrain hydrogenation facility siting and emissions profiles, elevating capital thresholds for new entrants. Japan's METI maintains JIS specifications for electronic materials that implicitly favor hydrogenated bisphenol A in high-reliability applications through purity and thermal stability benchmarks. Stakeholders must monitor evolving biocidal product regulations in Europe and accumulating toxicological data packages, as these will determine whether hydrogenated bisphenol A achieves standalone regulatory recognition or remains classified within broader bisphenol A hazard groupings.
Market Dynamics
East Asian epoxy resin formulators are accelerating procurement of hydrogenated bisphenol A as automotive OEMs tighten specifications for weatherable coatings, compressing reformulation timelines across the supply base.
Growth Catalysts
- REACH authorization pressure:ECHA restrictions on conventional bisphenol A in consumer-facing applications redirect European formulation R&D toward saturated alternatives.
- Automotive coating specifications:OEM weatherability standards for exterior refinish systems specify hydrogenated grades to eliminate UV degradation pathways.
- Yangtze River Delta concentration:Specialty resin producers in this Chinese chemical cluster are scaling hydrogenation capacity, lowering procurement costs for regional electronics manufacturers.
Market Restraints
- Purified cyclohexane feedstock volatility:Hydrogenation requires pharmaceutical-grade cyclohexane streams subject to petrochemical pricing swings.
- Japanese supply concentration:Optical-grade hydrogenated bisphenol A production clusters with three integrated petrochemical groups, creating single-source risk for laminators.
- Residual aromatic detection limits:Sub-ppm quantification of unsaturated bisphenol A requires capital-intensive chromatographic infrastructure unavailable to mid-scale compounders.
Strategic Opportunities
- India electronics packaging:BIS certification timelines for high-reliability laminates create first-mover advantage for hydrogenated grade suppliers.
- Medical device adhesive migration:FDA scrutiny of estrogenic activity in conventional bisphenol A opens substitution pathways for surgical bonding applications.
- Aliphatic polycarbonate convergence:Hydrogenated bisphenol A is hybridizing with CO₂-derived carbonate chemistry to produce transparent, weatherable engineering thermoplastics.
Industry Challenges
- Hydrogenation catalyst expertise scarcity:Noble metal catalyst management and poison control require specialized chemical engineering talent concentrated in Japanese and German process licensors.
- GB standard compliance timelines:China's MEE hazardous chemical production permits for new hydrogenation facilities extend 18-24 months, delaying capacity commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogenated Bisphenol a Market |
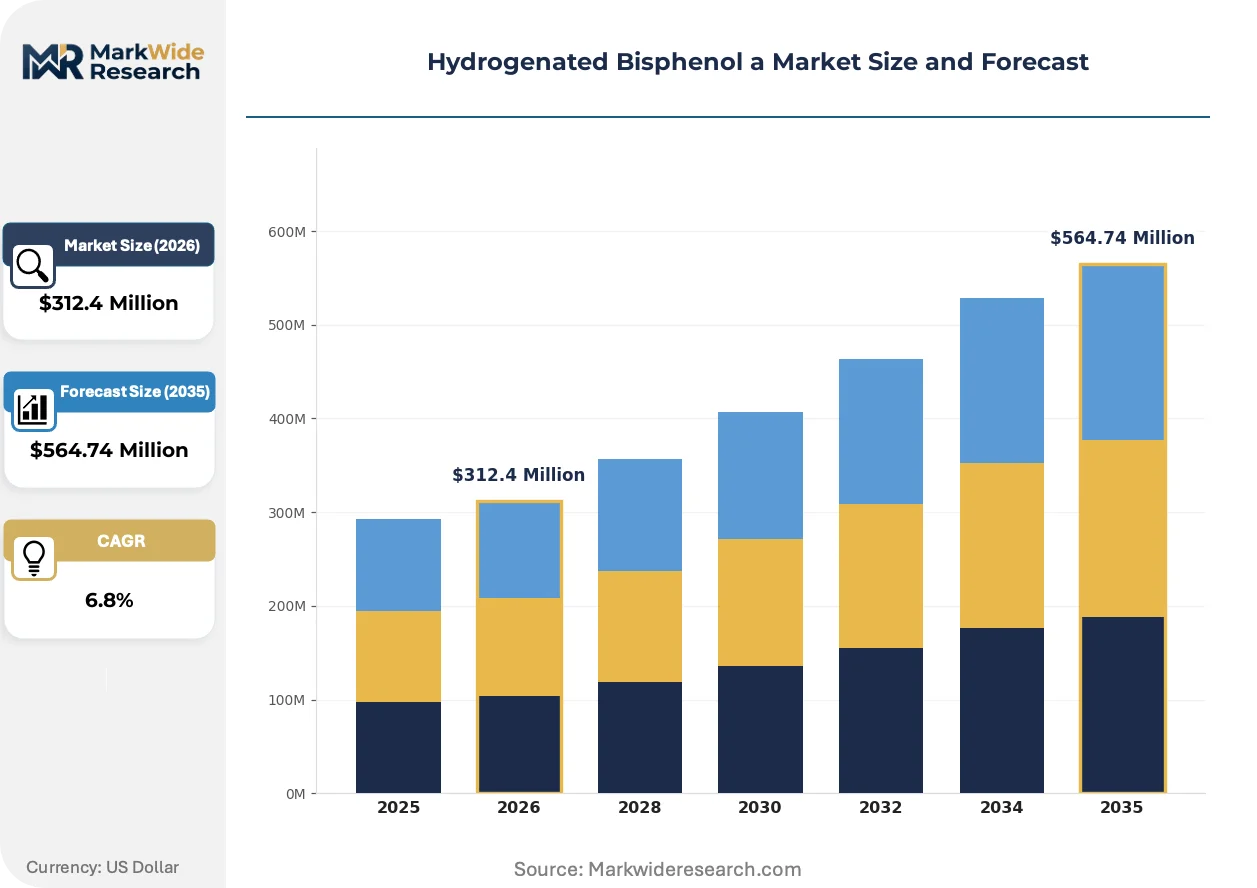
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Resins, Adhesives, Plastics End Use Industry: Automotive, Construction, Electronics, Packaging Application: Protective Coatings, Structural Components, Insulation Materials, Thermal Management Delivery Mode: Liquid, Solid, Powder, Emulsion |
| Companies Covered | New Japan Chemical, Maruzen Petrochemical, Milliken Chemical, Puyang Huicheng Electronic Materials, Yangzhou Baohua Chemical, Hexion, Atul Ltd, Anhui Xinyuan Chemical Co. Ltd, Kukdo Chemicals Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogenated Bisphenol a Market Strategic Shifts
Continuous hydrogenation reactor design is displacing batch processing in new capacity installations, while regulatory data packages on toxicological endpoints accumulate to determine standalone hazard classification.
Membrane-assisted catalytic hydrogenation is hybridizing fixed-bed reactor economics with product purity specifications previously achievable only through crystallization sequences. Electronics-grade resin formulators in South Korea and Taiwan are piloting these units to reduce solvent waste generation. The technology is hybridizing cost structures between commodity hydrogenation and specialty purification, enabling mid-scale producers to contest optical-grade markets.
ECHA's accumulating restriction proposals for bisphenol A derivatives are compressing reformulation windows for coating and adhesive value chains. Manufacturers must submit substitution plans within 24-36 months or secure authorization for continued use. Consumer-facing applications in food contact and children's products face the most severe compliance compression, driving technical service investment.
Specification-driven procurement is consolidating buyer power among tier-one automotive refinish compounders and semiconductor packaging substrate laminators. These buyers now require certificate-of-analysis documentation for every lot, displacing spot-market purchasing for standard grades. The pattern is most pronounced in Japan's Kansai region and China's Jiangsu province, where integrated coating and electronics clusters dominate consumption.
Hydrogenated Bisphenol a Market Segmentation
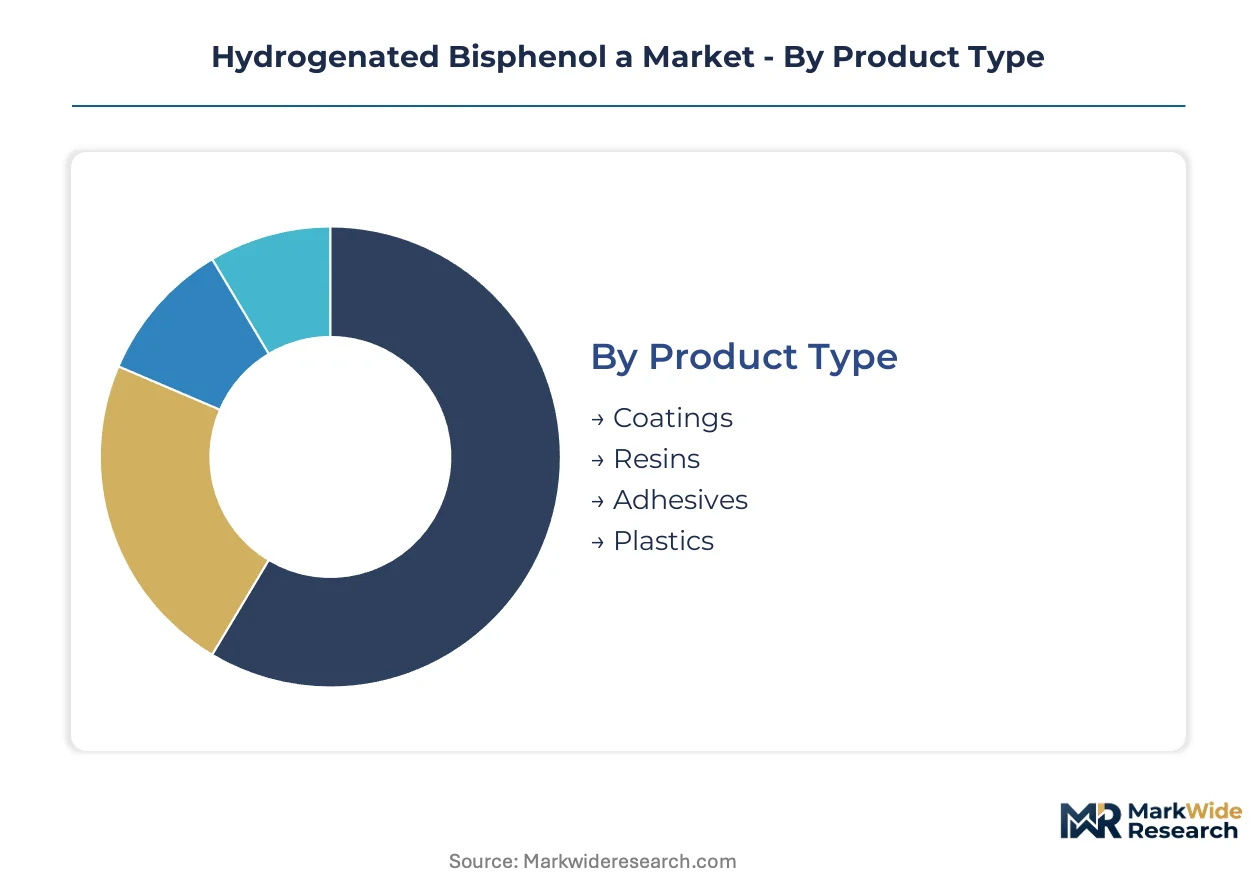
Hydrogenated bisphenol A procurement patterns diverge sharply across end-use specifications, with automotive coating compounders demanding certificate-of-analysis documentation while electronics laminators prioritize sub-ppm aromatic detection limits. Understanding these segment boundaries clarifies where formulation R&D investments concentrate and which purity grades command sustained premium positioning.
Product Type:
Application functionality determines cost tier and margin structure across the four product categories, with optical-grade specifications separating premium positioning from commodity hydrogenation outputs.
- Coatings:Exterior-durable epoxy systems for automotive refinish and infrastructure protection specify hydrogenated grades to eliminate UV degradation pathways through saturated cyclohexane ring structures. Demand concentrates with tier-one automotive compounders in Japan's Kansai region and China's Jiangsu province, where OEM weatherability standards compress reformulation timelines.
- Resins:High-Tg laminates for semiconductor packaging substrates require hydrogenation degrees exceeding 99.5% with melting point ranges of 120-130°C. Electronics manufacturers in South Korea and Taiwan are piloting membrane-assisted catalytic hydrogenation to reduce solvent waste while meeting JIS specifications for thermal stability.
- Adhesives:Surgical bonding and aerospace applications leverage the absence of estrogenic activity to satisfy FDA and EMA scrutiny of conventional bisphenol A.
- Plastics:Aliphatic polycarbonate precursors hybridize with CO₂-derived carbonate chemistry for transparent engineering thermoplastics.
Coatings commands the established base. The steepest expansion runs through resins.
End Use Industry:
Customer type and regulatory exposure create divergent procurement behaviors across these four industrial verticals, with consumer-facing applications facing the most severe compliance compression.
- Automotive:OEM specifications for exterior refinish systems drive specification-driven procurement consolidation among refinish compounders. REACH authorization pressure on conventional bisphenol A redirects European formulation R&D, while China's Yangtze River Delta specialty resin producers scale hydrogenation capacity to serve domestic automotive supply chains.
- Electronics:Printed circuit board laminators and semiconductor packaging substrate manufacturers occupy the fastest-climbing demand trajectory. Puyang Huicheng Electronic Materials and comparable specialists defend high-purity niches through backward integration into cyclohexane-derived feedstocks.
- Construction:Infrastructure protective coatings specify weatherable epoxies for bridge and marine applications where UV resistance extends maintenance intervals.
- Packaging:Food contact and children's product applications face ECHA restriction proposals with 24-36 month substitution timelines.
Automotive anchors current procurement volumes. Electronics gains share fastest.
Application:
Volume concentration and technical performance requirements segment these four application modes, with thermal and environmental stress resistance determining grade specification.
- Protective Coatings:Marine, industrial, and automotive exterior systems specify hydrogenated bisphenol A to prevent UV-induced yellowing and embrittlement. Procurement concentrates with integrated coating clusters in China's Jiangsu province and Japan's Kansai region.
- Structural Components:Load-bearing epoxy composites for aerospace and wind energy applications leverage the saturated molecular structure for hydrolytic stability.
- Insulation Materials:Electrical laminates and potting compounds for high-reliability electronics require low-color, high-purity grades with controlled ionic contamination.
- Thermal Management:Heat-dissipating adhesives and encapsulants for power electronics utilize hydrogenated grades for thermal oxidative stability.
Protective coatings maintains the volume base. Thermal management shows the steepest trajectory.
Delivery Mode:
Supply chain configuration and customer formulation infrastructure determine which physical form factors dominate procurement, with liquid and solid grades serving distinct compounding workflows.
- Liquid:Pre-dissolved solutions in reactive diluents enable direct incorporation into coating and adhesive formulations without melting infrastructure. Preferred by mid-scale compounders lacking heated processing equipment.
- Solid:Crystalline flakes with defined melting point ranges support controlled addition to hot-melt and extrusion processes. Standard for electronics-grade resin production.
- Powder:Micronized grades for powder coating applications where electrostatic spray deposition requires specific particle size distributions.
- Emulsion:Aqueous dispersions for waterborne coating systems meeting VOC regulations in Europe and North America.
Solid forms command the established base. Liquid delivery climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port complex underwrites China's dominance in hydrogenated bisphenol A supply chains, handling cyclohexane feedstock imports and specialty resin exports for East Asian electronics and automotive coating manufacturers.
China
Specialty resin producers in Jiangsu province are scaling hydrogenation capacity to serve domestic automotive OEMs and semiconductor packaging substrate laminators. MEE enforcement of GB standards for hazardous chemical production constrains new facility siting, elevating capital thresholds for entrants. The Yangtze River Delta chemical cluster concentrates backward-integrated producers supplying high-purity grades to South Korean and Taiwanese electronics manufacturers.
Japan
Integrated petrochemical groups in the Kansai region anchor optical-grade hydrogenated bisphenol A production for printed circuit board laminators and automotive refinish compounders. METI maintains JIS specifications for electronic materials that implicitly favor hydrogenated grades through purity and thermal stability benchmarks. Three petrochemical groups control optical-grade output, creating single-source procurement risk for laminators.
South Korea
Electronics-grade resin formulators in the Seoul Capital Area are piloting membrane-assisted catalytic hydrogenation to reduce solvent waste while meeting thermal stability requirements for high-Tg laminates. The country's national environmental regulator enforces emissions standards that accelerate continuous reactor adoption over batch processing. Busan-Ulsan petrochemical complexes supply cyclohexane-derived feedstocks to domestic specialty chemical producers.
Germany
Automotive refinish compounders in North Rhine-Westphalia are redirecting formulation R&D toward saturated bisphenol A alternatives under REACH authorization pressure on conventional bisphenol A. ECHA restriction proposals compress substitution timelines to 24-36 months for consumer-facing coating applications. The country's chemical regulator coordinates with industry associations on toxicological data packages for standalone hazard classification.
United States
Epoxy resin formulators in the Gulf Coast petrochemical corridor are expanding procurement of hydrogenated grades to meet automotive OEM weatherability specifications for exterior coating systems. EPA oversight under TSCA Section 5 governs new chemical notifications for hydrogenated bisphenol A derivatives in adhesive and coating applications. Texas-Louisiana chemical clusters import pharmaceutical-grade cyclohexane feedstocks subject to petrochemical pricing volatility.
Hydrogenated Bisphenol a Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, anchoring feedstock and intermediate supply. The vendor base stratifies across three tiers: integrated petrochemical groups with captive hydrogenation capacity, specialty resin producers with backward integration into cyclohexane streams, and formulation-focused compounders reliant on merchant supply. Strategic moves concentrate on capacity expansion in China's Yangtze River Delta and technology licensing for continuous hydrogenation reactor designs.
Among Japanese integrated producers, New Japan Chemical and Maruzen Petrochemical exemplify the premium-tier archetype through proprietary catalytic hydrogenation positioning. Puyang Huicheng Electronic Materials occupies a defensible niche among Chinese specialists, representing the mid-scale purity-grade segment serving semiconductor packaging substrate laminators. These three anchors illustrate how geographic concentration and feedstock integration separate premium positioning from commodity hydrogenation outputs.
| Leading Market Players |
|---|
| New Japan Chemical |
| Maruzen Petrochemical |
| Milliken Chemical |
| Puyang Huicheng Electronic Materials |
| Yangzhou Baohua Chemical |
| Hexion |
| Atul Ltd |
| Anhui Xinyuan Chemical Co. Ltd |
| Kukdo Chemicals Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta chemical cluster's hydrogenation capacity expansion is compressing procurement costs for regional electronics manufacturers while concentrating pricing power among backward-integrated specialty resin producers. This geographic supply concentration enables tier-one automotive compounders in Japan's Kansai region to enforce certificate-of-analysis documentation requirements that sustain premium-grade price premiums.
Pricing Analysis
Three-tier pricing structure across optical-grade, electronics-grade, and industrial-grade levels separates premium positioning from commodity hydrogenation outputs. Price differentiation rests on hydrogenation degree certification and sub-ppm aromatic detection limits, with optical-grade specifications commanding sustained premiums. Cost compression in industrial-grade tiers is intensifying because purified cyclohexane feedstock volatility transmits directly through to compounder margins. Electronics laminators in South Korea and Taiwan exhibit the lowest price sensitivity due to JIS specification compliance requirements, while mid-scale coating compounders in China's interior provinces face acute procurement cost pressure.
Supply Chain Analysis
Single-source vulnerability for optical-grade production concentrates with three integrated Japanese petrochemical groups in the Kansai region. Feedstock supply draws from pharmaceutical-grade cyclohexane streams sourced from Busan-Ulsan complexes in South Korea, Texas-Louisiana corridors in the United States, and domestic Chinese hydrogenation facilities. Tariff exposure between China and key electronics manufacturing destinations in Southeast Asia is elevating logistics cost uncertainty for Yangtze River Delta exporters. Distribution runs through specialty chemical distributors serving tier-one automotive refinish compounders and semiconductor packaging substrate laminators with lot-traceable documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogenated bisphenol A procurement is accelerating as REACH authorization pressure on conventional bisphenol A compresses European reformulation timelines to 24-36 months. This regulatory inflection creates structural demand displacement toward saturated alternatives across coating and adhesive value chains.
For Market Incumbents: Build catalytic hydrogenation expertise moats through proprietary noble metal catalyst management protocols and poison control systems. Expand membrane-assisted continuous reactor capacity in the Yangtze River Delta to capture electronics-grade demand from South Korean and Taiwanese laminators. Secure long-term offtake agreements with tier-one automotive compounders before new Chinese entrants achieve optical-grade purity thresholds. For New Entrants and Emerging Players: Establish a beachhead in India's electronics packaging substrate segment ahead of BIS certification timeline completion for high-reliability laminates. Target medical device adhesive applications where FDA scrutiny of estrogenic activity in conventional bisphenol A opens substitution pathways for surgical bonding. Lead with aqueous emulsion delivery formats for waterborne coating systems meeting European VOC regulations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty resin producers with backward integration into cyclohexane-derived feedstocks and demonstrated sub-ppm aromatic detection capabilities. The 5-10 year viability window rewards acquisition targets holding proprietary continuous hydrogenation reactor licenses from Japanese or German process licensors. Monitor ECHA toxicological data package accumulation as the signal indicating whether hydrogenated bisphenol A achieves standalone regulatory recognition or remains classified within broader bisphenol A hazard groupings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclohexane Feedstocks | Captive supply of pharmaceutical-grade cyclohexane insulates margin compression from petrochemical pricing volatility. |
| Membrane-Assisted Catalytic Hydrogenation Scale-Up | Continuous reactor adoption reduces solvent waste generation while meeting JIS thermal stability specifications for electronics-grade output. |
| Optical-Grade Certification Investment | Sub-ppm aromatic detection infrastructure enables premium positioning in semiconductor packaging substrate laminator supply chains. |
| Long-Term Supply Agreement with Automotive OEMs | Contract-based procurement consolidation displaces spot-market purchasing among tier-one refinish compounders in Japan's Kansai region. |
| Joint Venture for China Capacity Expansion | Partnership with Jiangsu province specialty resin producers navigates MEE hazardous chemical production permit timelines. |
Study Parameters
Cross-validation between primary interviews with hydrogenation plant managers, epoxy resin procurement leads at automotive OEMs, and specialty chemical distribution channel partners anchors the qualitative findings. Secondary validation draws from customs and trade data tracking cyclohexane feedstock flows, ACC and Cefic industry reports on epoxy resin formulation trends, and SEC 10-K filings from listed petrochemical groups. Bottom-up capacity assessments from the Yangtze River Delta, Kansai region, and Busan-Ulsan complexes were triangulated against top-down demand estimates from electronics and automotive end-use segments.
Calibration against historical hydrogenation capacity commissioning timelines and regulatory authorization milestones shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hydrogenation grade tier, end-use industry vertical, physical delivery mode, and regional production hub clustering. CAGRs were derived through iterative reconciliation of supply-side capacity expansion announcements with demand-side specification-driven procurement patterns, incorporating membrane-assisted reactor technology adoption curves and REACH substitution timeline assumptions as industry-specific forecast inputs.
Sensitivities concentrate around ECHA standalone hazard classification outcomes, MEE hazardous chemical production permit approval velocities, and cyclohexane feedstock pricing volatility transmission to downstream compounders. Forecasts reflect documented assumptions regarding continuous reactor technology diffusion rates and automotive OEM weatherability specification tightening trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Quenching Fluids and Salts Market