
 Co-Polymer Sealants Market | 2026-2036
Co-Polymer Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Polymer Sealants Market Analysis
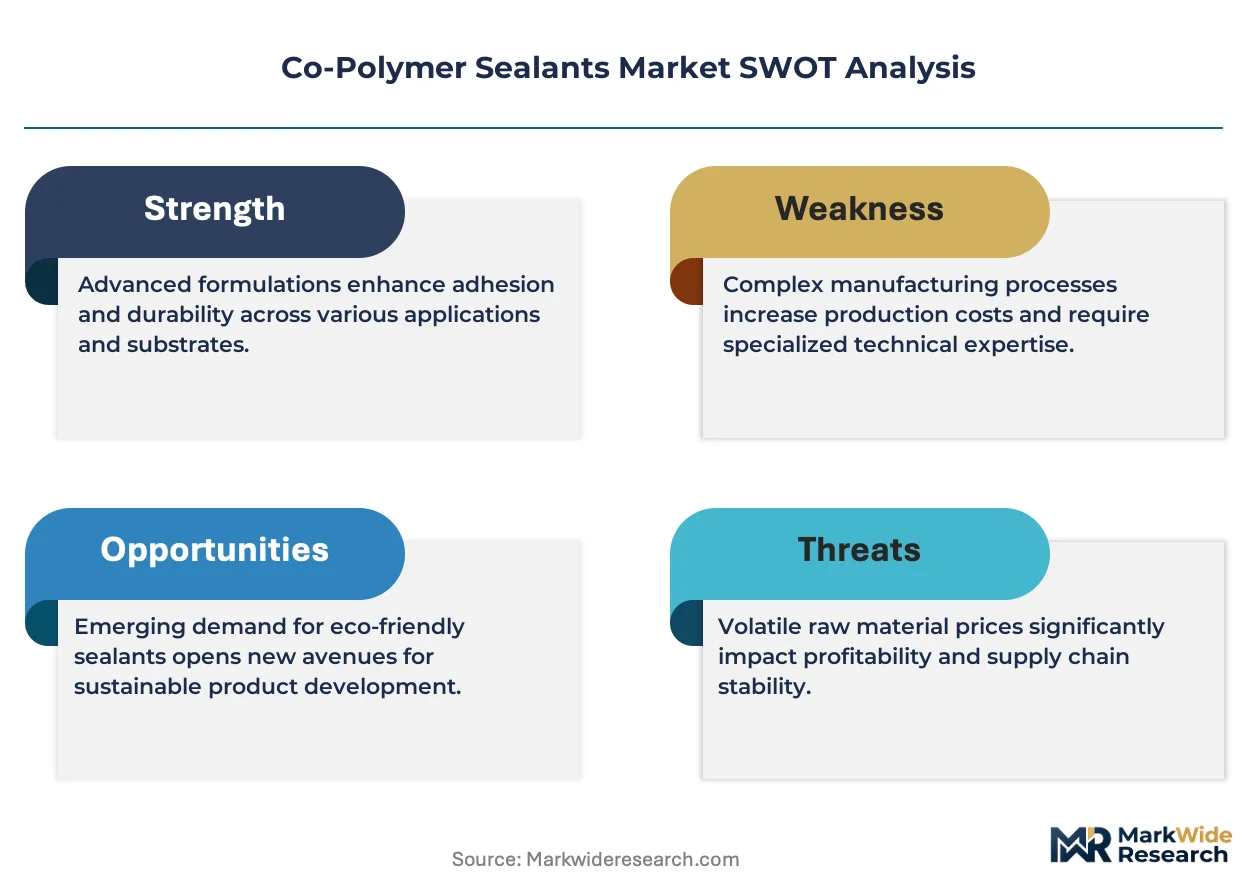
The EU Green Deal is broadening performance requirements for construction-grade sealants across member states. BASF SE leverages its integrated polymer feedstock position to supply reactive co-polymer systems for high-performance joints. Dow anchors its presence through hot melt technologies serving automotive assembly lines in North America and Europe. Sika AG specializes in construction applications, sustaining margin pools through specification-grade products for commercial building envelopes.
Co-polymer sealants combine two or more distinct monomer units—typically acrylic, polyurethane, or silicone backbones—into a single polymer chain, yielding tailored adhesion, elasticity, and chemical resistance profiles. Manufacturers extrude or compound these materials with fillers, plasticizers, and curing agents to achieve Shore A hardness values between 15 and 50 for construction joints and automotive seam sealing. Water-based formulations lead volume in residential construction due to lower VOC emissions and simplified cleanup protocols, while reactive systems command premium positioning in aerospace and marine applications where cure speed and environmental durability determine specification. Hot melt co-polymer adhesives represent the fastest-growing form factor, displacing mechanical fasteners in automotive interior assembly and appliance manufacturing.
REACH registration requirements in Europe and EPA VOC regulations in the United States constrain solvent-based product lines while creating compliance-driven demand for certified low-emission alternatives. China's GB standards and MEE enforcement protocols are tightening similarly, reshaping export qualification requirements for multinational suppliers. ISO 11600 classification for building construction sealants provides the cross-border technical baseline that buyers reference in procurement specifications. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent certification timelines could fragment product development roadmaps and regional inventory strategies.
Market Dynamics
Automotive OEMs are consolidating fastener replacement programs with hot melt co-polymer systems, compressing specification cycles from 18 months to 8 months and forcing raw material suppliers to pre-qualify formulations against multiple OEM platforms simultaneously. This demand compression is reshaping R&D prioritization across the value chain.
Growth Catalysts
- EU Green Deal construction mandates:Member states are expanding performance requirements for building envelope sealants, creating specification-grade demand for low-VOC co-polymer systems in commercial retrofits.
- Hot melt automotive assembly:Interior trim manufacturers are displacing mechanical clips with reactive co-polymer adhesives, reducing part count and enabling lighter vehicle architectures.
- China's eastern manufacturing belt:Petrochemical clusters in Jiangsu and Zhejiang provinces are achieving backward integration into acrylic monomer production, shortening feedstock lead times for sealant compounders.
Market Restraints
- Propylene oxide supply volatility:Polyurethane backbone production depends on this intermediate, with price swings exceeding 40% annually disrupting margin planning for mid-tier formulators.
- REACH registration cost barriers:Small European compounders face six-figure compliance expenditures for novel monomer substances, consolidating innovation capacity among integrated feedstock producers.
- Silicone hybrid substitution:Advanced silicone-acrylic hybrids are capturing specification share in high-elongation construction joints above 25% movement capability.
Strategic Opportunities
- India's infrastructure buildout:Metro rail and airport expansion projects in Maharashtra and Karnataka are specifying imported co-polymer joint systems for seismic-rated structures.
- Waterborne aerospace primers:Dual-cure polyurethane-acrylic systems are penetrating military airframe maintenance depots seeking chromate-free corrosion protection.
- GB standard harmonization:China's alignment of VOC test methods with ISO 11600 is reducing re-certification costs for multinational suppliers serving domestic and export markets simultaneously.
Industry Challenges
- Formulation chemist scarcity:Experienced professionals capable of balancing Shore A hardness with adhesion promoter compatibility are concentrated among retirees and competitors, inflating compensation 15-20% above materials science norms.
- Multi-jurisdiction certification lag:Simultaneous EPA, REACH, and GB standard approvals extend product launch timelines 14-22 months, straining working capital for specialty product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Polymer Sealants Market |
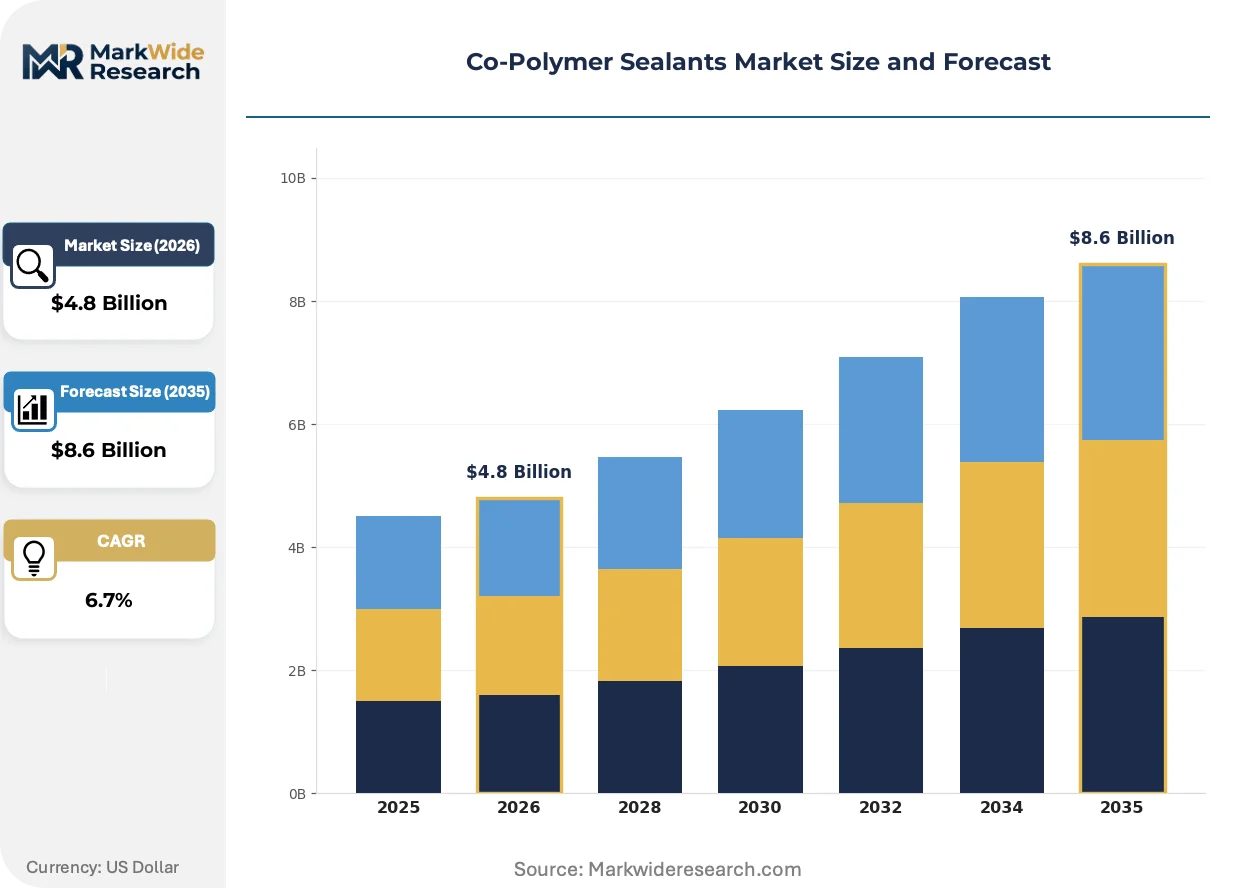
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Construction, Automotive, Marine, Aerospace End User: Contractors, Manufacturers, DIY Users, Fabricators Form: Caulk, Adhesive, Tape, Tube |
| Companies Covered | BASF SE, Dow, Henkel AG, Evonik, Bostik, Ashland Global Holdings Inc., Sika AG, H.B. Fuller Company, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Polymer Sealants Market Emerging Trajectories
Formulation science is converging with digital specification tools, compressing the path from lab bench to approved vendor list while fragmenting procurement authority across engineering, sustainability, and purchasing functions.
Reactive hot melt co-polymer systems combining polyurethane backbone with acrylic functionality are modularizing automotive interior assembly workflows. Tier-1 suppliers are adopting these materials for instrument panel lamination and headliner attachment, eliminating clamp fixtures and reducing work-in-process inventory. The technology is modularizing production line layouts, enabling reconfigurable manufacturing cells that switch between vehicle platforms within shift changes.
EPA VOC regulations under 40 CFR 59 are tightening solvent-based product lines in architectural sealant categories, forcing reformulation toward waterborne and 100% solids systems. Manufacturers serving the US market are investing in reactive extrusion equipment to produce moisture-cure products exempt from VOC calculations. Construction-grade polyurethane sealants face the steepest compliance burden, with several state-level air districts proposing thresholds below federal minimums.
Specification authority is migrating from general contractors to envelope consultants and commissioning agents, fragmenting traditional distribution relationships. Building owners in Germany's industrial corridor now require third-party EPD verification and ISO 14001 certification from sealant suppliers before shortlisting. This credential stacking favors integrated manufacturers with captive life-cycle assessment capabilities over regional compounders dependent on external certification bodies.
Co-Polymer Sealants Market Segmentation
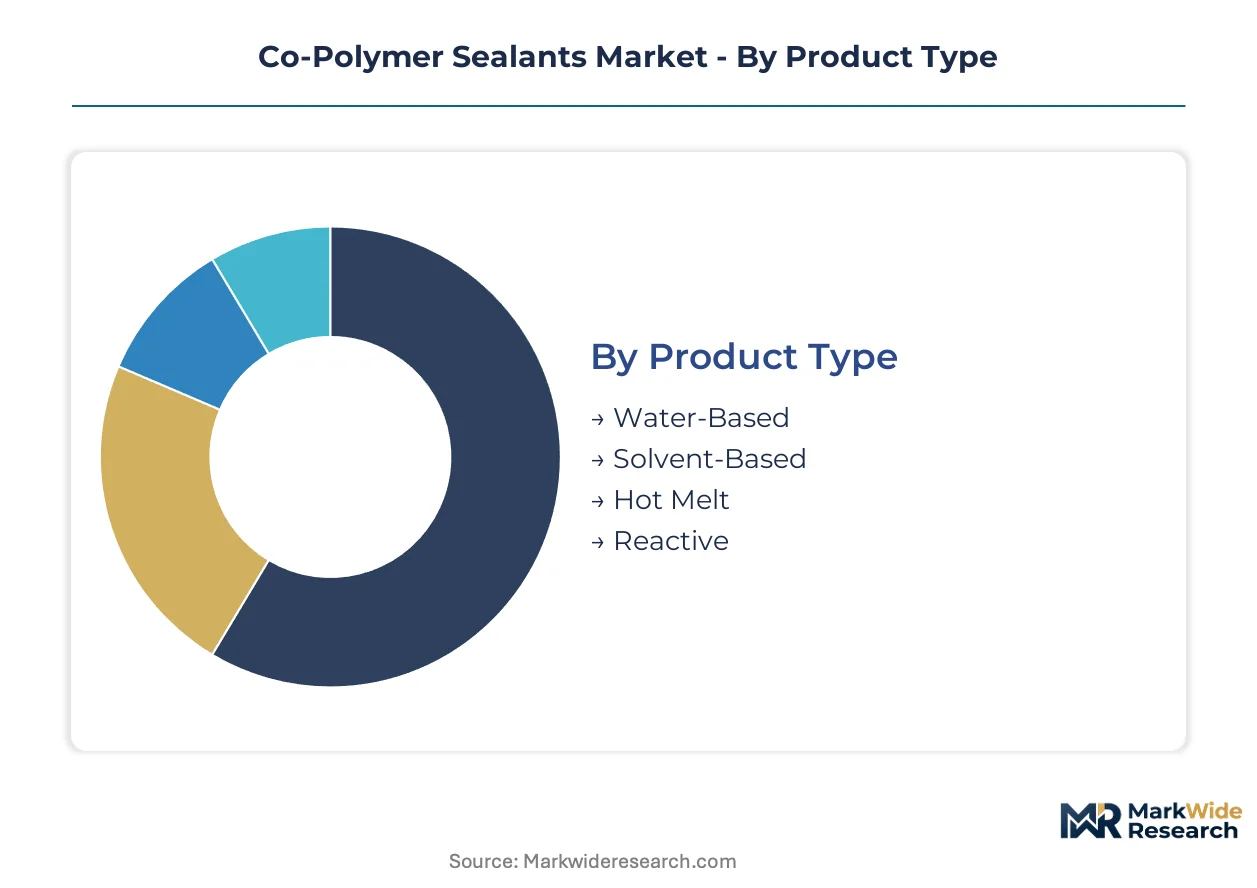
Co-polymer sealant buyers fragment across formulation chemistry, cure mechanism, and delivery format. Specification authority migrates differently across construction, automotive, and industrial channels, demanding parallel segmentation logic.
Product Type:
Cost tier separates specification-grade buyers from volume purchasers in this category.
- Water-Based:Acrylic and polyurethane dispersions dominate residential construction with sub-50 g/L VOC profiles. Demand concentrates in Germany's industrial corridor where EU Green Deal mandates accelerate solvent displacement in commercial retrofits.
- Hot Melt:Reactive polyurethane systems cure through atmospheric moisture, enabling fixture-free automotive interior assembly. OEM specification cycles compress from 18 months to 8 months as Tier-1 suppliers displace mechanical clips in instrument panel lamination.
- Solvent-Based:Higher solids formulations retain niche positioning in marine and aerospace applications where environmental durability trumps emission thresholds.
- Reactive:Two-component systems command premium positioning in seismic-rated construction joints and military airframe maintenance depots.
Water-based formulations lead volumes today; hot melt systems are gaining share fastest.
Application:
End-use maturity determines margin pool depth and specification cycle length.
- Construction:Building envelope sealants face ISO 11600 classification requirements and third-party EPD verification demands from German building owners. Specification authority has migrated from general contractors to envelope consultants.
- Automotive:Interior trim manufacturers adopt hot melt co-polymers for headliner attachment and carpet bonding, reducing part count while enabling lighter vehicle architectures.
- Marine:Saltwater immersion resistance requirements favor silicone-polyurethane hybrids in hull sealing and deck caulking applications.
- Aerospace:Dual-cure polyurethane-acrylic primers penetrate military maintenance depots seeking chromate-free corrosion protection under REACH and EPA constraints.
Construction commands the largest revenue pool; automotive applications show the steepest expansion trajectory.
End User:
Procurement sophistication separates professional specifiers from price-sensitive volume buyers.
- Contractors:Commercial envelope specialists require certified low-emission alternatives with documented compliance against REACH, EPA, and converging GB standards.
- Manufacturers:Automotive OEMs and Tier-1 suppliers consolidate adhesive portfolios while demanding simultaneous pre-qualification across multiple platforms.
- DIY Users:Retail channel purchasers prioritize simplified cleanup protocols and lower odor profiles in residential repair and renovation.
- Fabricators:Custom assembly operations source specification-grade reactive systems for seismic-rated joints in India's metro rail and airport infrastructure.
Manufacturers drive premium pricing; contractors anchor volume throughput.
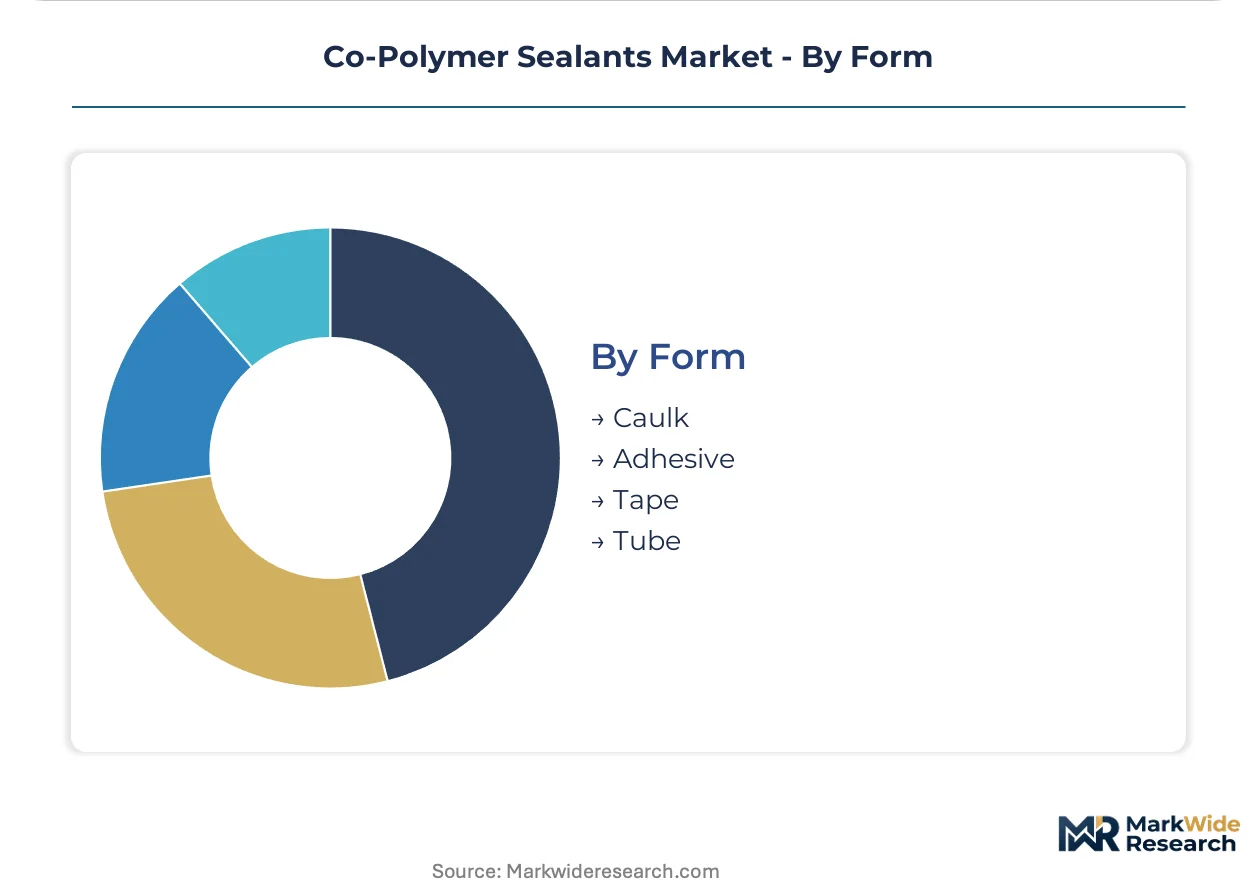
Form:
Delivery format dictates application equipment requirements and skilled labor intensity.
- Caulk:Gun-applied cartridges dominate residential construction and DIY renovation with Shore A hardness calibrated between 15 and 50 for joint movement accommodation.
- Adhesive:Reactive hot melt systems in pellet and slug formats feed automated dispensing equipment on automotive assembly lines.
- Tape:Pre-formed butyl and acrylic tapes serve glazing and HVAC duct sealing applications where consistent bead geometry matters.
- Tube:Squeeze tubes target small-batch maintenance and repair operations across marine and aerospace aftermarket channels.
Caulk formats lead unit volumes; adhesive forms climb the fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with polyurethane-acrylic expertise concentrate in Germany's industrial corridor, China's eastern petrochemical belt, and the US Gulf Coast, anchoring regional innovation capacity.
Germany
Commercial envelope retrofits and automotive OEM specification programs drive demand for low-VOC reactive systems. REACH registration administered by ECHA constrains novel monomer introductions while favoring incumbents with existing dossiers. The Rhine-Ruhr industrial corridor hosts integrated polymer producers supplying construction-grade sealants to specification-grade buyers.
United States
Hot melt adhesive adoption in automotive interior assembly and appliance manufacturing compresses qualification cycles. EPA regulations under 40 CFR 59 tighten solvent-based architectural sealant categories, forcing reformulation investments. The Gulf Coast petrochemical hub in Texas and Louisiana provides captive propylene oxide feedstock for polyurethane backbone production.
China
Metro rail infrastructure in eastern provinces and export-oriented manufacturing create dual demand streams for seismic-rated joint systems. GB standards alignment with ISO 11600 by MEE reduces re-certification costs for multinational suppliers. Jiangsu and Zhejiang petrochemical clusters achieve backward integration into acrylic monomer production.
India
Airport expansion in Maharashtra and Karnataka alongside metro rail projects specifies imported co-polymer systems for structural joints. BIS certification requirements for construction chemicals create compliance barriers for uncertified imports. Mumbai-Pune industrial corridor fabricators source specification-grade reactive systems for seismic-rated applications.
Co-Polymer Sealants Market Vendor Landscape
Capital-heavy producers with integrated polymer feedstock positions compete with asset-light formulators dependent on merchant resin supply, creating a tiered structure where backward integration determines margin sustainability. The vendor base concentrates among diversified chemical conglomerates, construction specialty chemical houses, and adhesive-focused mid-caps. Three archetypes dominate: integrated feedstock producers, specification-grade construction specialists, and automotive assembly solution providers. Competitive moves center on reactive extrusion capacity expansion and simultaneous multi-OEM platform pre-qualification.
Within the integrated feedstock tier, BASF SE and Dow exemplify capital-heavy positioning through captive polymer production. Sika AG occupies a position among construction specialty houses with specification-grade focus. These three entities represent the dominant competitive anchors across formulation chemistry, cure mechanism, and end-use application vectors.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Henkel AG |
| Evonik |
| Bostik |
| Ashland Global Holdings Inc. |
| Sika AG |
| H.B. Fuller Company |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders in Germany's industrial corridor anchor pricing discipline through captive distribution networks and long-term specification relationships with envelope consultants. Their ownership structure insulates margin pools from quarterly earnings pressure while enabling patient investment in REACH-compliant formulation pipelines.
Pricing Analysis
Bundled technical service and unbundled commodity supply split the market into divergent pricing regimes. Three-tier pricing structure across specification-grade, certified-standard, and economy-level formulations separates procurement channels. Price differentiation centers on ISO 11600 certification tier and after-sales application support. Cost compression in water-based residential segments intensifies because Chinese acrylic monomer capacity expansion feeds oversupply. DIY retail purchasers exhibit highest price sensitivity; seismic-rated infrastructure fabricators show least.
Supply Chain Analysis
Formulation chemist scarcity in Jiangsu province and the Rhine-Ruhr corridor constrains batch scheduling flexibility for reactive system producers. Supply concentrates in Germany, China, and the United States, with propylene oxide and acrylic acid as critical backbone inputs. The chain rests on single-source vulnerability for specialized adhesion promoters. Distribution runs through construction chemical distributors and direct automotive Tier-1 supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EU Green Deal mandates and REACH enforcement shift procurement toward premium low-VOC specification grades with documented EPD verification.
For Market Incumbents: Extend reactive extrusion capacity in the US Gulf Coast and Rhine-Ruhr corridors to capture automotive platform consolidation demand. Deepen backward integration into acrylic monomer production in China's eastern petrochemical belt. Silicone-acrylic hybrid substitution threatens polyurethane share in high-elongation joints; counter with accelerated dual-cure polyurethane-acrylic R&D programs. For New Entrants and Emerging Players: Waterborne aerospace primer technology offers a technology-first wedge into military maintenance depot supply chains currently served by legacy chromate systems. India's metro rail and airport infrastructure in Maharashtra and Karnataka presents the most penetrable geography for specification-grade reactive joint systems. Pursue BIS certification partnerships with established construction chemical distributors to bypass direct regulatory navigation. For Investors and Strategic Acquirers: Construction specialty chemical houses are the most active acquirer in this space, seeking specification-grade margin pools in commercial envelope retrofits. Five-to-ten-year viability hinges on captive life-cycle assessment capabilities and ISO 14001 credential stacking. Monitor GB standard harmonization progress with ISO 11600 as the inflection signal for multinational supplier margin expansion in China's domestic market.| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Extrusion Capacity Expansion | Enables moisture-cure product lines exempt from EPA 40 CFR 59 VOC calculations. |
| Backward Integration into Acrylic Monomer | Jiangsu and Zhejiang petrochemical clusters shorten feedstock lead times for sealant compounders. |
| EPD Verification and ISO 14001 Certification | German building owners now require credential stacking before shortlisting suppliers. |
| Dual-Cure Polyurethane-Acrylic R&D | Military airframe maintenance depots seek chromate-free corrosion protection under REACH constraints. |
| BIS Certification Partnership | Construction chemical distributors in India provide compliance pathway for imported seismic-rated systems. |
Methodological Framework
Coverage spans Germany, the United States, China, and India, with primary inputs from each market through structured interviews with plant managers at integrated polymer producers, procurement leads at automotive OEMs and Tier-1 suppliers, distribution channel partners in construction chemicals, and technical R&D directors at specialty sealant compounders. Secondary validation draws from ECHA REACH registration databases, EPA 40 CFR 59 regulatory filings, Chinese MEE GB standard publications, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume modeling triangulates against top-down demand aggregation across end-use applications.
Granularity-level framing applies country-level modeling for regulatory divergence effects, segment-level disaggregation across water-based, hot melt, solvent-based, and reactive chemistries, and end-use resolution distinguishing construction envelope, automotive assembly, marine, and aerospace channels. CAGRs derive from segmented volume projections and value-per-unit assumptions tied to formulation complexity tiers. Industry-specific forecast inputs include automotive OEM platform consolidation timelines and EU Green Deal implementation schedules across member states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propylene oxide price volatility, REACH registration cost escalation for novel monomers, and regulatory divergence between EPA, ECHA, and MEE certification timelines. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market