
 Di (2-Ethylhexyl) Phthalate Market | 2026-2036
Di (2-Ethylhexyl) Phthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Di (2-Ethylhexyl) Phthalate Market Outlook
Market Context with Strategic Players
The split between premium-grade phthalate esters and commodity plasticizers is shifting as regulatory thresholds tighten across major economies. BASF SE leverages its integrated oxo-alcohol chain to sustain cost discipline in high-purity grades. Eastman Chemical Company differentiates through non-phthalate alternatives while maintaining DEHP capacity for exempted industrial segments. ExxonMobil Corporation anchors volume positions in Asia-Pacific through its Singapore and Texas Gulf Coast manufacturing complexes.
Technical Definition and Structural Segments
Di (2-ethylhexyl) phthalate, commonly abbreviated DEHP, is a colorless viscous liquid plasticizer produced by esterifying phthalic anhydride with 2-ethylhexanol; it imparts flexibility and durability to polyvinyl chloride formulations at loadings typically ranging from 30 to 50 percent by weight. The plasticizers segment dominates value capture given its indispensability in flexible PVC compounding, while the flooring application grows fastest as commercial construction rebounds and resilient surface demand intensifies. Distribution through direct sales channels controls the margin pool for bulk industrial buyers, though distributors occupy critical positions in fragmented regional markets where logistics integration determines contract viability.
Regulatory Framework and Forward Outlook
REACH in Europe and EPA risk evaluations in the United States are reshaping permissible DEHP concentrations in consumer-facing goods, with ECHA classifying the substance as a substance of very high concern for endocrine disruption and reproductive toxicity. China's MEE enforces emission standards on phthalate manufacturing facilities under its dual carbon policy framework, while India's BIS certification requirements for plasticizer purity create non-tariff barriers for unqualified imports. Stakeholders must monitor regulatory divergence between jurisdictions that maintain industrial exemptions versus those accelerating phase-out timelines, as this split will determine where legacy capacity retains economic viability and where conversion investments become unavoidable.
Market Dynamics
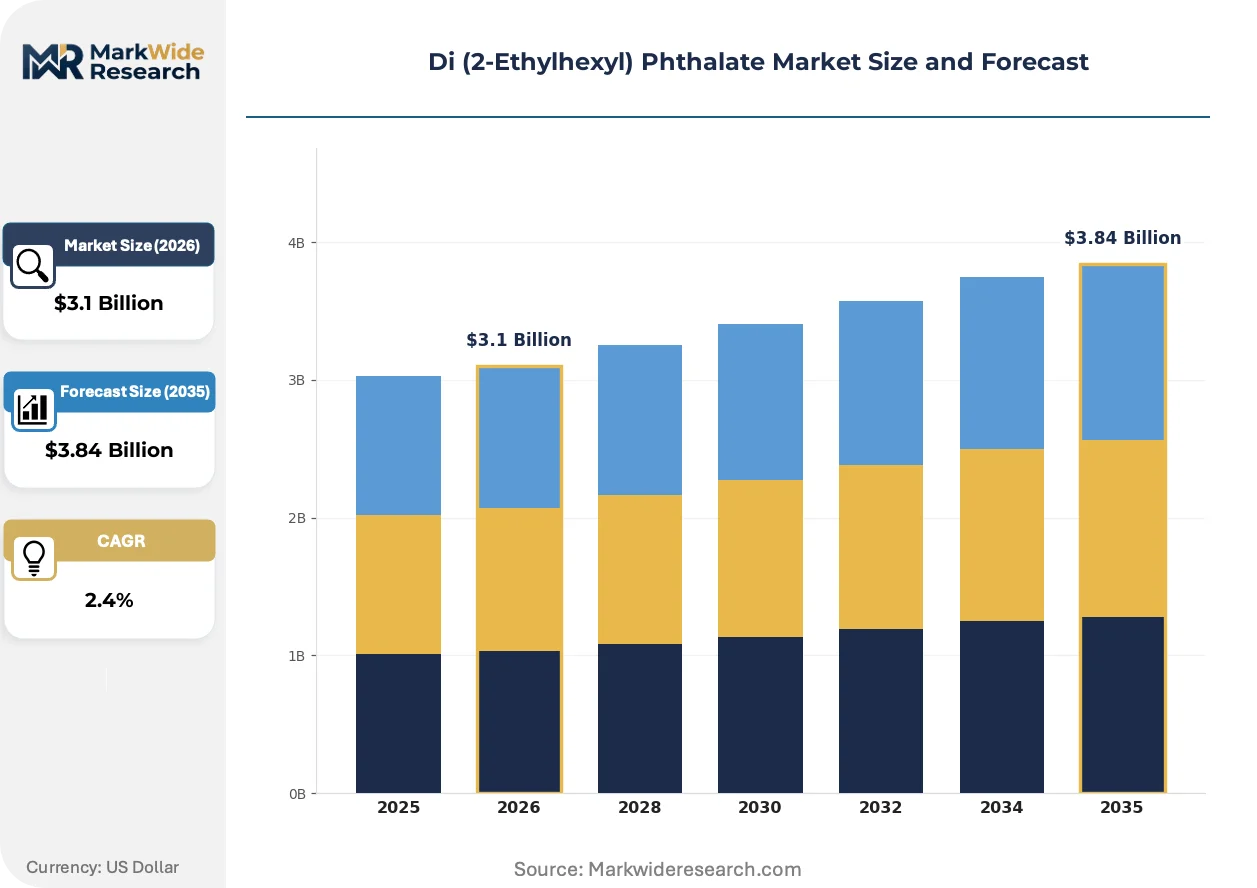
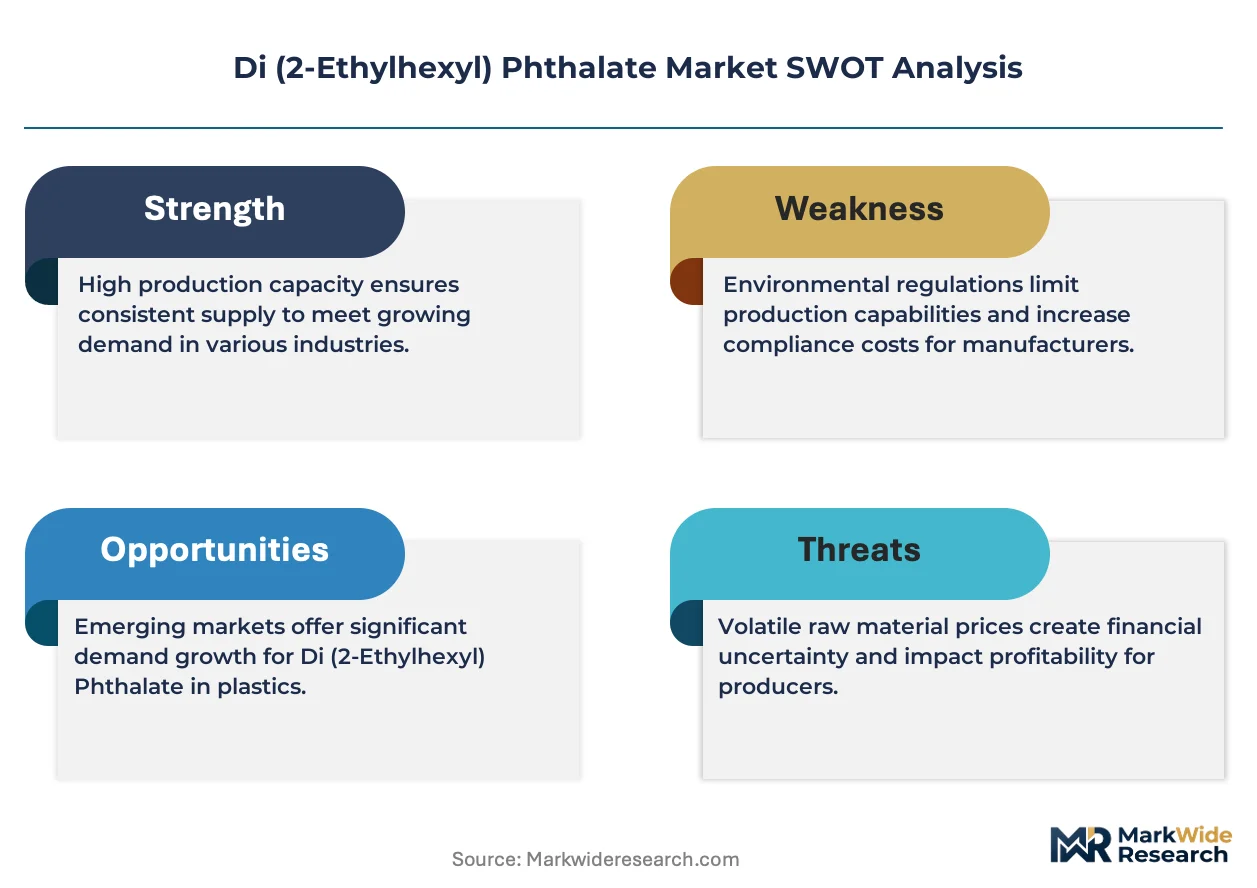
REACH restrictions on phthalate plasticizers in Europe are redirecting formulation strategies toward compliant alternatives, forcing manufacturers to rebalance legacy DEHP capacity against non-phthalate conversion investments while construction and automotive demand in Asia-Pacific absorbs remaining volume.
Growth Catalysts
- Flexible PVC flooring expansion:Commercial construction rebounds across China and India are intensifying resilient surface specifications, pulling DEHP volumes into vinyl sheet and tile compounding at loadings between 30 and 50 percent by weight.
- Automotive manufacturing concentration:Interior component production in India and Southeast Asia maintains industrial-grade DEHP demand for wire insulation and dashboard skins exempt from consumer-facing restrictions under BIS certification frameworks.
- Dual carbon policy accommodation:China's MEE emission standards on phthalate facilities are accelerating efficiency upgrades rather than closures, preserving operational capacity for producers meeting tightened environmental benchmarks.
Market Restraints
- 2-ethylhexanol feedstock volatility:Oxo-alcohol pricing swings tied to propylene and natural gas markets compress margin predictability for integrated and merchant producers alike.
- Substitution acceleration in medical devices:DEHP-free alternatives are capturing IV bag and tubing specifications previously exempt under FDA device regulations, eroding a historically protected demand pocket.
- ECHA SVHC classification friction:Endocrine disruption and reproductive toxicity designations under REACH Article 57 are triggering downstream notification obligations that increase compliance costs for EU-based compounders.
Strategic Opportunities
- Industrial exemption harvesting:Construction and automotive applications in India remain outside BIS phthalate bans, creating a transitional demand window for legacy-grade material.
- Non-phthalate co-location:Producers with existing oxo-alcohol infrastructure can retrofit esterification trains for DINCH or DOTP output, capturing premium pricing from REACH-compliant formulations.
- Direct channel expansion:Bulk industrial buyers in China's Yangtze River Delta are consolidating procurement through producer-direct contracts, bypassing distributor markups and locking in volume commitments.
Industry Challenges
- Process safety certification gaps:India's BIS purity requirements and China's MEE emission audits demand simultaneous compliance investments that strain mid-scale facility economics.
- Legacy system integration friction:Converting existing DEHP esterification capacity to non-phthalate output requires reactor metallurgy upgrades and catalyst replacement timelines that extend 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Di (2-Ethylhexyl) Phthalate Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Additives, Resins, Copolymers Application: Packaging, Flooring, Coatings, Adhesives End Use Industry: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | BASF SE, Eastman Chemical Company, UPC Group, Nan Ya Plastics Corporation, Mitsubishi Chemical Corporation, Aekyung Petrochemical Co., Ltd., Perstorp Holding AB, KLJ Group, ExxonMobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Di (2-Ethylhexyl) Phthalate Market Strategic Shifts
Formulation science and regulatory compliance are converging to reshape how plasticizer portfolios are constructed, with producers racing to match performance specifications while preempting jurisdiction-specific bans.
Cyclohexane dicarboxylic acid esters, notably DINCH, are integrating into medical device and food contact applications as drop-in replacements for DEHP in sensitive end-uses. European compounders under REACH pressure are adopting these alternatives at accelerated qualification cycles, compressing the timeline for legacy phthalate phase-out in consumer-facing goods. This integration is enabling producers to retain customer relationships through portfolio transition rather than volume exit.
ECHA's 2023-2024 updates to SVHC candidate listing protocols are tightening notification thresholds for DEHP presence in articles above 0.1 percent by weight. Downstream manufacturers in Germany and France are reformulating to avoid supply chain disclosure obligations, shifting specification authority from compounders to brand owners with direct consumer liability. Flooring and wire insulation segments with industrial exemptions are now the primary European demand reservoirs.
Specification-driven procurement is consolidating buyer power among large construction and automotive OEMs in China and India, displacing fragmented distributor networks for volume plasticizer sourcing. Tier-1 vinyl flooring producers in Shanghai and Guangdong are negotiating multi-year direct supply agreements with Singapore and Texas Gulf Coast manufacturing complexes. This concentration is most visible in commercial resilient surface contracts where logistics integration determines contract viability over price alone.
Di (2-Ethylhexyl) Phthalate Market Segmentation
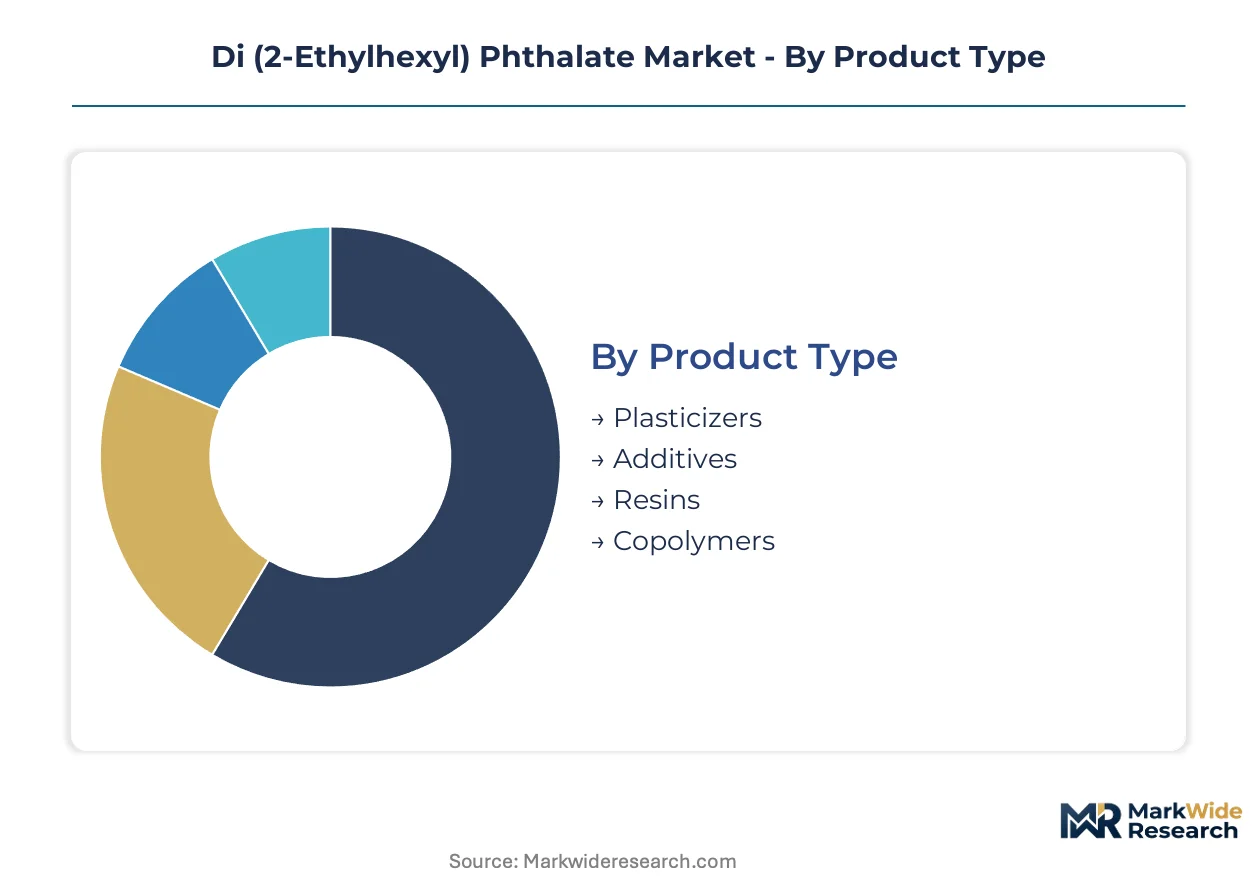
DEHP formulation strategies diverge sharply across end-use specifications, with REACH SVHC thresholds, FDA device exemptions, and BIS purity grades determining which segments absorb legacy capacity versus compliant alternatives. Segment selection dictates reactor metallurgy, catalyst systems, and emission control investments required for viable production economics.
Product Type:
Certification burdens cluster heaviest on plasticizers destined for medical device and food contact applications, where DINCH and DOTP conversions predominate, while industrial-grade additives face lighter purity thresholds under China's MEE framework.
- Plasticizers:These ester compounds constitute the functional core of flexible PVC compounding, typically loaded at 30-50 percent by weight to impart elasticity and durability. Demand concentrates in China's vinyl flooring manufacturing clusters around Shanghai and Guangdong, where commercial construction specifications pull volumes despite REACH-driven substitution in European consumer goods.
- Additives:Secondary formulation components include stabilizers and lubricants co-processed with DEHP in integrated compounding operations. Automotive wire insulation production in India's Chennai and Pune manufacturing corridors maintains industrial-grade demand under BIS exemption frameworks for non-consumer applications.
- Resins:Polymer matrices requiring plasticizer integration for processability in specialty coating formulations.
- Copolymers:Modified polymer structures incorporating phthalate esters for enhanced flexibility in niche industrial applications.
Leading the category by volume: Plasticizers. Growing fastest: Additives in automotive exempt segments.
Application:
Cost tier stratification separates commodity flooring specifications from premium medical-grade coatings, with the former tolerating higher DEHP loadings under industrial exemptions while the latter commands three-figure price premiums for phthalate-free alternatives.
- Flooring:Resilient vinyl sheet and tile compounding represents the single largest DEHP absorption channel, with China's commercial construction rebound driving specification volumes. Yangtze River Delta producers negotiate direct supply contracts with Singapore manufacturing complexes, bypassing distributor markups through logistics-integrated procurement.
- Packaging:Flexible film and container applications face accelerating substitution pressure under EFSA food contact regulations, with European compounders reformulating to avoid SVHC notification obligations above 0.1 percent by weight.
- Coatings:Protective and decorative surface treatments for industrial substrates.
- Adhesives:Bonding formulations incorporating plasticizers for tack and flexibility modification.
Dominant by revenue: Flooring. Steepest expansion trajectory: Packaging conversion to compliant alternatives.
End Use Industry:
Customer type fragmentation distinguishes consolidated automotive OEM procurement from fragmented construction subcontractor purchasing, with the former consolidating volume through multi-year direct agreements and the latter remaining captive to regional distributor networks.
- Construction:Commercial and residential building applications span flooring, wall coverings, and waterproofing membranes. India's infrastructure investment cycle and China's urban renewal programs concentrate incremental demand, with BIS certification requirements creating non-tariff barriers for unqualified imports while preserving domestic capacity economics.
- Automotive:Interior component specifications for wire insulation, dashboard skins, and sealing systems maintain DEHP demand in industrial-grade tiers exempt from consumer-facing restrictions. Southeast Asian manufacturing bases in Thailand and Vietnam absorb volumes as production relocates from higher-regulation jurisdictions.
- Consumer Goods:Household products and personal care packaging facing substitution mandates.
- Electronics:Cable sheathing and connector housings for device manufacturing.
Volume leadership: Construction. Fastest share gain: Automotive as production shifts to exempt manufacturing bases.
Distribution Channel:
Supply concentration in bulk chemical logistics favors direct channel expansion for volume buyers, while fragmented regional markets sustain distributor relevance through last-mile integration and credit extension to smaller compounders.
- Direct Sales:Producer-to-compounder relationships lock in volume commitments through multi-year contracts, with China's tier-1 vinyl flooring manufacturers consolidating procurement around Singapore and Texas Gulf Coast supply points. Logistics integration—tank car availability, port access, and customs clearance speed—determines contract viability more than unit pricing alone.
- Distributors:Regional intermediaries occupy critical positions in India's fragmented state-level markets, where BIS purity documentation and MEE-equivalent emission certifications must be verified at each transaction layer. Mid-scale compounders rely on distributor credit terms and technical support for formulation adjustments.
- Retail:Small-volume sales to specialty chemical purchasers and research institutions.
- Online:Digital procurement platforms for standardized grade spot purchasing.
Channel dominance: Direct Sales. Fastest channel evolution: Distributors adding compliance documentation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the global DEHP manufacturing footprint, with the Yangtze River Delta housing integrated oxo-alcohol and esterification complexes serving vinyl flooring compounders across East Asia. Regulatory divergence between jurisdictions preserving industrial exemptions and those accelerating phase-out timelines is fragmenting regional demand patterns.
China
Commercial construction specifications in Guangdong and Jiangsu provinces pull DEHP volumes into resilient vinyl sheet and tile compounding. MEE emission standards under the dual carbon policy framework are accelerating efficiency upgrades at phthalate facilities rather than triggering closures. Integrated producers in the Yangtze River Delta are negotiating direct supply contracts with tier-1 flooring manufacturers, bypassing traditional distributor networks.
India
Infrastructure investment cycles in Maharashtra and Tamil Nadu are concentrating incremental construction demand for flexible PVC applications. BIS certification requirements for plasticizer purity create non-tariff barriers that preserve domestic capacity economics against unqualified imports. Automotive wire insulation production in Chennai and Pune manufacturing corridors maintains industrial-grade DEHP demand under exemption frameworks for non-consumer applications.
Germany
ECHA's SVHC classification for endocrine disruption is triggering downstream notification obligations that increase compliance costs for EU-based compounders. REACH Article 57 designations are compressing qualification cycles for DINCH and DOTP alternatives in medical device and food contact applications. Industrial flooring and wire insulation segments with explicit exemptions now serve as the primary European demand reservoirs for legacy phthalate grades.
United States
EPA risk evaluations are reshaping permissible DEHP concentrations in consumer-facing goods while preserving industrial exemptions for construction and automotive applications. Texas Gulf Coast manufacturing complexes anchor North American supply through integrated oxo-alcohol chains. Medical device manufacturers are accelerating DEHP-free conversions for IV bag and tubing specifications previously protected under FDA device regulations.
Thailand
Automotive interior component production is absorbing DEHP volumes as manufacturing relocates from higher-regulation jurisdictions in Northeast Asia. Industrial-grade specifications for wire insulation and dashboard skins remain exempt from consumer-facing restrictions under national chemical management frameworks. Bangkok-based compounders are consolidating procurement relationships with Singapore supply points for logistics-integrated volume commitments.
Di (2-Ethylhexyl) Phthalate Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and geographic-integration dimensions, with REACH-compliant non-phthalate portfolios commanding substantial price premiums over legacy DEHP capacity. The vendor base stratifies into three archetypes: integrated petrochemical majors with captive oxo-alcohol supply, regional esterification specialists serving exempt industrial segments, and diversified chemical houses pivoting toward compliant alternative chemistries. Capacity expansion and portfolio diversification toward DINCH or DOTP output represent the dominant competitive moves as regulatory thresholds tighten.
Among integrated petrochemical majors, BASF SE and ExxonMobil Corporation exemplify the scale-driven archetype with manufacturing complexes spanning Singapore and the Texas Gulf Coast. Eastman Chemical Company occupies a position within the diversification-focused tier, maintaining legacy DEHP capacity for exempted industrial segments while building non-phthalate alternative portfolios. These three entities represent the competitive anchors around which mid-scale regional specialists and pure-play esterification houses must position for contract viability.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| UPC Group |
| Nan Ya Plastics Corporation |
| Mitsubishi Chemical Corporation |
| Aekyung Petrochemical Co., Ltd. |
| Perstorp Holding AB |
| KLJ Group |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
2-ethylhexanol feedstock costs cascade from propylene and natural gas markets through oxo-alcohol production into DEHP pricing tiers, with integrated producers at Singapore and Texas Gulf Coast complexes capturing margin buffers unavailable to merchant esterification houses dependent on spot alcohol purchases.
Pricing Analysis
Certification-grade premiums anchor value-based pricing, with REACH-compliant DINCH and DOTP alternatives commanding substantial markups over legacy DEHP in medical device and food contact specifications. Price differentiation separates pharmaceutical-grade purity tiers from industrial flooring grades under China's MEE framework. Cost compression in commodity plasticizers intensifies as construction demand concentrates procurement power among Yangtze River Delta vinyl flooring manufacturers. Tier-1 automotive OEMs in India exhibit lowest price sensitivity due to BIS-mandated purity documentation requirements, while fragmented construction subcontractors remain most exposed to distributor markups.
Supply Chain Analysis
Specialized chemical engineering talent pools in Germany's Ruhr Valley and the US Gulf Coast sustain continuous esterification operations, while workforce gaps in India's specialty chemical sector constrain capacity expansion timelines. Manufacturing gravity centers on China, the United States, and Germany, with Singapore serving as Asia-Pacific supply hub. Phthalic anhydride and 2-ethylhexanol dependencies create feedstock vulnerability to propylene price cycles. Single-source exposure concentrates in oxo-alcohol supply chains. Distribution runs through direct sales channels for bulk industrial buyers, with regional distributors retaining relevance in fragmented Indian state-level markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH SVHC classification erects compliance barriers that favor incumbent producers with existing DINCH and DOTP conversion capabilities, transforming regulatory burden into sustainable competitive moat.
For Market Incumbents: Deploy backward integration into captive oxo-alcohol production to buffer margin erosion from propylene volatility. Accelerate reactor metallurgy upgrades for non-phthalate esterification trains to preempt ECHA phase-out timelines. Consolidate direct supply relationships with Yangtze River Delta flooring manufacturers before distributor networks reconstitute around compliance documentation services. For New Entrants and Emerging Players: Premium-to-economy pricing spreads in India's automotive wire insulation segment offer white-space entry below established DINCH suppliers. Target BIS-exempt industrial applications in Maharashtra and Tamil Nadu construction corridors where legacy DEHP retains specification authority. Pursue toll manufacturing arrangements with idled esterification capacity rather than greenfield investment. For Investors and Strategic Acquirers: ECHA's 2023-2024 SVHC candidate listing protocol tightening is the leading indicator that European compounder consolidation will accelerate. Position for five-to-ten year horizon around producers with simultaneous REACH-compliant alternative portfolios and retained legacy capacity for exempt industrial segments. Monitor BIS certification backlog lengths as inflection signal for Indian market access constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Phthalate Capacity Conversion | REACH Article 57 compliance preserves European market access for integrated producers. |
| Direct Channel Expansion | Logistics-integrated contracts with Shanghai flooring manufacturers displace distributor intermediaries. |
| Backward Integration | Captive oxo-alcohol supply buffers margin compression from propylene price volatility. |
| BIS Certification Investment | Purity documentation capabilities create non-tariff barriers protecting Indian domestic capacity. |
| Joint Venture Formation | Co-location with Yangtze River Delta vinyl compounders locks in volume commitments through customs clearance integration. |
Study Parameters
Document review covered customs trade databases, SEC 10-K filings, and ECHA regulatory notices, complemented by interviews with plant managers at integrated petrochemical complexes, procurement leads at vinyl flooring OEMs, distribution channel partners in Indian state-level markets, and technical R&D directors overseeing esterification process development. Bottom-up volume modeling from individual facility capacities and top-down demand segmentation from end-use industry consumption patterns were triangulated against trade flow data.
Historical production and consumption trajectories were cross-referenced against expert panel assessments of regulatory implementation timelines across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry classification, distribution channel structure, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth curves adjusted for substitution elasticity parameters and feedstock cost pass-through coefficients.
Inputs from ECHA regulatory filings and China's MEE emission audit disclosures were available through the study window; gaps in real-time BIS certification processing data introduce uncertainty bands around Indian market access forecasts. Projections assume continued industrial exemption frameworks in construction and automotive applications; material deviation in REACH Article 57 enforcement intensity or BIS purity threshold revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Soap Noodles Market