
 Biochemicals Control Market | 2026-2036
Biochemicals Control Market Size, Share, and Industry Trends Forecast 2026-2036
Biochemicals Control Market Outlook
Petrochemical-derived agrochemicals is realigning toward fermentation-based biocontrol agents as feedstock volatility erodes cost advantages. BASF SE leverages its integrated biotechnology platforms to anchor European supply of microbial pesticides. Syngenta AG competes through proprietary strain libraries that dominate field-trial pipelines. FMC Corporation differentiates by controlling North American distribution channels for nematode-based formulations.
Biochemicals control encompasses the regulated management of biological and bio-derived chemical agents used to modulate industrial, agricultural, and environmental processes, typically involving active concentrations measured in colony-forming units per milliliter or enzyme activity units per gram. These agents function as catalysts, preservatives, or biocidal intermediates in systems ranging from anaerobic digesters to pharmaceutical cleanrooms. Enzymes occupy the largest value pool within product type segmentation due to their irreplaceability in high-throughput food processing and textile finishing. Fermentation technology leads the technology dimension, though genetic engineering is recording the fastest expansion as CRISPR-edited microbial chassis shorten strain-development cycles from years to months.
EPA biopesticide registration requirements and the EU REACH framework govern active substance approval timelines, with EFSA safety assessments adding twelve to eighteen months for novel microbial strains entering European agriculture. FDA cGMP standards extend into pharmaceutical applications, mandating validated kill-step documentation for biocontrol agents used in sterile manufacturing environments. Stakeholders must monitor how diverging transatlantic data requirements for genome-edited microbes reshape registration strategies and partnership structures.
Market Dynamics
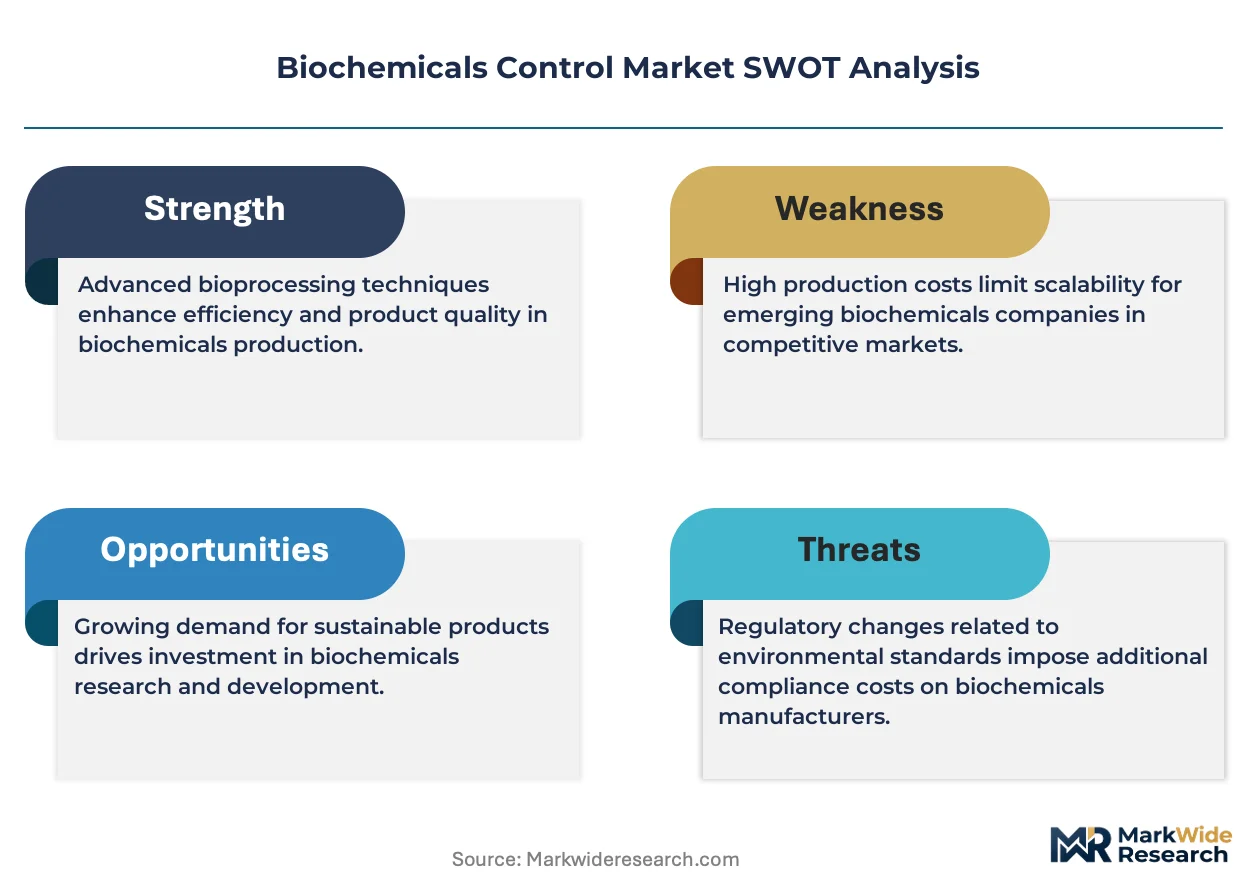
EU REACH and the F-Gas Regulation are forcing petrochemical-derived agrochemicals toward fermentation-based alternatives, compressing registration timelines while feedstock volatility erodes synthetic cost advantages. This regulatory-pressure axis is reconfiguring competitive positioning across the value chain.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal's 50% pesticide reduction targets are accelerating substitution toward microbial biocontrol agents in arable farming. Agricultural cooperatives in the Rhine-Main corridor are expanding procurement volumes accordingly.
- CRISPR-edited microbial chassis:Genetic engineering is compressing strain-development cycles from multi-year timelines to months, enabling faster pipeline progression for novel biocontrol candidates.
- Enzyme irreplaceability:High-throughput food processors and textile finishers cannot substitute enzymatic biocatalysts without process redesign, locking in demand regardless of price fluctuations.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price swings distort comparative economics between synthetic and bio-based crop protection, delaying capital commitment to fermentation capacity expansion.
- EFSA safety assessment timelines:Novel microbial strains face twelve-to-eighteen-month additional review periods beyond base REACH compliance, extending time-to-revenue for developers.
- Colony-forming unit stability:Living biocontrol agents require cold-chain integrity through distribution, limiting reach into infrastructure-deficient agricultural regions.
Strategic Opportunities
- Pharmaceutical cleanroom applications:FDA cGMP-validated kill-step documentation creates premium positioning for biocontrol agents in sterile manufacturing environments, with pricing power unavailable in agricultural segments.
- Genetic engineering-fermentation convergence:CRISPR-edited chassis integrated with continuous fermentation systems enable real-time strain optimization during production campaigns.
- India specialty crop expansion:Grape and pomegranate growers in Maharashtra are adopting nematode-based formulations as residue-conscious export markets tighten MRL requirements.
Industry Challenges
- Genome-edited microbe data requirements:Diverging EPA and EFSA evidentiary standards for edited strains force dual-track registration strategies, doubling documentation burden.
- Validated kill-step certification:Pharmaceutical applications require extensive documentation of biocontrol agent elimination, extending qualification timelines for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biochemicals Control Market |
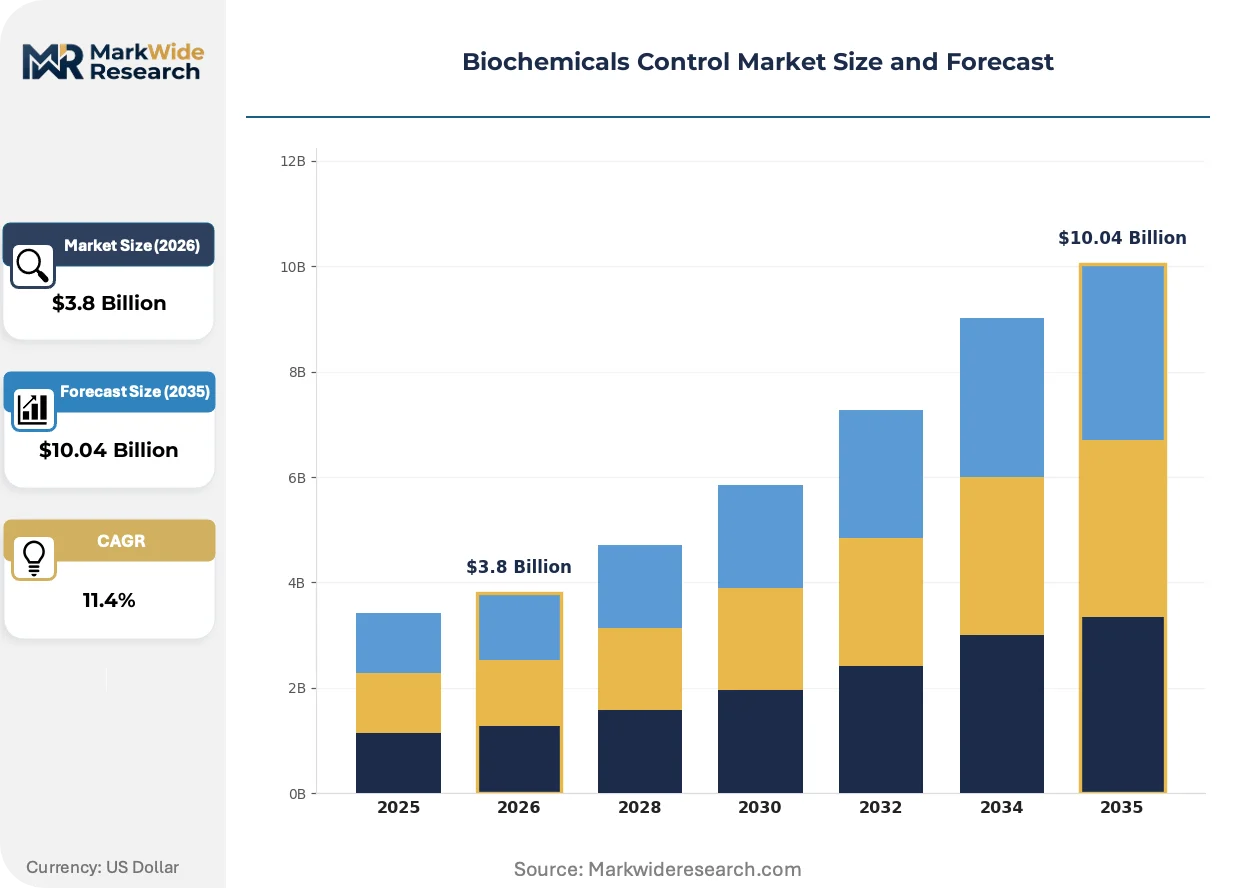
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Amino Acids, Biofuels, Bioplastics Application: Agriculture, Food Processing, Pharmaceuticals, Waste Management End User: Food Industry, Pharmaceutical Manufacturers, Agricultural Producers, Waste Treatment Facilities Technology: Fermentation, Bioconversion, Genetic Engineering, Bioaugmentation |
| Companies Covered | GlaxoSmithKline, Accord Healthcare Inc., Biologics Inc., BioZyme Inc, Juno Therapeutics, BASF SE, Syngenta AG, Corteva Agriscience, FMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biochemicals Control Market Strategic Shifts
Bioprocess automation and regulatory data harmonization are compressing development timelines while procurement patterns shift toward integrated supply partnerships. These forces are redrawing competitive boundaries between technology licensors and finished-formulation suppliers.
Continuous fermentation monitoring coupled with machine-learning-driven bioreactor control is automating strain performance optimization in real time. Contract manufacturers serving agricultural biocontrol markets are deploying these systems to reduce batch failure rates. The technology is automating quality assurance steps previously requiring manual sampling and laboratory analysis, compressing release timelines by weeks.
EPA biopesticide registration requirements are tightening evidentiary standards for microbial metabolite characterization, extending pre-submission study phases. The industrial consequence is consolidation of registration expertise among specialized consultancies and larger developers with captive toxicology capabilities. Novel strain categories entering US agriculture are responding by front-loading metabolite profiling to avoid mid-review data requests.
Buyers in specialty crop segments are consolidating supplier relationships around full-lifecycle technical support rather than transactional product procurement. This behavior is displacing distributor-centric models with direct manufacturer-grower partnerships in high-value horticulture. The shift is most visible in California's Central Valley, where almond and pistachio processors now require biocontrol suppliers to embed field-scouting services into annual contracts.
Biochemicals Control Market Segmentation
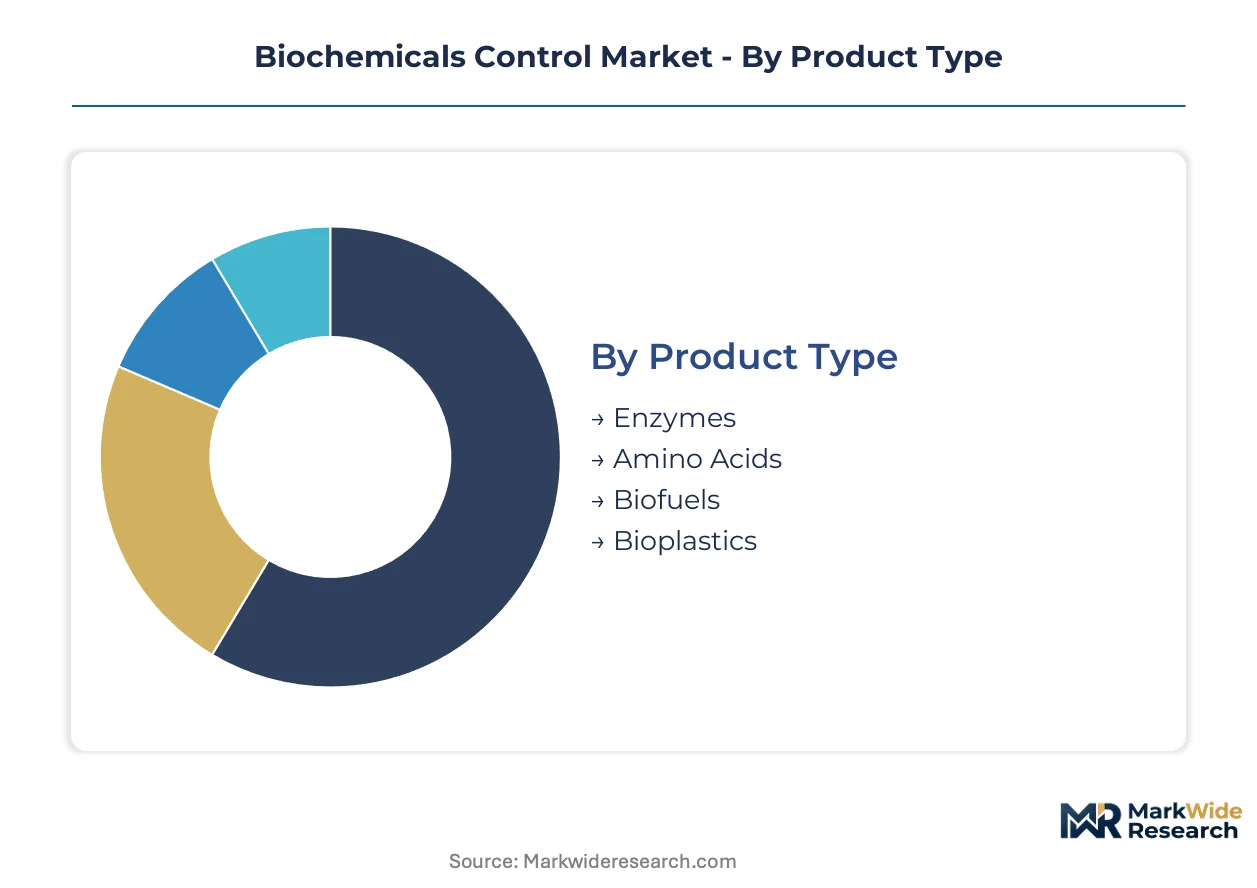
Biochemicals control procurement patterns diverge sharply across application environments, with pharmaceutical cleanrooms demanding validated kill-step documentation while agricultural buyers prioritize colony-forming unit stability through distribution. Segmentation clarity enables suppliers to align strain development, fermentation scale, and regulatory submission strategies with specific end-use economics.
Product Type:
Upgrade cycles in food processing and textile finishing are compressing replacement timelines for enzymatic biocatalysts as throughput requirements intensify.
- Enzymes:These protein biocatalysts operate at specific activity units per gram, with amylases and cellulases dominating high-throughput starch processing and denim finishing operations. Demand concentrates in Germany's Rhine-Main biotech corridor, where integrated fermentation facilities supply European food processors facing EU Green Deal compliance deadlines. Their irreplaceability in existing process architectures locks in procurement regardless of synthetic chemical price fluctuations.
- Amino Acids:Fermentation-derived building blocks serve as preservatives and nutritional modulators in pharmaceutical formulations and animal feed supplements. Agricultural cooperatives in the corridor are expanding volumes for lysine and methionine applications as protein feed alternatives gain traction under sustainability mandates. Cold-chain distribution requirements limit penetration into infrastructure-deficient regions.
- Biofuels:Cellulosic ethanol and advanced biodiesel rely on biocontrol agents for fermentation efficiency and contamination prevention.
- Bioplastics:Polylactic acid and polyhydroxyalkanoate production employs enzymatic biocatalysts for monomer purity control.
Volume placements concentrate in Enzymes; the faster expansion belongs to Amino Acids.
Application:
Cost-tier differentiation separates premium pharmaceutical applications from price-sensitive agricultural segments, with documentation requirements driving margin stratification.
- Agriculture:Microbial pesticides and nematode-based formulations protect specialty crops against soil-borne pathogens and insect pests. Maharashtra grape and pomegranate growers are adopting residue-conscious biocontrol as export markets tighten maximum residue limits. EU F-Gas Regulation and REACH frameworks are accelerating substitution away from synthetic chemical controls.
- Pharmaceuticals:Sterile manufacturing environments require FDA cGMP-validated biocontrol agents with documented kill-step elimination. Cleanroom applications command pricing power unavailable in agricultural segments due to extensive qualification timelines and captive toxicology capabilities. EFSA safety assessments add twelve-to-eighteen-month review periods for novel strains.
- Food Processing:Enzymatic biocatalysts enable high-throughput starch conversion, dairy processing, and beverage clarification without thermal degradation.
- Waste Management:Bioaugmentation agents accelerate anaerobic digester performance and bioremediation of industrial effluents.
Revenue concentration sits in Agriculture; steepest expansion trajectory belongs to Pharmaceuticals.
End User:
Customer-type fragmentation separates transactional agricultural procurement from integrated technical partnerships in high-value horticulture.
- Food Industry:Processors of baked goods, beverages, and dairy products specify enzymatic biocatalysts for yield optimization and shelf-life extension. California almond and pistachio handlers now require suppliers to embed field-scouting services into annual contracts, displacing distributor-centric models. Continuous fermentation monitoring systems are automating quality assurance steps.
- Pharmaceutical Manufacturers:Sterile injectable and biologics producers mandate validated kill-step documentation for biocontrol agents used in aseptic processing. The evidentiary burden extends qualification timelines for new entrants while creating premium positioning for established suppliers with captive regulatory expertise. EPA biopesticide registration requirements are tightening metabolite characterization standards.
- Agricultural Producers:Arable farming cooperatives and specialty crop growers procure microbial biocontrol agents for integrated pest management programs.
- Waste Treatment Facilities:Municipal and industrial anaerobic digester operators deploy bioaugmentation for biogas yield optimization.
Procurement scale favors Food Industry; partnership intensity is climbing fastest among Pharmaceutical Manufacturers.
Technology:
Supply concentration in fermentation infrastructure is creating capability scarcity as genetic engineering platforms shorten development cycles.
- Fermentation:Batch and continuous bioreactor systems cultivate microbial chassis at industrial scale, with machine-learning-driven control automating strain performance optimization. Contract manufacturers serving agricultural markets are deploying these systems to reduce batch failure rates. The technology compresses release timelines by automating manual sampling and laboratory analysis.
- Genetic Engineering:CRISPR-edited microbial chassis are compressing strain-development cycles from multi-year timelines to months. Real-time strain optimization during production campaigns is enabled by convergence with continuous fermentation systems. Diverging EPA and EFSA evidentiary standards for genome-edited microbes force dual-track registration strategies.
- Bioconversion:Enzymatic transformation of feedstock molecules into value-added biochemicals operates at specific substrate loadings and conversion efficiencies.
- Bioaugmentation:Directed introduction of specialized microbial consortia accelerates degradation processes in wastewater and soil remediation.
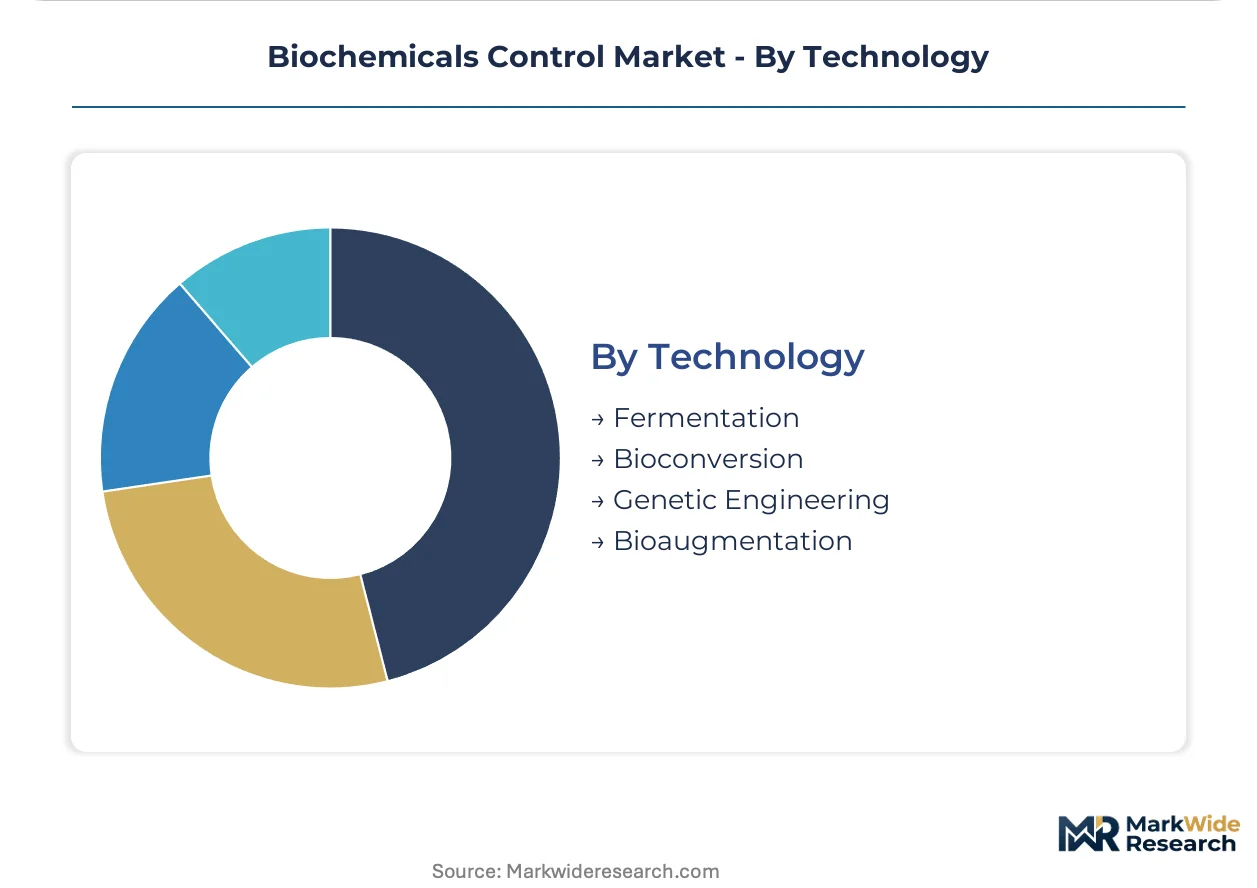
Installed capacity concentrates in Fermentation; capability investment is expanding most quickly in Genetic Engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural cooperatives in Germany's Rhine-Main corridor are expanding procurement volumes for microbial biocontrol agents, while pharmaceutical manufacturers in the United States and India drive premium demand for validated cleanroom applications.
United States
California almond and pistachio processors now require biocontrol suppliers to embed field-scouting services into annual contracts, displacing distributor-centric models. EPA biopesticide registration requirements are tightening evidentiary standards for microbial metabolite characterization. The Central Valley specialty crop cluster is consolidating supplier relationships around full-lifecycle technical support rather than transactional procurement.
Germany
Integrated fermentation facilities in the Rhine-Main biotech corridor supply European food processors facing EU Green Deal compliance deadlines for 50% pesticide reduction. The F-Gas Regulation and REACH framework are accelerating substitution away from synthetic chemical controls toward fermentation-based alternatives. BASF SE leverages its biotechnology platforms to anchor regional supply of microbial pesticides for arable farming cooperatives.
India
Grape and pomegranate growers in Maharashtra are adopting nematode-based formulations as residue-conscious export markets tighten maximum residue limit requirements. The FSSAI and central agricultural regulator are harmonizing import tolerances for biocontrol agents with EU and US standards. Cold-chain infrastructure gaps limit penetration of living biocontrol agents into infrastructure-deficient interior agricultural regions.
China
Cellulosic ethanol producers in the Yangtze River Delta rely on biocontrol agents for fermentation efficiency and contamination prevention in advanced biofuel campaigns. The Ministry of Ecology and Environment's dual carbon goals are accelerating bio-based chemical substitution in industrial processes. Contract manufacturers serving domestic agricultural markets are deploying machine-learning-driven bioreactor control systems to reduce batch failure rates.
Japan
Pharmaceutical cleanroom applications in the Kanto region command premium positioning due to PMDA-validated kill-step documentation requirements for sterile manufacturing environments. METI standards for bio-based industrial chemicals are converging with ISO frameworks for enzymatic biocatalyst certification. The Kansai biotechnology cluster specializes in high-purity enzyme production for food processing and textile finishing applications.
Biochemicals Control Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated biotechnology platforms commanding premium positioning in pharmaceutical applications while agricultural distributors compete on colony-forming unit stability through distribution. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with captive fermentation capacity, specialized microbial strain developers, and contract manufacturing organizations with regulatory submission expertise. Dominant competitive moves include convergence of genetic engineering with continuous fermentation systems and consolidation of registration expertise among specialized consultancies.
Within the diversified chemical tier, BASF SE and Syngenta AG exemplify integrated platform strategies, with the former anchoring European supply chains and the latter competing through proprietary biological asset libraries. FMC Corporation occupies a position in the North American distribution channel tier for nematode-based formulations. These three entities represent distinct approaches to capturing value across the biochemicals control spectrum, from strain development through finished-formulation supply.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Accord Healthcare Inc. |
| Biologics Inc. |
| BioZyme Inc |
| Juno Therapeutics |
| BASF SE |
| Syngenta AG |
| Corteva Agriscience |
| FMC Corporation |
| Others |
Value Chain & Pricing Dynamics
Crude oil price volatility cascades through fermentation feedstock markets, compressing margins on petrochemical-derived agrochemicals while elevating bio-based alternatives across three-tier pricing structures separating pharmaceutical-grade from agricultural-standard from commodity-economy tiers. This feedstock-driven repricing is reshaping procurement economics for buyers in Germany's Rhine-Main corridor and California's Central Valley alike.
Pricing Analysis
Volume placements concentrate in agricultural-standard tiers where colony-forming unit stability commands modest premiums; pharmaceutical-grade applications with FDA cGMP-validated kill-step documentation capture disproportionate margins. Price differentiation hinges on certification tier and geographic delivery cost, with cold-chain infrastructure gaps inflating landed costs in infrastructure-deficient regions. Cost compression in agricultural segments is intensifying because feedstock volatility erodes synthetic chemical cost advantages. Food processors exhibit highest price sensitivity due to enzymatic irreplaceability locking in demand regardless of fluctuations; pharmaceutical manufacturers show lowest sensitivity given captive qualification timelines.
Supply Chain Analysis
Specialized fermentation workforce availability in Germany, the United States, and India constrains capacity expansion timelines for microbial chassis production. Manufacturing draws from molasses and corn-derived dextrose feedstocks, with CRISPR-edited strain libraries and continuous bioreactor control systems as critical technology inputs. Single-source vulnerability sits with concentrated contract manufacturing organizations possessing regulatory submission expertise. Distribution runs through direct manufacturer-grower partnerships displacing distributor-centric models in high-value horticulture segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity props pricing across all tiers, with qualified cleanroom manufacturing slots for pharmaceutical applications commanding longest lead times and deepest backlogs.
For Market Incumbents: Cement dominance by anchoring European supply chains through integrated biotechnology platforms and capturing registration expertise among specialized consultancies. Threats from genome-edited microbe developers with compressed strain-development cycles demand preemptive capacity addition in the Rhine-Main corridor. Certification investment in FDA cGMP-validated kill-step documentation creates defensive moats against emerging microbial pesticide suppliers. For New Entrants and Emerging Players: Capture white-space in Maharashtra specialty crop segments where residue-conscious export markets tighten maximum residue limits and cold-chain gaps limit incumbent penetration. India's harmonizing import tolerances with EU and US standards present the most penetrable regulatory entry point. Go-to-market through embedded field-scouting services bundled into annual contracts displaces transactional procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturing organizations with regulatory submission expertise in Germany and the United States during feedstock volatility windows. Long-term viability rests on convergence of genetic engineering with continuous fermentation systems compressing development timelines. Watch EPA biopesticide registration timeline extensions as inflection indicator for consolidation pressure among specialized consultancies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Molasses and dextrose sourcing control insulates margin compression from crude oil volatility in Rhine-Main corridor. |
| Continuous Fermentation Scale-Up | Machine-learning-driven bioreactor deployment reduces batch failure rates for agricultural biocontrol contract manufacturers. |
| Dual-Track Registration Investment | Parallel EPA and EFSA evidentiary packages address diverging genome-edited microbe data requirements. |
| Field-Scouting Service Embedding | California almond and pistachio processors now mandate annual contract bundling displacing distributor models. |
| Pharmaceutical Cleanroom Qualification | FDA cGMP-validated kill-step documentation commands pricing power unavailable in agricultural segments. |
Study Parameters
Independent corroboration across fermentation technology licensors, contract manufacturing organizations, and agricultural cooperative procurement directors underwrites the qualitative findings. Primary interviews with regulatory affairs leads at microbial pesticide developers, technical R&D directors at enzyme suppliers, and distribution channel partners in North America and Europe combined with secondary validation from EPA biopesticide registration databases, EFSA safety assessment filings, EU REACH substance dossiers, and customs trade data for fermentation equipment imports. Bottom-up strain pipeline counts and top-down agricultural input expenditure models triangulate volume estimates.
Comparable-period anchoring to historical biopesticide adoption curves and enzymatic biocatalyst replacement cycles shapes the projection framework across the analysis window. Segmentation dimensions modeled include product type, application environment, technology platform, and end-user procurement archetype. CAGRs derive from fitted growth curves against regulatory deadline acceleration and feedstock substitution economics. Industry-specific inputs incorporate EU Green Deal pesticide reduction compliance timelines and CRISPR-edited microbial chassis development velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to diverging transatlantic data requirements for genome-edited microbes and colony-forming unit stability through distribution infrastructure buildout. Forecasts reflect assumptions on regulatory harmonization progress and cold-chain penetration rates. Material deviation in EPA evidentiary standard tightening or EFSA safety assessment timeline extension warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Nitrous Oxide Market