
 Swimming Pool Salt Chlorinator Market | 2026-2036
Swimming Pool Salt Chlorinator Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Pool Salt Chlorinator Market Insights
Pool service company purchasing is consolidating as regional maintenance chains expand their fleet coverage and standardize on single-vendor salt chlorination platforms. Pentair leverages its distribution network across North American pool retailers to capture this consolidated procurement flow. Fluidra anchors its position in European commercial installations through specialized high-output cell systems. Hayward Industries differentiates via integrated smart-pool ecosystems that bundle chlorination with pump and heating controls.
A swimming pool salt chlorinator is an electrolytic water treatment device that converts dissolved sodium chloride into free chlorine through titanium-coated electrode cells, maintaining sanitizer levels between one and three parts per million without manual chemical dosing. The technology eliminates bulk chlorine storage while providing continuous oxidation of organic contaminants in residential and commercial aquatic environments. In-ground systems dominate installed value due to permanent plumbing integration and higher-capacity cell requirements, though above-ground units represent the fastest-growing product category as entry-level saltwater conversion kits gain traction at mass retailers. Automated technology commands the widest margin pool by reducing homeowner intervention and enabling remote monitoring via mobile applications.
EPA regulations on chemical handling and discharge shape product design requirements for salt chlorinator manufacturers serving the United States market. CE marking under EU machinery and low-voltage directives governs access to European member states, while Australia's electrical safety standards administered by state-level regulators mandate specific isolation and grounding protocols for pool-mounted equipment. Stakeholders must monitor evolving interoperability standards between chlorination systems and smart-home platforms to preserve technology premiums against commoditized base units.
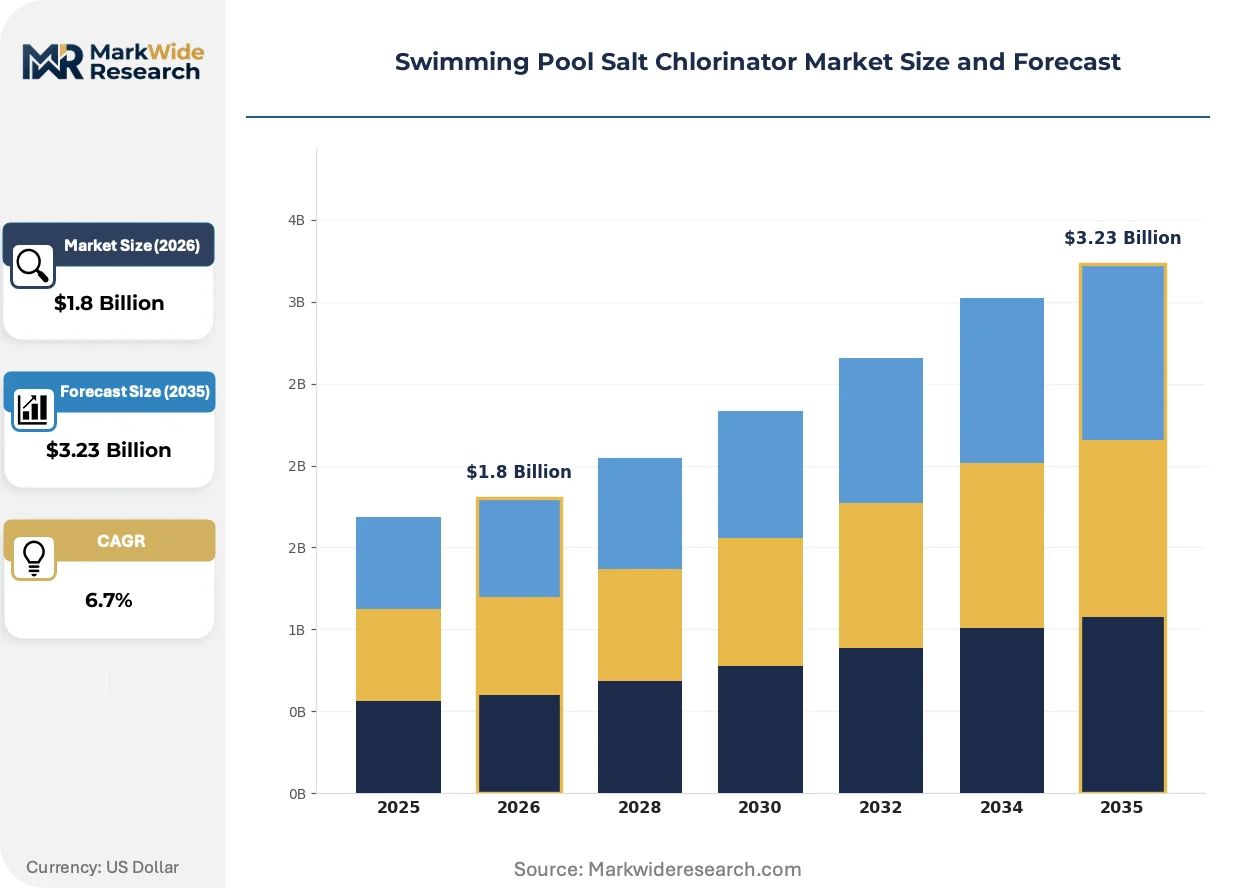
Market Dynamics
The Swimming Pool Salt Chlorinator Market is experiencing structural compression as residential pool owners abandon manual chlorine dosing in favor of electrolytic sanitization systems, while commercial operators face tightening chemical-handling compliance obligations.
Growth Catalysts
- EPA Chemical Storage Mandates:Stricter discharge and containment rules for bulk chlorine are accelerating salt chlorinator adoption among US commercial pool operators seeking to eliminate hazardous material inventory.
- Titanium Electrode Cell Advances:Extended-lifespan coated anodes are reducing replacement frequency and lifetime ownership costs for residential buyers.
- Suburban Pool Construction:New in-ground installations in US exurban counties are specifying salt systems as standard equipment rather than upgrade options.
Market Restraints
- Cell Replacement Cost Burden:Electrode degradation requires periodic capital expenditure that erodes total-cost-of-ownership advantages versus traditional chlorination.
- Salinity Corrosion Damage:Salt-induced degradation of pool decking, handrails, and adjacent landscaping creates liability exposure and homeowner resistance.
- Regional Water Restrictions:Drought-driven municipal limits on pool filling and backwashing constrain system activation in California and Arizona jurisdictions.
Strategic Opportunities
- Smart-Home Integration:Voice-assistant compatibility and unified pool equipment control via mobile applications command pricing premiums over standalone chlorinators.
- Above-Ground Conversion Kits:Mass retail channel penetration for entry-level saltwater retrofit packages targets the installed base of vinyl-liner pool owners.
- Australian Commercial Standards:State-level electrical safety mandates for pool-mounted equipment create specification lock-in for compliant system suppliers.
Industry Challenges
- Installer Certification Bottlenecks:Shortage of electricians qualified for wet-environment equipment grounding slows residential retrofit timelines.
- Legacy Pump Compatibility:Variable-speed circulation systems require recalibrated flow sensors, complicating upgrades for existing pool infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimming Pool Salt Chlorinator Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground, In Ground, Mobile, Commercial Component: Cell, Control Module, Salt Tank, Sensor Technology: Electrolytic, Manual, Automated, Hybrid End User: Residential, Hotels, Fitness Centers, Community Pools |
| Companies Covered | Hayward Industries, Pentair, Fluidra, Zodiac Pool Systems, AstralPool, Waterco, Emaux Group, AutoPilot, Solaxx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Pool Salt Chlorinator Market Trends and Innovations
Electrolytic water treatment is evolving from standalone sanitation hardware into networked pool management infrastructure, with sensor fusion and predictive maintenance algorithms redefining equipment value propositions.
Reverse-polarity self-cleaning cell technology is overtaking manual acid-wash maintenance protocols in mid-market residential segments. The automated electrode reversal cycle extends operational intervals between service calls. Equipment manufacturers are compressing warranty support costs while capturing recurring revenue through connected-cell subscription tiers.
REACH substance restrictions on titanium dioxide processing are reshaping European electrode supply chains. Manufacturers must document coating composition and recyclability to maintain CE machinery directive compliance. Spanish and Italian commercial installers are prioritizing suppliers with pre-certified circular-economy documentation to accelerate project permitting.
Service contract unbundling is fragmenting buyer relationships in the US residential segment. Independent pool technicians are deploying their own cellular-connected monitoring hardware to displace manufacturer-branded platforms. Florida and Texas markets exhibit the highest technician autonomy, with regional service cooperatives negotiating direct cell supply agreements outside traditional distribution hierarchies.
Swimming Pool Salt Chlorinator Market Segmentation
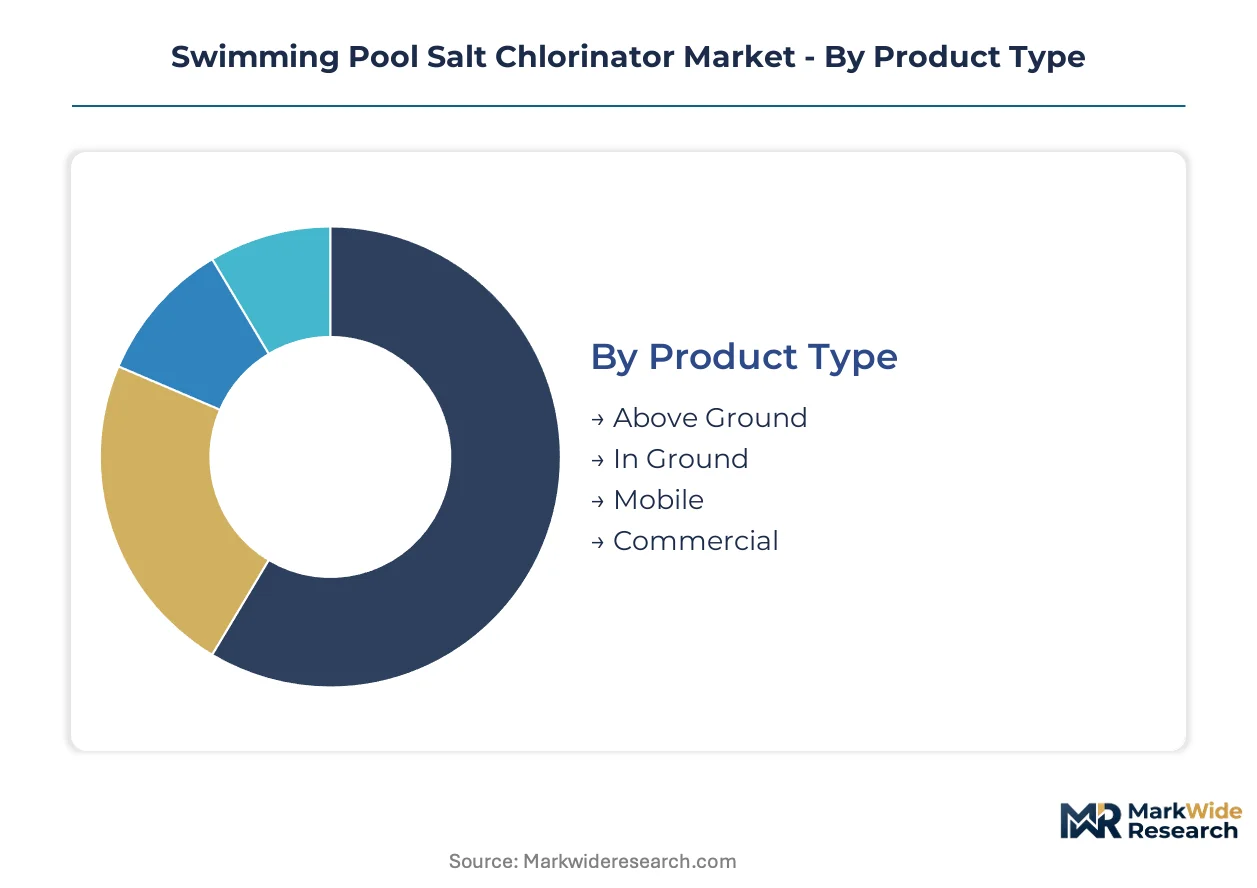
Salt chlorinator procurement varies sharply by installation permanence, operational scale, and automation requirements. Equipment specifications diverge across residential retrofit versus new commercial construction, with capital deployment patterns dictating vendor selection and service attachment rates.
Product Type:
Capital requirements scale with installation permanence and plumbing integration depth, creating distinct financing and margin profiles across the product hierarchy.
- In Ground:Permanent titanium electrode cells integrate with concrete gunite or fiberglass shells, requiring licensed electrician grounding and dedicated circulation loops. Demand concentrates in US exurban counties where new construction specifies salt systems as standard equipment, driven by homeowner preference for eliminated chemical handling.
- Above Ground:Vinyl-liner conversion kits with clamp-on cell housings and temporary plumbing adapters dominate mass retail channels. Australian and Spanish markets show steepest expansion as existing pool owners retrofit without structural modifications, constrained by shorter cell lifespans from variable flow conditions.
- Mobile:Portable cart-mounted units serve event rentals and temporary installations with self-contained power and salinity dosing.
- Commercial:High-output parallel cell arrays handle elevated bather loads in municipal aquatic centers with redundant sanitation capacity.
Most installed capacity flows through In Ground systems. Expansion is steepest in Above Ground as conversion kit penetration accelerates at big-box retailers.
Component:
Replacement cycle economics and proprietary interface lock-in determine recurring revenue capture across the component stack.
- Cell:Titanium-coated anode assemblies constitute the primary wear item, with reverse-polarity self-cleaning variants extending service intervals. US residential demand clusters in suburban markets where homeowners trade higher upfront cost for reduced acid-wash maintenance.
- Control Module:Microprocessor-driven power management units with salinity sensing and flow detection enable automated chlorine output adjustment. Australian state electrical safety mandates create specification lock-in for compliant suppliers, concentrating procurement among pre-certified vendors.
- Salt Tank:Brine reservoir systems with dissolution grids support high-capacity commercial installations.
- Sensor:Redox and temperature probes provide closed-loop feedback for precision sanitation control.
Cell replacement generates the highest attach rate for manufacturer service contracts. Control Module integration with smart-home platforms commands the widest pricing premiums.
Technology:
Automation intensity separates commodity hardware from value-capturing connected infrastructure in vendor portfolios.
- Automated:Sensor-fusion systems with predictive maintenance algorithms and mobile application remote monitoring redefine equipment value propositions. Demand concentrates among US residential buyers seeking voice-assistant compatibility and unified pump-heating-chlorination control.
- Electrolytic:Standard fixed-output cells without feedback loops dominate price-sensitive entry segments. Spanish and Italian commercial installers prioritize pre-certified circular-economy documentation to accelerate REACH-compliant project permitting.
- Manual:Basic timer-based units require homeowner intervention for seasonal adjustment.
- Hybrid:Combined electrolytic-UV systems address high-contaminant load scenarios in fitness centers.
Automated systems capture the highest margin pool. Electrolytic base units retain volume leadership in developing markets.
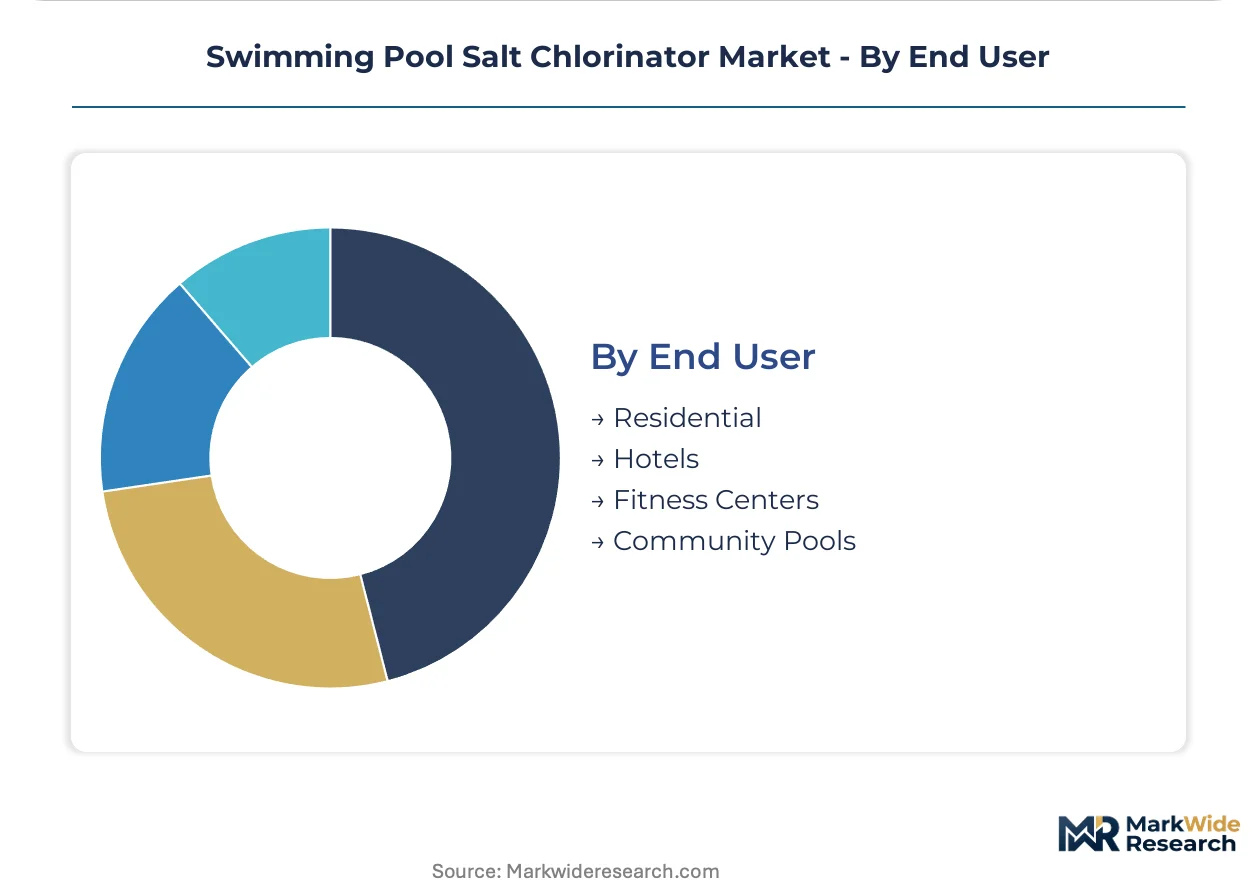
End User:
Compliance obligation severity and chemical handling liability exposure create divergent procurement authority structures across buyer types.
- Residential:Individual pool owners in suburban North America drive fastest segment expansion as salt-based sanitization displaces traditional chlorine handling and EPA storage mandates tighten. Florida and Texas markets exhibit highest technician autonomy with regional service cooperatives negotiating direct cell supply.
- Hotels:Resort and hospitality operators face guest liability exposure from chloramine irritation and chemical spill risks. Australian commercial standards for pool-mounted electrical equipment create compliant supplier specification lock-in.
- Fitness Centers:High-bather-load facilities require redundant capacity and automated shock oxidation protocols.
- Community Pools:Municipal operators balance budget constraints against public sector chemical discharge regulations.
Residential accounts deploy the most unit volume. Hotels generate the highest per-site equipment value through integrated smart-pool ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's saltwater pool penetration has reached mature levels in new construction, while Spain's commercial installers prioritize suppliers with pre-certified circular-economy documentation to accelerate project permitting.
United States
Suburban pool construction in exurban counties specifies salt systems as standard equipment, driven by homeowner preference for eliminated chemical handling. EPA discharge and containment rules for bulk chlorine accelerate adoption among commercial pool operators. Florida and Texas markets exhibit highest technician autonomy, with regional service cooperatives negotiating direct cell supply agreements outside traditional distribution hierarchies.
Australia
State-level electrical safety standards administered by regulators mandate specific isolation and grounding protocols for pool-mounted equipment, creating specification lock-in for compliant system suppliers. Existing pool owners retrofit vinyl-liner installations without structural modifications, constrained by shorter cell lifespans from variable flow conditions. New South Wales and Queensland lead residential conversion kit penetration at mass retailers.
Spain
REACH substance restrictions on titanium dioxide processing reshape European electrode supply chains, requiring manufacturers to document coating composition and recyclability. Commercial installers prioritize suppliers with pre-certified circular-economy documentation to accelerate project permitting. Catalonia and Andalusia concentrate hospitality sector procurement for integrated smart-pool ecosystems.
Italy
CE marking under EU machinery and low-voltage directives governs access to member states, with commercial operators facing tightening chemical-handling compliance obligations. Lombardy and Emilia-Romagna anchor high-output cell system deployment for municipal aquatic centers with redundant sanitation capacity. Italian installers mirror Spanish prioritization of circular-economy documentation for REACH-compliant permitting.
Swimming Pool Salt Chlorinator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the salt chlorinator value chain, with market structure consolidating around integrated pool equipment platforms. Three archetypes dominate: full-stack pool equipment conglomerates with distribution network control, specialized electrolytic cell manufacturers with titanium coating expertise, and smart-home integrators bundling chlorination with unified pump-heating controls. Competitive moves concentrate on strategic partnerships with regional maintenance chains and technology licensing for predictive maintenance algorithms.
Among diversified pool equipment conglomerates, Pentair and Hayward Industries exemplify the full-stack archetype with distribution network leverage across North American retailers. Fluidra anchors the European commercial installation segment through specialized high-output cell systems. Zodiac Pool Systems occupies a position within the technology-integrator tier, representing the voice-assistant compatibility and mobile remote monitoring vector that commands pricing premiums over standalone chlorinators.
| Leading Market Players |
|---|
| Hayward Industries |
| Pentair |
| Fluidra |
| Zodiac Pool Systems |
| AstralPool |
| Waterco |
| Emaux Group |
| AutoPilot |
| Solaxx |
| Others |
Pricing and Supply Chain Analysis
Reverse-polarity self-cleaning cell technology is compressing maintenance cost structures while concentrating procurement leverage among titanium coating specialists with proprietary electrode formulations. This production-method transition simultaneously elevates upfront equipment premiums and locks in replacement-part dependency, reshaping how margin pools distribute across manufacturers and aftermarket service providers.
Pricing Analysis
Capacity additions in Chinese titanium dioxide processing are reshaping price floors for electrode assemblies across European and Australian markets. Three-tier pricing structure across premium automated, standard electrolytic, and economy manual levels stratifies by salinity sensing precision and smart-home integration depth. Cost compression in the above-ground conversion kit tier is intensifying because mass retail channel expansion concentrates buyer power at big-box distributors. Residential retrofit segments exhibit highest price sensitivity, while commercial municipal operators show lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Cell refurbishment and core-return programs are emerging as critical reverse-logistics flows that recapture titanium anode material and extend circular-economy documentation for REACH-compliant European installations. Manufacturing concentration centers on China for titanium dioxide coating, Australia for control module assembly under state electrical safety mandates, and Spain for high-output commercial cell arrays. Raw material dependencies include rutile-grade titanium feedstock, specialized polymer housings for wet-environment electrical isolation, and rare-earth elements for sensor fusion components. Single-source vulnerability in rutile supply from Ukrainian and Australian mines creates exposure to commodity price volatility. Distribution runs through North American pool retailer networks, European commercial installer direct procurement, and Australian mass retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EPA chemical storage mandates in the United States and REACH substance restrictions in Europe creates geographic-arbitrage opportunities for manufacturers with dual-certification capabilities, as compliance cost differentials of 15-25 percent separate premium-tier market access from commodity exclusion.
For Market Incumbents: To counter independent technician displacement of manufacturer-branded monitoring platforms, Pentair and Hayward Industries should deepen backward integration into titanium electrode coating to secure supply continuity against REACH documentation requirements. Fluidra must reinforce channel control through exclusive service partnerships with regional maintenance chains in Florida and Texas where technician autonomy concentrates. Certification investment in Australian state-level electrical safety pre-approval creates specification lock-in against emerging Asian competitors. For New Entrants and Emerging Players: Predictive maintenance algorithms with cellular-connected sensor fusion represent the most penetrable technology wedge for displacing incumbent control module attach rates. Above-ground vinyl-liner conversion kits in Australian and Spanish mass retail channels offer white-space expansion with minimal installer certification bottlenecks. Direct-to-technician cell supply agreements outside traditional distribution hierarchies provide the strongest go-to-market angle in fragmented US service markets. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized electrolytic cell manufacturers with titanium coating expertise but limited smart-home integration capabilities, as platform consolidation favors full-stack pool equipment conglomerates. Long-term viability over the coming decade hinges on captive supply of REACH-compliant electrode materials and predictive maintenance software recurring revenue. Acquisition targets should demonstrate pre-certified circular-economy documentation and state-level electrical safety approvals in Australia. The signal to watch is technician cooperative formation rates in Texas and Florida as indicators of distribution disintermediation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Platform Integration | Voice-assistant compatibility commands pricing premiums over standalone chlorinators in US residential segments. |
| REACH-Compliant Electrode Sourcing | Pre-certified circular-economy documentation accelerates project permitting for Spanish and Italian commercial installers. |
| Technician Cooperative Partnerships | Direct cell supply agreements outside distribution hierarchies capture Florida and Texas service market fragmentation. |
| Reverse-Polarity Self-Cleaning Cell Deployment | Automated electrode reversal extends service intervals and compresses warranty support costs for mid-market residential buyers. |
| Australian Electrical Safety Pre-Certification | State-level isolation and grounding protocol approval creates specification lock-in against unqualified competitors. |
Research Methodology
Multiple input streams — primary interviews with pool equipment distributors, commercial installer technical directors, and residential service technicians, alongside secondary validation through EPA regulatory filings, Australian state electrical safety registers, and REACH substance restriction databases — were reconciled through bottom-up equipment shipment analysis and top-down market sizing triangulation. Primary fieldwork captured procurement authority structures across consolidated regional maintenance chains and fragmented independent technician cooperatives. Secondary sources included customs trade data for titanium dioxide and electrode assembly flows, SEC filings from listed pool equipment conglomerates, and industry association membership directories for installer certification tracking.
Historical volume trajectories were cross-referenced against panel input from equipment procurement officers at municipal aquatic centers and hospitality operators to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated installation permanence, automation intensity, and end-user compliance obligation severity alongside geographic regulatory cluster differentiation. CAGRs were derived from curve-fitting approaches applied to disclosed manufacturer shipment data and regional construction permit correlations. Industry-specific forecast inputs included suburban pool construction permit velocities in US exurban counties and drought-driven municipal water restriction enforcement patterns in California and Arizona jurisdictions.
The model holds under stable regulatory enforcement of EPA chemical storage mandates and REACH titanium dioxide documentation requirements; deviation in state-level electrical safety standard harmonization or drought restriction intensity would shift replacement cycle timing and new installation specifications. Forecasts incorporate assumptions regarding titanium electrode degradation rates and reverse-polarity technology adoption curves. Practitioners should monitor technician cooperative formation rates in Texas and Florida and Australian state regulator pre-approval timeline extensions for early signals of distribution structure transformation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Global Neopentyl Glycol Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
VOC Concentrator Market