
 Cellulosic Polymers Market | 2026-2036
Cellulosic Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulosic Polymers Market Outlook
Multi-source procurement for specialty cellulose derivatives is recalibrating how compounders secure raw material streams. Eastman Chemical Company leverages its integrated cellulose ester technology to sustain supply continuity for coating and film applications. Daicel Corporation anchors the Asia-Pacific supply base with captive acetic acid and cellulose feedstock operations.
Cellulosic polymers comprise regenerated or derivative compounds from cellulose, typically featuring degrees of substitution between 0.5 and 3.0 that govern solubility in organic solvents or aqueous systems; these materials function as binders, film formers, rheology modifiers, and encapsulation matrices across industrial and consumer formulations. Cellulose acetate dominates volume flows through mature cigarette filter tow demand, while hydroxypropyl methylcellulose captures expanding margin pools in pharmaceutical controlled-release tablets and construction-grade cement retarders. Carboxymethyl cellulose competes aggressively in food additive and oilfield drilling fluid segments where thickening efficiency and water retention command premium positioning.
REACH registration requirements and the EPA's Toxic Substances Control Act framework impose purity and migration testing burdens on cellulosic polymer suppliers seeking European and United States market access. FDA excipient guidelines and IPEC GMP certification further stratify the pharmaceutical-grade supply tier, filtering out uncertified producers from high-value drug formulation channels. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Pharmaceutical formulators are accelerating hydroxypropyl methylcellulose qualification for controlled-release matrices, tightening purity specifications faster than cellulose ester suppliers can expand pharmaceutical-grade capacity.
Growth Catalysts
- Controlled-Release Drug Formulation:Pharmaceutical manufacturers are expanding hydroxypropyl methylcellulose use in oral solid dosage systems that modulate active ingredient release kinetics over extended periods.
- REACH Registration Thresholds:European chemical registration requirements are filtering out uncertified cellulose derivative producers from food-contact and medical-grade supply channels.
- China Domestic Excipient Scale-Up:Chinese pharmaceutical packaging film and excipient production is capturing regional demand previously served by imported specialty cellulose grades.
Market Restraints
- Acetic Acid Feedstock Volatility:Cellulose acetate manufacturers face margin pressure from petrochemical-derived acetic acid price swings that propagate through esterification cost structures.
- Pulp Supply Geographic Concentration:Dissolving wood pulp for specialty cellulose derivatives concentrates in Brazilian and South African forestry operations, creating single-source vulnerability.
- Cellulose Nanocrystal Substitution:Emerging nanocellulose materials threaten traditional thickening applications in food and personal care where transparency and low dosage confer performance advantages.
Strategic Opportunities
- Biodegradable Flexible Packaging:Cellulose acetate and regenerated cellulose films are displacing conventional plastics in European fresh produce wrapping under single-use plastic directive pressure.
- Construction Cement Retarder Expansion:Hydroxypropyl methylcellulose demand from ready-mix concrete producers is rising in India's infrastructure build-out, particularly in high-temperature pouring conditions.
- 3D Printing Filament Formulation:Cellulose acetate compounds are entering desktop filament markets as low-odor, biodegradable alternatives to petroleum-based thermoplastics in educational and prototyping segments.
Industry Challenges
- IPEC GMP Certification Timelines:Pharmaceutical-grade cellulose derivative producers face 18-24 month qualification periods that delay market entry for new manufacturing facilities.
- Esterification Process Capital Intensity:Acetylation and etherification reactor systems require significant upfront investment, constraining mid-scale entrants from achieving cost-competitive unit economics.
- Legacy Equipment Integration:Established cellulose ester plants must retrofit solvent recovery and emission control systems to meet evolving EPA Maximum Achievable Control Technology standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulosic Polymers Market |
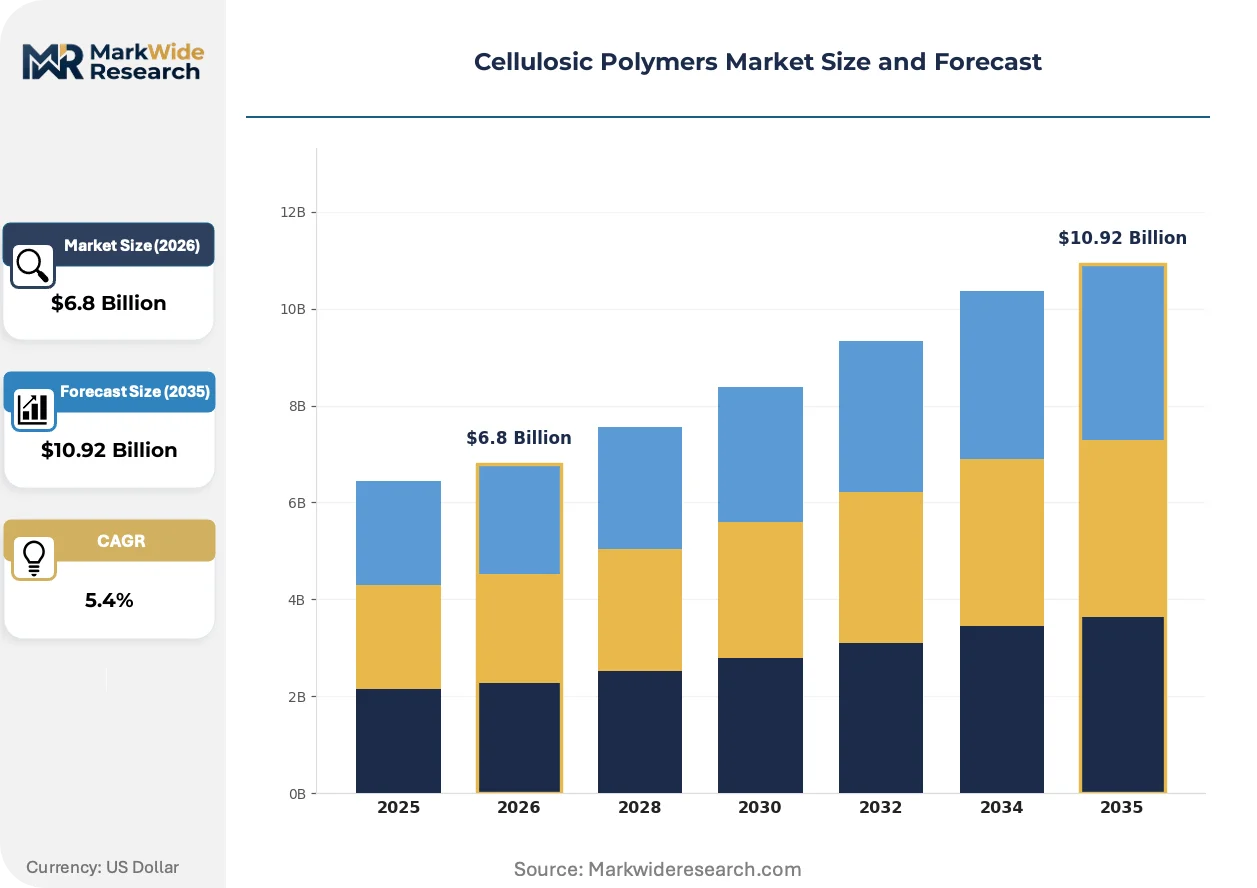
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Acetate, Hydroxypropyl Methylcellulose, Ethyl Cellulose, Carboxymethyl Cellulose Application: Pharmaceuticals, Packaging, Textiles, Food Additives End Use Industry: Cosmetics, Food & Beverage, Personal Care, Construction Form: Powder, Granule, Film, Gel |
| Companies Covered | Nouryon Chemicals Holding B.V., Eastman Chemical Company, Celanese Corporation, DuPont, Daicel Corporation, Ashland, Dow, Inc., Lenzing AG, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulosic Polymers Market Strategic Shifts
Process intensification and regulatory chemistry are compressing development cycles for next-generation cellulosic materials, while end-use sectors demand functional performance beyond traditional commodity specifications.
Continuous acetylation reactor technology is automating cellulose ester production throughput while reducing solvent inventory and energy intensity per ton of output. Specialty chemical compounders in coating and film applications are piloting these systems to shorten batch cycle times from hours to minutes. The technology is automating quality consistency that previously required extensive manual sampling and laboratory adjustment.
EPA's Toxic Substances Control Act Section 5 notification requirements are tightening pre-manufacture scrutiny for novel cellulose derivatives intended for food-contact applications. Suppliers must now submit migration testing data and environmental fate studies before commercial introduction. Pharmaceutical-grade cellulose acetate and carboxymethyl cellulose producers are responding by front-loading toxicology investment to preserve United States market access.
Direct procurement relationships between pharmaceutical formulators and cellulose derivative manufacturers are displacing traditional distributor intermediaries in high-volume excipient supply. Large generic drug manufacturers in India and China are negotiating multi-year toll manufacturing agreements that specify purity, particle size distribution, and batch documentation protocols. This channel consolidation is most visible in controlled-release tablet formulations where supply security outweighs spot-price optimization.
Cellulosic Polymers Market Segmentation
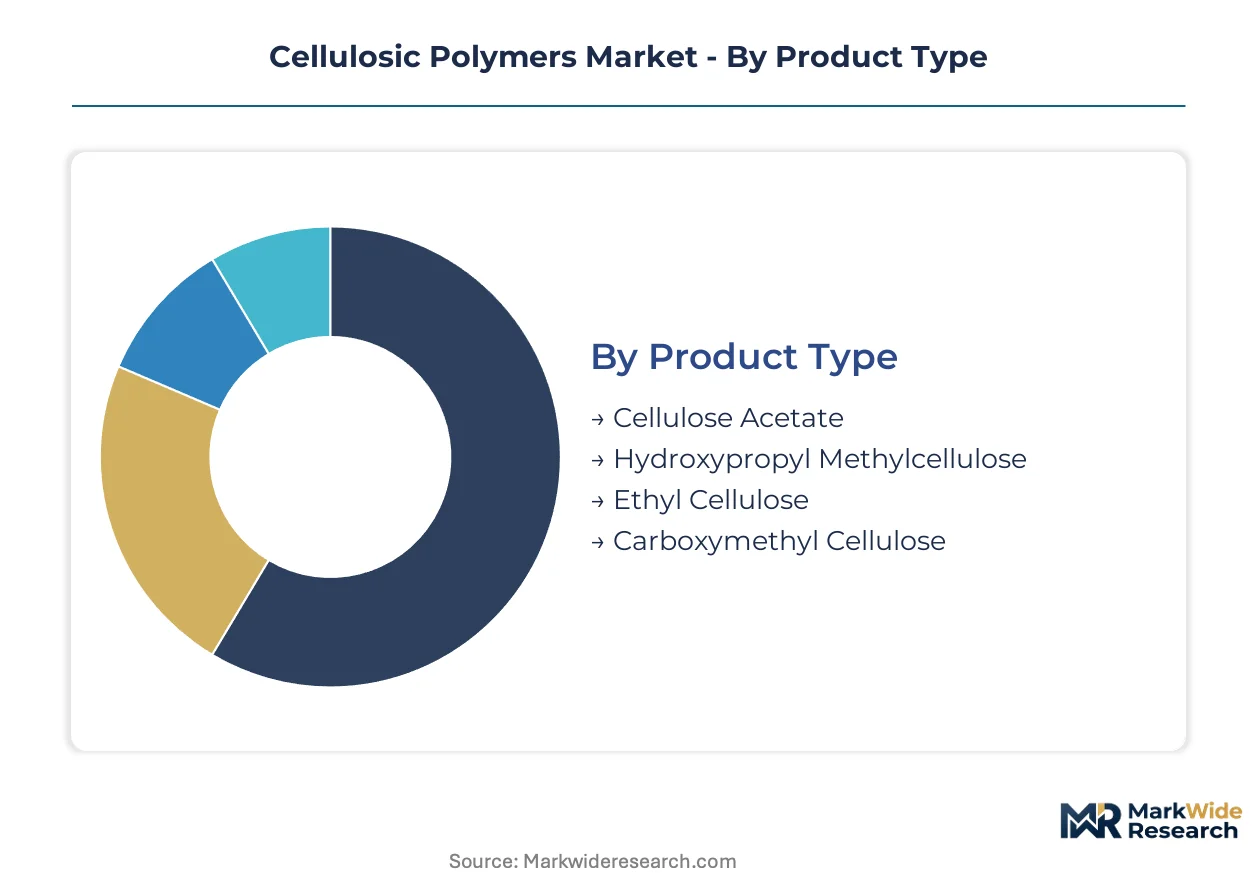
Cellulosic polymers serve fundamentally different performance roles depending on their chemical substitution patterns and physical form. Segmentation reveals where formulation complexity drives premium pricing versus where commodity substitution pressures dominate procurement decisions.
Product Type:
Integration depth varies sharply across cellulose derivatives, with some grades functioning as standalone film formers while others require complex compounding to achieve target rheology.
- Cellulose Acetate:Partially acetylated cellulose with degrees of substitution between 2.0 and 2.5 enables thermoplastic processing and solvent solubility for coating applications. Cigarette filter tow manufacturers in China and the United States absorb the majority of commodity-grade volumes, though pharmaceutical-grade specifications for enteric coatings command 3-4x price premiums.
- Hydroxypropyl Methylcellulose:Mixed ether substitution delivers thermal gelation properties critical for controlled-release tablet matrices and construction-grade cement retarders. Pharmaceutical formulators in India and China are qualifying this grade fastest for oral solid dosage systems, tightening purity specifications faster than suppliers can expand pharmaceutical-grade capacity.
- Ethyl Cellulose:Ethyl ether substitution produces water-insoluble, organosoluble films for sustained-release coatings and hot-melt adhesives.
- Carboxymethyl Cellulose:Anionic ether derivative with high water solubility serves thickening and water-retention functions in food systems and oilfield drilling fluids.
Volume placements concentrate in Cellulose Acetate; the faster expansion belongs to Hydroxypropyl Methylcellulose.
Application:
Application segments diverge by regulatory burden intensity, with pharmaceutical and food-contact channels imposing qualification barriers that filter out uncertified suppliers.
- Pharmaceuticals:Excipient and controlled-release matrix applications demand IPEC GMP certification and FDA Drug Master File documentation for market access. Hydroxypropyl methylcellulose and ethyl cellulose dominate oral solid dosage formulations, with Indian and Chinese generic manufacturers negotiating direct toll manufacturing agreements to secure supply continuity.
- Packaging:Regenerated cellulose films and cellulose acetate compounds displace conventional plastics in European fresh produce wrapping under single-use plastic directive pressure. Biodegradability certification and migration testing compliance create tiered supplier qualification.
- Textiles:Fiber applications leverage regenerated cellulose viscose and lyocell processes for apparel and industrial yarn production.
- Food Additives:Carboxymethyl cellulose and methylcellulose serve as thickeners, stabilizers, and emulsifiers in processed foods.
Revenue margins peak in Pharmaceuticals; Packaging captures the steepest expansion trajectory as regulatory pressure accelerates material substitution.
End Use Industry:
End-use concentration patterns reflect regional industrial structure, with construction demand scaling in infrastructure-intensive economies and personal care formulating in consumer markets with premium positioning.
- Cosmetics:Film-forming and rheology-modifying functions in color cosmetics and skincare formulations favor hydroxypropyl methylcellulose and ethyl cellulose grades with defined particle size distributions.
- Food & Beverage:Carboxymethyl cellulose dominates processed food thickening where water retention and freeze-thaw stability command specification compliance.
- Personal Care:Shampoo and toothpaste formulations drive methylcellulose and carboxymethyl cellulose demand for viscosity control and surfactant compatibility.
- Construction:Hydroxypropyl methylcellulose functions as cement retarder and water retention agent in ready-mix concrete, with Indian infrastructure build-out generating fastest regional demand growth for high-temperature pouring formulations.
Construction absorbs the largest tonnage volumes; Cosmetics generates the highest margin per kilogram through specialized grade specifications.
Form:
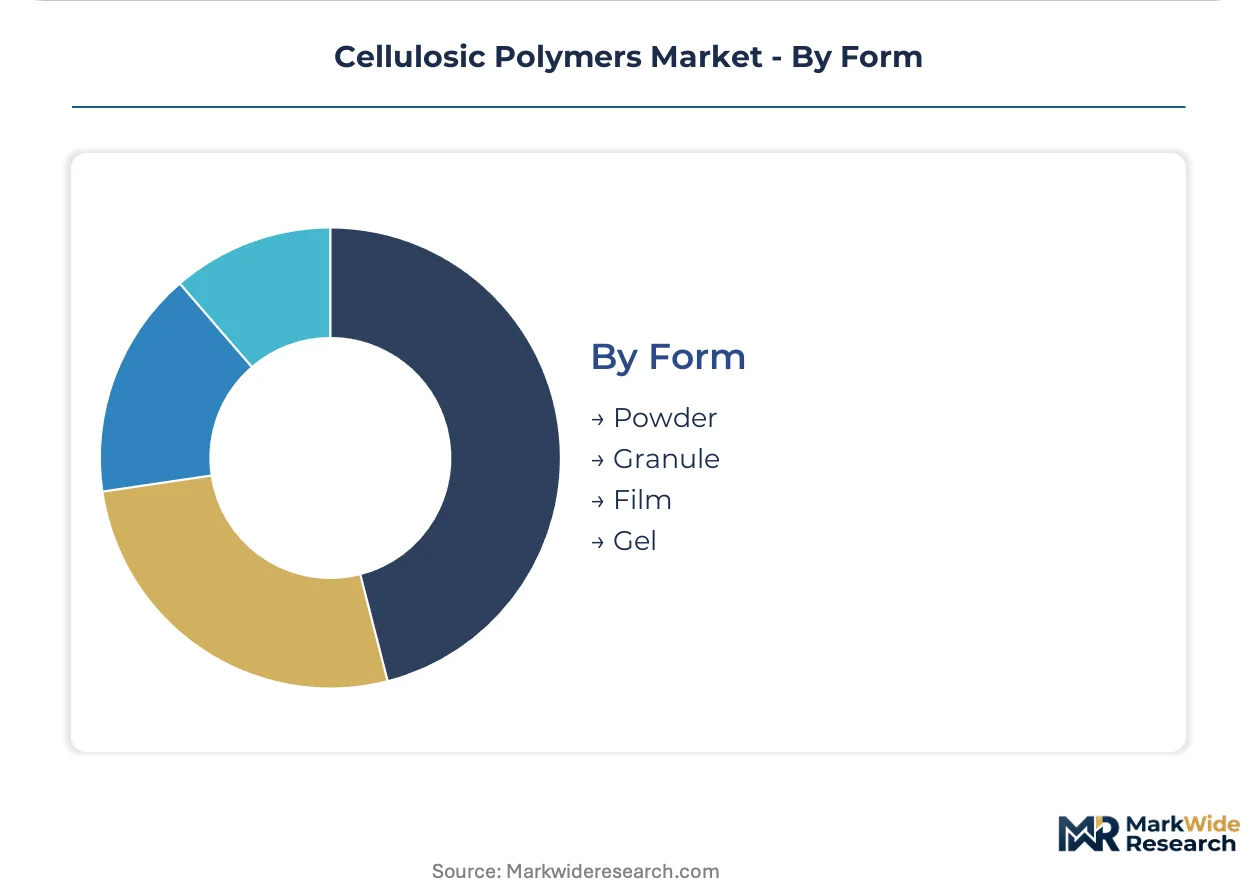
Physical form determines handling infrastructure requirements and dissolution kinetics, with powder dominating bulk chemical trade and film formats requiring dedicated processing equipment.
- Powder:Standardized particle size distributions enable direct dispersion in aqueous and solvent systems across pharmaceutical, food, and construction applications. Bulk handling and pneumatic conveying infrastructure supports high-volume procurement.
- Granule:Agglomerated formats reduce dusting and improve flow properties for direct compression tableting and dry-mix construction materials.
- Film:Regenerated cellulose and cellulose acetate films serve packaging and coating applications where clarity, barrier properties, and biodegradability create differentiated positioning.
- Gel:Pre-hydrated or concentrated gel forms simplify incorporation into personal care and pharmaceutical formulations where rapid dispersion and batch consistency reduce manufacturing variability.
Powder form commands the greatest shipment volumes; Film formats are climbing the fastest as sustainable packaging substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of cellulosic polymer demand through domestic excipient manufacturing and cigarette filter tow production. India and the United States follow as pharmaceutical formulation hubs with diverging regulatory pathways. European markets prioritize biodegradable packaging substitution under directive pressure.
China
Domestic hydroxypropyl methylcellulose production for controlled-release tablets is displacing imported pharmaceutical-grade volumes. SAMR's evolving excipient registration framework is tightening purity documentation requirements for local manufacturers. Zhejiang and Jiangsu provinces host expanding cellulose ether facilities serving both domestic drug formulators and export markets.
United States
Cellulose acetate demand from cigarette filter manufacturers concentrates in the Southeast manufacturing corridor. EPA's TSCA Section 5 notification requirements are extending pre-manufacture review timelines for novel cellulose derivatives. New Jersey and Delaware chemical processing clusters maintain legacy cellulose ester infrastructure serving coating and film applications.
Germany
REACH registration compliance costs are filtering non-certified cellulose derivative suppliers from food-contact and medical-grade channels. ECHA's substance evaluation protocols are intensifying migration testing burdens for packaging film producers. The Rhine-Ruhr industrial region retains specialized cellulose ester compounding capacity for pharmaceutical coating applications.
India
Infrastructure build-out is accelerating hydroxypropyl methylcellulose consumption for cement retarders in high-temperature concrete pouring. CDSCO's excipient quality guidelines are aligning with IPEC GMP standards for domestic generic drug manufacturers. Gujarat and Maharashtra pharmaceutical clusters are negotiating direct toll manufacturing agreements with cellulose derivative suppliers.
Brazil
Dissolving wood pulp supply from forestry operations underpins regional cellulose derivative feedstock security. ANVISA's pharmaceutical ingredient registration requirements are extending qualification timelines for imported excipient grades. São Paulo state hosts formulation facilities dependent on consistent specialty cellulose supply for controlled-release product development.
Cellulosic Polymers Market Competitive Environment
Capacity expansion dominates the current landscape as established producers retrofit solvent recovery systems and automate acetylation throughput. The market structure concentrates around integrated chemical conglomerates with captive pulp or acetic acid supply, mid-scale regional compounders serving pharmaceutical formulators, and specialty cellulose ether producers focused on construction and personal care segments. Strategic archetypes include backward-integrated pulp-to-derivative manufacturers, toll manufacturing specialists with IPEC GMP certification, and regional packaging film compounders. Competitive moves center on pharmaceutical-grade capacity expansion and direct procurement relationship formation with generic drug manufacturers.
Among North American chemical conglomerates, Eastman Chemical Company and Celanese Corporation occupy positions reflecting integrated cellulose ester technology platforms. Daicel Corporation anchors the Asia-Pacific supply base with operations in Japan. These three entities exemplify divergent geographic anchoring strategies while representing the scale-driven tier of the competitive landscape.
| Leading Market Players |
|---|
| Nouryon Chemicals Holding B.V. |
| Eastman Chemical Company |
| Celanese Corporation |
| DuPont |
| Daicel Corporation |
| Ashland |
| Dow, Inc. |
| Lenzing AG |
| Mitsubishi Chemical Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Acetic acid spot pricing volatility cascades through cellulose ester supply chains into stratified procurement tiers, with pharmaceutical-grade specifications commanding substantial premiums over commodity cigarette filter tow grades. Dissolving wood pulp contract structures in Brazil and South Africa anchor feedstock cost baselines that compounders pass through via long-term offtake agreements or spot-adjusted formulas.
Pricing Analysis
Volume placements concentrate in commodity cellulose acetate for filter tow while margin pools accrue to pharmaceutical-grade hydroxypropyl methylcellulose. Three-tier pricing structure across premium, standard, and economy levels separates IPEC GMP-certified excipients from food-grade and industrial specifications. Cost compression in standard-grade cellulose ethers is intensifying because Chinese domestic capacity expansion erodes import premiums. Generic drug manufacturers in India exhibit highest price sensitivity, while innovator pharmaceutical formulators prioritize supply security over unit cost optimization.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical formulators mandate multi-supplier qualification across cellulose ether and ester categories, forcing compounders to maintain redundant manufacturing relationships. Geographic supply concentration centers on China, the United States, and Germany for derivative production, with Brazil and South Africa anchoring dissolving pulp feedstock. Raw material dependencies rest on petrochemical-derived acetic acid, dissolving wood pulp, and methylation reagents. Single-source vulnerability in Brazilian forestry operations creates structural risk for specialty cellulose supply security. Distribution runs through direct toll manufacturing agreements for pharmaceutical volumes and distributor networks for industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as REACH registration burdens and IPEC GMP certification timelines filter uncertified producers from high-value pharmaceutical channels, forcing capital-constrained compounders toward commoditized industrial segments or exit.
For Market Incumbents: Deploy continuous acetylation reactor technology to automate throughput and compress batch cycle times from hours to minutes, defending against emerging nanocellulose substitution in food and personal care thickening applications. Capture backward integration into captive dissolving pulp supply through long-term forestry concessions in Brazil or South Africa, insulating margin structures from feedstock price volatility and single-source concentration risk. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade hydroxypropyl methylcellulose offers entry traction for toll manufacturing specialists willing to absorb 18-24 month IPEC GMP qualification timelines. Target construction-grade cement retarder demand in India's infrastructure build-out, where high-temperature pouring formulations drive specification compliance without pharmaceutical certification barriers. Pursue toll manufacturing agreements with domestic generic drug manufacturers as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale cellulose ether producers with existing SAMR registration in China and underutilized esterification capacity, particularly those stranded by acetic acid margin pressure. Long-term viability hinges on pharmaceutical-grade certification density rather than commodity volume scale. Watch CDSCO excipient guideline alignment with IPEC GMP standards as the inflection signal for Indian market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Capacity Expansion | IPEC GMP certification unlocks direct toll manufacturing agreements with Indian and Chinese generic drug formulators. |
| Backward Integration into Dissolving Pulp | Captive forestry operations in Brazil insulate cellulose ester producers from South African supply concentration risk. |
| Continuous Acetylation Technology Deployment | Automated reactor systems reduce solvent inventory and energy intensity per ton for coating and film compounders. |
| Biodegradable Packaging Film Scale-Up | Cellulose acetate compounds displace conventional plastics in European fresh produce wrapping under single-use plastic directive pressure. |
| Construction Cement Retarder Formulation Partnership | Hydroxypropyl methylcellulose qualification with Indian ready-mix concrete producers captures infrastructure build-out demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving pharmaceutical formulators, cellulose derivative plant managers, procurement leads at coating compounders, and ECHA registration consultants. Bottom-up volume modeling triangulated against top-down value estimates derived from SEC 10-K disclosures, Cefic sector reports, and SAMR excipient registration databases.
Data-stream reconciliation across shipment volumes, capacity utilization rates, and price realization data informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product substitution pattern, end-use industry, grade certification tier, and regional production hub. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand drivers, incorporating acetic acid price correlation coefficients and pharmaceutical formulation pipeline data as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade excipient volumes carry tighter precision than commodity cellulose acetate for filter tow due to mandatory batch documentation. Forecasts reflect assumptions regarding REACH registration timeline stability, SAMR guideline evolution, and acetic acid feedstock price correlation persistence. Deviation in IPEC GMP certification backlog duration or Brazilian pulp supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Global Thermosetting Polymer Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market