
 Light Weapons Market | 2026-2036
Light Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Light Weapons Market Intelligence
Increased reliance on national-level defense budgets and long-term procurement contracts is fragmenting the competitive landscape for smaller suppliers. Heckler & Koch GmbH specializes in precision-engineered arms for elite special forces units globally. FN Herstal S.A. leverages its extensive portfolio to secure large-scale, multi-year military contracts. Meanwhile, Glock Ges.m.b.H dominates the global law enforcement handgun market through its focus on polymer-framed pistols and strong distribution channels.
Light weapons are defined as portable firearms operable by an individual or a small crew, typically under 20kg. These systems are technically differentiated by their operating mechanism, such as gas-operated or blowback designs, and specific ammunition caliber. Their primary purpose is to provide direct fire for infantry and law enforcement units. Assault Rifles constitute the largest segment for military forces, while Pistols are standard for police. The Sniper Rifles category commands high margins due to specialized optics and precision manufacturing.
The market operates under strict regulatory controls, including the US International Traffic in Arms Regulations (ITAR) and EU directives governing firearm exports. National procurement standards, such as those from Germany's Federal Office of Bundeswehr Equipment (BAAINBw), dictate technical specifications and testing protocols. These complex rules shape international market access and product development cycles. Navigating disparate and politically sensitive regulatory frameworks is a core strategic challenge for all manufacturers.
Market Dynamics
The central force shaping the light weapons market is the doctrinal shift towards modular, multi-caliber weapon systems. This evolution is driven by the need for operational flexibility across diverse combat environments, pushing procurement away from single-purpose firearms towards adaptable platforms.
Growth Catalysts
- Modular Platforms:The adoption of modular weapon systems allows for mission-specific customization, reducing total lifecycle costs for military and law enforcement agencies. This supports demand for interchangeable components like barrels, stocks, and optics.
- Infantry Modernization Programs:Nations like India and Poland are executing large-scale infantry and border security upgrades, creating significant demand for new assault rifles and machine guns to replace legacy equipment.
- Police Force Upgrades:Global police modernization initiatives are driving demand for compact, polymer-based pistols and submachine guns suitable for urban law enforcement, particularly for patrol and special weapons and tactics units.
Market Restraints
- Export Control Regimes:Strict regulations like the US International Traffic in Arms Regulations (ITAR) and equivalent EU directives create significant compliance burdens and lengthen sales cycles, limiting market access for suppliers in non-allied nations.
- High Cost of Advanced Materials:The use of lightweight composites and advanced alloys in manufacturing increases unit costs, creating a price barrier for budget-constrained military and police forces in emerging economies and slowing widespread adoption.
- Specialized Optics Dependency:Reliance on a concentrated group of suppliers for high-performance optics and fire control systems creates supply chain vulnerabilities and pricing pressure, particularly for advanced sniper and designated marksman rifles.
Strategic Opportunities
- Smart Weapon Integration:Integrating digital fire control, target tracking, and networked communication capabilities into small arms offers an opportunity to enhance soldier lethality, creating a new premium product tier for advanced military customers.
- Southeast Asian Defense Spending:Rising defense budgets in countries like Vietnam and the Philippines, driven by regional security concerns, present an opportunity for suppliers of patrol carbines and light machine guns for maritime and border security forces.
- Less-Lethal System Development:Demand from law enforcement for de-escalation tools provides an opportunity to develop advanced less-lethal systems, such as next-generation kinetic energy launchers, as adjuncts to conventional firearms.
Industry Challenges
- Navigating Disparate Procurement Standards:Manufacturers face the challenge of adapting core platforms to meet divergent technical specifications and testing protocols from national bodies like Germany's BAAINBw, increasing product development costs and time-to-market.
- Integration with Legacy Infantry Gear:Ensuring new weapon systems are fully compatible with existing soldier equipment, including body armor, load-bearing vests, and communication headsets, presents a significant design and testing challenge for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Weapons Market |
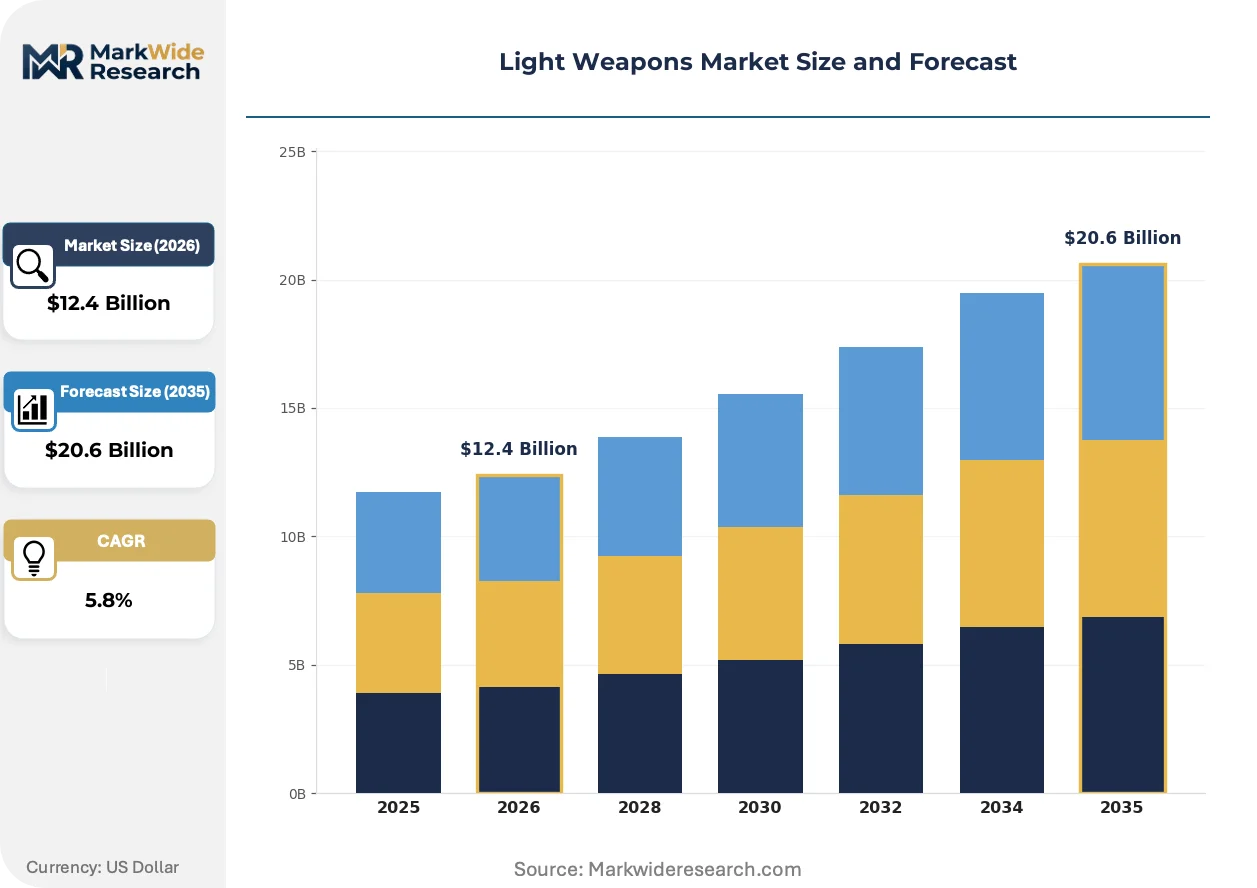
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assault Rifles, Submachine Guns, Sniper Rifles, Machine Guns, Pistols, Carbines Technology: Semi-Automatic, Automatic, Bolt-Action, Gas-Operated, Blowback, Lever-Action Application: Military Forces, Law Enforcement, Security Agencies, Paramilitary Groups, Private Security, Special Operations End User: Defense Contractors, Tactical Units, Homeland Security, Peacekeeping Forces, Counterterrorism Teams, Border Patrol |
| Companies Covered | Fabbrica d’Armi Pietro Beretta S.p.A., Lockheed Martin Corporation, FN Herstal S.A., General Dynamics Corporation, Rheinmetall AG, Heckler & Koch GmbH, BAE Systems plc, Glock Ges.m.b.H, SIG Sauer GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Weapons Market Strategic Shifts & Innovations
The light weapons sector is undergoing a fundamental transformation as digital technologies are integrated into mechanical platforms. This convergence is altering weapon functionality, procurement criteria, and the very definition of soldier lethality in modern warfare and law enforcement scenarios.
Integrated fire control systems combine laser rangefinders, ballistic computers, and environmental sensors. Special operations and elite infantry units are the primary adopters, seeking to increase first-round hit probability at extended ranges. This technology is digitizing the engagement sequence, transforming the rifle into a data-driven weapon system.
EU directives governing firearms exports, alongside national controls, are becoming increasingly stringent. These regulations require manufacturers to implement rigorous end-user verification, adding complexity to international sales. The Sniper and Assault Rifles segments are most affected, forcing investment in compliance to secure military contracts.
Military buyers are acquiring complete weapon systems, including optics, suppressors, and ammunition, as a single package. This disrupts the model of sourcing components separately, favoring manufacturers who act as system integrators. This trend is most visible in infantry modernization programs within NATO countries and India.
Light Weapons Market Segmentation
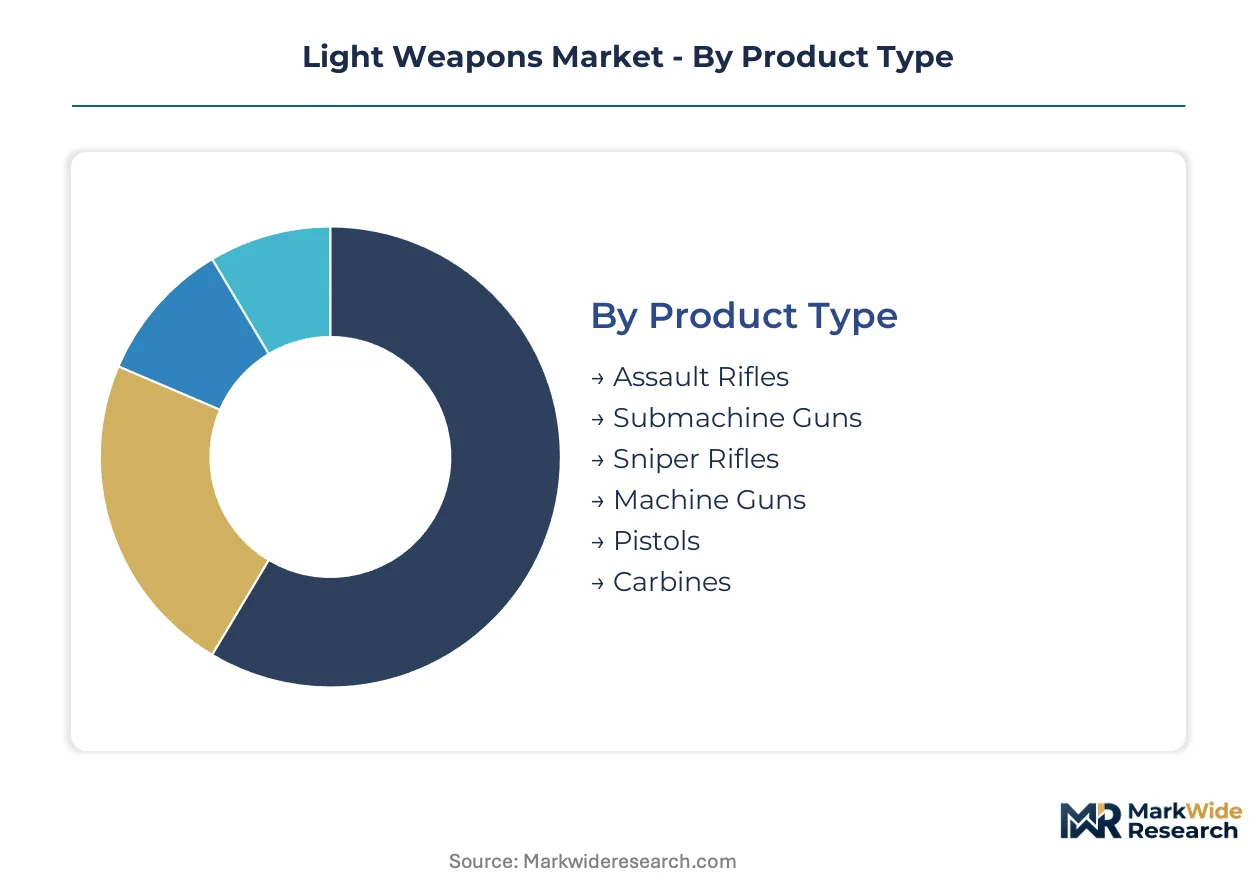
The light weapons market segments by product type, underlying technology, application, and end user, reflecting diverse operational requirements across military and law enforcement agencies. Understanding these distinctions helps manufacturers tailor product development and market penetration strategies for specific defense and security needs.
Product Type:
The intensity of after-sales service and long-term maintenance contracts often varies significantly across different light weapon product types, influencing total cost of ownership for procurement agencies.
- Assault Rifles:These gas-operated or direct impingement firearms fire intermediate cartridges, providing a balance of range, accuracy, and rate of fire for infantry forces. Demand concentrates in nations like India and Poland for large-scale infantry modernization programs.
- Pistols:Compact, semi-automatic handguns, frequently polymer-framed, serve as standard sidearms for law enforcement and military personnel. Global police force upgrades drive significant demand for these reliable, easy-to-carry weapons.
- Submachine Guns:These automatic or semi-automatic firearms chamber pistol-caliber ammunition, optimized for close-quarters combat and urban environments. Security agencies and special operations units utilize submachine guns for their high rate of fire and maneuverability.
- Sniper Rifles:High-precision, long-range rifles, often bolt-action, equipped with specialized optics for designated marksmen and special forces. These weapons command high margins due to their precision manufacturing.
- Machine Guns:Fully automatic firearms designed for sustained suppressive fire, available in light, medium, and heavy variants for infantry support. Military forces globally deploy machine guns for area denial and firepower.
- Carbines:Shorter, lighter variants of rifles, providing enhanced maneuverability for vehicle crews, special operations, and certain law enforcement roles. These weapons are increasingly popular for close-in engagements.
By volume, Assault Rifles typically lead the market. By growth pace, Pistols represent the fastest-growing trajectory due to widespread police modernization initiatives.
Technology:
The cost tier of light weapons is often dictated by the complexity and precision of their operating mechanisms, with advanced designs requiring more sophisticated manufacturing processes.
- Gas-Operated:This mechanism uses gas from the fired cartridge to cycle the action, common in modern assault rifles and machine guns for reliability and sustained fire. Many contemporary military platforms leverage gas-operated designs.
- Semi-Automatic:These firearms fire one round per trigger pull and automatically reload, widely used in pistols, carbines, and some rifles for both military and civilian markets. Law enforcement agencies primarily equip officers with semi-automatic pistols.
- Automatic:These weapons continue to fire as long as the trigger is depressed and ammunition remains, primarily found in machine guns and some assault rifles for military applications. Special operations units deploy automatic weapons for superior suppressive fire.
- Bolt-Action:A manual operating system where the user manipulates a bolt to load, fire, and eject cartridges, favored for its simplicity and inherent accuracy in sniper rifles. Precision shooting relies heavily on bolt-action mechanisms.
- Blowback:This simple operating system uses the pressure of expanding gases directly against the bolt to cycle the action, commonly found in submachine guns and smaller caliber pistols. Many less powerful firearms utilize blowback designs.
- Lever-Action:A manual operating system using a lever to cycle the action, primarily found in hunting rifles and niche applications due to its historical design. This technology holds a small share in the contemporary market.
Semi-Automatic technology captures the largest market share. Gas-Operated mechanisms are seeing the steepest expansion trajectory driven by new military procurement.
Application:
The volume of light weapons procurement is heavily influenced by the specific application, with large-scale military and law enforcement requirements driving the highest unit demand.
- Military Forces:National armies and armed forces are the primary users of light weapons, procuring assault rifles, machine guns, and sniper rifles for infantry operations. Infantry modernization programs globally drive substantial military demand.
- Law Enforcement:Police departments and federal agencies equip officers with pistols, submachine guns, and carbines for patrol and tactical operations. Urban law enforcement units increasingly require compact, reliable firearms.
- Special Operations:Elite military and law enforcement units require highly specialized and customizable light weapon systems, often integrating advanced optics and modular components. These units prioritize adaptability and precision.
- Border Patrol:Agencies responsible for border security utilize patrol carbines, light machine guns, and pistols to secure national frontiers. Countries like India and Poland are upgrading their border security capabilities.
- Security Agencies:Government intelligence and security organizations employ a range of light weapons for protective details, counter-terrorism, and covert operations. These agencies often require discreet and reliable firearms.
- Paramilitary Groups:Non-state armed groups and auxiliary forces acquire light weapons for various operational objectives, often through illicit channels or support from foreign entities. This segment operates outside formal procurement.
Military Forces represent the largest segment by procurement volume. Special Operations applications exhibit significant growth in demand for specialized, high-margin systems.
End User:
Customer type significantly shapes product specifications and procurement processes, from the rigorous standards of tactical units to the broader needs of homeland security agencies.
- Tactical Units:Highly trained military and law enforcement teams requiring specialized, high-performance light weapons with advanced features and modularity. These units often influence product innovation for precision and adaptability.
- Border Patrol:Agencies responsible for securing national borders, demanding durable and reliable light weapons suitable for diverse environmental conditions and extended operations. India and Poland are investing heavily in border security equipment.
- Homeland Security:Domestic security agencies and federal organizations procuring light weapons for critical infrastructure protection, counter-terrorism, and emergency response. These agencies require versatile firearms for various scenarios.
- Defense Contractors:Entities that supply military forces, often acting as integrators for complete weapon systems including firearms, optics, and ammunition. These contractors manage complex supply chains for national defense.
- Counterterrorism Teams:Specialized units focused on preventing and responding to terrorist threats, requiring highly accurate and adaptable light weapon systems for urban and close-quarters engagements. These teams prioritize rapid deployment capabilities.
- Peacekeeping Forces:Military and police contingents deployed for international peacekeeping missions, requiring standard issue light weapons for self-defense and maintaining order. These forces often operate under strict rules of engagement.
Tactical Units drive demand for premium, high-specification products. Border Patrol represents a rapidly expanding customer segment due to geopolitical concerns and modernization efforts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The light weapons market exhibits a pricing power asymmetry, where established manufacturers in Western nations command higher margins for advanced systems compared to the more cost-sensitive procurement in emerging economies. This dynamic influences technology transfer and localized production agreements. National defense budgets and long-term procurement contracts shape regional demand.
United States
Demand for specialized light weapons stems from tactical units and ongoing military modernization. The US International Traffic in Arms Regulations (ITAR) strictly governs export controls, influencing global market access. Major defense contractors in states like Virginia and California drive innovation and system integration.
Germany
Procurement for precision-engineered arms is driven by elite special forces units and national defense requirements. The Federal Office of Bundeswehr Equipment (BAAINBw) sets stringent technical specifications for weapon systems. Manufacturers like Heckler & Koch GmbH in Oberndorf am Neckar specialize in high-end military firearms.
India
Significant infantry modernization programs and border security upgrades fuel substantial demand for assault rifles and machine guns. The "Make in India" initiative encourages domestic manufacturing and technology transfer for defense procurement. Production facilities in cities like Kanpur and Jabalpur are expanding to meet national requirements.
Poland
Border patrol and infantry upgrades are generating strong demand for new light weapon systems. National procurement standards guide the acquisition of new equipment for its armed forces and law enforcement. Defense industries in cities such as Radom are upgrading production capabilities for modern small arms.
Vietnam
Rising defense budgets, driven by regional security concerns, create opportunities for patrol carbines and light machine guns. The Ministry of National Defense oversees military procurement, prioritizing equipment for maritime and border security forces. State-owned defense enterprises in Hanoi are focusing on local assembly and maintenance.
Light Weapons Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical sub-assemblies. The light weapons market features a tiered structure, with a few large defense conglomerates alongside numerous specialized manufacturers. Key archetypes include full-system providers, high-precision niche specialists, and mass-market handgun suppliers. Strategic partnerships for technology transfer and portfolio diversification into complete weapon systems are dominant competitive moves.
Within the specialized weapon archetype, Germany-based Heckler & Koch GmbH exemplifies precision engineering for elite special forces, focusing on high-performance military firearms. Belgium's FN Herstal S.A. represents a major player securing large-scale military contracts through an extensive product portfolio spanning various weapon types. Austria's Glock Ges.m.b.H occupies a distinct position, dominating the global law enforcement handgun market with its polymer-framed pistols and robust distribution channels. These entities collectively anchor specific market segments, influencing product development and market access strategies across diverse end-user requirements.
| Leading Market Players |
|---|
| Fabbrica d’Armi Pietro Beretta S.p.A. |
| Lockheed Martin Corporation |
| FN Herstal S.A. |
| General Dynamics Corporation |
| Rheinmetall AG |
| Heckler & Koch GmbH |
| BAE Systems plc |
| Glock Ges.m.b.H |
| SIG Sauer GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Regional production capacity expansion in nations like India and Poland influences supplier behavior by increasing competition for domestic contracts. This expanding utilization drives pricing posture, particularly for standard assault rifles and pistols in these upgrading markets.
Pricing Analysis
Configured-to-order pricing for elite units contrasts with per-unit transactional pricing for large-scale military and law enforcement procurement. Price differentiation stems from customization level for specialized optics and after-sales service contracts, especially for advanced sniper rifles. Pricing pressure stems from specialized optics dependency, particularly for high-performance systems. Budget-constrained military and police forces in emerging economies exhibit high price sensitivity, while special operations units prioritize performance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, reflecting the long procurement cycles in the light weapons market. Supply concentration centers on established manufacturers in the United States, Germany, and emerging production hubs in India. Raw material dependencies include advanced polymer composites and specialized optics, where single-source vulnerability poses a structural supply chain risk. Integrated system delivery through defense contractors dominates the downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The light weapons market presents a significant service-attach opportunity, particularly as after-sales service and long-term maintenance contracts expand faster than hardware unit sales. This recurring revenue stream enhances total lifecycle value for manufacturers and procurement agencies.
For Market Incumbents:Insulate core market share by deepening vertical integration into specialized optics and advanced materials. Incumbents should also invest heavily in compliance capabilities for stringent export control regimes like ITAR, mitigating the threat of market access restrictions. Diversifying product portfolios into complete weapon systems, including ammunition and suppressors, enhances value capture and customer stickiness. This strategy reinforces their position against emerging modular platform providers.
For New Entrants and Emerging Players:Southeast Asian defense spending for maritime and border security forces represents a significant geographic underpenetration for new entrants. Target law enforcement agencies with advanced less-lethal systems or cost-effective, polymer-based pistols for urban patrol. A go-to-market angle focusing on rapid customization and local assembly partnerships can circumvent high material costs and export control complexities. This approach allows for agile market entry in underserved segments.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the smart weapon integration sub-segment, driven by R&D in digital fire control and networked communication. Long-term viability over the next decade appears strong, supported by sustained defense budgets and modernization programs. Acquisition targets should include high-precision niche specialists in optics or advanced material manufacturing, or software firms focused on digital weapon integration. The signal to watch is the adoption rate of integrated fire control systems by elite units.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Smart Weapon Technologies | Enhances soldier lethality and creates a premium product tier for advanced military customers. |
| Expand After-Sales Service Contracts | Increases recurring revenue and strengthens long-term customer relationships with procurement agencies. |
| Form Regional Manufacturing Partnerships | Facilitates market access and mitigates export control burdens in key growth nations like India. |
| Diversify into Less-Lethal Systems | Addresses rising demand from law enforcement for de-escalation tools and broadens product utility. |
| Invest in Advanced Material R&D | Reduces weapon weight and improves performance, appealing to modern infantry and special forces requirements. |
Research Approach
The analysis maps light weapon product types and end-user applications, each validated through extensive primary interviews with procurement officers and R&D engineers. This involved conversations with defense contractors and regulatory compliance specialists. Secondary validation drew from national defense budgets, EU export directives, and Germany's BAAINBw specifications. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
The forecast framework held geopolitical stability and major regulatory regimes fixed, while varying defense budget allocations and technological adoption rates across the analysis window. Segmentation dimensions modeled included product type, operating technology, military and law enforcement applications, and end-user categories. Compound Annual Growth Rates were derived from historical growth trends and projected adoption rates. Key inputs included infantry modernization program timelines and police force upgrade budgets.
Practitioners should monitor geopolitical shifts and new export control legislation for early signals impacting market dynamics. Forecasts reflect assumptions documented at the time of publication. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Electrical Weapon Market