
 Europe Medium and Large Caliber Ammunition Market | 2026-2036
Europe Medium and Large Caliber Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medium and Large Caliber Ammunition Market Foresight
Market Context
The EU Green Deal is decoupling legacy ammunition demand from conventional manufacturing footprints across European defense supply chains. Rheinmetall AG leverages its pan-European production network to sustain shell and propellant output at scale. KNDS N V anchors Franco-German collaboration through joint artillery programs and shared manufacturing assets. BAE Systems plc competes on naval and land systems integration while extending its ammunition capabilities through British and Swedish facilities.
Technical Definition and Segments
Europe medium and large caliber ammunition encompasses projectiles, shells, and cartridges ranging from 20mm to 155mm, typically employing steel or tungsten penetrators, brass cartridge cases, and nitrocellulose-based propellants for direct and indirect fire weapons. These munitions serve military combat, training exercises, and law enforcement operations requiring kinetic energy delivery, area suppression, or precision engagement against hardened targets. Shells and projectiles dominate current procurement volumes as NATO members replenish depleted artillery stockpiles, while smart munitions and guided systems represent the fastest-expanding technology segment where margin pools concentrate due to sensor integration and precision requirements. Conventional ammunition retains mature, high-volume status across training applications where cost-per-round sensitivity limits premium technology uptake.
Regulatory Framework
REACH, RoHS, and the EU Green Deal collectively restrict toxic substances in propellants and primers while mandating environmental accountability across ammunition life cycles. ECHA chemical classification rules and national defense procurement standards from BSI and DIN shape product specifications, testing protocols, and cross-border transfer compliance. Stakeholders must monitor evolving EU defense procurement directives and environmental liability frameworks that will determine which manufacturers can retain access to continental supply chains.
Market Dynamics
NATO artillery replenishment mandates and EU Green Deal environmental compliance are forcing simultaneous capacity expansion and manufacturing retooling across European ammunition plants. Defense ministries now require dual-capable production lines that satisfy battlefield performance standards while eliminating toxic propellant residues.
Growth Catalysts
- REACH chemical restrictions:The EU Green Deal's phased elimination of lead-based primers and heavy metal stabilizers is accelerating R&D investment in green propellant chemistry. Manufacturers securing ECHA pre-registration for novel formulations gain preferred supplier status in German and French tenders.
- Polish land force modernization:Warsaw's accelerated artillery brigade expansion is absorbing surplus shell capacity from Rheinmetall's Unterlüß facility and drawing joint venture investment into new Polish production lines.
- Insensitive munitions (IM) standards:STANAG 4439 compliance requirements for cook-off resistance are filtering procurement specifications. IM-certified propellants and warheads now dominate NATO shared stockpile agreements.
Market Restraints
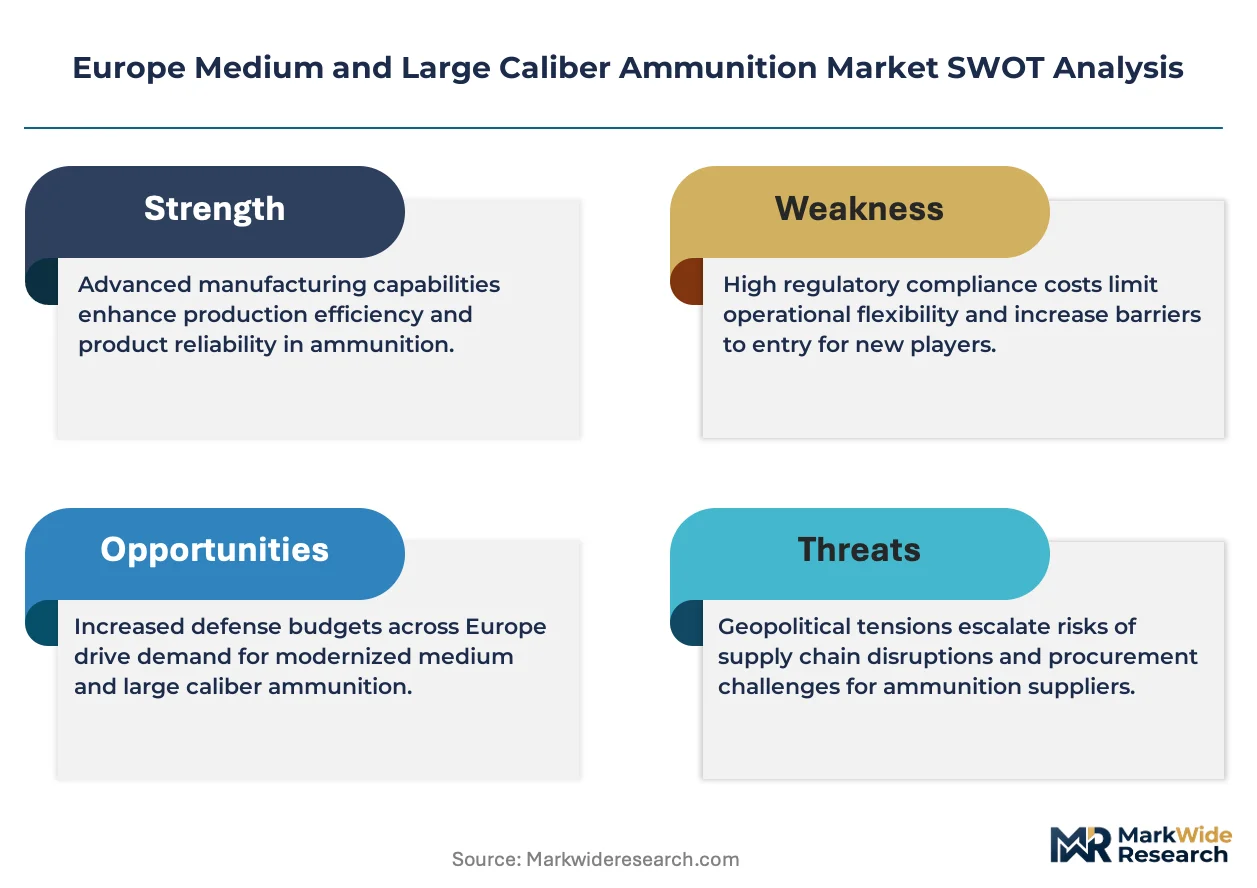
- Nitrocellulose supply concentration:European propellant manufacturers depend on cotton linters and wood pulp supply chains concentrated in Brazilian and Chinese chemical processing. Price volatility in these feedstocks directly compresses propellant margins.
- RoHS substance restrictions:The directive's extension to defense exemptions remains contested, creating regulatory uncertainty for primer manufacturers using lead styphnate and barium nitrate compositions.
- Long-lead capital equipment:Hydraulic press forging lines for 155mm shell bodies require 24-36 month procurement cycles. Equipment scarcity limits capacity expansion velocity regardless of order backlog.
Strategic Opportunities
- Romania and Bulgaria:These NATO members maintain underutilized Soviet-era ammunition plants now receiving modernization funding through the European Peace Facility. Greenfield IM-compliant production lines here could serve Black Sea deterrence requirements.
- Guided mortar rounds:GPS-assisted 120mm munitions for urban close-support missions represent an emerging application segment. Integration of MEMS inertial units with semi-active laser seekers is collapsing precision engagement costs.
- CSRD supply chain disclosure:The Corporate Sustainability Reporting Directive mandates Scope 3 emissions tracking. Ammunition producers with verified low-carbon propellant supply chains will qualify for preferential EU defense procurement scoring.
Industry Challenges
- Propellant chemist scarcity:Europe retains fewer than 200 specialists capable of formulating nitrocellulose-based energetic materials. Retirement waves at state-owned research institutes threaten knowledge transfer continuity.
- NATO qualification timelines:New ammunition variants require 18-24 months of live-fire testing across multiple national proving grounds. These certification cycles delay revenue recognition despite signed procurement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medium and Large Caliber Ammunition Market |
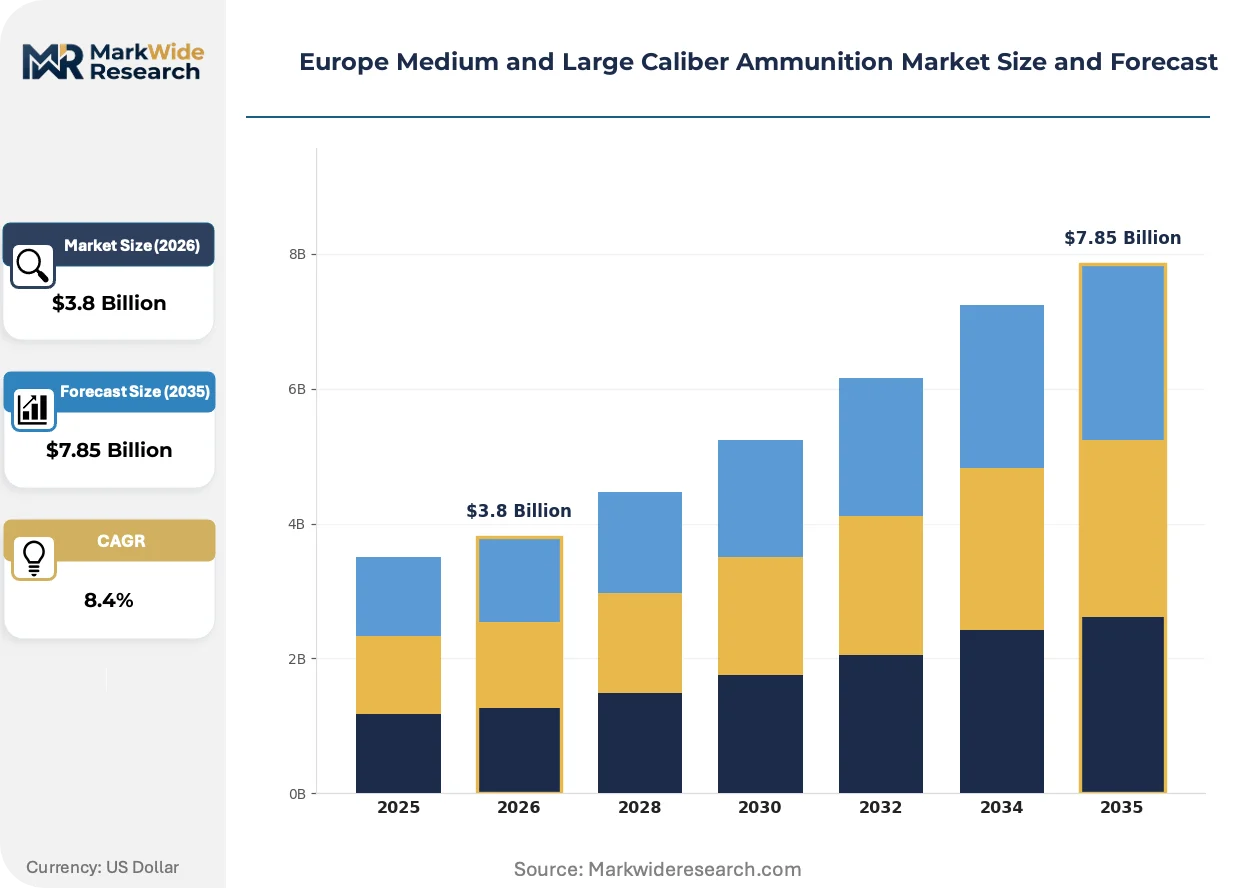
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shells, Cartridges, Projectiles, Ammunition Kits End User: Military, Law Enforcement, Defense Contractors, Civilian Users Application: Combat, Training, Hunting, Law Enforcement Operations Technology: Conventional, Smart Munitions, Guided Systems, Fragmentation |
| Companies Covered | KNDS N V, Northrop Grumman Corporation, Rheinmetall AG, Leonardo S p A, RTX Corporation, BAE Systems plc, Nammo AS, Diehl Stiftung & Co KG, General Dynamics Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medium and Large Caliber Ammunition Market Shifts & Advancements
Digital manufacturing and environmental compliance are converging to transform how European ammunition is formulated, produced, and procured. Smart factory investments now compete with green chemistry R&D for capital allocation priority.
Modular artillery charge systems is rewriting propellant logistics. Germany's Bundeswehr and France's Armée de Terre are fielding variable-zone modular charges that reduce barrel wear and simplify supply chains. This technology is rewriting inventory management economics by collapsing the SKU count for artillery batteries from dozens of charge types to three standardized modules.
REACH authorization requirements for diisocyanates in polymer binders are forcing reformulation of composite case ammunition. Industrial consequence includes accelerated adoption of thermoplastic elastomer alternatives in shell driving bands and obturator rings. Naval gun ammunition programs are most affected, with British and Swedish manufacturers submitting substance substitution plans to ECHA ahead of 2025 sunset dates.
Joint procurement consortia through the European Defence Agency are consolidating national ammunition tenders into framework contracts spanning multiple calibers and services. France, Germany, Belgium and the Netherlands now coordinate 155mm shell purchases through the Collaborative Procurement of Ammunition initiative. This buyer-side concentration is most visible in Central European land forces, where national stockpile targets are harmonized through NATO force planning cycles.
Europe Medium and Large Caliber Ammunition Market Segmentation
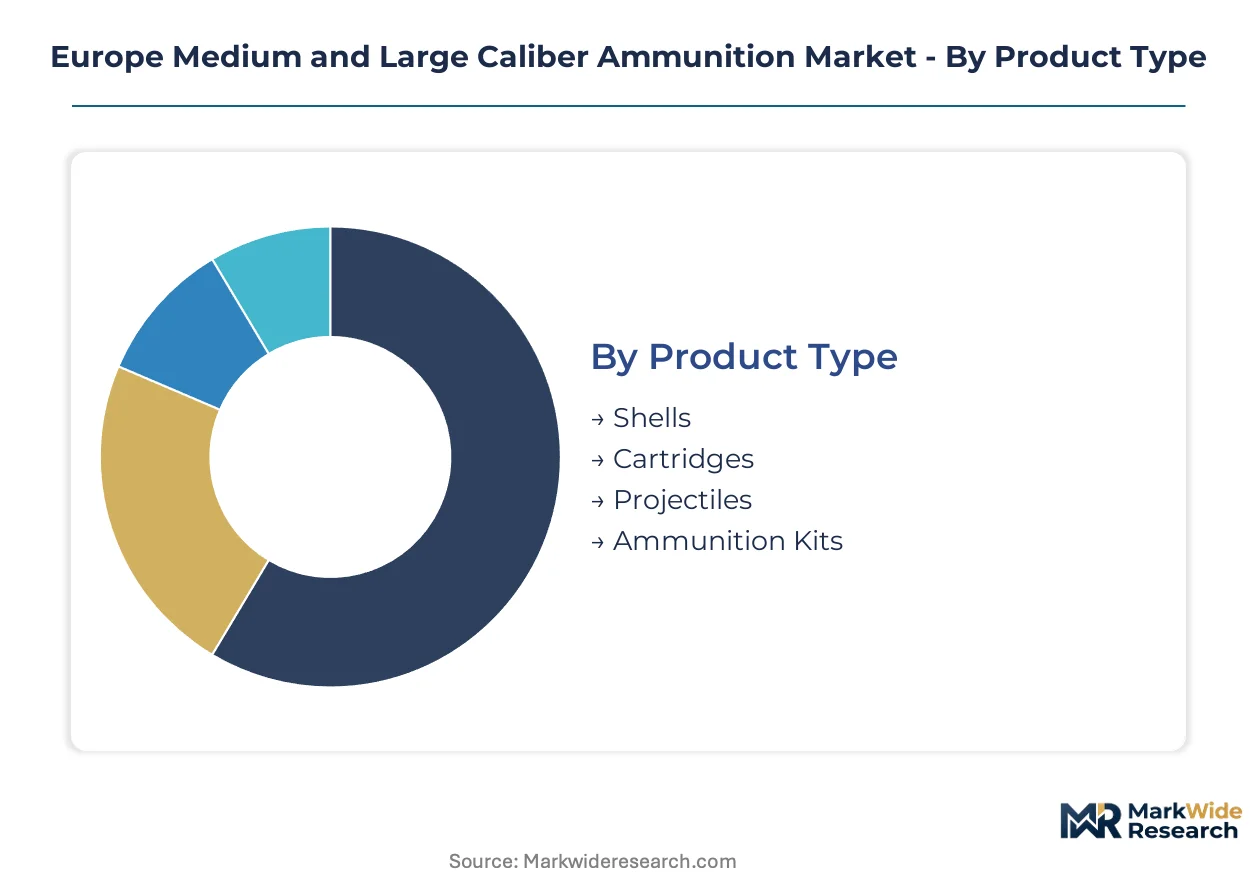
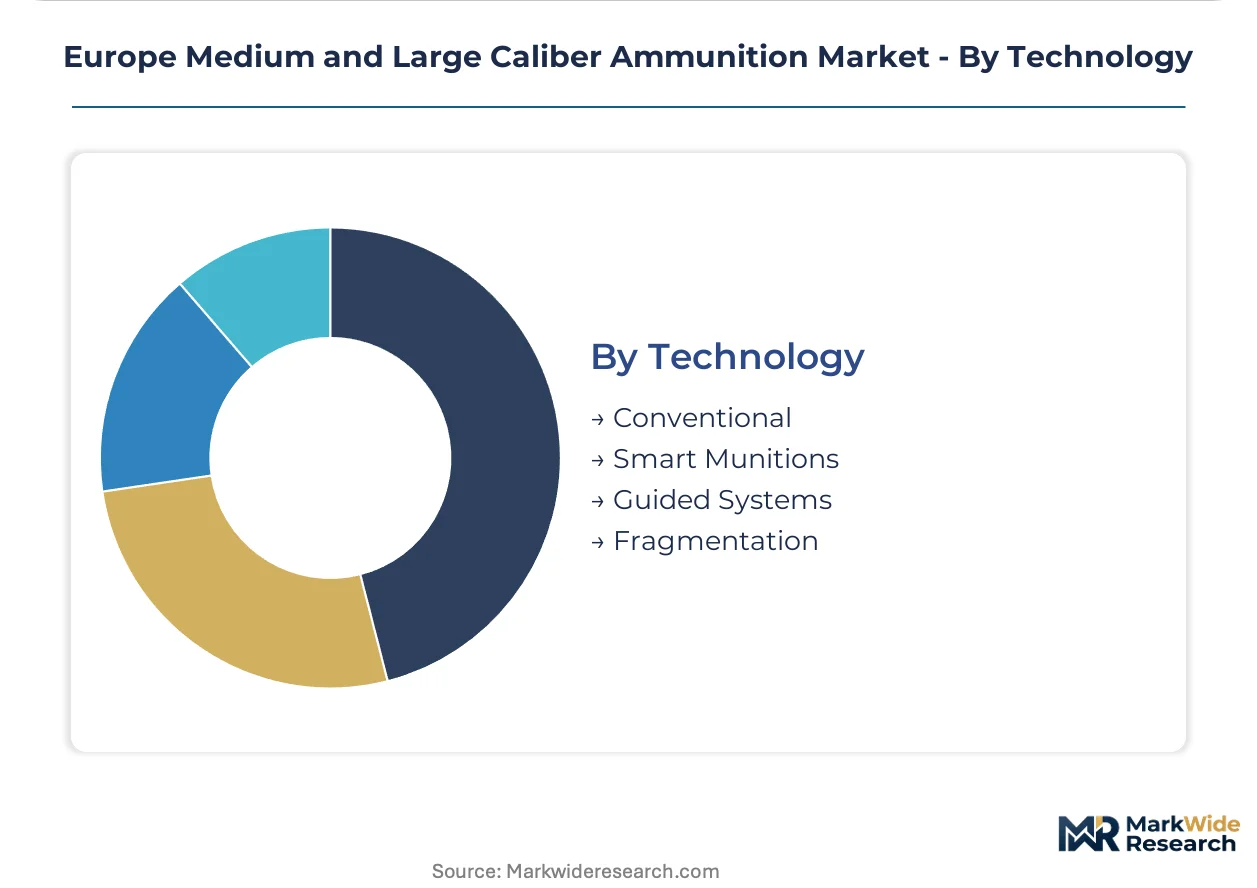
Segmentation in European medium and large caliber ammunition reveals how procurement priorities diverge between volume-intensive training requirements and precision-guided combat systems. Defense ministries structure tenders around product type and technology tiers, while end-user categories determine qualification standards and transfer compliance protocols.
Product Type:
Defense ministries weight shelf-life stability and interoperability certification when selecting among product formats.
- Shells:Steel-cased 155mm and 120mm artillery shells dominate NATO replenishment contracts. German and Polish land forces absorb the majority of European shell output as both nations rebuild strategic stockpiles depleted by donations to Ukraine.
- Projectiles:These kinetic penetrators and high-explosive fillers employ tungsten or steel cores with variable fragmentation patterns. French and British naval gun programs drive specialized projectile demand for surface-to-surface engagement beyond 50km.
- Cartridges:Brass or steel-cased ammunition linking propellant to projectile serves automatic cannon systems from 20mm to 40mm.
- Ammunition Kits:Modular packaging combines propellant charges, fuzes, and projectiles for field assembly.
Volume sits with shells; growth tilts toward smart projectile configurations.
End User:
Budget authority and qualification stringency separate institutional buyers from commercial access.
- Military:National armed forces account for the dominant procurement share across all caliber categories. Bundeswehr and Armée de Terre tenders specify STANAG interoperability and insensitive munitions compliance as mandatory gatekeepers.
- Defense Contractors:System integrators and platform manufacturers purchase ammunition for weapon qualification and bundled vehicle-weapon contracts. Rheinmetall and KNDS procurement teams source directly from propellant suppliers to secure captive supply for artillery system deliveries.
- Law Enforcement:Special tactical units require limited quantities of 40mm less-lethal and breaching ammunition.
- Civilian Users:Collectors and historical reenactment organizations represent a restricted niche governed by national firearms directives.
Contract flow concentrates with military end users; contractor direct sourcing is expanding fastest.
Application:
Mission profile determines performance specifications and environmental operating envelopes.
- Combat:Live-fire engagements demand reliability across temperature extremes from -46°C to +63°C. Artillery barrage requirements in Eastern European theaters are accelerating orders for extended-range base-bleed and rocket-assisted projectiles.
- Training:High-volume consumption favors cost-optimized conventional ammunition with reduced toxic residue profiles. The EU Green Deal is pressuring ranges in Germany and Denmark to transition toward lead-free practice rounds.
- Law Enforcement Operations:Precision requirements at short range favor reduced-ricochet frangible designs.
- Hunting:Large-caliber safari and dangerous game ammunition serves a marginal European market concentrated in Scandinavian and Eastern European jurisdictions.
Training absorbs the highest round counts; combat applications command the steepest technology premiums.
Technology:
Guidance integration and insensitive munitions certification are splitting procurement into performance tiers.
- Conventional:Established spin-stabilized and fin-stabilized designs without guidance packages retain cost advantages for saturation fire missions. These systems face margin compression from propellant feedstock volatility and REACH compliance costs.
- Guided Systems:GPS and semi-active laser guidance transform 155mm and 120mm rounds into precision strike assets. French Caesar and German PzH 2000 howitzer programs are qualifying guided rounds for counter-battery and point-target missions.
- Smart Munitions:Sensor-fuzed submunitions and programmable airburst systems enable area denial with reduced collateral effects.
- Fragmentation:Controlled fragmentation warheads optimize lethal radius against personnel and soft targets.
Conventional technology holds installed base dominance; guided systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unterlüß anchors European ammunition manufacturing through Rheinmetall's integrated propellant and shell forging complex. This Lower Saxony cluster supplies NATO artillery replenishment programs while adapting production lines for REACH-compliant formulations.
Germany
Bundeswehr artillery brigade expansion drives 155mm shell demand through 2030. BSI and DIN standards mandate STANAG interoperability and insensitive munitions certification for all new procurement. The Unterlüß-Wittenberg corridor concentrates propellant chemistry R&D and hydraulic press forging capacity for extended-range projectiles.
France
Armée de Terre Caesar howitzer fleet modernization absorbs precision-guided round volumes. ANSM regulates energetic material transport while national procurement directives prioritize EU Green Deal compliance in propellant selection. The Bourges-Tarbes axis hosts state-owned research institutes and KNDS manufacturing assets for modular artillery charges.
Poland
Warsaw's accelerated artillery brigade buildup draws shell supply from German facilities and incentivizes greenfield Polish production investment. National defense procurement aligns with NATO force planning targets for eastern flank deterrence. The Dęblin-Łódź industrial zone attracts joint venture ammunition plant construction with IM-compliant forging lines.
United Kingdom
British Army AS90 replacement and naval gun programs sustain specialized projectile demand. Health and Safety Executive regulations govern nitrocellulose storage and transport across propellant supply chains. The Glascoed-Radway Green cluster maintains BAE Systems ammunition assembly and qualification testing for STANAG certification.
Sweden
Swedish Armed Forces archipelago defense requirements sustain 120mm mortar and 40mm naval ammunition procurement. Swedish Chemicals Agency (KEMI) implements REACH restrictions on primer compositions ahead of EU-wide deadlines. The Karlskoga-Bofors legacy industrial zone concentrates Nammo precision munitions manufacturing and insensitive propellant formulation.
Europe Medium and Large Caliber Ammunition Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology tiers, with guided systems and smart munitions commanding pricing multiples over conventional training rounds. The European supplier base consolidates around state-affiliated industrial groups and specialized energetic material houses. Three archetypes dominate: integrated defense conglomerates with captive ammunition divisions, standalone propellant and shell specialists, and system integrators sourcing ammunition for bundled platform contracts. Competitive moves center on joint venture production line expansion in Central Europe and strategic partnerships for green propellant chemistry development.
Among German-anchored industrial groups, Rheinmetall AG and KNDS N V exemplify the integrated conglomerate archetype with pan-European production networks. BAE Systems plc occupies a position bridging British naval gun specialization with land systems ammunition integration. These three entities represent distinct geographic and capability positioning within NATO procurement frameworks.
| Leading Market Players |
|---|
| KNDS N V |
| Northrop Grumman Corporation |
| Rheinmetall AG |
| Leonardo S p A |
| RTX Corporation |
| BAE Systems plc |
| Nammo AS |
| Diehl Stiftung & Co KG |
| General Dynamics Corporation |
| Others |
Supply & Pricing Matrix
Propellant chemist scarcity in the Unterlüß-Wittenberg corridor widens labor-cost differentials between premium guided munitions and conventional training rounds. REACH-compliant formulation expertise commands compensation multiples that stratify end-product pricing across NATO procurement tiers.
Pricing Analysis
Outcome-based pricing anchors guided 155mm rounds where per-target elimination costs displace raw materials as the value metric. Three-tier pricing structure across precision-guided, insensitive-munition-certified, and conventional training levels separates STANAG-qualified combat loads from range ammunition. Cost compression in conventional shells intensifies because Brazilian nitrocellulose feedstock volatility feeds through propellant input costs. Defense contractors sourcing for bundled artillery system deliveries exhibit lowest price sensitivity; national training range operators face strictest budget constraints per round.
Supply Chain Analysis
Regional distribution centers in Lower Saxony, Bourges-Tarbes, and Karlskoga form a hub-and-spoke pattern for classified munitions transport under national energetic material regulations. Manufacturing concentration in Germany, France, and Sweden draws from cotton linters and tungsten supply chains anchored in Brazilian chemical processing and Chinese concentrate refining. Single-source vulnerability in hydraulic press forging equipment for 155mm shell bodies creates 24-36 month procurement bottlenecks regardless of order backlog. Distribution runs through military logistics commands with STANAG interoperability certification as the gatekeeping requirement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European ammunition manufacturing is becoming a vertical-integration race. Captive control over REACH-compliant propellant chemistry separates margin leaders from commodity assemblers.
For Market Incumbents: Acquire specialized propellant formulation laboratories in the Bourges-Tarbes research corridor to secure ECHA pre-registration pipelines for lead-free primer chemistry. Consolidate hydraulic press forging capacity across the Unterlüß-Wittenberg axis before equipment lead times extend further. Knowledge transfer continuity threats from retiring state-institute chemists demand preemptive talent capture. For New Entrants and Emerging Players: Joint venture partners with Polish defense industrial holdings offer the most penetrable entry path into NATO eastern flank replenishment programs. Romania and Bulgaria's underutilized Soviet-era plants receiving European Peace Facility modernization funding present greenfield IM-compliant production opportunities. Qualify through EDA collaborative procurement frameworks rather than national tender competitions. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap propellant specialists given CSRD Scope 3 disclosure mandates and preferential EU defense procurement scoring for verified low-carbon supply chains. Long-term viability over a decade-long window hinges on green chemistry R&D amortization across multi-national framework contracts. Watch for ECHA substance authorization sunset dates as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propellant Chemistry | Captive ECHA pre-registration access secures preferred supplier status in German and French tenders. |
| Joint Venture Production in Central Europe | Polish and Romanian greenfield sites align with NATO eastern flank deterrence requirements and European Peace Facility funding. |
| Insensitive Munitions Certification Investment | STANAG 4439 compliance unlocks shared NATO stockpile agreements and premium pricing tiers. |
| REACH-Compliant Formulation R&D | Novel green propellant chemistry addresses EU Green Deal elimination mandates for lead-based primers. |
| Modular Artillery Charge System Adoption | German and French fielding of variable-zone charges collapses SKU complexity and rewrites inventory economics. |
Research Methodology
Trade customs databases, NATO procurement disclosure registers, and ECHA substance authorization filings formed the secondary backbone for supply chain mapping and regulatory timeline construction. Primary interviews with propellant plant managers, Bundeswehr procurement officers, EDA collaborative program directors, and nitrocellulose feedstock traders validated capacity utilization estimates and qualification timeline assumptions. Bottom-up shell and propellant volume estimates triangulated against top-down defense budget allocation analysis across the analysis window.
Historical production capacity and procurement contract award patterns informed the analytical framework for projection modeling across product type, technology tier, end-user category, and application mission profile. CAGRs were derived from segment-level demand build-ups incorporating NATO force planning targets, national stockpile replenishment schedules, and IM compliance transition curves. Forecast inputs included propellant chemist workforce demographics, hydraulic press equipment order backlogs, and ECHA authorization sunset sequencing.
Caveats apply where nitrocellulose supply disruptions, REACH substance restriction accelerations, or NATO qualification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions regarding national defense budget trajectories and EDA joint procurement consolidation momentum. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Americas Ballistic Missile Market