
 Asia-Pacific Cruise Missile Market | 2026-2036
Asia-Pacific Cruise Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cruise Missile Market Outlook
South Korean missile capacity is fragmenting across multiple development streams. LIG Nex1 leverages domestic propulsion expertise to anchor Seoul's surface-launched programs. Mitsubishi Heavy Industries sustains Japan's submarine-launched cruise missile lineage through specialized maritime integration. Bharat Dynamics Limited competes in the tactical export segment with cost-optimized land-attack variants.
Asia-Pacific cruise missiles are self-propelled guided weapons designed for precision engagement at standoff distances, typically employing turbofan or turbojet propulsion, inertial navigation with terminal seeker correlation, and warheads ranging from conventional unitary to penetrating configurations for fixed or relocatable targets. Surface-launched missiles occupy the largest procurement share as coastal defense and mobile ground batteries proliferate across contested littorals, while stealth technology commands premium allocation due to radar-cross-section requirements in dense air-defense environments. Targeting systems represent the fastest-evolving segment as multi-spectral seekers and artificial intelligence-assisted scene-matching displace single-mode guidance.
Australia's Defence Export Controls, Japan's Three Principles on Transfer of Defense Equipment, and South Korea's Defense Acquisition Program Administration collectively shape regional market access through technology-release classifications and end-user certification protocols. India's offset mandates under the Defence Acquisition Procedure further condition foreign supplier participation in domestic programs. Stakeholders must track evolving technology-transfer thresholds as indigenous industrial bases mature across multiple Asia-Pacific nations.
Market Dynamics
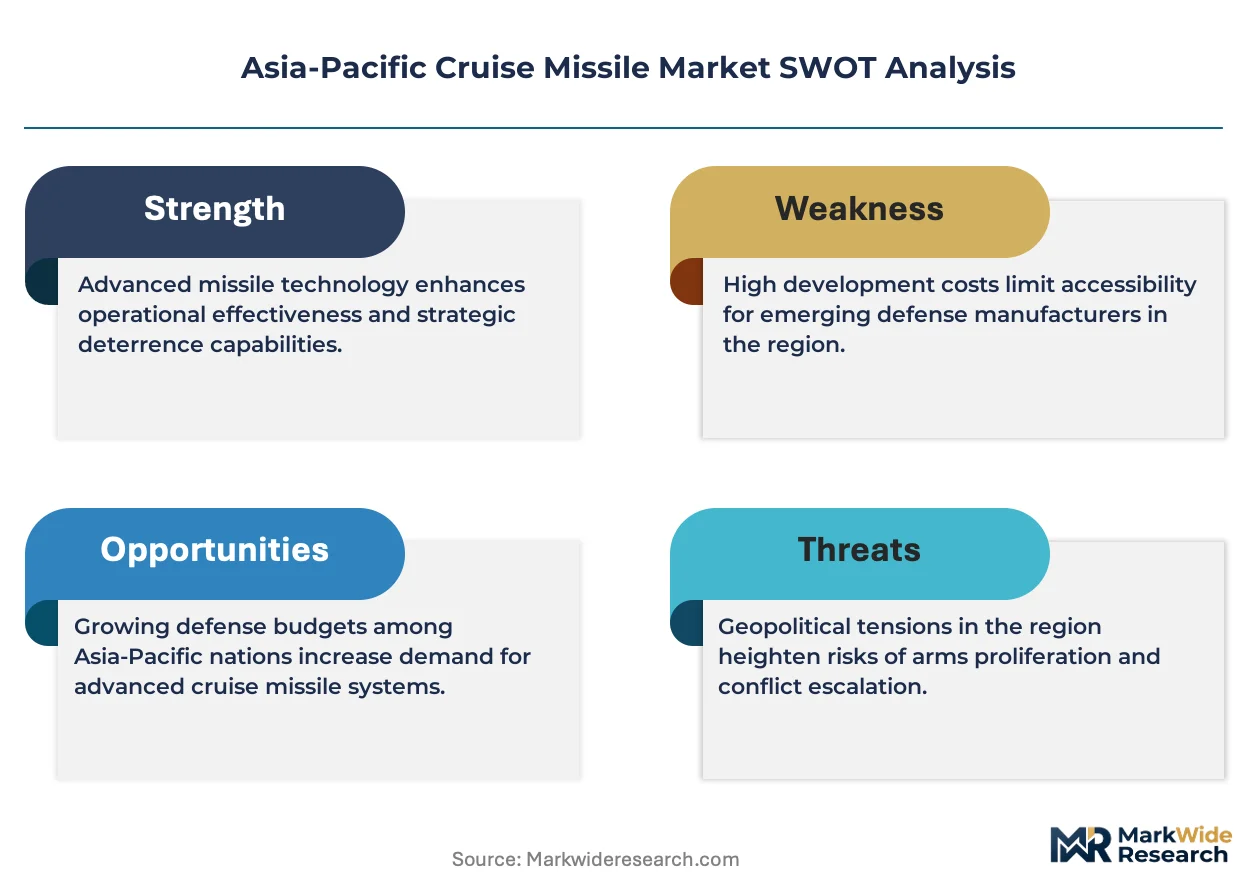
Precision-strike requirements across contested maritime corridors are forcing defense procurement offices to reevaluate standoff weapon inventories against layered air-defense networks. Turbofan propulsion miniaturization and multi-spectral seeker integration now determine contract awards more than unit cost alone.
Growth Catalysts
- Japan's Three Principles on Transfer of Defense Equipment revision:Relaxed export constraints enable Mitsubishi Heavy Industries to supply allied navies with submarine-launched variants, expanding addressable demand beyond domestic Self-Defense Forces requirements.
- India's Defence Acquisition Procedure offset mandates:Foreign OEMs must establish local propulsion component facilities, accelerating Bharat Dynamics Limited's absorption of turbojet manufacturing expertise for tactical land-attack programs.
- South Korean coastal defense batteries:LIG Nex1's surface-launched systems address operational gaps in maritime strike coverage against amphibious threat vectors across the Yellow Sea approaches.
Market Restraints
- Turbofan engine supply concentration:Specialized micro-turbojet production concentrates among three European and North American propulsion houses, creating single-source vulnerability for Asia-Pacific integrators.
- Terminal seeker component costs:Multi-spectral focal plane arrays and synthetic aperture radar processors consume 35-45% of unit flyaway cost, compressing procurement volumes under fixed defense budgets.
- Technology-release classification barriers:Australia's Defence Export Controls and Japan's end-user certification protocols block re-export of US-origin guidance subsystems, fragmenting regional supply chains.
Strategic Opportunities
- Vietnam's coastal defense modernization:Russian-origin anti-ship missile obsolescence creates replacement demand for mobile ground-launched precision strike with indigenous maintenance infrastructure.
- Artificial intelligence-assisted scene-matching convergence:Neural network target recognition fused with inertial navigation reduces dependence on GPS jamming-vulnerable signal chains.
- Indonesia's archipelagic strike requirements:Dispersed island geography favors compact surface-launched systems with over-the-horizon engagement envelopes for sea denial operations.
Industry Challenges
- Guidance algorithm validation timelines:Australia's Defence Export Controls and counterpart agencies in Japan and South Korea impose 18-36 month certification cycles for autonomous targeting logic, delaying operational deployment.
- Legacy platform integration friction:Existing naval combat management systems from 1990s-era frigate classes lack data bus compatibility with modern network-enabled cruise missile command links.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cruise Missile Market |
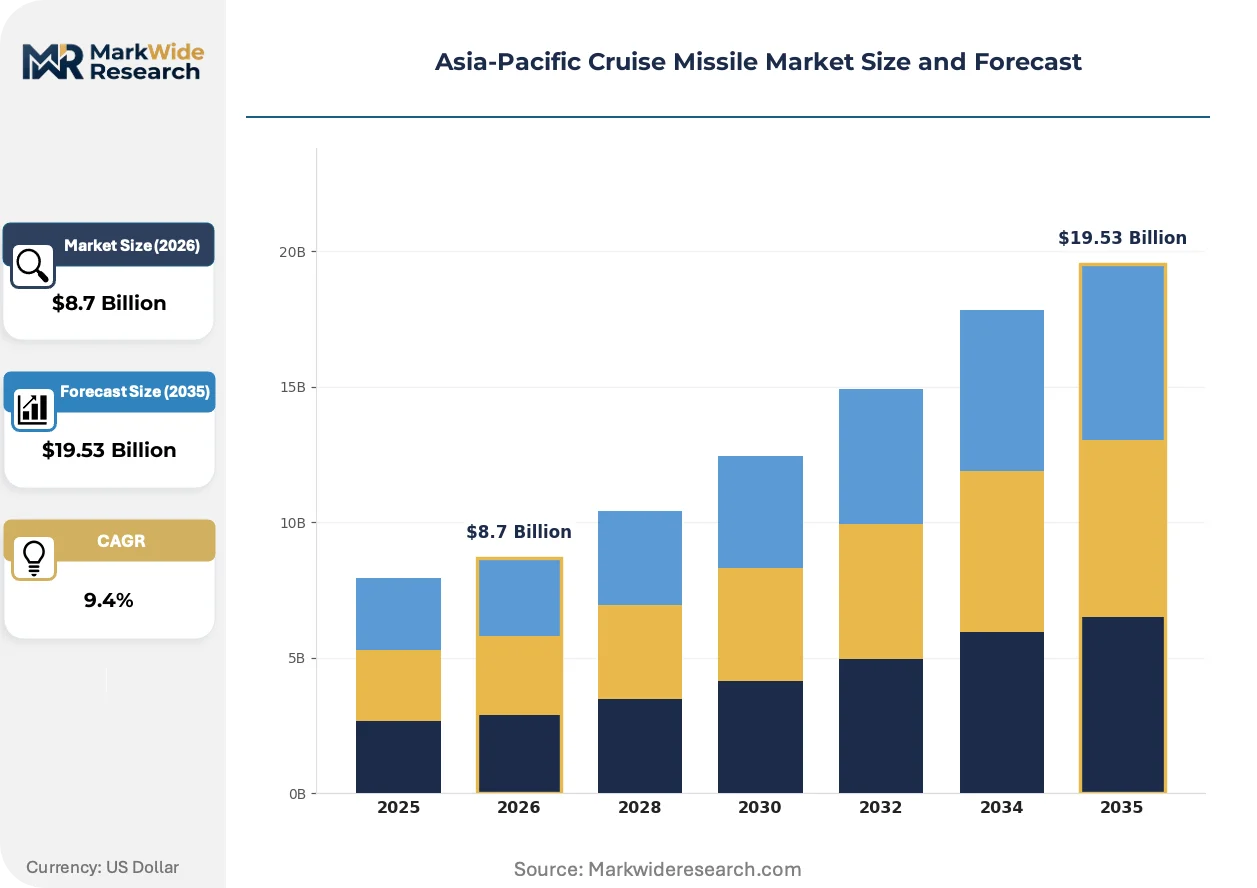
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Launched Missiles, Surface-Launched Missiles, Submarine-Launched Missiles, Land Attack Missiles Technology: Guided Missiles, Advanced Propulsion, Stealth Technology, Targeting Systems End User: Defense Forces, Naval Organizations, Aerospace Contractors, Government Agencies Application: Maritime Security, Strategic Deterrence, Tactical Operations, Border Defense |
| Companies Covered | Mitsubishi Heavy Industries, China Aerospace Science and Industry Corporation, Defence Research and Development Organisation, LIG Nex1, Bharat Dynamics Limited, Lockheed Martin Corporation, RTX Corporation, MBDA, Kongsberg Gruppen, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cruise Missile Market Strategic Shifts
Propulsion and seeker architectures are converging toward modular, software-defined configurations that permit mid-life capability insertion without airframe redesign. This shift rewards integrators with captive avionics development capacity.
Ramjet-assisted turbofan propulsion is migrating from experimental demonstrators to production surface-launched programs. South Korean and Japanese defense agencies now specify dual-mode engines for sustained supersonic terminal approach against time-critical relocatable targets. This migration from subsonic-only envelopes compresses adversary reaction timelines and forces countermeasure investment into directed-energy and hypervelocity interceptor categories previously reserved for ballistic missile defense.
India's offset mandates under the Defence Acquisition Procedure now require foreign suppliers to transfer turbojet casting and machining technology to domestic joint ventures. Bharat Dynamics Limited and private sector partners must absorb these capabilities within 48-month contractual windows or face procurement disqualification. Tactical land-attack variants with ranges under 300 kilometers face the most acute localization pressure, as these categories fall beneath MTCR threshold scrutiny while remaining strategically significant for regional deterrence.
Defense acquisition offices across Seoul, Tokyo, and Canberra now unbundle platform procurement from through-life support contracts, creating standalone sustainment competitions at 7-10 year intervals. This pattern disrupts traditional OEM capture of 25-year service revenue streams. South Korea's Defense Acquisition Program Administration pioneered this model for surface-launched cruise missile fleets, with Japan's Ministry of Defense now piloting equivalent arrangements for submarine-launched inventory.
Asia-Pacific Cruise Missile Market Segmentation
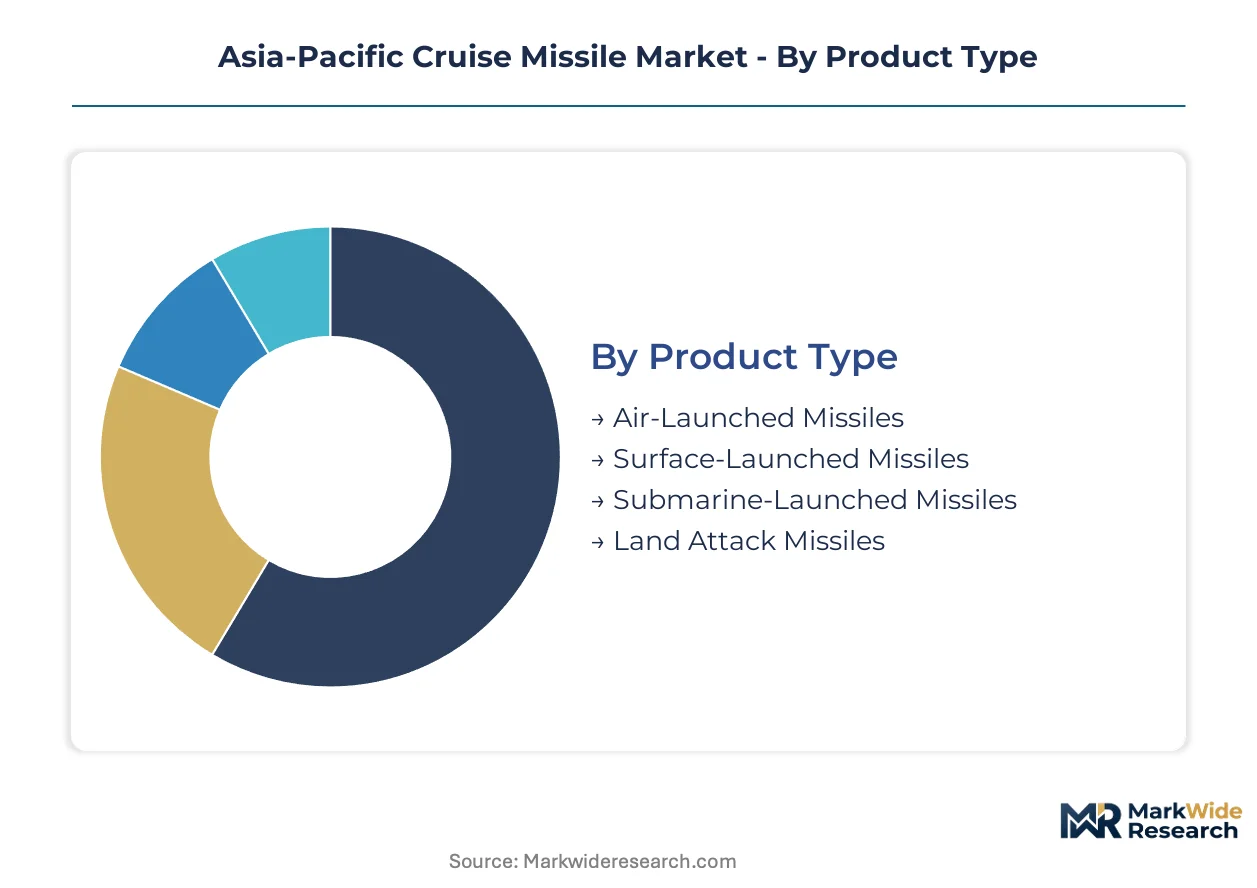
Segmentation reveals how procurement cycles diverge across propulsion architectures and launch platforms. Cycle times range from 18-month seeker upgrades to decade-long submarine integration programs, reshaping supplier revenue recognition patterns across the Asia-Pacific theater.
Product Type:
Surface-launched systems turn inventory fastest due to modular battery reconfiguration, while submarine-launched variants lock capital for years through hull-integration timelines.
- Surface-Launched Missiles:Coastal defense batteries and mobile ground systems employ containerized launchers with rapid reload architecture. South Korean procurement concentrates here as LIG Nex1 addresses Yellow Sea maritime strike gaps against amphibious threat vectors.
- Submarine-Launched Missiles:Torpedo tube or vertical launch cell integration demands hull-penetrating modifications and combat management system recertification. Japan's Maritime Self-Defense Forces sustain this segment through Mitsubishi Heavy Industries' specialized maritime integration lineage.
- Air-Launched Missiles:Hardpoint-compatible variants with reduced booster stages for platform weight constraints.
- Land Attack Missiles:Fixed-site targeting configurations with penetrating warhead options for hardened installations.
Surface-Launched Missiles dominate installed base across littoral defense networks. Submarine-Launched Missiles represent where expansion concentrates as undersea strike capability disperses beyond traditional nuclear powers.
Technology:
Cost tiers separate commoditized guidance packages from sovereign-controlled seeker architectures with export licensing barriers.
- Targeting Systems:Multi-spectral focal plane arrays and synthetic aperture radar processors enable terminal engagement in GPS-denied environments. India's Defence Research and Development Organisation prioritizes indigenous scene-matching development under revised procurement guidelines.
- Stealth Technology:Radar-absorbent materials and shaping techniques reduce cross-section for penetration of layered air-defense networks. Premium allocation flows here due to dense threat environments across contested maritime corridors.
- Advanced Propulsion:Ramjet-assisted turbofan and dual-mode engines for sustained supersonic terminal approach.
- Guided Missiles:Baseline inertial navigation with mid-course update capability for cost-constrained inventories.
Targeting Systems command the steepest expansion trajectory as artificial intelligence-assisted recognition displaces single-mode guidance. Guided Missiles retain volume share in reserve and export-tier procurement.
End User:
Customer type determines technology-release classification thresholds and maintenance infrastructure requirements.
- Defense Forces:Operational deployment authorities with sovereign maintenance certification and through-life support accountability. South Korea's Defense Acquisition Program Administration and Japan's Ministry of Defense shape regional demand through unbundled platform and sustainment contracting.
- Naval Organizations:Maritime-specific procurement offices with submarine integration expertise and combat system authority.
- Aerospace Contractors:Platform prime contractors integrating missile systems with airframe avionics buses.
- Government Agencies:Research and development funding bodies with technology-transfer oversight mandates.
Defense Forces dominate installed base with operational inventory accountability. Naval Organizations concentrate expansion as submarine-launched capability proliferates.
Application:
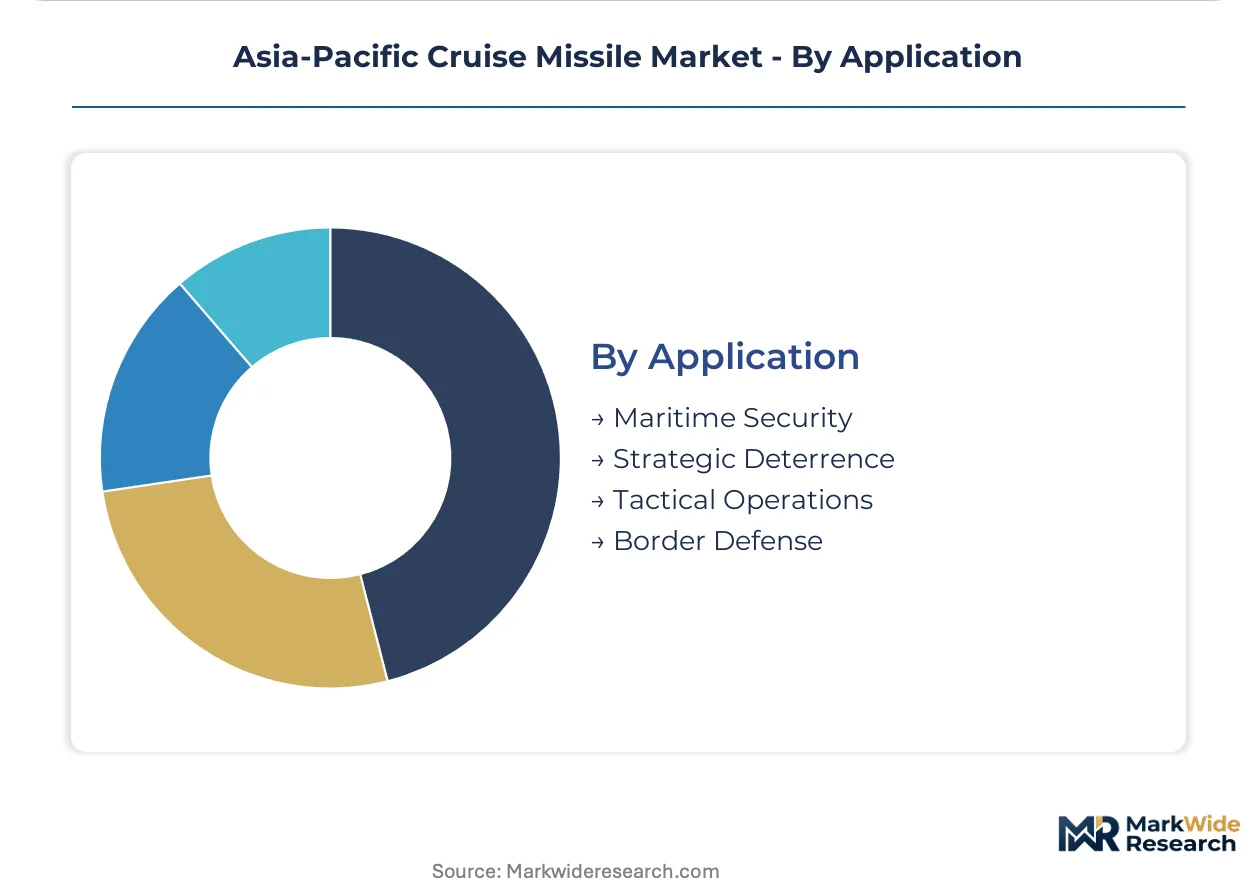
Volume distribution tracks maritime dispute intensity across specific littoral geographies rather than abstract threat categories.
- Maritime Security:Sea denial and coastal defense against surface and amphibious threats. Vietnam's Russian-origin anti-ship missile obsolescence creates replacement demand with indigenous maintenance infrastructure requirements.
- Strategic Deterrence:Standoff strike capability for escalation control below nuclear thresholds.
- Tactical Operations:Time-critical relocatable target engagement with compressed kill chains.
- Border Defense:Fixed-site protection with limited mobility requirements.
Maritime Security dominates installed base across archipelagic and littoral defense postures. Strategic Deterrence is where expansion concentrates as precision-strike arsenals diversify beyond ballistic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific theater. Japan prioritizes undersea-launched standoff weapons for maritime strike dispersion, while South Korea and India concentrate procurement in surface-mobile coastal defense batteries with rapid reload architectures.
Japan
Maritime Self-Defense Forces drive submarine-launched cruise missile integration through hull-penetrating vertical launch cell modifications. METI's revised Three Principles on Transfer of Defense Equipment relax export constraints, enabling supply to allied navies. Mitsubishi Heavy Industries anchors production in the Kanto region around Tokyo, sustaining specialized maritime integration expertise for torpedo tube and vertical launch configurations.
South Korea
Defense Acquisition Program Administration procurement concentrates in surface-launched systems for Yellow Sea maritime strike coverage against amphibious threat vectors. Coastal defense battery modernization programs specify containerized launchers with modular reload architecture. LIG Nex1 operates from the Seoul Capital Area, leveraging domestic propulsion expertise to anchor national surface-launched development streams.
India
Defence Research and Development Organisation accelerates indigenous programs under revised Defence Acquisition Procedure guidelines with mandatory offset mandates. Turbojet casting and machining technology transfer requirements compress 48-month contractual windows for foreign suppliers. Bharat Dynamics Limited competes from Hyderabad in Telangana, absorbing manufacturing expertise for tactical land-attack variants beneath MTCR threshold scrutiny.
Australia
Royal Australian Navy procurement emphasizes network-enabled cruise missile command links compatible with modern combat management systems. Defence Export Controls impose 18-36 month certification cycles for autonomous targeting logic, delaying operational deployment timelines. Industrial activity clusters in New South Wales and Victoria, where aerospace contractors integrate missile systems with platform avionics buses for through-life support competitions.
Vietnam
Russian-origin anti-ship missile obsolescence creates replacement demand for mobile ground-launched precision strike with indigenous maintenance infrastructure requirements. Coastal defense modernization prioritizes compact surface-launched systems for archipelagic sea denial operations. Procurement offices evaluate systems with over-the-horizon engagement envelopes suitable for dispersed island geography and limited mobility requirements.
Asia-Pacific Cruise Missile Market Competitive Environment
Capability concentration sits with specialized maritime integrators and propulsion houses; scale advantage sits with diversified aerospace conglomerates with captive avionics development capacity. The vendor base stratifies across three tiers: sovereign defense laboratories with technology-transfer mandates, regional prime contractors with platform integration lineage, and foreign OEMs establishing local joint ventures under offset requirements. Dominant competitive moves include turbojet manufacturing technology licensing under procurement disqualification pressure and unbundled through-life support contracting at 7-10 year intervals.
Within the sovereign laboratory tier, Defence Research and Development Organisation exemplifies indigenous development acceleration under revised procurement guidelines. Among regional prime contractors, Mitsubishi Heavy Industries and LIG Nex1 occupy positions anchored in specialized maritime and surface-launched integration lineages respectively. At the foreign OEM end, Lockheed Martin Corporation and RTX Corporation represent scale-driven participants navigating technology-release classification barriers and local facility establishment requirements.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| China Aerospace Science and Industry Corporation |
| Defence Research and Development Organisation |
| LIG Nex1 |
| Bharat Dynamics Limited |
| Lockheed Martin Corporation |
| RTX Corporation |
| MBDA |
| Kongsberg Gruppen |
| Others |
Value Chain & Pricing Dynamics
European and North American micro-turbojet manufacturers concentrate propulsion supply for Asia-Pacific integrators, anchoring margin capture in specialized engine houses while assembly-tier primes face cost compression from multi-spectral seeker procurement.
Pricing Analysis
Long-term offtake contracts dominate procurement for surface-launched systems, while submarine-launched programs run on project-based structures tied to hull-integration milestones. Price differentiation rests on seeker certification tier and propulsion localization level, with MTCR-compliant variants commanding premiums over export-restricted configurations. Cost compression in tactical land-attack segments intensifies as India's offset mandates force turbojet manufacturing technology transfer. Defense forces with sovereign maintenance certification show lowest price sensitivity; export-tier procurement offices in Vietnam and Indonesia face acute budget constraints.
Supply Chain Analysis
Export-control regimes in the United States, United Kingdom, and France restrict flow of guidance subsystems and multi-spectral focal plane arrays to Asia-Pacific integrators. Component supply draws from Germany for precision machining, Israel for seeker algorithms, and domestic Japanese and South Korean facilities for final assembly. Single-source vulnerability in micro-turbojet procurement creates structural risk for programs with accelerated delivery timelines. Distribution runs through defense acquisition program administration channels with technology-release certification gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-mode ramjet-assisted propulsion and artificial intelligence-assisted scene-matching are reshaping competitive positioning as defense procurement offices prioritize GPS-denied engagement capability.
For Market Incumbents: Build captive seeker development capacity as a moat against technology-transfer barriers. Mitsubishi Heavy Industries and LIG Nex1 should deepen in-house production of multi-spectral focal plane arrays to reduce dependence on US-origin components. Absorb turbojet casting expertise through joint ventures ahead of India's 48-month localization windows. Certification investment in autonomous targeting logic accelerates deployment timelines against Australia's Defence Export Controls.
For New Entrants and Emerging Players: Vietnam's coastal defense modernization represents the most penetrable entry point for mobile ground-launched precision strike with indigenous maintenance infrastructure. Indonesia's archipelagic geography favors compact surface-launched systems with over-the-horizon envelopes for sea denial operations. Partner with regional primes on through-life support competitions to bypass platform procurement barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed propulsion specialists holding micro-turbojet manufacturing technology. Long-term viability hinges on dual-use technology positioning beneath MTCR scrutiny thresholds. Watch for relaxation in Japan's Three Principles on Transfer of Defense Equipment as the signal for expanded addressable demand beyond domestic Self-Defense Forces requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Propulsion Development | Ramjet-assisted turbofan engines compress adversary reaction timelines for South Korean and Japanese defense agencies. |
| Indigenous Seeker Manufacturing | Domestic scene-matching development reduces GPS jamming vulnerability for India's Defence Research and Development Organisation programs. |
| Offset Compliance Structuring | Foreign OEM joint ventures with Bharat Dynamics Limited satisfy Defence Acquisition Procedure turbojet technology transfer mandates. |
| Unbundled Sustainment Contracting | Standalone 7-10 year support competitions disrupt traditional OEM capture of 25-year service revenue streams in Seoul and Tokyo. |
| Export Control Navigation | Technology-release classification expertise unlocks supply of submarine-launched variants to allied navies under revised METI principles. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of defense procurement databases, customs trade records, and regulatory filing repositories. Interviews with program managers at defense acquisition program administrations, propulsion engineering leads at specialized manufacturers, and compliance officers at export control agencies inform demand and supply-side assessments. Secondary sources include Defence Acquisition Procedure offset documentation, METI Three Principles revision texts, and MTCR threshold guidance. Bottom-up unit procurement tracking triangulates against top-down defense budget allocation analysis.
Forecast inputs incorporate propulsion architecture evolution, seeker technology maturation timelines, and regulatory relaxation trajectories across the projection horizon. Segmentation dimensions model launch platform type, guidance system sophistication tier, end-user certification level, and regional technology-transfer policy cluster. CAGRs derive from procurement cycle analysis and defense budget growth patterns. Industry-specific inputs include 18-36 month autonomous targeting logic certification timelines and 48-month turbojet localization contractual windows.
Macroeconomic conditions sit as an overlay; deviation in defense budget growth rates or currency volatility for import-dependent programs would shift the trajectory. Forecasts reflect assumptions regarding technology-release classification stability and propulsion supply concentration. Material shifts in MTCR threshold enforcement or major regional conflict escalation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Sonobuoy Launcher Market