
 Europe Aerospace Composites Market | 2026-2036
Europe Aerospace Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aerospace Composites Market Foresight
The tier-one supply channel into Airbus and Safran is narrowing as qualification timelines stretch and OEMs consolidate approved vendor lists. Hexcel Corporation leverages its Preston, UK facility to sustain carbon fiber prepreg supply for wing programs. Solvay SA anchors European resin formulation capabilities through its Georgia, US and European operations, competing on thermoplastic composite chemistry. SGL Carbon specializes in pitch-based carbon fibers for brake discs and structural applications, occupying a defensible niche against PAN-based rivals.
Europe aerospace composites are fiber-reinforced polymer systems, typically carbon fiber prepregs with epoxy or thermoplastic matrices, cured under autoclave or out-of-autoclave conditions to achieve specific strength-to-weight ratios exceeding 200 MPa per gram per cubic centimeter. Their primary purpose is to replace aluminum and titanium in airframes, reducing fuel burn and extending range. CFRP dominates structural components and aerodynamic surfaces where load-bearing efficiency determines design, while resin transfer molding gains share in engine parts and complex geometries where fiber placement automation reduces labor content. Interiors applications favor GFRP and sandwich composites for fire-resistance compliance at lower cost points.
EASA airworthiness directives and REACH chemical restrictions shape material selection, forcing reformulation of legacy resins and brominated flame retardants. The EU Green Deal industrial emissions framework pressures autoclave energy intensity, redirecting investment toward electron-beam curing and thermoplastic welding. CSRD disclosure requirements extend through the aerospace supply chain, compelling composite producers to document Scope 3 carbon content. Stakeholders must weigh qualification lock-in against next-generation thermoplastic adoption timelines as platform refresh cycles stretch toward mid-century.
Market Dynamics
Airbus production rate increases to 75 A320 family aircraft monthly by 2027 are compressing qualification timelines for composite suppliers. Tier-one vendors face simultaneous pressure to expand thermoplastic capacity while maintaining legacy thermoset output for in-service fleets.
Growth Catalysts
- EU Green Deal industrial emissions framework:Binding carbon intensity targets for manufacturing are accelerating investment in electron-beam curing and out-of-autoclave processes that cut energy consumption per part by half.
- Single-aisle aircraft backlog concentration:Airbus A320neo family orders exceeding 6,000 units are pulling carbon fiber prepreg demand toward narrow-body wing and fuselage applications.
- France-Germany-UK cluster density:Final assembly lines at Toulouse, Hamburg, and Broughton create localized demand pools that reduce logistics costs for qualified suppliers within 500-kilometer radii.
Market Restraints
- Acrylonitrile price volatility:PAN precursor carbon fiber production remains exposed to petrochemical feedstock swings that compress margin predictability for mid-tier weavers.
- Toray-Hexcel-Solvay supply triad:Concentration of qualified aerospace resin and fiber capacity in three vendor groups creates single-source vulnerability for new platform introductions.
- REACH chemical authorization delays:Legacy brominated flame retardants face sunset dates before replacement chemistries complete ECHA registration, forcing interim formulation compromises.
Strategic Opportunities
- Poland-Czech Republic corridor:Lower labor costs and proximity to German engineering centers are attracting automated fiber placement investments for secondary structure manufacturing.
- Thermoplastic welding automation:Convergence of induction heating and robotic path planning is enabling rivetless joining of fuselage panels, cutting assembly hours and part count.
- CSRD Scope 3 disclosure mandate:Supply chain carbon accounting requirements are creating first-mover advantage for composite recyclers offering certified recycled fiber content to tier-one suppliers.
Industry Challenges
- Non-destructive inspection technician shortage:Ultrasonic and thermography certification programs are failing to match output requirements for production ramp rates at Broughton and Hamburg.
- EASA major change approval timelines:Material equivalency demonstrations for thermoplastic substitutions are extending 18-24 months, delaying platform weight reduction targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aerospace Composites Market |
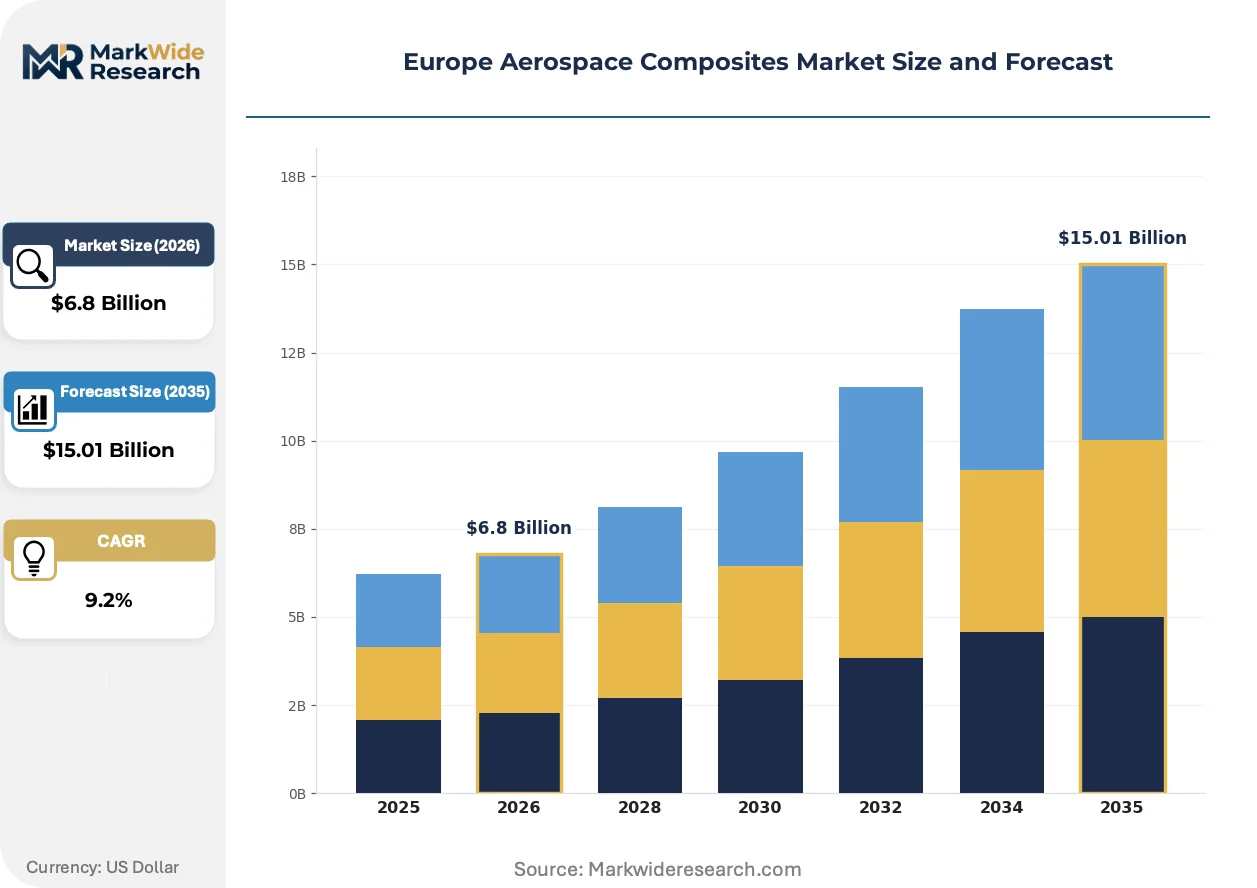
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.01 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CFRP, GFRP, Hybrid Composites, Sandwich Composites Manufacturing Process: Layup, Filament Winding, Resin Transfer Molding, Pultrusion Application: Structural Components, Interiors, Aerodynamic Surfaces, Engine Parts End User: Commercial Aviation, Defense, General Aviation, Space |
| Companies Covered | Toray Industries, Hexcel Corporation, Solvay SA, DuPont, Airborne, SGL Carbon, Teijin Limited, Mitsubishi Chemical, Syensqo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aerospace Composites Market Shifts & Advancements
Material-process combinations are pivoting toward energy-efficient curing and closed-loop fiber recovery. Automation is compressing labor content in layup and assembly while regulatory disclosure requirements reshape supplier qualification criteria.
Out-of-autoclave thermoset prepregs with toughened epoxy formulations are achieving void contents below 1% without pressure vessel curing. Narrow-body OEMs are qualifying these materials for empennage and fairing applications to bypass autoclave bottlenecks. The elimination of autoclave cycle constraints is rendering obsolete the capital-intensive pressure vessel infrastructure that previously dictated factory layout and throughput ceilings.
CSRD disclosure requirements extending through aerospace supply chains are mandating Scope 3 carbon footprint documentation from composite producers. EASA is aligning material qualification protocols with sustainability data submission, creating dual compliance tracks. Tier-two suppliers in France and Germany are investing in lifecycle assessment software to meet combined regulatory and customer audit demands.
Long-term service agreements bundling material supply with repair station accreditation are displacing spot procurement for in-service fleet support. Airlines operating A350 and B787 fleets are consolidating composite repair spend with OEM-authorized networks. This consolidation is most advanced in the UK and Germany, where Lufthansa Technik and British Airways Engineering have centralized MRO vendor panels.
Europe Aerospace Composites Market Segmentation
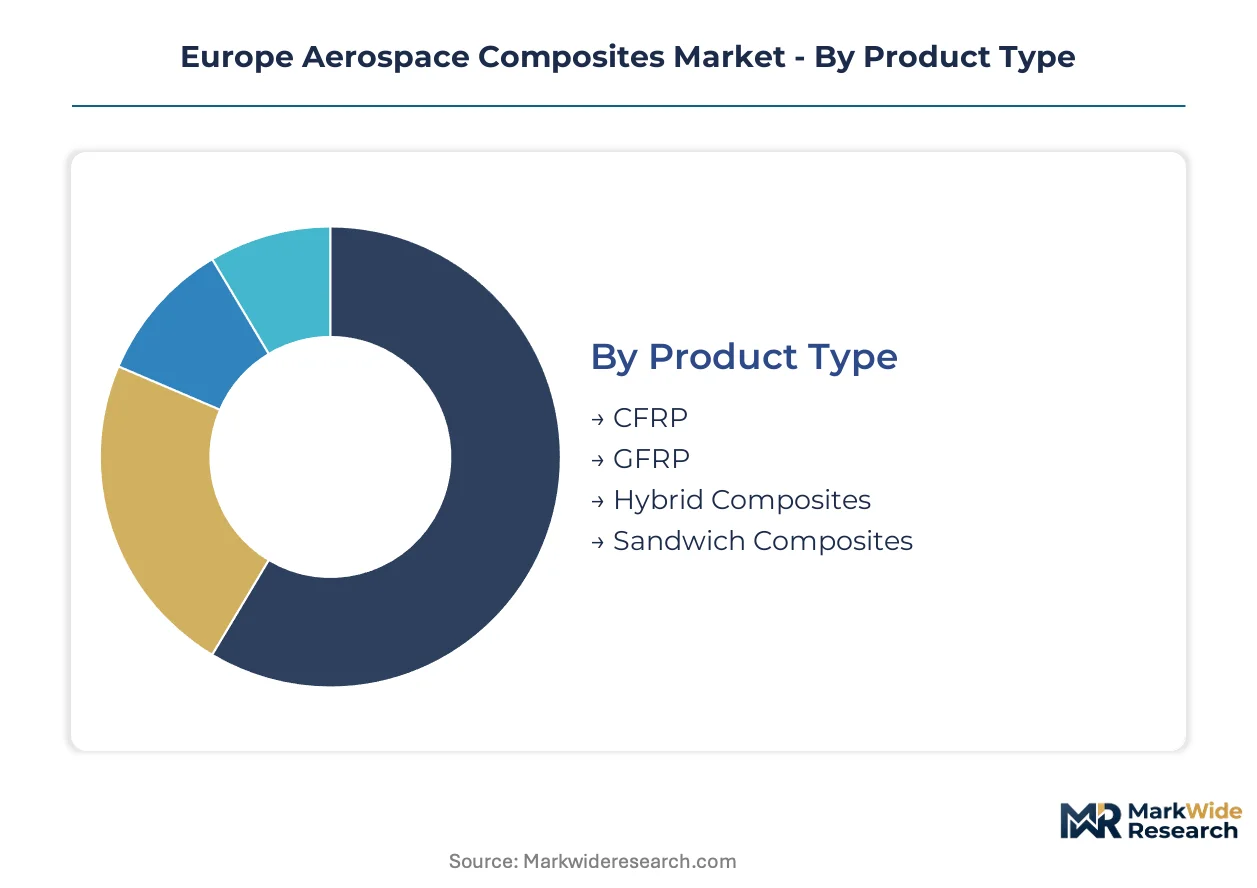
Material and process selection in Europe aerospace composites hinges on EASA airworthiness protocols and OEM platform specifications. Segmentation reveals how qualification timelines and energy intensity constraints reshape supplier investment priorities across fiber systems and manufacturing methods.
Product Type:
Mature thermoset systems dominate current airframe programs, while emerging thermoplastic formulations capture next-generation platform development.
- CFRP:Carbon fiber reinforced polymers with epoxy or thermoplastic matrices achieve specific strength-to-weight ratios exceeding aluminum by 40%. Demand concentrates in wing boxes and fuselage barrels at Airbus facilities in Toulouse and Hamburg, where EASA qualification protocols favor established prepreg suppliers.
- GFRP:Glass fiber systems trade structural efficiency for cost containment and dielectric properties. Applications cluster in radomes and interior panels within the UK-Germany supply corridor, driven by REACH compliance pressures on halogenated flame retardants.
- Hybrid Composites:Carbon-glass combinations balance performance and cost in secondary structures.
- Sandwich Composites:Nomex or aluminum honeycomb cores with composite skins dominate cabin interiors and flooring.
CFRP retains volume leadership; hybrid composites hold the steepest expansion curve.
Manufacturing Process:
Cost tier stratification separates capital-intensive autoclave methods from emerging out-of-autoclave alternatives targeting energy reduction.
- Layup:Automated fiber placement and tape laying systems deposit unidirectional prepreg with precision tolerances below 0.5 millimeters. Investment concentrates at Broughton and Hamburg final assembly sites, where Airbus production rate targets compress cycle times.
- Resin Transfer Molding:Closed-mold infusion of dry fiber preforms enables complex geometries with reduced volatile emissions. Adoption accelerates in engine nacelles and ducting across French and German tier-one suppliers, aligned with EU Green Deal manufacturing emissions targets.
- Filament Winding:Continuous fiber deposition around mandrels produces pressure vessels and cylindrical structures.
- Pultrusion:Continuous pulling of resin-impregnated fibers through heated dies yields constant cross-section profiles.
Layup commands the highest process share; resin transfer molding climbs the fastest on sustainability metrics.
Application:
Application segmentation tracks load-bearing requirements against fire-smoke-toxicity regulatory thresholds.
- Structural Components:Primary load-bearing elements including wing spars, fuselage frames, and empennage boxes demand certified damage tolerance. Qualification concentrates at Hexcel's Preston facility and Safran supply nodes in France, where material equivalency demonstrations extend 18-24 months.
- Interiors:Cabin elements including sidewalls, ceilings, and monuments prioritize fire-resistance compliance over structural efficiency. Specification activity clusters in Germany and the UK, where airline retrofit programs and OEM delivery schedules converge.
- Aerodynamic Surfaces:Control surfaces and fairings optimize stiffness-to-weight for flutter resistance.
- Engine Parts:Fan blades, cowls, and thrust reversers require elevated temperature performance.
Structural components retain volume leadership; interiors hold the steepest expansion curve.
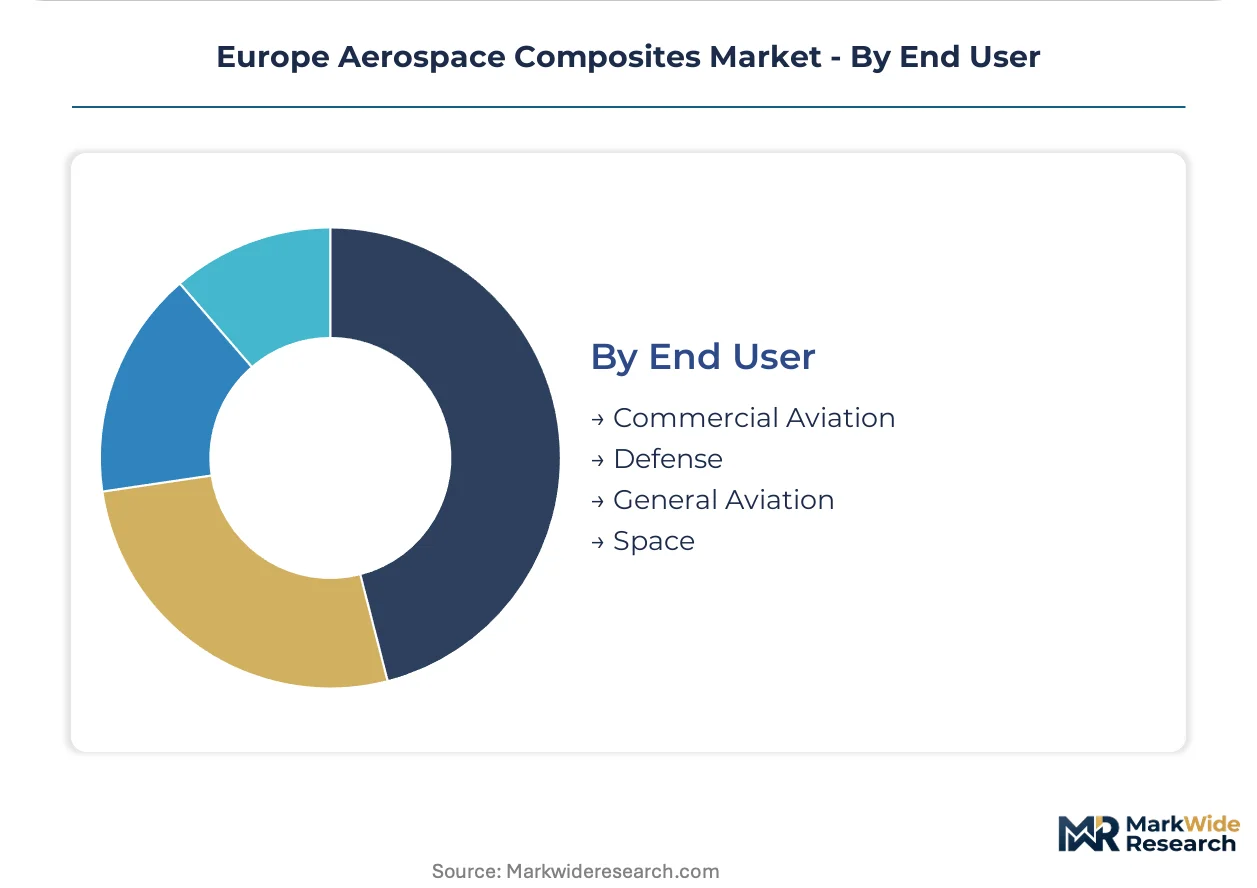
End User:
Customer type segmentation reflects divergent procurement cycles and qualification stringency.
- Commercial Aviation:Narrow-body and wide-body OEM programs generate prepreg demand at scale. Airbus A320neo family production rates pulling toward 75 monthly units concentrate supply chain investment in France, Germany, and the UK.
- Defense:Military platforms including Eurofighter Typhoon and future combat air systems impose classified material specifications. Development activity clusters in Germany and the UK, where national security protocols restrict supplier access.
- General Aviation:Business jet and regional aircraft manufacturers operate lower volume, higher customization procurement.
- Space:Launch vehicle and satellite structures demand extreme stiffness-to-weight and outgassing control.
Commercial aviation retains volume leadership; defense holds the steepest expansion curve on next-generation platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor and the Channel Tunnel rail freight link underpin composite logistics between continental manufacturing centers and UK assembly sites. These infrastructure assets enable just-in-time prepreg delivery from German resin plants to Toulouse and Hamburg final assembly lines.
France
Airbus Toulouse and Safran Landing Systems generate concentrated demand for carbon fiber wing structures and brake disc preforms. The EU Green Deal industrial emissions framework mandates energy intensity reductions that redirect investment toward electron-beam curing facilities in the Occitanie region. The Aerospace Valley cluster around Toulouse-Blagnac hosts automated fiber placement operations serving A350 wing programs.
Germany
Hamburg Finkenwerder final assembly and MTU Aero Engines drive prepreg consumption for narrow-body fuselage sections and turbine components. REACH chemical authorization delays for brominated flame retardants force interim formulation adjustments at Bavarian resin compounders. The Munich-Stuttgart corridor concentrates thermoplastic welding R&D for next-generation fuselage joining.
United Kingdom
Airbus Broughton wing manufacturing and GKN Aerospace facilities anchor CFRP demand for commercial and defense platforms. CSRD disclosure requirements compel Lancashire-based weavers to document Scope 3 carbon content through lifecycle assessment software. The Northwest England cluster specializes in out-of-autoclave qualification for empennage applications.
Spain
Airbus Getafe and Alestis Aerospace produce aerostructures and interiors components for A320 family programs. EASA airworthiness directives on fire-smoke-toxicity performance tighten specification requirements for Madrid-area sandwich panel suppliers. The Madrid-Castile-La Mancha corridor develops resin transfer molding capacity for engine nacelle production.
Italy
Leonardo Aerostructures and Avio Aero generate demand for composite fan blades and helicopter airframes. The F-Gas Regulation pressures refrigerant-dependent autoclave operations in Piedmont toward alternative curing methods. The Turin-Novara industrial zone concentrates filament winding expertise for pressure vessel and satellite structure applications.
Europe Aerospace Composites Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a supply structure shaped by EASA qualification lock-in. The vendor base narrows as approved supplier lists consolidate around fiber-resin-preform triads capable of meeting 18-24 month material equivalency timelines. Three archetypes dominate: PAN-based carbon fiber producers, thermoplastic resin formulators, and automated fiber placement system integrators. Competitive dynamics center on backward integration into precursor supply and geographic co-location with final assembly lines.
Among carbon fiber specialists, Toray Industries and Hexcel Corporation exemplify the scale-driven archetype with established European manufacturing footprints. Solvay SA anchors the resin formulation tier through integrated polymer chemistry capabilities. These three entities represent the qualified supply triad that tier-one aerospace manufacturers depend upon for platform certification continuity.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| Solvay SA |
| DuPont |
| Airborne |
| SGL Carbon |
| Teijin Limited |
| Mitsubishi Chemical |
| Syensqo |
| Others |
Supply & Pricing Matrix
The Rhine-Main-Danube waterway corridor channels prepreg shipments from German resin plants to Toulouse and Hamburg assembly lines, compressing logistics costs for qualified suppliers within its catchment while amplifying price premiums for vendors outside this radius. EASA qualification lock-in narrows the approved vendor pool, granting pricing power to carbon fiber triads that have absorbed 18-24 month equivalency timelines.
Pricing Analysis
Three-tier pricing structure across EASA-qualified, process-qualified, and uncertified supplier levels segments the market by certification depth. Price differentiation tracks autoclave energy intensity and thermoplastic chemistry sophistication, with electron-beam curing commanding premiums over legacy thermal methods. Cost compression in thermoset prepregs is intensifying because out-of-autoclave alternatives bypass capital-intensive pressure vessel infrastructure. Narrow-body OEM procurement teams exhibit highest price sensitivity on secondary structures, while wing box programs tolerate premium resin systems for damage tolerance guarantees.
Supply Chain Analysis
Acrylonitrile feedstock draws from petrochemical complexes in Germany, Belgium, and the Netherlands, tethering PAN precursor costs to regional natural gas pricing. Carbon fiber tow, epoxy resin formulations, and brominated flame retardants constitute the critical input triad. Single-source vulnerability concentrates in qualified aerospace resin capacity held by the Toray-Hexcel-Solvay triad. Distribution runs through tier-one prepreggers co-located within 500 kilometers of Airbus final assembly sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service agreements bundling material supply with repair station accreditation are expanding faster than virgin prepreg hardware sales, creating recurring-revenue pools that outpace unit shipment growth. Airlines consolidating MRO spend around OEM-authorized networks are locking in decade-spanning service relationships.
For Market Incumbents: Build qualification moats by accelerating thermoplastic welding R&D investments ahead of next-generation fuselage programs. Anchor backward integration into PAN precursor supply to buffer acrylonitrile volatility. Defensive consolidation should target automated fiber placement system integrators in the Poland-Czech corridor before emerging players capture secondary structure volume. For New Entrants and Emerging Players: Pursue out-of-autoclave empennage qualification at UK-based tier-two suppliers where EASA timelines have created incumbent fatigue. Poland-Czech Republic automated fiber placement for secondary structures offers the most penetrable white space. A go-to-market angle anchored in CSRD-compliant recycled fiber certification addresses tier-one Scope 3 disclosure mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded aerospace resin assets awaiting REACH compliance resolution. Five-to-ten year viability hinges on thermoplastic platform adoption curves outpacing legacy thermoset fleet support obligations. Watch electron-beam curing facility announcements as inflection signals for next-generation capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Welding Automation | Induction heating convergence with robotic path planning eliminates rivet count at Hamburg fuselage assembly. |
| Backward Integration into Precursor | Captive acrylonitrile supply secures margin stability against petrochemical feedstock swings. |
| CSRD-Compliant Recycling Certification | Certified recycled fiber content addresses tier-one supplier Scope 3 disclosure requirements. |
| Out-of-Autoclave Qualification | Void content below 1% without pressure vessel curing bypasses energy intensity constraints. |
| Repair Station Network Accreditation | Lufthansa Technik and British Airways Engineering vendor consolidation captures in-service fleet spend. |
Research Methodology
A spread of perspectives from composite plant managers, Airbus procurement leads, EASA certification engineers, and aftermarket service heads converged on the working assumptions around thermoplastic adoption timelines. Primary interviews triangulated against customs data for carbon fiber imports, EASA airworthiness directive filings, EU Green Deal industrial emissions disclosures, and SEC filings from qualified resin suppliers. Bottom-up segment sizing cross-checked with top-down aerospace production forecasts.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling CFRP versus GFRP material splits, autoclave versus out-of-autoclave process shares, and structural versus interior application trajectories. CAGRs derived from production rate assumptions at Toulouse, Hamburg, and Broughton final assembly lines, filtered through REACH chemical authorization sunset schedules and CSRD disclosure phase-in requirements.
Sensitivities concentrate around EASA major change approval delays, acrylonitrile price volatility, and thermoplastic platform refresh timing. Forecasts embed assumptions about electron-beam curing scale-up and recycled fiber qualification pathways that industry stakeholders may revise. Cross-checking against Airbus monthly production bulletins and ECHA substance registration updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Space Electronics Market