
 Man-Portable Rocket Launcher Market | 2026-2036
Man-Portable Rocket Launcher Market Size, Share, and Industry Trends Forecast 2026-2036
Man-Portable Rocket Launcher Market Analysis
ITAR compliance is rebalancing the cost-of-entry calculus for foreign suppliers seeking Pentagon contracts. Lockheed Martin Corporation leverages its captive R&D infrastructure to sustain dominance in precision-guided platforms. Saab AB anchors Nordic supply chains through localized production and bilateral offset agreements with Baltic partners.
A man-portable rocket launcher is an individual-served, tube-based or rail-fired weapon system typically weighing under twenty kilograms, designed to deliver unguided or precision-guided munitions against armored vehicles, fortifications, or low-altitude aerial targets. The system employs shaped-charge or tandem-warhead configurations with effective ranges spanning fifty to one thousand meters depending on guidance architecture. Shoulder-fired variants remain the volume backbone for infantry squads, while guided segments capture disproportionate margin pools due to sensor fusion and fire-and-forget seeker costs. Thermal Imaging and Laser Guidance technologies are displacing unguided stocks in procurement budgets across mechanized units.
The US State Department's Directorate of Defense Trade Controls, the EU's Common Position on arms exports, and NATO's Standardization Office collectively shape cross-border transfer protocols and technical interoperability mandates. These frameworks determine which platforms qualify for allied procurement pools and which face end-use monitoring restrictions. Stakeholders must track evolving classification thresholds for precision-strike components as dual-use technology controls tighten across supplier nations.
Market Dynamics
Precision-guided munitions are compressing procurement cycles for unguided systems across NATO mechanized infantry formations, forcing suppliers to reconfigure R&D pipelines toward sensor fusion architectures.
Growth Catalysts
- Counter-Urban Warfare Doctrine:The US Department of Defense's operational emphasis drives demand for confined-space capable launchers with reduced backblast signatures.
- EU Common Position Alignment:Harmonized export licensing across member states accelerates cross-border procurement pooling for Baltic defense initiatives.
- Tandem Warhead Proliferation:Reactive armor penetration requirements propel adoption of dual-charge configurations in Eastern European inventories.
Market Restraints
- Infrared Seeker Supply Concentration:US-based focal plane array manufacturers control critical thermal imaging component flows, creating single-source vulnerability.
- ITAR Classification Thresholds:State Department export controls impose multi-year compliance timelines on foreign platform integrators seeking Pentagon contracts.
- Grenade Launcher Substitution:Automatic 40mm systems compete for squad-level anti-structure missions at lower per-unit cost.
Strategic Opportunities
- Baltic Offset Agreements:Estonia, Latvia, and Lithuania mandate localized final assembly, opening captive production slots for Nordic suppliers.
- Laser-Guided Retrofit Kits:Beam-riding modules transform existing unguided stocks without full system replacement.
- Special Operations Channel Expansion:Direct procurement authority for SOCOM units bypasses standard acquisition bureaucracy.
Industry Challenges
- Seeker Integration Complexity:Fire-and-forget algorithms demand software engineering talent scarce in traditional ordnance suppliers.
- NATO Standardization Office Timelines:STANAG certification for new guidance protocols extends development-to-fielding intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Man-Portable Rocket Launcher Market |
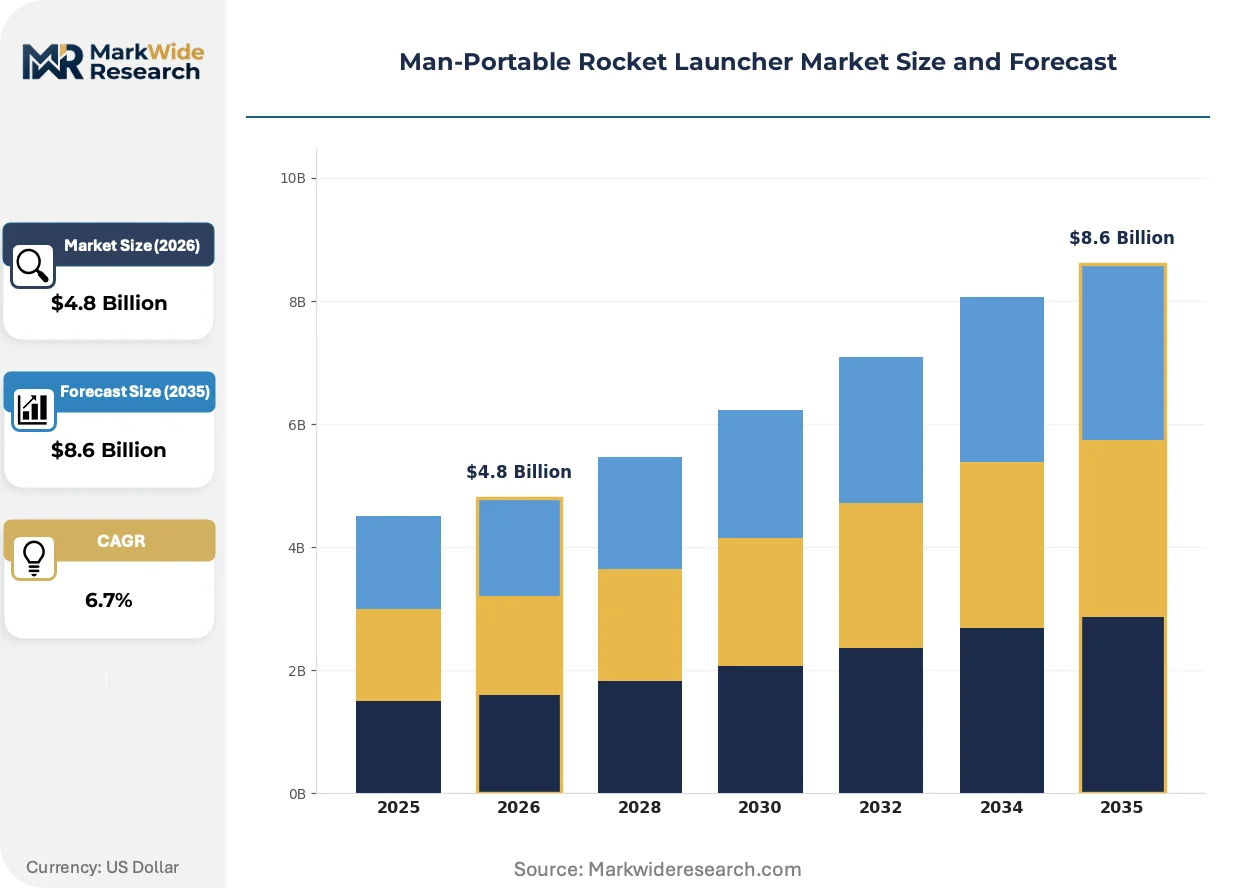
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoulder-fired, Multi-tube, Recoil-less, Guided Technology: Thermal Imaging, Laser Guidance, Precision Guidance, Smart End User: Military, Law Enforcement, Private Security, Special Operations Application: Anti-tank, Air Defense, Ground Support, Urban Warfare |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, General Dynamics Corporation, Saab AB, MBDA, BAE Systems, Thales Group, Rafael Advanced Defense Systems, ASELSAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Man-Portable Rocket Launcher Market Emerging Trajectories
Active seeker architectures are reconfiguring competitive advantage away from tube manufacturing toward software-defined targeting ecosystems.
Thermal clip-on modules is overtaking standalone night-vision configurations as the baseline specification for shoulder-fired systems. Mechanized squads in Poland and Romania now require fused thermal-laser designation packages for all new procurements. This compression of the electro-optical stack is marginalizing analog sighting equipment and elevating margin capture toward sensor suppliers.
The EU's Common Position on arms exports now mandates end-use monitoring for all precision-strike components, extending documentation obligations through operational lifecycle. German and French suppliers face expanded reporting requirements for transfers outside NATO membership. Baltic partners are responding by concentrating procurement within allied frameworks to streamline compliance.
Unit-level maintenance contracts now unbundle from hardware acquisition, shifting lifecycle revenue toward depot-service providers. Nordic defense forces pioneered this separation, with Danish and Norwegian army procurement offices treating launchers as capital assets and sensors as consumable subsystems. This bifurcation is visible across mechanized units prioritizing rapid seeker swap-out over platform longevity.
Man-Portable Rocket Launcher Market Segmentation
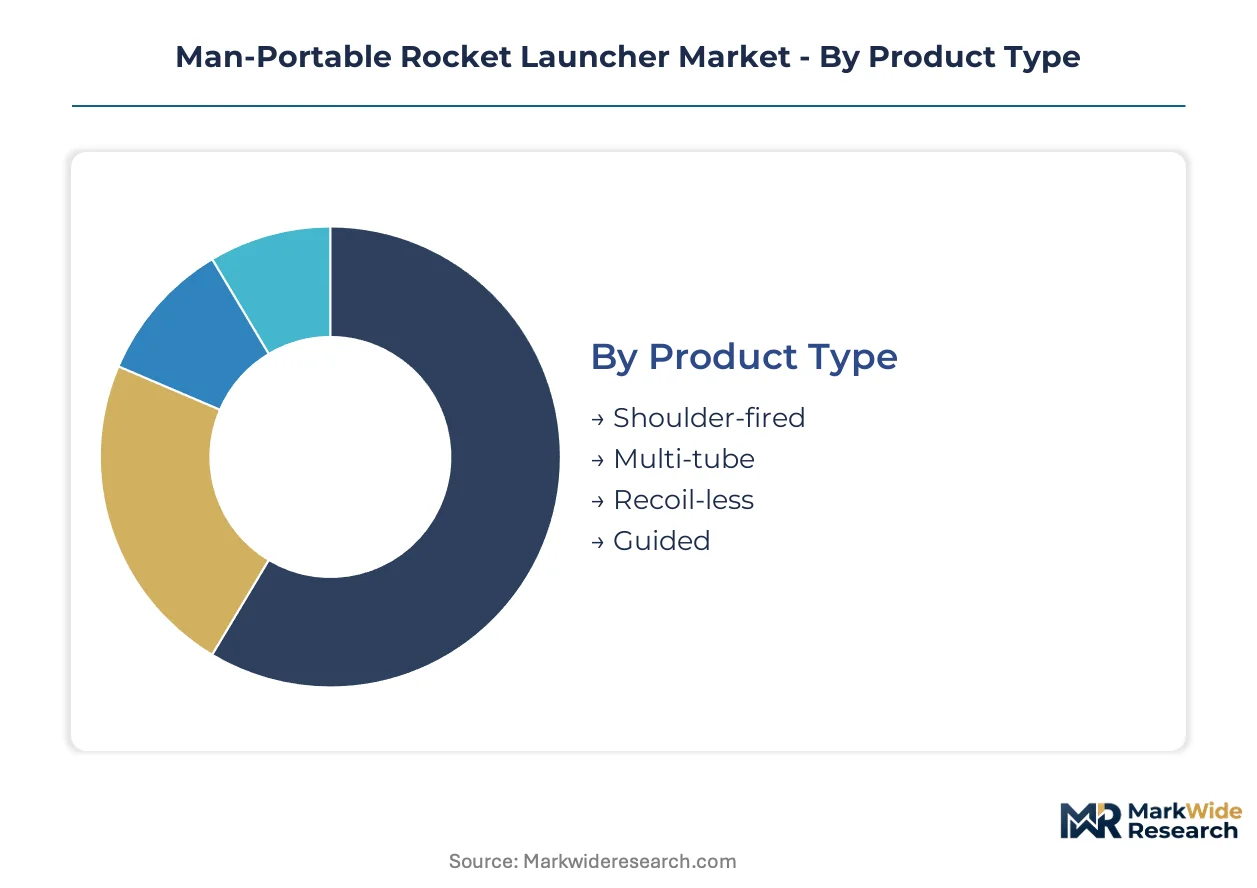
Procurement officers segment man-portable rocket launchers by operational environment and target profile, not hardware specifications alone. The divergence between unguided tube systems and precision-guided platforms creates distinct supplier ecosystems with incompatible R&D footprints.
Product Type:
Cost tier separates infantry squads from mechanized formations in this category.
- Shoulder-fired:Tube-based systems weighing under seven kilograms dominate squad-level inventories across NATO mechanized units. Polish and Romanian army procurement offices specify these as baseline equipment for every fire team, driven by unit cost ceilings and minimal training requirements.
- Guided:Fire-and-forget architectures with onboard seekers command disproportionate margin pools due to sensor fusion complexity. US Special Operations Command channels direct procurement authority toward these systems, bypassing standard acquisition timelines for counter-urban warfare missions.
- Multi-tube:Clustered launch configurations for area suppression roles.
- Recoil-less:Backblast-reduced variants for confined-space deployment.
Volume sits with Shoulder-fired; growth tilts toward Guided.
Technology:
Application environment dictates sensor package selection more than launcher hardware.
- Thermal Imaging:Clip-on focal plane arrays now displace standalone night-vision equipment as baseline specification. Danish and Norwegian forces pioneered treating these as consumable subsystems, elevating margin capture toward sensor suppliers and away from tube manufacturers.
- Laser Guidance:Beam-riding modules enable precision strike without full system replacement. Baltic defense initiatives concentrate procurement of retrofit kits to extend existing unguided stocks, accelerating cross-border pooling under EU Common Position alignment.
- Precision Guidance:Integrated seeker-and-control packages for fire-and-forget engagement.
- Smart:Network-enabled systems with programmable fuzing and target discrimination.
Thermal Imaging captures current procurement volume; Laser Guidance offers the steepest expansion trajectory through retrofit economics.
End User:
Maturity of doctrine determines guidance architecture adoption rates.
- Military:Mechanized infantry formations across NATO standardize on tandem-warhead configurations for reactive armor penetration. The US Department of Defense's counter-urban warfare emphasis drives confined-space capable launcher specifications with reduced backblast signatures.
- Special Operations:Direct procurement authority enables rapid fielding of experimental seeker architectures. SOCOM units bypass STANAG certification timelines, compressing development-to-deployment intervals for active seeker prototypes.
- Law Enforcement:Limited procurement for counter-terrorism and high-risk warrant service.
- Private Security:Restricted market constrained by end-use monitoring protocols and ITAR classification thresholds.
Military accounts for installed base; Special Operations is gaining share fastest through streamlined acquisition channels.
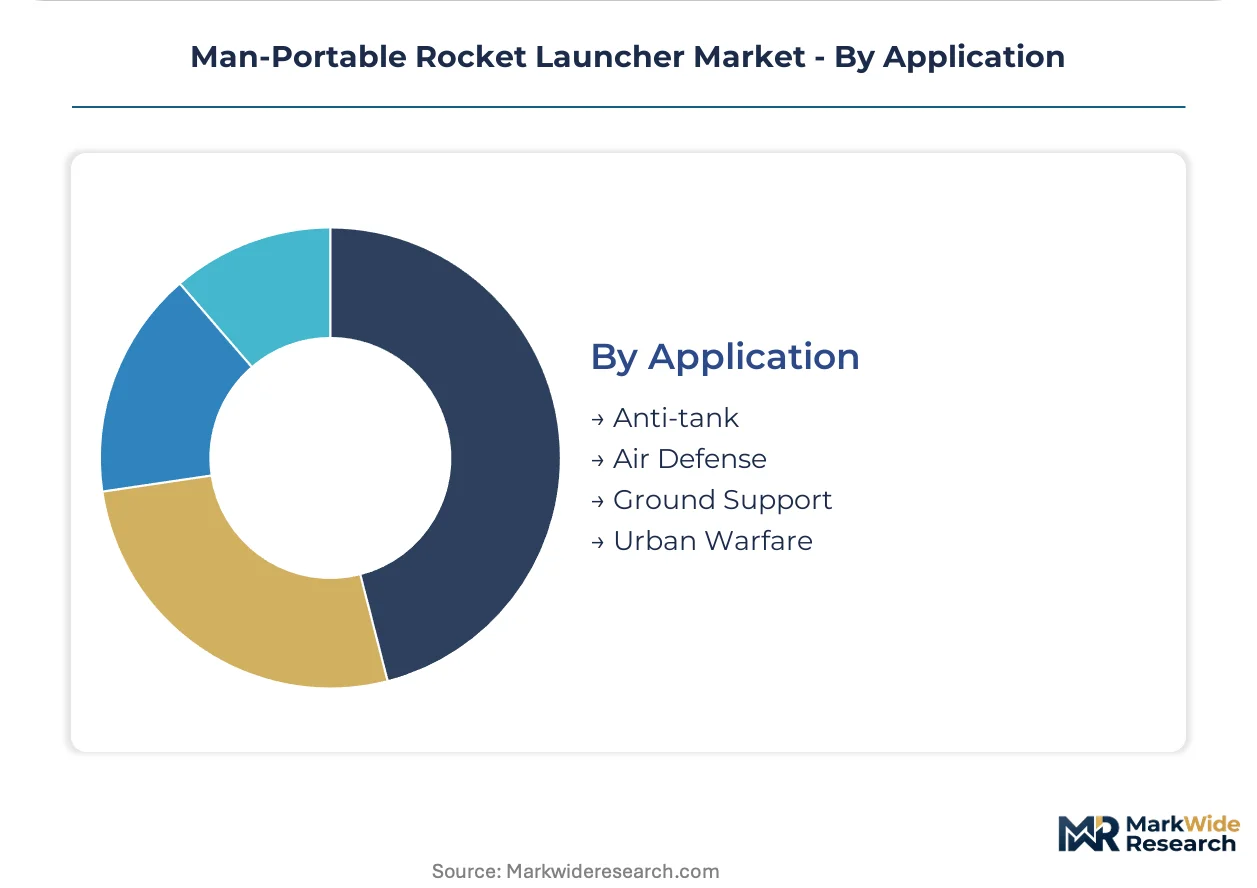
Application:
Target kinematics drive guidance complexity requirements.
- Anti-tank:Tandem-warhead configurations penetrate reactive armor through dual-charge sequencing. Eastern European inventories prioritize these specifications following regional threat assessments, with localized final assembly mandated through Baltic offset agreements.
- Urban Warfare:Reduced-signature launchers with confined-space backblast management. The US Department of Defense's operational emphasis reshapes training protocols and deployment doctrine for subterranean and built-up area engagement.
- Air Defense:Man-portable systems against low-altitude rotary-wing and UAV targets.
- Ground Support:Direct fire against fortified positions and light structures.
Anti-tank represents legacy volume concentration; Urban Warfare climbs the fastest as doctrine evolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement incentives in the United States concentrate prime contractor activity around Huntsville, Alabama, and Orlando, Florida, where ITAR-compliant special economic zones accelerate foreign military sales processing.
United States
Modernization cycles for infantry squads drive shoulder-fired system demand through Program Executive Office Soldier. The Department of Defense's Directorate of Defense Trade Controls enforces multi-year compliance timelines on platform integrators. Huntsville's Redstone Arsenal anchors production clustering for precision-guided munitions development.
Poland
Tandem-warhead configurations for reactive armor penetration dominate mechanized unit procurement following regional threat assessments. EU Common Position alignment harmonizes export licensing for Baltic defense initiative pooling. Localized final assembly mandates in Warsaw and Poznań open captive production slots for Nordic suppliers.
Germany
Counter-urban warfare doctrine adoption reshapes training protocols for confined-space launcher specifications. The Federal Office for Economic Affairs and Export Control extends end-use monitoring documentation through operational lifecycle. Industrial concentration in Bavaria and Baden-Württemberg supports sensor fusion subsystem integration.
Sweden
Bilateral offset agreements with Baltic partners anchor Nordic supply chain localization requirements. The Swedish Inspectorate of Strategic Products mandates expanded reporting for precision-strike component transfers. Saab AB's Linköping facilities concentrate guided platform R&D and captive manufacturing infrastructure.
Israel
Active seeker prototype development for special operations channels compresses development-to-deployment intervals. The Ministry of Defense's Defense Export Control Agency regulates dual-use technology thresholds for thermal imaging components. Rafael Advanced Defense Systems in Haifa exemplifies fire-and-forget algorithm integration capabilities.
Man-Portable Rocket Launcher Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base concentrates around five prime contractors capturing Pentagon and allied defense ministry contracts, with mid-tier integrators filling offset-driven localization mandates. Two strategic archetypes dominate: systems integrators with captive R&D infrastructure, and component specialists supplying seeker and guidance subassemblies. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers reposition toward sensor-defined targeting ecosystems.
Within the systems integrator tier, Lockheed Martin Corporation and RTX Corporation occupy positions defined by ITAR-compliant infrastructure and precision-guided platform portfolios. Saab AB anchors Nordic supply chain configurations through bilateral offset agreements. These three entities exemplify the divergence between volume-scale tube manufacturing and margin-capture sensor integration.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| General Dynamics Corporation |
| Saab AB |
| MBDA |
| BAE Systems |
| Thales Group |
| Rafael Advanced Defense Systems |
| ASELSAN |
| Others |
Supply Flow & Price Mechanics
Guided-versus-unguided system bifurcation splits procurement budgets into two incompatible cost structures, with sensor fusion platforms commanding five-to-ten-fold unit premiums over tube-based alternatives while concentrating supplier margins in US and Israeli electro-optical component houses. This divergence forces Baltic and Nordic defense ministries to segment acquisition timelines, front-loading unguided volume purchases while deferring precision-guided commitments until offset negotiations secure localized final assembly rights.
Pricing Analysis
Short-lead-time premiums dominate contract negotiations, with Pentagon Program Executive Office Soldier paying substantial markups for rapid fielding of counter-urban warfare configurations while allied ministries secure discounted pricing through multi-year framework agreements. Three-tier pricing structure across precision-guided, thermal-equipped, and baseline unguided levels reflects certification grade and ITAR compliance burden. Cost compression in unguided segments intensifies because Polish and Romanian mechanized units prioritize volume procurement over sensor sophistication. Law enforcement buyers exhibit highest price sensitivity due to constrained counter-terrorism budgets.
Supply Chain Analysis
Baltic offset mandates and EU Common Position localization rules are reshaping sourcing patterns, compelling Nordic suppliers to establish captive assembly in Estonia, Latvia, and Lithuania rather than consolidate production in Sweden. Infrared focal plane array manufacturing concentrates in the United States, Israel, and France, while tube fabrication draws from Germany, Poland, and Sweden. Single-source vulnerability pervades thermal seeker component flows, with US-based manufacturers controlling critical focal plane array output. Distribution runs through defense ministry procurement offices and NATO Standardization Office-certified channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as software-defined targeting ecosystems marginalize pure-play tube manufacturers lacking sensor fusion capabilities, forcing subscale ordnance houses toward acquisition or exit.
For Market Incumbents: Hedge against seeker supply concentration by securing dual-source agreements with Israeli and French focal plane array suppliers, while accelerating backward integration into thermal imaging component production. ITAR compliance timelines and STANAG certification delays threaten Lockheed Martin and RTX Corporation margins if uncaptured by captive R&D infrastructure. For New Entrants and Emerging Players: Capture white-space in laser-guided retrofit kit provision for Eastern European unguided stock modernization, where Baltic defense initiatives concentrate procurement under EU Common Position alignment. Beam-riding module integration offers the most penetrable entry vector, with direct SOCOM channel engagement providing fastest path to revenue validation. For Investors and Strategic Acquirers: Re-rating potential sits with sensor fusion specialists given NATO mechanized unit procurement shifts toward fire-and-forget architectures. Long-term viability favors targets with established ITAR-compliant infrastructure and active seeker algorithm portfolios. Watch STANAG certification timeline compression as inflection indicator for development-to-deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Seeker Technology Acquisition | Active seeker algorithm capabilities compress development cycles for SOCOM counter-urban warfare programs. |
| Baltic Offset Compliance | Localized final assembly in Estonia satisfies EU Common Position mandates and secures Nordic supply chain anchoring. |
| Thermal Imaging Backward Integration | In-house focal plane array production mitigates single-source vulnerability from US component suppliers. |
| Laser-Guided Retrofit Development | Beam-riding modules extend existing unguided inventory life without full system replacement costs. |
| SOCOM Channel Direct Engagement | Bypassing standard Pentagon acquisition timelines accelerates experimental seeker architecture fielding. |
Methodological Framework
Independent corroboration across defense ministry procurement officers, prime contractor program managers, and Baltic offset negotiation teams underwrites the qualitative findings, with secondary validation drawing from NATO Standardization Office certification records, US State Department Directorate of Defense Trade Controls licensing databases, and EU Common Position implementation reports. Primary interviews with Special Operations Command acquisition specialists, Danish and Norwegian army procurement directors, and Saab AB supply chain executives combined with bottom-up and top-down triangulation across the analysis window.
Rate-of-change decomposition separates volume growth in shoulder-fired unguided systems from value expansion in precision-guided platforms, modeling across product type, guidance technology, end-user maturity, and regional regulatory cluster dimensions. CAGRs derive from procurement pipeline visibility and doctrine evolution trajectories, with forecast inputs incorporating ITAR compliance timeline assumptions and STANAG certification interval estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to infrared seeker supply disruptions, Baltic offset renegotiations, and counter-urban warfare doctrine adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market