
 Surface to Air Missiles Market | 2026-2036
Surface to Air Missiles Market Size, Share, and Industry Trends Forecast 2026-2036
Surface to Air Missiles Market Analysis
Aftermarket sustainment and depot-level refurbishment is reshaping margin distribution across the Surface to Air Missiles landscape. Lockheed Martin Corporation leverages its PAC-3 MSE production footprint to capture recurring upgrade revenue streams. RTX Corporation sustains long-term service contracts through its Patriot ecosystem dominance in European basing corridors. MBDA anchors continental European demand via its Aster family production lines in France and Italy.
Surface to air missiles are self-propelled guided weapons designed to intercept aerial threats including aircraft, cruise missiles, and unmanned systems, typically employing dual-pulse solid rocket motors and active radar seekers for terminal engagement. These systems serve as territorial air defense nodes, creating exclusion zones against hostile incursion. Medium-range missiles command the largest procurement volume due to their balance of coverage area and mobility, while infrared guidance technology experiences accelerated investment as counter-stealth and low-signature target requirements intensify. Long-range missiles concentrate the highest unit margins, reflecting exotic propulsion and sensor fusion complexity.
The US Department of Defense and NATO standardization bodies enforce interoperability mandates that shape transatlantic procurement alignment, while national regulators in France, Germany, and Poland impose localized industrial participation requirements. The EU's evolving defense procurement directives progressively relax cross-border competition constraints, enabling consolidated European tenders. Stakeholders must monitor hypersonic threat maturation timelines and corresponding seeker architecture bets to align R&D portfolios with emerging operational requirements.
Market Dynamics
Dual-pulse solid rocket motor architectures are displacing legacy single-pulse designs across medium-range interceptors, compressing seeker refresh cycles and forcing subsystem suppliers to recalibrate thermal management roadmaps.
Growth Catalysts
- Counter-hypersonic mandates:The US Department of Defense's next-generation interceptor programs accelerate propulsion and sensor fusion R&D across NATO-aligned industrial bases.
- Indo-Pacific territorial tensions:Sovereign missile shield investments in Japan, Australia, and South Korea expand procurement pipelines for layered air defense batteries.
- REACH-compliant materials substitution:European manufacturers reformulate solid propellant binders to meet ECHA chemical restrictions, creating qualified supplier advantages.
Market Restraints
- Gallium nitride substrate scarcity:Active electronically scanned array seeker production faces chokepoints from concentrated semiconductor foundry capacity in East Asia.
- US ITAR export controls:State Department licensing timelines extend delivery schedules for non-NATO buyers, compressing competitive windows.
- Legacy system path dependency:Existing Patriot and SAMP/T basing infrastructure limits rapid platform switching for European operators.
Strategic Opportunities
- Poland's Wisła and Narew programs:Europe's largest missile defense procurement pipeline creates offset manufacturing opportunities for component suppliers.
- Directed energy convergence:Laser-based close-in weapon systems paired with kinetic interceptors enable layered defense architectures against drone swarms.
- EU defense procurement directive liberalization:Relaxed cross-border tender rules enable consolidated European consortium bidding against US primes.
Industry Challenges
- Seeker algorithm talent scarcity:Terminal guidance software engineering expertise concentrates in aerospace hubs around Tucson, Huntsville, and Munich.
- All-up-round test range capacity:Pacific and Atlantic missile test corridors face scheduling bottlenecks that compress development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface to Air Missiles Market |
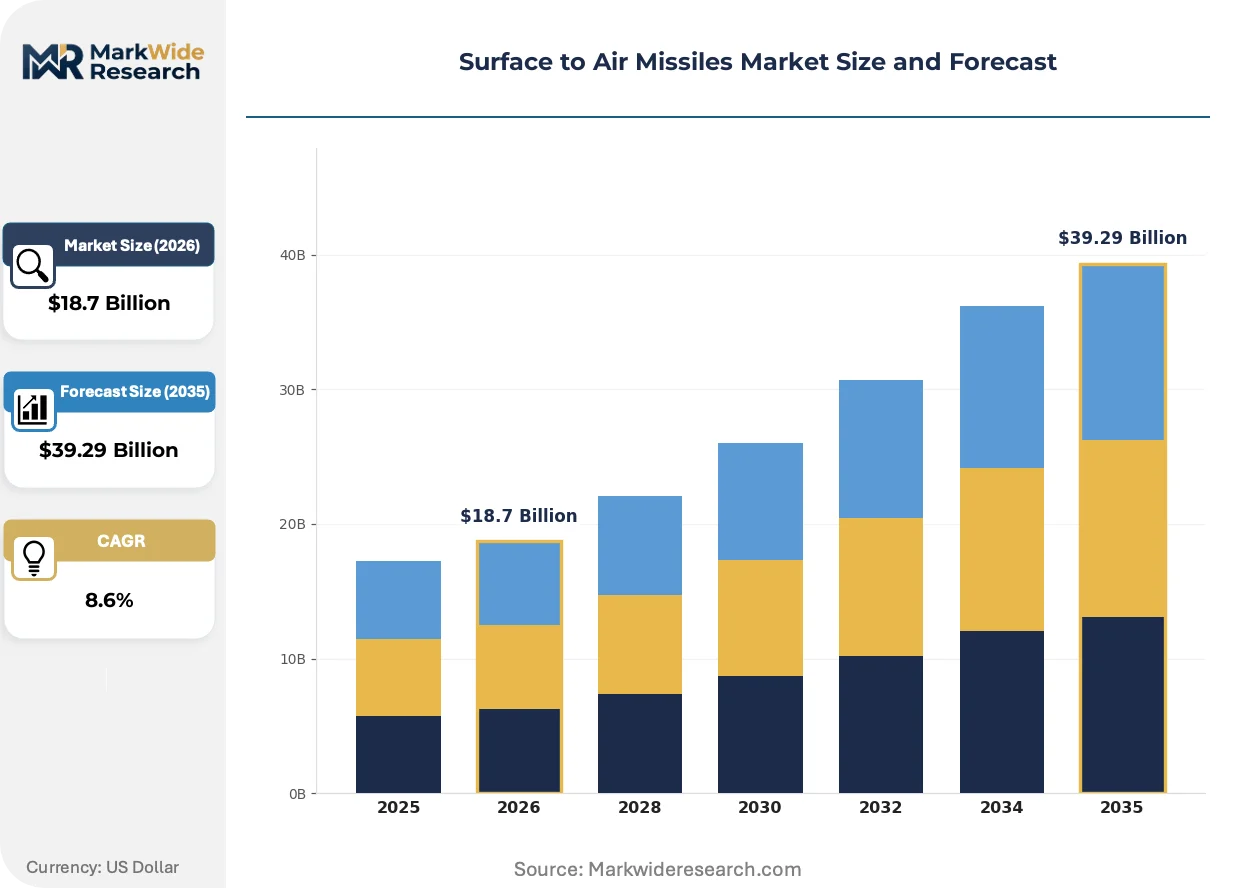
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short-Range Missiles, Medium-Range Missiles, Long-Range Missiles, Very Long Range Missiles Technology: Active Radar Guidance, Passive Radar Guidance, Command Guidance, Infrared Guidance End User: Military Forces, Defense Contractors, Government Agencies, Private Security Firms Application: Air Defense, Anti-Terrorism, Peacekeeping Operations, Conflict Zones |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, MBDA, Northrop Grumman Corporation, Thales Group, BAE Systems, Israel Aerospace Industries Ltd., Raytheon Technologies Corporation, Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface to Air Missiles Market Emerging Trajectories
Active radar seeker architectures are compressing engagement timelines while passive infrared augmentation addresses low-signature target detection. These shifts reshape subsystem supplier hierarchies and qualification pathways.
Dual-mode seeker technology is migrating from experimental demonstrators into serial production configurations. Medium-range interceptors for mobile land-based batteries now integrate millimeter-wave radar with imaging infrared focal plane arrays. This convergence is compressing the terminal engagement envelope and displacing single-mode seekers in NATO standardization drafts.
The EU's F-Gas Regulation and associated ECHA restrictions on per- and polyfluoroalkyl substances are forcing reformulation of solid rocket motor insulation and nozzle throat materials. French and Italian manufacturers now qualify silicon carbide-ceramic matrix composites as replacements. Medium-range systems with shorter design cycles adapt faster than heavy strategic interceptors locked in decade-long development.
Buyers are unbundling aftermarket sustainment from initial platform procurement. European operators now contract depot-level refurbishment separately from missile all-up-round purchases, compressing OEM service revenue streams. This pattern concentrates in Germany and Poland where defense budget transparency rules mandate competitive tendering for multi-year support contracts.
Surface to Air Missiles Market Segmentation
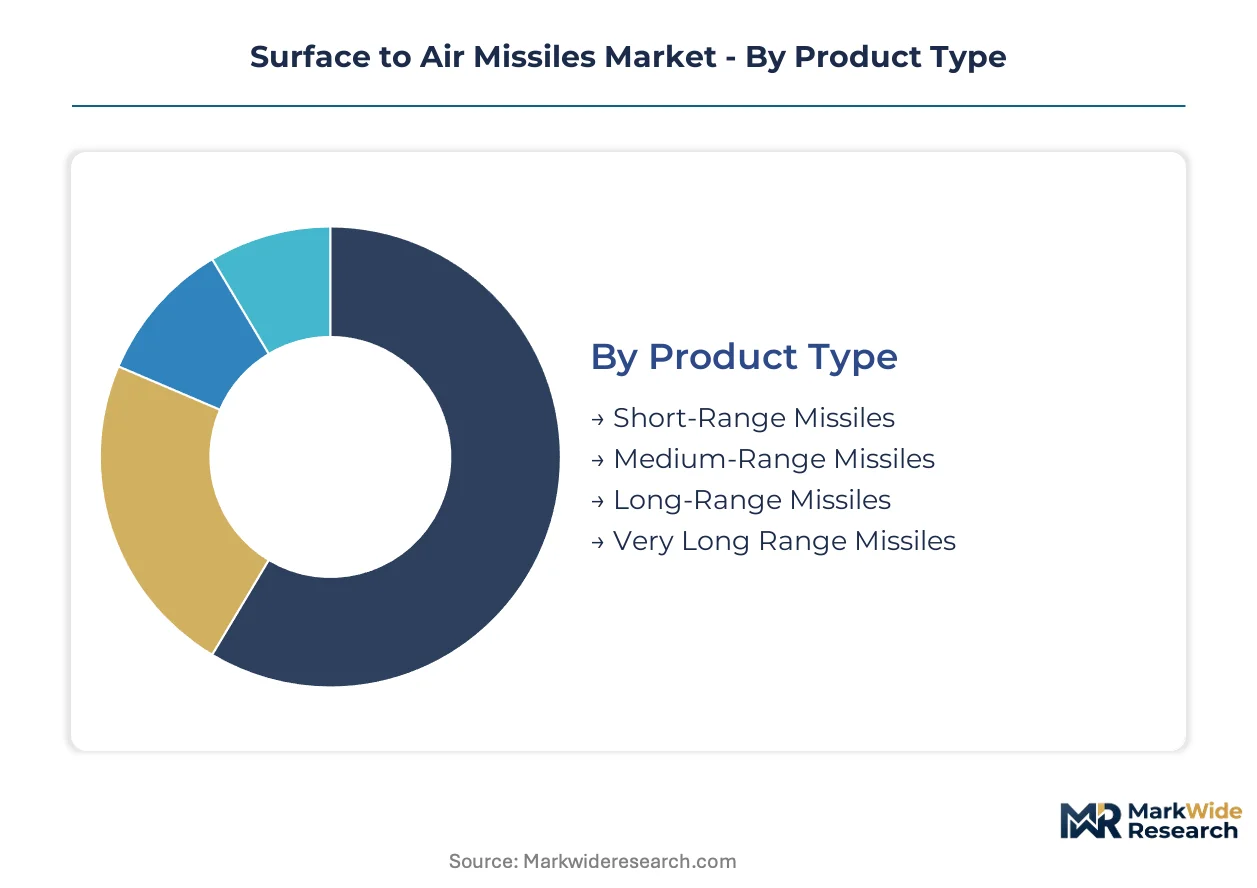
Segmentation in surface to air missiles reveals how mission profiles dictate technical specifications across range envelopes, guidance architectures, and operational contexts. Procurement patterns diverge sharply between territorial defense networks and expeditionary deployments.
Product Type:
Range envelopes define mobility requirements, battery density, and integration complexity across layered air defense architectures.
- Short-Range Missiles:These systems employ infrared or command guidance with minimal radar dependency, enabling rapid deployment in point-defense scenarios. Demand clusters around forward operating bases and critical infrastructure protection in Japan and South Korea, driven by saturation drone threats and cruise missile proliferation.
- Medium-Range Missiles:Dual-pulse solid rocket motors and active radar seekers balance coverage area with tactical mobility, making these systems the procurement volume leader. NATO's European basing corridors concentrate orders here, with Poland's Wisła and Narew programs exemplifying multi-billion dollar commitments to mobile land-based batteries.
- Long-Range Missiles:Exotic propulsion and sensor fusion architectures command premium unit economics for strategic area defense.
- Very Long Range Missiles:Upper-tier interceptors address ballistic missile threats through hit-to-kill kinetic vehicles and space-capable boosters.
The dominant share belongs to Medium-Range Missiles, while Short-Range Missiles are closing the gap fastest.
Technology:
Guidance modality determines countermeasure susceptibility, all-weather operability, and software complexity in terminal engagement phases.
- Active Radar Guidance:Onboard seekers with gallium nitride transmit/receive modules enable fire-and-forget autonomy against agile targets. Investment concentrates in US and European programs countering hypersonic glide vehicles, though semiconductor substrate scarcity constrains production scaling.
- Infrared Guidance:Imaging focal plane arrays detect low-signature aircraft through thermal contrast rather than radar cross-section. Japanese and Australian procurement for Indo-Pacific maritime scenarios accelerates adoption, as counter-stealth requirements intensify seeker diversification.
- Passive Radar Guidance:Home-on-jam architectures exploit adversary emitter signatures without revealing interceptor position.
- Command Guidance:Ground-controlled trajectory correction persists in cost-constrained deployments and legacy system integration.
Active Radar Guidance holds the installed base advantage, yet Infrared Guidance demonstrates the steepest expansion trajectory as dual-mode architectures mature.
End User:
Budget authority and operational doctrine shape procurement scale, technical specification access, and sustainment contracting models.
- Military Forces:Uniformed services execute sovereign air defense with full-spectrum system ownership and organic maintenance capabilities. US Army and Marine Corps modernization programs, alongside NATO force structure enhancements, anchor demand for next-generation interceptors with open architecture command systems.
- Defense Contractors:Prime integrators and subsystem suppliers capture recurring revenue through platform production and depot-level refurbishment. Long-term service contracts in Germany and Poland increasingly unbundle sustainment from initial procurement, compressing OEM margin structures.
- Government Agencies:Civil defense and homeland security organizations acquire point-defense capabilities for critical infrastructure.
- Private Security Firms:Commercial operators field limited short-range systems for facility protection in high-threat environments.
Military Forces account for the preponderance of contract value, though Defense Contractors are expanding their share through aftermarket capture.
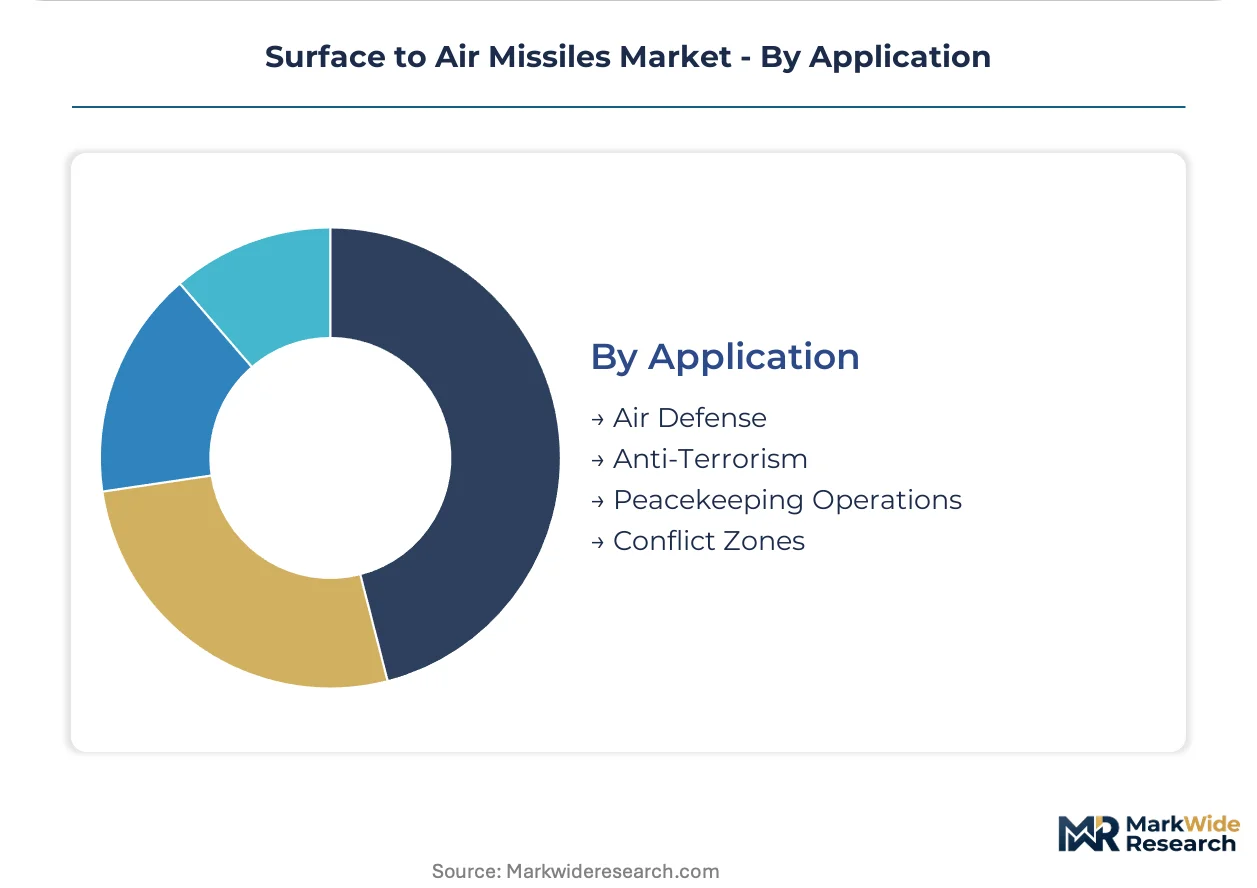
Application:
Operational context imposes rules of engagement constraints, collateral damage thresholds, and interoperability requirements that shape system selection.
- Air Defense:Territorial integrity missions demand layered coverage against manned aircraft, cruise missiles, and unmanned systems. Japan's missile shield investments and NATO's integrated air defense system exemplify procurement scale, with sovereign programs in Australia and South Korea adding Indo-Pacific pipeline depth.
- Conflict Zones:Contested environments prioritize rapid emplacement and disengagement with reduced logistics footprints. Ukrainian operational experience accelerates European interest in mobile, distributed batteries capable of shoot-and-scoot tactics against saturation attacks.
- Anti-Terrorism:Point defense against asymmetric aerial threats protects high-value targets and mass gatherings.
- Peacekeeping Operations:Restrictive rules of engagement favor non-kinetic or limited-lethality intercept options where collateral risk dominates.
Air Defense commands the structural majority of procurement volume, while Conflict Zones are gaining share fastest as expeditionary readiness requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland and South Korea demonstrate the highest procurement elasticity, driving volume through multi-billion dollar modernization programs. The United States and Japan maintain price-inelastic demand curves, prioritizing capability over unit cost in next-generation interceptor development. European buyers occupy the middle ground, balancing NATO interoperability mandates with national budget constraints.
United States
The US Department of Defense's counter-hypersonic mandates accelerate next-generation interceptor R&D across multiple service branches. ITAR export controls administered by the State Department extend licensing timelines for non-NATO buyers. Huntsville, Alabama and Tucson, Arizona anchor the domestic industrial base, concentrating seeker algorithm engineering talent and test range infrastructure.
Poland
The Wisła and Narew programs constitute Europe's largest missile defense procurement pipeline, driving demand for mobile land-based batteries. EU defense procurement directives progressively relax cross-border competition constraints, enabling consolidated European tenders. Warsaw and its surrounding industrial corridor host offset manufacturing facilities negotiated through foreign military sales agreements.
Japan
Sovereign missile shield investments respond to territorial tensions in the East China Sea, expanding procurement for layered air defense. METI coordinates industrial participation requirements with domestic security policy frameworks. The Kanto region around Tokyo concentrates prime integrator partnerships and subsystem supplier clusters for maritime-focused interceptors.
South Korea
Indo-Pacific theater positioning drives sustained investment in medium-range mobile batteries with rapid emplacement capabilities. The country's national defense procurement agency enforces localized content thresholds through offset agreements. The Seoul Capital Area hosts command system integration facilities and active radar seeker production partnerships.
Germany
Defense budget transparency rules mandate competitive tendering for multi-year sustainment contracts, unbundling aftermarket services from initial procurement. ECHA REACH compliance forces reformulation of solid propellant binders and insulation materials. Bavaria and Lower Saxony concentrate depot-level refurbishment capacity and qualified supplier networks for NATO-standard interceptors.
Surface to Air Missiles Market Vendor Landscape
Capability concentration sits with specialist seeker and propulsion houses; scale advantage sits with platform integrators commanding multi-decade service ecosystems. The market structures around three tiers: prime integrators with NATO baseline certifications, subsystem specialists qualified for gallium nitride seeker production, and regional champions serving non-aligned buyers. Dominant competitive moves include backward integration into solid rocket motor production and strategic partnerships for dual-mode seeker development.
Within the prime integrator tier, Lockheed Martin Corporation and RTX Corporation exemplify platform-scale competitors with established NATO supply chain positions. MBDA occupies a distinctive position as a European consortium anchor, reflecting continental industrial policy preferences for indigenous capability. These three entities represent divergent geographic alignment strategies while competing for overlapping procurement pipelines in Poland, Germany, and Indo-Pacific markets.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| MBDA |
| Northrop Grumman Corporation |
| Thales Group |
| BAE Systems |
| Israel Aerospace Industries Ltd. |
| Raytheon Technologies Corporation |
| Boeing Company |
| Others |
Supply Flow & Price Mechanics
Huntsville's concentrated seeker algorithm engineering base feeds directly into OEM pricing power for active radar guidance systems. Gallium nitride substrate scarcity from East Asian foundries compresses margins on terminal engagement electronics, while depot-level refurbishment unbundling in Germany and Poland shifts lifetime value capture toward aftermarket service tiers.
Pricing Analysis
Aftermarket sustainment contracts now drive lifetime value across NATO-aligned procurement corridors. Three-tier pricing structure across premium, standard, and economy levels separates exotic propulsion long-range interceptors from dual-pulse medium-range workhorses and command-guided legacy stocks. Price differentiation hinges on certification grade for gallium nitride seeker production and vertical integration into solid rocket motor manufacturing. Cost compression in short-range infrared systems is intensifying because Japanese and Australian buyers demand counter-stealth focal plane arrays at scale. Defense contractors exhibit highest price sensitivity due to unbundled tendering mandates, while sovereign military forces in Japan and the United States prioritize capability over unit economics.
Supply Chain Analysis
US ITAR export controls administered by the State Department restrict gallium nitride transmit/receive module flows to non-NATO buyers. Geographic supply concentration centers on the United States for seeker algorithm development, France and Italy for Aster-family propulsion systems, and South Korea for rapid emplacement battery integration. Raw material dependencies include silicon carbide-ceramic matrix composites for nozzle throat insulation, dual-pulse solid rocket motor propellant binders reformulated for ECHA REACH compliance, and imaging infrared focal plane arrays for maritime-focused interceptors. Single-source vulnerability concentrates in East Asian semiconductor foundry capacity for active electronically scanned array production. Distribution runs through foreign military sales agreements with offset manufacturing clauses and competitive tendering for multi-year sustainment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
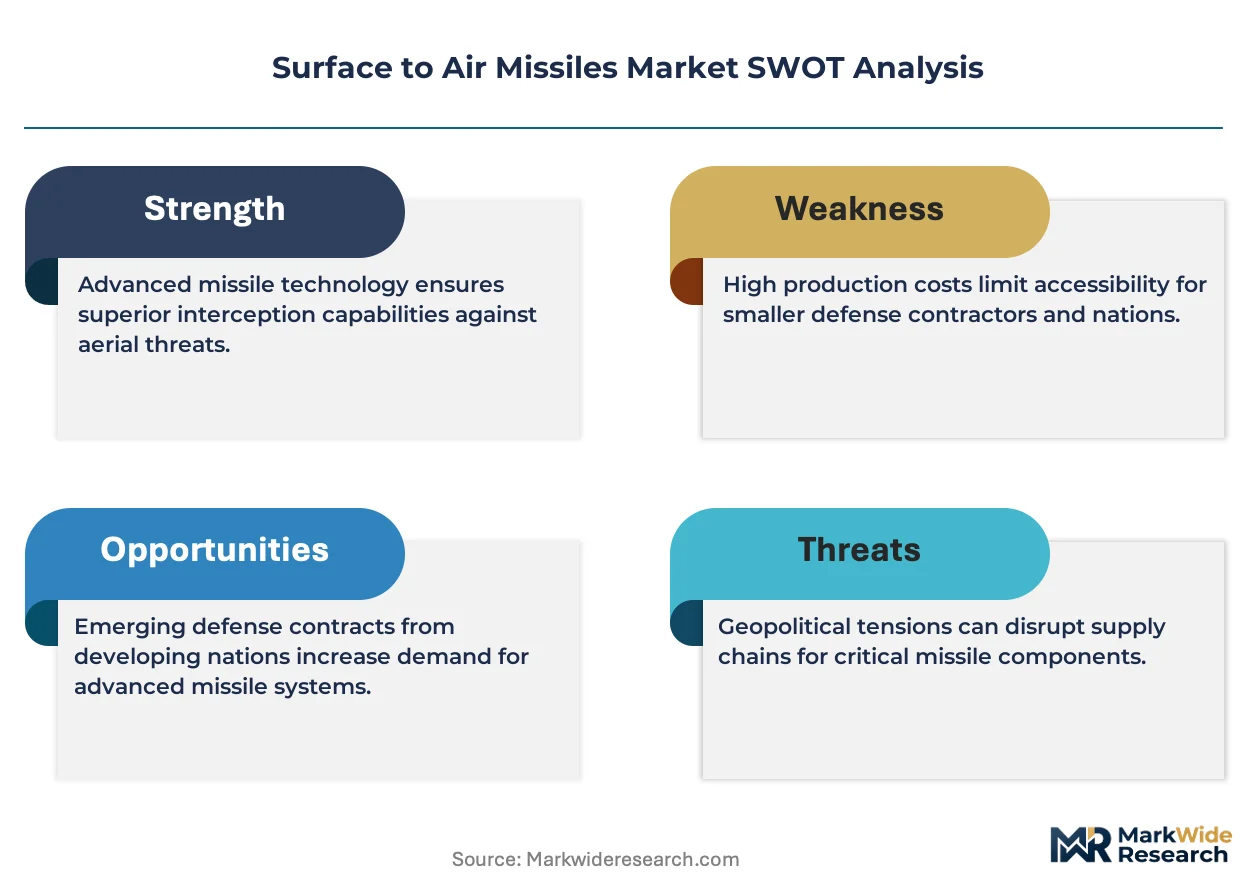
Incumbents face substitution defense against directed energy convergence threatening kinetic interceptor relevance in close-in weapon system applications. Laser-based layered defense architectures paired with traditional missiles demand portfolio recalibration across prime integrators.
For Market Incumbents: Harden seeker algorithm talent pipelines in Tucson, Huntsville, and Munich against terminal guidance software engineering scarcity. Backward integration into gallium nitride substrate sourcing mitigates semiconductor foundry chokepoint exposure. Lockheed Martin Corporation and RTX Corporation must defend PAC-3 MSE and Patriot ecosystem dominance against MBDA's consolidated European consortium bidding enabled by EU defense procurement directive liberalization.
For New Entrants and Emerging Players: Establish a beachhead in Poland's Wisła and Narew offset manufacturing corridors where Europe's largest missile defense procurement pipeline creates qualified supplier entry points. Short-range infrared systems for Indo-Pacific maritime scenarios represent the most penetrable segment given Japanese and Australian counter-stealth procurement acceleration. Go-to-market leverage rests on silicon carbide-ceramic matrix composite qualification for ECHA-compliant solid rocket motor insulation.
For Investors and Strategic Acquirers: Carve-out targets emerge from European prime integrators divesting non-core seeker production lines amid dual-mode sensor fusion consolidation. Five-to-ten year viability favors subsystem specialists with gallium nitride active electronically scanned array certifications and depot-level refurbishment footprints in Bavaria or Lower Saxony. Watch for directed energy weapon program budget acceleration as kinetic interceptor displacement signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Seeker Integration | Millimeter-wave radar paired with imaging infrared compresses terminal engagement envelopes for NATO standardization. |
| Gallium Nitride Substrate Sourcing | Active electronically scanned array production draws from captive supply agreements reducing East Asian foundry dependency. |
| REACH-Compliant Propellant Reformulation | ECHA chemical restrictions force silicon carbide-ceramic matrix composite adoption for solid rocket motor insulation. |
| Aftermarket Sustainment Unbundling | Competitive tendering for depot-level refurbishment compresses OEM service revenue streams in Germany and Poland. |
| Directed Energy Convergence | Laser-based close-in weapon systems paired with kinetic interceptors enable layered defense against saturation drone threats. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of defense procurement databases, foreign military sales agreements, and ECHA regulatory filings. Primary interviews engaged program executive officers at US Army and Marine Corps modernization directorates, procurement leads at Poland's national defense agency, seeker subsystem engineering directors in Tucson and Huntsville, and aftermarket service heads at German depot-level refurbishment facilities. Secondary validation drew from NATO standardization drafts, EU defense procurement directive texts, US State Department ITAR licensing records, and METI industrial coordination frameworks. Bottom-up triangulation across product type, range envelope, and guidance modality segmentation converged with top-down macro defense spending analysis.
Forecast inputs include propulsion architecture adoption curves, seeker technology refresh cycles, and sovereign missile shield investment commitments across the analysis window. Segmentation dimensions modeled encompass range envelope, guidance modality, end-user budget authority, and operational application context. CAGRs derived from polynomial trend fitting against historical procurement pipelines adjusted for technology substitution effects. Hypersonic threat maturation timelines and corresponding interceptor development schedules informed trajectory calibration.
Sensitivities concentrate around gallium nitride semiconductor supply disruption, ECHA chemical restriction scope expansion, and US ITAR licensing timeline extension. Forecasts reflect documented assumptions regarding NATO interoperability mandate continuity and Indo-Pacific territorial tension persistence. Material shifts in directed energy weapon program funding or EU defense procurement directive implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market