
 Global Military Artificial Intelligence (AI) Market | 2026-2036
Global Military Artificial Intelligence (AI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Artificial Intelligence (AI) Market Foresight
Modular AI payload architectures is hardening as the dominant procurement configuration, allowing defense buyers to swap algorithmic modules across drone swarms, ground robots, and maritime platforms without vendor lock-in. Lockheed Martin leverages its classified manufacturing scale to dominate integrated system deliveries for the U.S. Air Force and Navy. Anduril Industries competes through vertical control over its Lattice AI operating system, which spans counter-drone systems to autonomous underwater vehicles. Helsing specializes in real-time sensor fusion for European fighter jet modernization programs, anchoring its position in NATO electronic warfare upgrades.
Military artificial intelligence encompasses algorithmic systems designed for threat detection, decision acceleration, and autonomous platform control under contested electromagnetic conditions, typically operating with sub-100-millisecond inference latency on hardened edge processors. Its primary purpose is compressing the sensor-to-shooter timeline while reducing cognitive load on human operators in high-tempo combat environments. Machine learning platforms for predictive maintenance and target recognition currently capture the largest share of procurement value, while edge computing deployments for denied-communications environments represent the fastest-expanding segment as militaries prepare for satellite-degraded warfare. Computer vision applications for satellite imagery analysis command premium pricing due to classified training data scarcity and sovereign cloud requirements.
The U.S. Department of Defense, the EU AI Act enforcement structures, and the U.K. Ministry of Defence's AI ethics framework collectively shape vendor eligibility, data governance protocols, and cross-border technology transfer restrictions for military AI suppliers. Compliance with NATO's forthcoming AI certification standards will determine market access for non-aligned component providers. Stakeholders must monitor how export control expansions around foundation model weights reshape partnership structures between U.S. primes and allied startups.
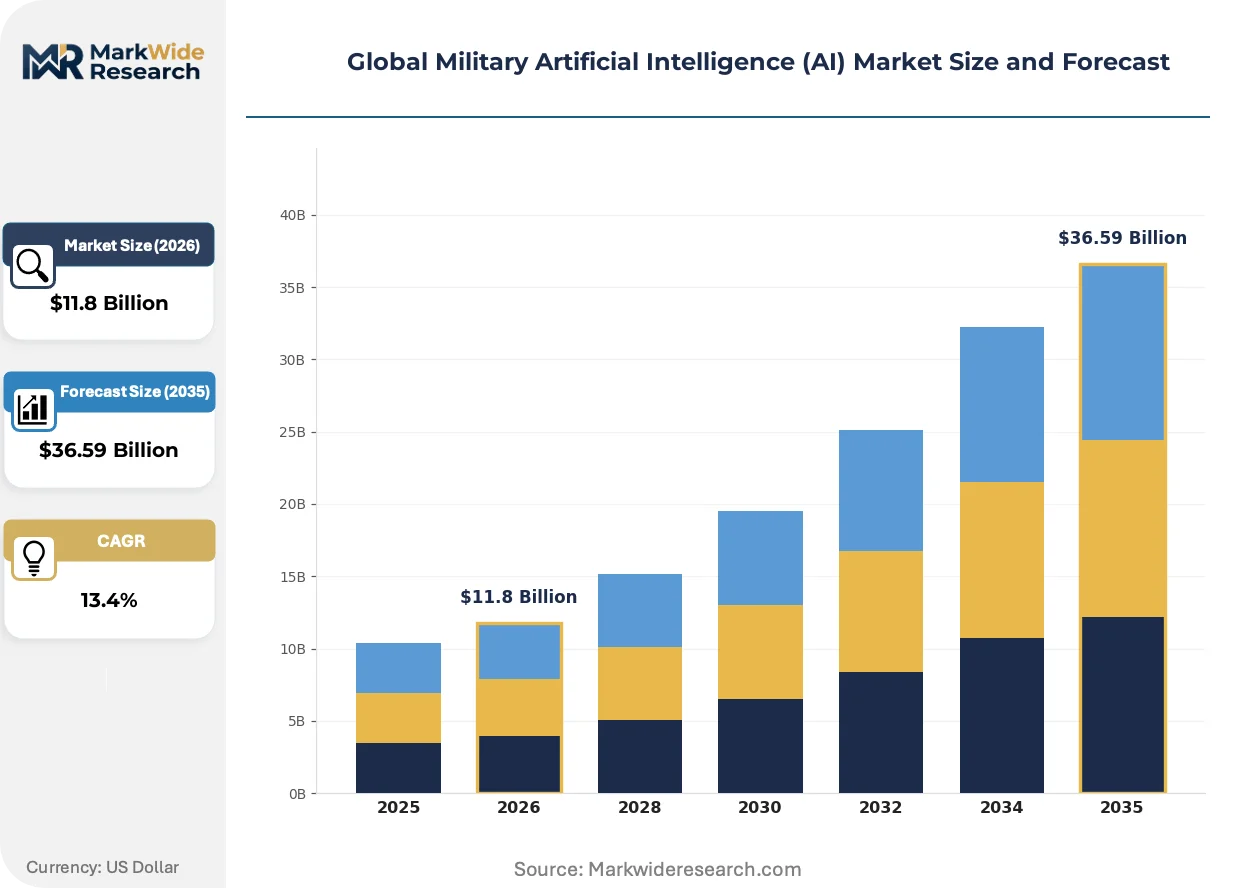
Market Dynamics
Modular AI payload architectures are compressing vendor lock-in cycles across NATO procurement channels, forcing defense primes to open algorithmic interfaces that were previously proprietary. This structural loosening is redistributing value from integrated system vendors to specialized software layer suppliers.
Growth Catalysts
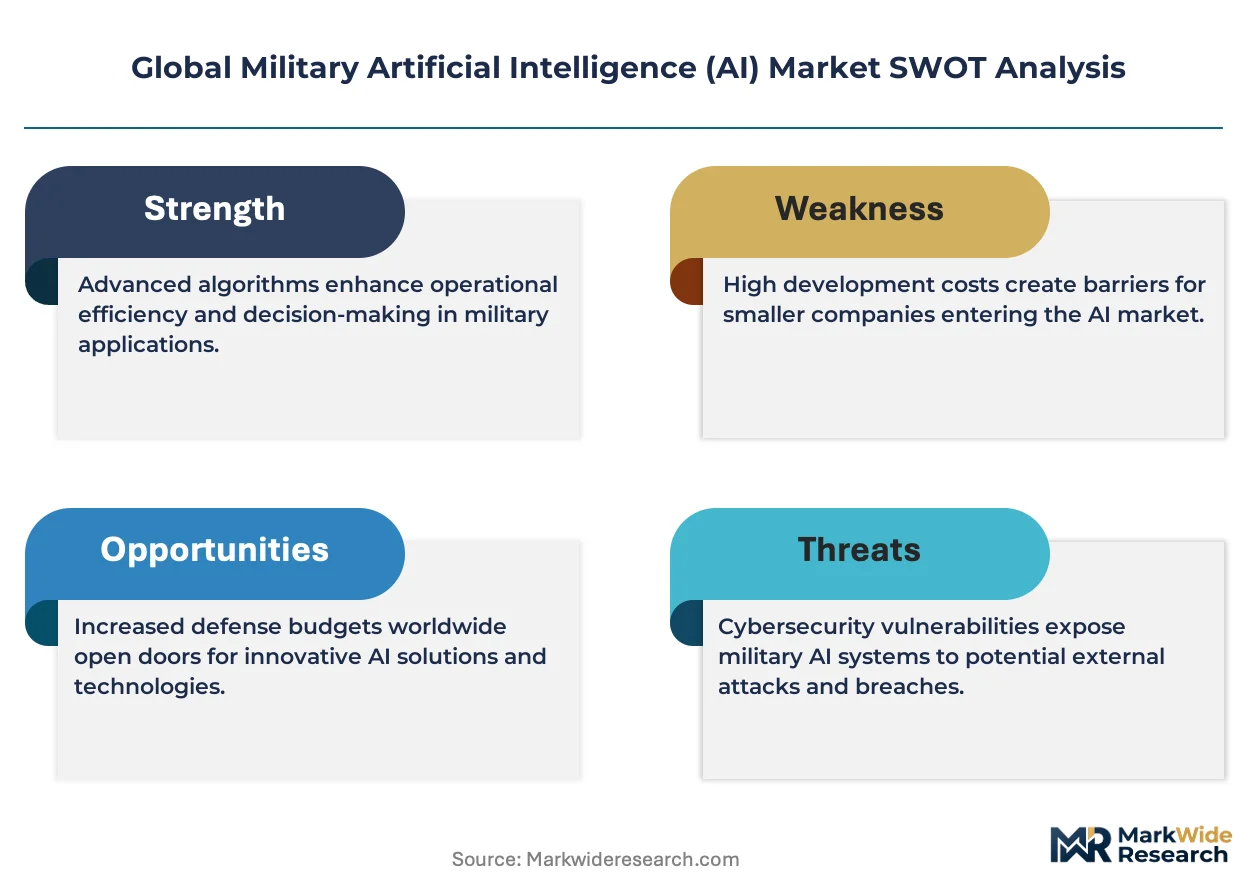
- EU AI Act enforcement structures:The Act's high-risk system classification is accelerating certification investments among European defense suppliers seeking NATO interoperability credentials.
- Autonomous vehicle fleets:Swarming drone procurement across multiple allied militaries is pulling real-time edge inference hardware into volume production.
- Sensor-to-shooter timeline compression:Electronic warfare modernization programs in contested electromagnetic environments are mandating sub-100-millisecond inference specifications.
Market Restraints
- Classified training data scarcity:Sovereign cloud requirements for satellite imagery analysis limit algorithmic development to cleared personnel pools, constraining model iteration velocity.
- Export control expansions:Foundation model weight restrictions are fragmenting partnership structures between U.S. primes and allied component startups.
- Hardened edge processor supply:Radiation-hardened semiconductor fabrication concentrates in a limited foundry base, creating single-point vulnerability for denied-communications deployments.
Strategic Opportunities
- Israeli classified AI defense budgets:The country's integrated military-civilian technology base offers testbed access for counter-drone and autonomous underwater vehicle validation.
- Machine learning for predictive maintenance:Fighter jet and naval platform operators are unbundling maintenance contracts to reward algorithmic uptime guarantees.
- Lattice-style vertical operating systems:Control over counter-drone-to-submarine software stacks enables recurring revenue capture across multiple platform categories.
Industry Challenges
- Cleared AI/ML engineering talent:Security clearance timelines lag algorithmic development cycles, forcing vendors to segment work between classified and unclassified engineering tracks.
- NATO AI certification standards:Forthcoming interoperability mandates require dual-track compliance investments that strain mid-tier supplier balance sheets.
- Legacy platform integration:Fighter jet and naval vessel modernization programs demand backward-compatible algorithmic interfaces that increase development complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Artificial Intelligence (AI) Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $36.59 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Autonomous Vehicles, Cyber Defense, Surveillance Systems, Command & Control, Logistics Optimization, Training Simulations Solution Type: Machine Learning Platforms, Natural Language Processing, Expert Systems, Computer Vision, Robotic Process Automation, Predictive Analytics Deployment Mode: On-Premises, Cloud-Based, Edge Computing, Hybrid Systems End User: Defense Contractors, Military Units, Intelligence Agencies, Research Institutions |
| Companies Covered | Shield AI, V2X, Anduril Industries, Redwire, Vannevar, Palantir Technologies, Lockheed Martin, AeroVironment, Helsing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Artificial Intelligence (AI) Market Shifts & Advancements
Algorithmic warfare is migrating from demonstration programs to operational procurement specifications, with defense buyers now requiring proven inference latency under contested conditions rather than laboratory benchmarks.
Neuromorphic computing architectures are overtaking conventional GPU-based inference for power-constrained platforms. Submarine and long-endurance drone programs are adopting spiking neural network chips that reduce wattage per inference by orders of magnitude. This shift is overtaking traditional von Neumann designs in NATO undersea warfare procurement, compressing supplier qualification lists to vendors with radiation-hardened neuromorphic fabrication partnerships.
The EU AI Act's high-risk system registry is mandating algorithmic audit trails for defense applications. Suppliers must now document training data provenance and model decision boundaries to maintain market access. European fighter jet modernization programs are most affected, with Helsing and comparable specialists restructuring engineering workflows to satisfy documentation requirements that precede certification.
Defense procurement officers are unbundling hardware and algorithmic performance guarantees. Traditional integrated system contracts are fragmenting into separate airframe, sensor, and software layer competitions that reward modular interoperability. The U.S. Air Force's Collaborative Combat Aircraft program exemplifies this pattern, with Anduril and Lockheed Martin competing on software stack openness rather than sole-source platform dominance.
Global Military Artificial Intelligence (AI) Market Segmentation
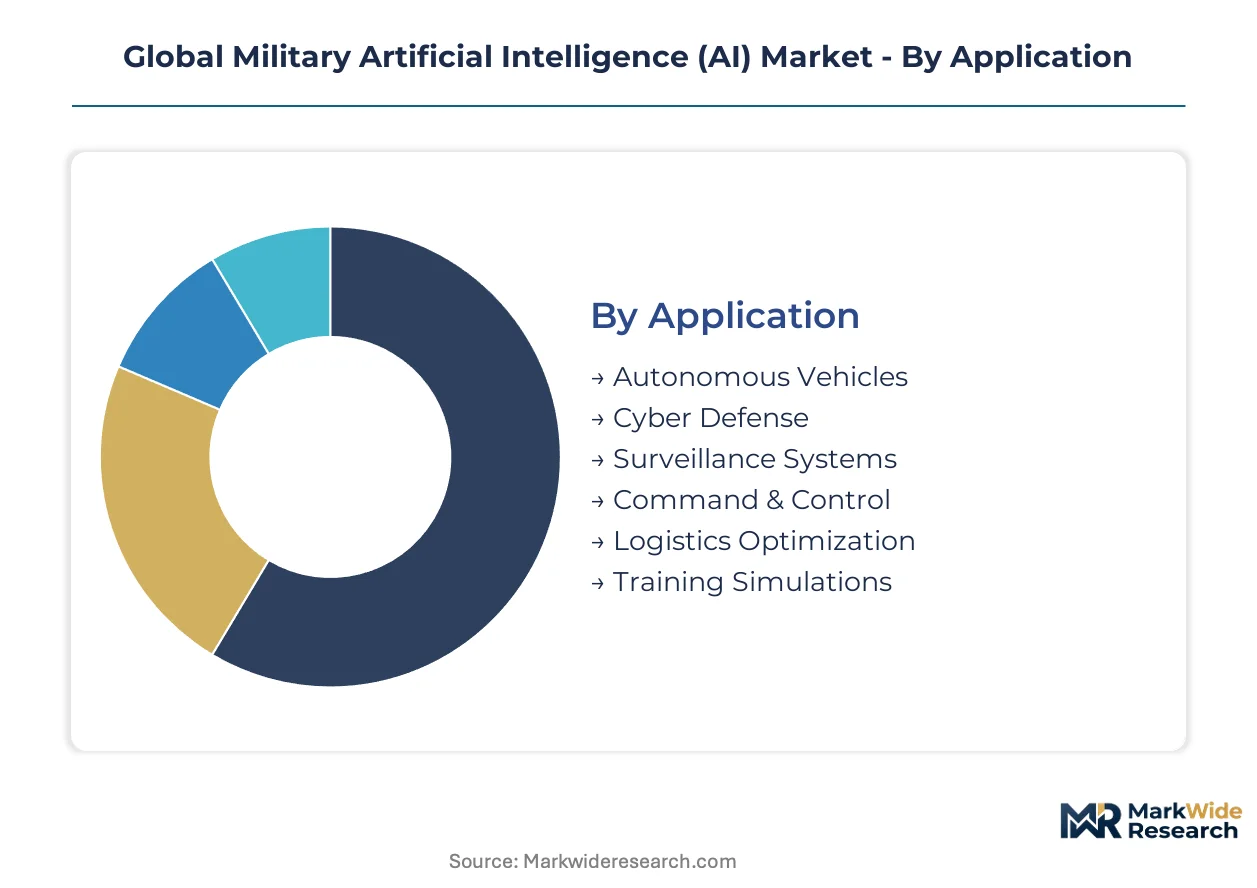
Military AI procurement splits across operational domains, technical architectures, and security clearance levels. Buyers segment investments by battlefield function, algorithmic capability, infrastructure placement, and end-user classification. Understanding these divisions reveals where budget authority concentrates and where vendor specialization creates defensible positions.
Application:
Standalone battlefield systems operate independently on hardened edge processors, while embedded modules integrate into existing platform architectures. This distinction determines certification pathways and procurement timelines.
- Autonomous Vehicles:Algorithmic control systems for drone swarms, ground robots, and maritime platforms operate with sub-100-millisecond inference latency. Procurement concentrates in the United States, the United Kingdom, and Israel as classified defense budgets expand for crewless platform fleets.
- Cyber Defense:Real-time threat detection and automated response systems monitor network traffic for anomaly patterns. Demand clusters around intelligence agencies requiring sovereign cloud deployments with algorithmic audit trails mandated by the EU AI Act.
- Surveillance Systems:Multi-sensor fusion platforms process satellite imagery and signals intelligence.
- Command & Control:Decision-support interfaces compress sensor-to-shooter timelines for battlefield coordination.
- Logistics Optimization:Predictive algorithms manage supply chain routing and inventory positioning.
- Training Simulations:Synthetic environments replicate contested electromagnetic conditions for operator preparation.
Volume placements concentrate in Autonomous Vehicles; the faster expansion belongs to Cyber Defense.
Solution Type:
Cost tier stratification separates enterprise-grade platforms with NATO certification from experimental modules under development contracts. Premium pricing attaches to systems with proven inference under contested conditions.
- Machine Learning Platforms:Predictive maintenance and target recognition frameworks capture substantial procurement value through uptime guarantees. Fighter jet and naval operators unbundle maintenance contracts to reward algorithmic performance, with the U.S. Air Force and Navy driving volume commitments.
- Computer Vision:Satellite imagery analysis commands premium pricing due to classified training data scarcity and sovereign cloud requirements. European fighter jet modernization programs anchor demand as Helsing and comparable specialists restructure workflows for EU AI Act compliance.
- Natural Language Processing:Multilingual intelligence document analysis and automated translation for coalition operations.
- Expert Systems:Rule-based decision support encoding operational doctrine for consistent command judgments.
- Robotic Process Automation:Administrative workflow automation for defense procurement and personnel systems.
- Predictive Analytics:Force deployment modeling and maintenance scheduling based on operational pattern recognition.
Machine Learning Platforms dominate current procurement value; Computer Vision gains share fastest as imagery analysis requirements intensify.
Deployment Mode:
Security classification and connectivity assumptions determine infrastructure placement, with denied-communications environments driving specialized hardware requirements.
- Edge Computing:Hardened processors deploy inference capability directly on platforms for satellite-degraded warfare scenarios. NATO undersea warfare procurement increasingly specifies radiation-hardened neuromorphic chips that reduce wattage per inference for submarine and long-endurance drone programs.
- On-Premises:Sovereign data centers host classified model training and inference for intelligence applications. Scarcity of cleared AI/ML engineering talent constrains development velocity as security clearance timelines lag algorithmic cycles.
- Cloud-Based:Unclassified development environments and coalition interoperability platforms.
- Hybrid Systems:Tiered architectures routing sensitive processing on-premises while leveraging cloud scale for unclassified workloads.
Edge Computing attracts the steepest budget expansion trajectory; On-Premises retains the largest installed base.
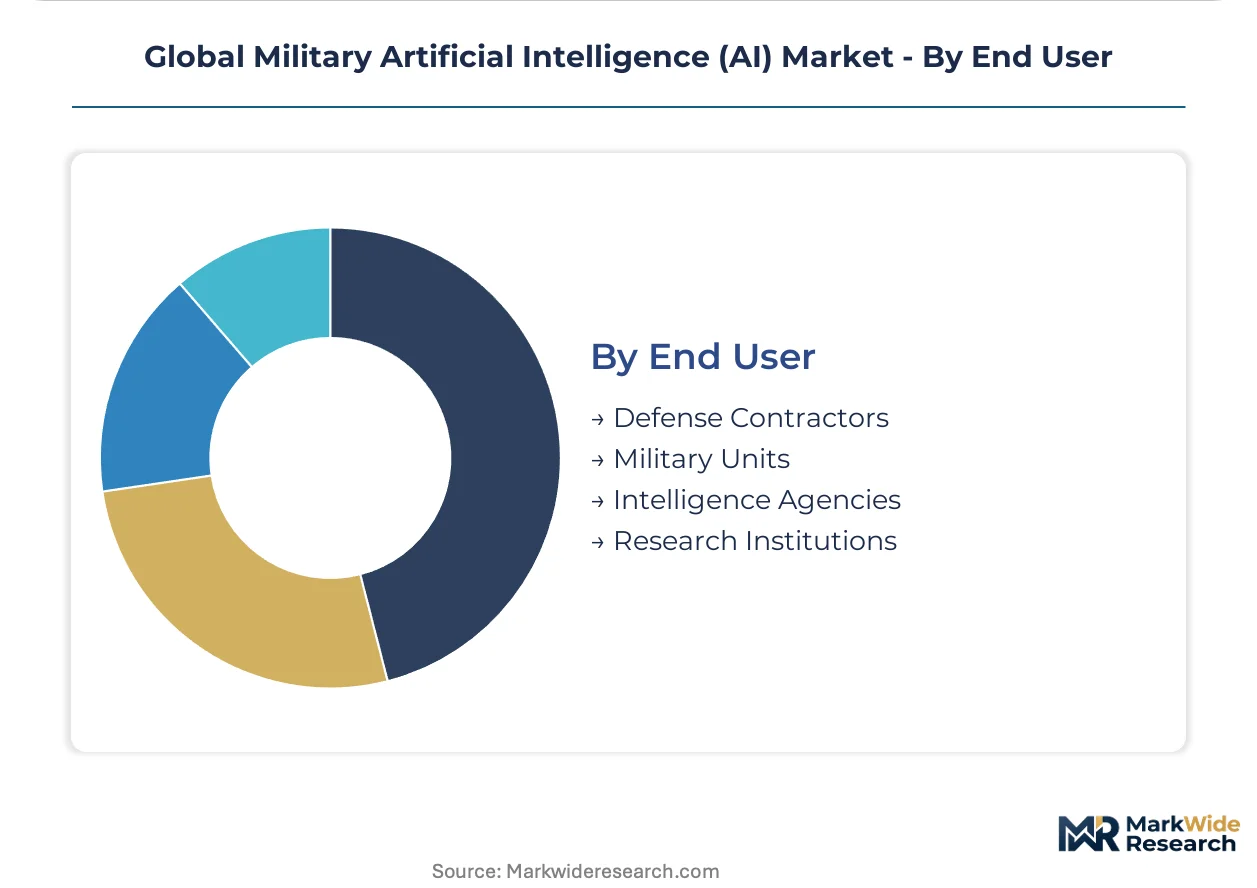
End User:
Procurement authority and security clearance requirements fragment the customer base, with classified program access determining vendor qualification.
- Defense Contractors:System integrators like Lockheed Martin and Anduril Industries embed AI modules into platform deliveries. The U.S. Department of Defense's Responsible AI Strategy accelerates vendor certification requirements across NATO-aligned channels.
- Military Units:Operational commands procure standalone capabilities for immediate deployment. Modular AI payload architectures allow algorithmic module swapping across drone swarms, ground robots, and maritime platforms without vendor lock-in.
- Intelligence Agencies:Specialized requirements for signals analysis and clandestine platform control.
- Research Institutions:Unclassified algorithmic development and dual-use technology exploration.
Defense Contractors channel the highest procurement volume; Military Units are climbing fastest as operational deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized defense technology zones in the United States, United Kingdom, and Israel concentrate military AI development through classified contracting corridors and integrated military-civilian research parks.
United States
The U.S. Department of Defense's Responsible AI Strategy drives vendor certification requirements across Pentagon procurement channels. The National Institute of Standards and Technology (NIST) coordinates AI risk management frameworks that shape algorithmic audit standards. Northern Virginia's defense corridor hosts Palantir and Anduril operations centers where classified model development intersects with intelligence community demand.
United Kingdom
The Ministry of Defence's AI ethics framework mandates algorithmic transparency for operational deployment decisions. The UK Defence Science and Technology Laboratory enforces testing protocols for autonomous systems entering NATO interoperability programs. London and Bristol clusters concentrate Helsing's European fighter jet sensor fusion operations alongside GCHQ-affiliated cybersecurity specialists.
Israel
Integrated military-civilian technology bases accelerate counter-drone and autonomous underwater vehicle validation through direct IDF procurement pathways. The Israel Defense Forces' classified AI defense budgets bypass traditional foreign military sales timelines. Tel Aviv and Haifa corridors host Shield AI partnership facilities where algorithmic warfare modules undergo live-fire testing before NATO export.
Germany
The EU AI Act's high-risk system classification forces Bundeswehr suppliers to document training data provenance for electronic warfare platforms. The Federal Office for Information Security (BSI) audits defense AI systems for coalition interoperability compliance. Munich and Stuttgart industrial zones anchor Helsing's NATO electronic warfare upgrade contracts alongside automotive-to-defense technology transfer operations.
France
Dassault Aviation's Rafale modernization programs pull real-time sensor fusion algorithms into sovereign cloud environments. The National Agency for Food, Environmental and Occupational Health Safety (ANSES) extends its technical assessment capabilities to defense AI risk classification. Paris-Saclay research clusters concentrate Thales and Safran algorithmic development for satellite-degraded warfare scenarios.
Global Military Artificial Intelligence (AI) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels that reward either manufacturing scale or software stack control. Market structure tilts toward tiered concentration where prime contractors embed AI modules into integrated platform deliveries while mid-tier suppliers capture recurring revenue through modular algorithmic interfaces. Two strategic archetypes dominate: vertically integrated system vendors with classified manufacturing access and horizontal software layer specialists with NATO certification credentials. Competitive moves center on M&A activity targeting cleared engineering talent pools and strategic partnerships bridging U.S. prime contractor reach with allied startup agility.
Within the classified system integration tier, Lockheed Martin occupies a position exemplifying manufacturing-scale dominance for U.S. Air Force and Navy programs. Anduril Industries anchors the vertical software stack archetype through proprietary operating system control spanning counter-drone to submarine applications. Helsing represents the European specialist model, with NATO electronic warfare upgrade contracts demonstrating how regional algorithmic expertise penetrates fighter jet modernization procurement. These three configurations illustrate how vendor positioning strategies diverge based on procurement channel access and sovereign technology requirements.
| Leading Market Players |
|---|
| Shield AI |
| V2X |
| Anduril Industries |
| Redwire |
| Vannevar |
| Palantir Technologies |
| Lockheed Martin |
| AeroVironment |
| Helsing |
| Others |
Supply & Pricing Matrix
The U.S. Department of Defense's Responsible AI Strategy gates qualified supply and premium-tier pricing access by mandating vendor certification across NATO-aligned procurement channels. Defense buyers now segment algorithmic modules by security clearance level and proven inference latency under contested conditions, with uncertified suppliers locked out of classified contracts regardless of technical performance.
Pricing Analysis
Cost-down pressure on edge computing deployments accelerates because radiation-hardened semiconductor fabrication concentrates among limited foundries. Pricing stratifies across NATO-certified premium tiers, standard interoperability modules, and experimental development contracts, with certification level and sovereign cloud requirements driving differentiation. Fighter jet and naval platform operators demonstrate highest price sensitivity as they unbundle maintenance contracts to reward algorithmic uptime guarantees, while intelligence agencies accept premium positioning for satellite imagery analysis with classified training data provenance.
Supply Chain Analysis
Dual-sourcing requirements for hardened edge processors mandate multi-supplier qualification across Taiwan, South Korea, and the United States to mitigate single-point vulnerability. Radiation-hardened neuromorphic chips, gallium nitride substrates, and classified training datasets anchor raw material dependencies. Tariff exposure on semiconductor fabrication equipment poses structural risk as export control expansions fragment partnership structures. Distribution runs through defense primes with classified manufacturing access and direct military procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleared AI/ML engineering talent scarcity props pricing across all tiers, constraining model iteration velocity and compressing vendor qualification timelines. This capacity bottleneck limits supply elasticity regardless of procurement volume expansion.
For Market Incumbents: Anticipate modular AI payload architectures compressing proprietary interface value by opening algorithmic standards previously controlled. Lockheed Martin and comparable primes must accelerate backward integration into radiation-hardened semiconductor partnerships to defend manufacturing-scale positioning against software-layer specialists. Certification investment in NATO interoperability credentials represents the critical defensive lever as forthcoming standards reshape vendor eligibility. For New Entrants and Emerging Players: Launch via modular algorithmic interfaces targeting European fighter jet modernization programs where Helsing's sensor fusion specialization demonstrates penetrable white space. Israeli classified AI defense budgets offer testbed access for counter-drone validation before NATO export, with integrated military-civilian technology bases reducing foreign military sales timeline friction. Lattice-style vertical operating systems enable recurring revenue capture across multiple platform categories without sole-source platform development costs. For Investors and Strategic Acquirers: Foundation model weight restriction announcements are the leading indicator that partnership fragmentation between U.S. primes and allied startups will accelerate acquisition demand for cleared engineering talent pools. Long-term viability across the analysis window hinges on positioning within NATO certification hierarchies rather than technical differentiation alone. Acquisition targets should demonstrate existing interoperability credentials with defense procurement officers unbundling hardware and software layer competitions.| Strategic Initiative | Industry Significance |
|---|---|
| NATO AI Certification Investment | EU AI Act enforcement structures mandate algorithmic audit trails that determine market access for defense suppliers. |
| Neuromorphic Chip Partnership | Submarine and long-endurance drone programs specify spiking neural network architectures that compress supplier qualification lists. |
| Modular Payload Architecture Development | U.S. Air Force Collaborative Combat Aircraft program rewards software stack openness over integrated platform dominance. |
| Cleared Engineering Talent Acquisition | Security clearance timelines lag algorithmic development cycles, forcing segmentation between classified and unclassified tracks. |
| Sovereign Cloud Infrastructure Deployment | Intelligence agencies require classified model training environments that constrain development velocity to cleared personnel pools. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with defense procurement officers, AI/ML engineering leads at cleared contractors, platform integration specialists, and NATO interoperability certification auditors. Pentagon budget justifications, EU AI Act implementation guidance, SEC 10-K disclosures from listed primes, and satellite imagery procurement databases supplied validation benchmarks. Bottom-up segment sizing triangulated against top-down defense expenditure allocations across the analysis window.
Granularity-level modeling deployed separate projections for autonomous vehicle control systems, cyber defense platforms, and surveillance applications by solution type, deployment mode, and end-user classification. Machine learning platforms, computer vision modules, and edge computing hardware were tracked through distinct capability maturity curves. CAGRs derived from procurement volume commitments in classified budget documents and demonstrated inference latency specifications rather than laboratory benchmarks. Fighter jet modernization program timelines and naval platform maintenance contract unbundling patterns supplied industry-specific forecast inputs.
Export control expansion announcements, foundation model weight restriction implementations, and radiation-hardened foundry capacity constraints are the dominant revision risks to procurement volume assumptions. Forecasts reflect documented assumptions regarding NATO certification standard finalization timelines and cleared personnel pool expansion rates. Deviation in hardened semiconductor fabrication capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market