
 Electrical Weapon Market | 2026-2036
Electrical Weapon Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Weapon Market Analysis
REACH compliance is consolidating the cost-of-entry calculus for European electrical weapon manufacturers by restricting certain battery chemistries and electronic components. Axon Enterprise Inc. dominates the conducted electrical weapon segment through its integrated body camera and cloud evidence platform. BAE Systems Plc leverages its defense electronics heritage to sustain high-voltage pulse generation systems for military applications. Lockheed Martin Corp. anchors the directed-energy weapons pipeline with non-kinetic electromagnetic platforms.
An electrical weapon delivers incapacitating electrical charge through direct contact or projectile deployment, typically operating at 50,000 volts with microcoulomb charge delivery to disrupt neuromuscular function without lethal force. Capacitor discharge technology leads the product mix due to its reliability in rapid-fire scenarios, while hybrid systems integrating battery and piezoelectric elements represent the fastest-growing technology segment as manufacturers seek reduced weight and extended duty cycles. Law enforcement applications command the largest revenue pool, though military procurement of electromagnetic pulse weapons is expanding the highest-margin segment.
The EU AI Act and MDR frameworks govern automated targeting systems and device safety certifications across European jurisdictions, while the FDA oversees medical claims related to cardiac risk profiles in the United States. BIS standards in India and NMPA requirements in China create divergent compliance pathways that fragment market access for standardized product platforms. Stakeholders must monitor evolving less-lethal force doctrines in major defense ministries and track capacitor supply chain concentration in East Asian manufacturing clusters.
Market Dynamics
The Electrical Weapon Market pivots on capacitor supply chain concentration in East Asian manufacturing clusters, where single-source dependencies for high-voltage pulse components create procurement bottlenecks that ripple through tiered supplier networks.
Growth Catalysts
- EU Green Deal battery mandates:REACH compliance requirements are forcing chemistry transitions toward solid-state architectures that reduce thermal runaway risks in conducted electrical weapons.
- Municipal police procurement:Law enforcement agencies across the United States sustain replacement cycles for legacy taser deployments while expanding less-lethal force arsenals.
- Piezoelectric hybrid architectures:Battery-piezoelectric integration is extending duty cycles while reducing device weight below traditional capacitor-only systems.
Market Restraints
- East Asian capacitor concentration:High-voltage pulse component manufacturing clusters in Taiwan and South Korea create single-point-of-failure exposure for Western assemblers.
- REACH substance restrictions:ECHA limitations on nickel-cadmium and certain electrolyte formulations force reformulation costs that compress margins for European manufacturers.
- Cardiac risk liability exposure:FDA oversight of medical claims related to arrhythmia induction creates litigation reserves that inflate insurance premiums across the installed base.
Strategic Opportunities
- Indian defense modernization:BIS certification pathways for conducted electrical weapons remain underpenetrated relative to projected paramilitary procurement budgets.
- Cloud evidence integration:Convergence between electrical weapon discharge logs and body-worn camera metadata creates subscription revenue streams beyond hardware sales.
- Directed-energy military pivot:Electromagnetic pulse platforms for vehicle and drone disablement represent uncontracted white space in defense ministry less-lethal doctrine development.
Industry Challenges
- High-voltage engineering talent scarcity:Specialized capacitor discharge design expertise concentrates among legacy defense electronics engineers nearing retirement.
- Multi-jurisdiction certification timelines:Sequential FDA, CE marking, and BIS approval processes extend product launch windows by eighteen to thirty months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Weapon Market |
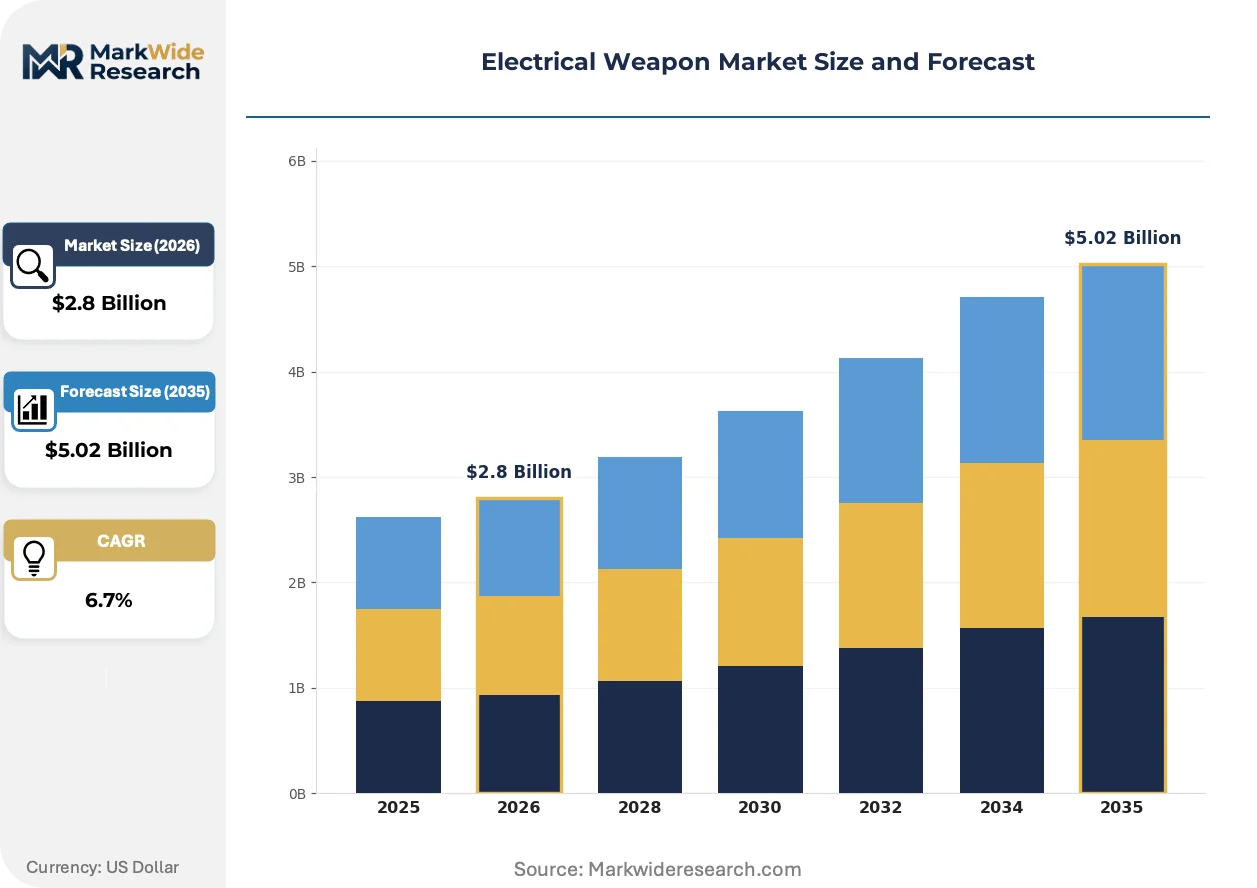
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tasers, Stun Guns, Baton Electroshockers, Electric Shields, Shock Collars Technology: Battery Powered, Capacitor Discharge, Magnetic Pulse, Piezoelectric, Hybrid Systems Application: Law Enforcement, Personal Defense, Security Services, Military, Wildlife Control End User: Police Forces, Private Security Firms, Military Units, Civilian Consumers, Animal Control Agencies |
| Companies Covered | BAE Systems Plc, Combined Systems Inc., Axon Enterprise Inc., Naval Group, Honeywell International Inc., Lockheed Martin Corp., Textron Inc., Mitsubishi Heavy Ltd., RTX Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Weapon Market Emerging Trajectories
Electrical weapon architectures are fragmenting across three vectors: power source miniaturization, automated targeting integration, and evidence-chain digitization. Each vector carries distinct competitive implications for hardware margins and recurring revenue capture.
Solid-state battery chemistry is decentralizing power architecture decisions away from traditional lithium-ion suppliers. Law enforcement procurement officers in Germany and France now specify solid-state configurations for reduced thermal signature during extended duty cycles. This chemistry shift is decentralizing supply relationships toward specialized solid-state foundries and away from incumbent cylindrical cell manufacturers.
EU AI Act automated targeting provisions are restructuring firmware development roadmaps for conducted electrical weapons with integrated aim-assist systems. Manufacturers must now segregate European and non-European software loads to comply with prohibited AI practices for kinetic effectors. Military procurement in Belgium and the Netherlands faces the steepest compliance recertification burdens under these MDR-adjacent requirements.
Agency-level evidence management contracts are unbundling hardware from data services. State police departments in Texas and Florida now negotiate five-year cloud storage agreements separate from device replacement schedules. This unbundling is most visible in jurisdictions with existing body-worn camera infrastructure where electrical weapon discharge logs must integrate into unified evidence platforms.
Electrical Weapon Market Segmentation
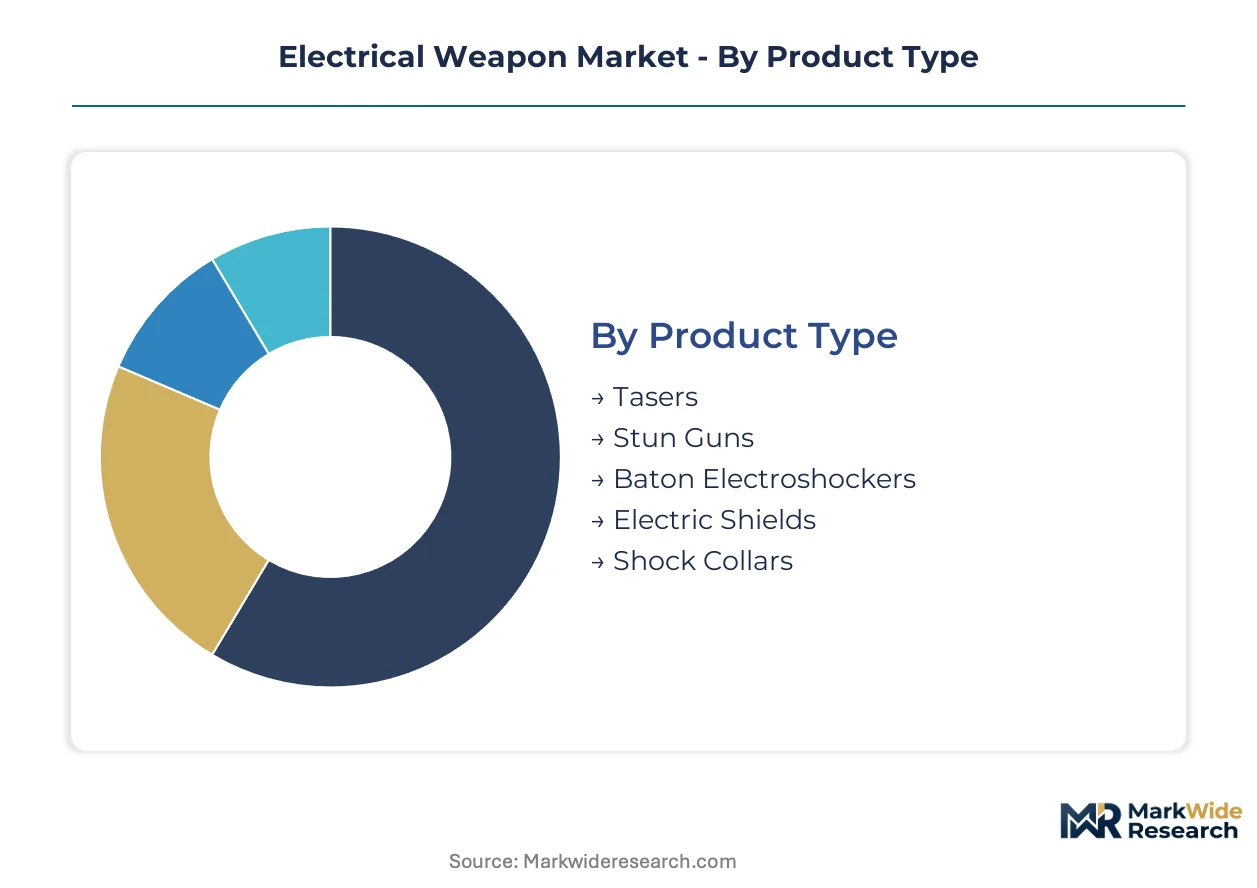
Electrical weapon procurement patterns diverge sharply across deployment contexts, with voltage specifications and duty cycle requirements dictating component sourcing strategies. Manufacturers must align capacitor supply relationships and battery chemistry roadmaps to the operational tempo of each segment.
Product Type:
Supply concentration for high-voltage pulse components concentrates procurement leverage around taser and stun gun assemblers who command volume commitments from Taiwanese and South Korean capacitor foundries.
- Tasers:Projectile-deployed conducted electrical weapons operating at 50,000 volts with wire-tethered darts. United States municipal police departments sustain replacement cycles for legacy deployments while federal agencies expand less-lethal arsenals under updated use-of-force protocols.
- Stun Guns:Direct-contact devices delivering incapacitating charge through surface electrodes. Demand concentrates in private security services across Germany and France where concealed-carry regulations favor compact form factors over projectile range.
- Baton Electroshockers:Extended-reach contact weapons integrating striking surface with electrical discharge capability.
- Electric Shields:Riot control equipment with perimeter electrification for crowd management applications.
- Shock Collars:Animal training and wildlife deterrence devices with adjustable stimulus thresholds.
Today's leader: Tasers. Tomorrow's challenger: Stun Guns.
Technology:
Cost tier stratification separates premium capacitor-discharge platforms from emerging solid-state architectures that promise reduced thermal signatures during extended duty cycles.
- Capacitor Discharge:Rapid energy release systems dominating law enforcement procurement for reliability in rapid-fire scenarios. Taiwan-based manufacturing clusters create single-source dependencies that ripple through tiered supplier networks serving Western assemblers.
- Hybrid Systems:Battery-piezoelectric integration extending duty cycles while reducing device weight below traditional capacitor-only configurations. Military procurement offices in Belgium and the Netherlands are evaluating hybrid architectures for electromagnetic pulse applications against unmanned aerial systems.
- Battery Powered:Conventional lithium-ion architectures facing chemistry transitions under REACH substance restrictions.
- Magnetic Pulse:Non-contact electromagnetic incapacitation platforms for vehicle and drone disablement.
- Piezoelectric:Mechanical stress-to-electric conversion for reduced battery dependence in field conditions.
Capacitor discharge commands current procurement volumes. Hybrid systems are climbing the fastest as manufacturers pursue weight reduction targets.
Application:
Margin structure varies dramatically across application contexts, with military electromagnetic pulse platforms capturing premium pricing while wildlife control operates on commoditized hardware economics.
- Law Enforcement:Conducted electrical weapons for municipal and federal agency less-lethal force protocols. Procurement in Texas and Florida now unbundles hardware from five-year cloud evidence storage agreements.
- Military:Electromagnetic pulse and directed-energy platforms for vehicle and drone disablement. Defense ministries in India and the Netherlands face divergent certification timelines for non-kinetic effector deployment.
- Personal Defense:Compact stun devices for civilian carry where jurisdictional regulations fragment market access.
- Security Services:Private sector deployment across corporate and critical infrastructure protection.
- Wildlife Control:Animal deterrence and herding applications with standardized voltage thresholds.
Law Enforcement anchors revenue concentration. Military applications hold the steepest expansion trajectory as less-lethal doctrine evolves.
End User:
Customer type dictates firmware certification burdens, with police forces triggering EU AI Act automated targeting compliance while civilian consumers face simplified safety approvals.
- Police Forces:Municipal, state, and federal agencies with integrated body-worn camera and evidence platform requirements. German and French procurement officers now specify solid-state battery configurations for reduced thermal signatures.
- Military Units:Defense ministry procurement with electromagnetic pulse specifications for counter-UAS applications. BIS certification pathways in India remain underpenetrated relative to projected paramilitary budgets.
- Private Security Firms:Commercial sector deployment with tiered pricing across premium certified and economy unmarked equipment.
- Civilian Consumers:Personal defense acquisition subject to carry permit fragmentation across state and national jurisdictions.
- Animal Control Agencies:Government wildlife management with standardized stimulus protocols for non-lethal deterrence.
Police Forces dominate installed base economics. Military Units are gaining share fastest as directed-energy procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized high-voltage engineering talent concentrates in defense electronics corridors across the United States, Germany, and South Korea, anchoring regional manufacturing capabilities for pulse generation systems.
United States
Municipal police departments in Texas and Florida sustain replacement cycles for legacy conducted electrical weapon deployments while expanding less-lethal arsenals under updated federal use-of-force protocols. FDA oversight of medical claims related to cardiac risk profiles creates litigation reserves that inflate insurance premiums across the installed base. Manufacturing clusters in Arizona and Massachusetts anchor capacitor assembly operations serving Western defense contractors.
Germany
Procurement officers in Berlin and Munich now specify solid-state battery configurations for reduced thermal signatures during extended law enforcement duty cycles. REACH substance restrictions on nickel-cadmium and certain electrolyte formulations force reformulation costs that compress margins for domestic manufacturers. The Eindhoven-Twente corridor across the Dutch border supplies specialized solid-state foundries that German assemblers increasingly favor over incumbent cylindrical cell suppliers.
India
Paramilitary procurement budgets project expansion of conducted electrical weapon arsenals for riot control and border security applications. BIS certification pathways remain underpenetrated relative to projected demand, creating first-mover advantages for early entrants. Industrial clusters in Pune and Hyderabad host emerging defense electronics assembly operations targeting domestic substitution for high-voltage pulse components.
Netherlands
Defense ministries in The Hague face steep compliance recertification burdens under EU AI Act automated targeting provisions for conducted electrical weapons with integrated aim-assist systems. Military procurement offices evaluate hybrid battery-piezoelectric architectures for electromagnetic pulse applications against unmanned aerial systems. The Brainport Eindhoven region anchors firmware development capabilities for segregated European software loads.
South Korea
Capacitor manufacturing clusters in Suwon and Gwangju create single-source dependencies for high-voltage pulse components that ripple through tiered supplier networks serving Western assemblers. MFDS-equivalent safety frameworks govern medical device classifications for conducted electrical weapons with cardiac monitoring claims. The Seoul Capital Area concentrates backward integration capabilities from semiconductor fabrication into specialized pulse generation electronics.
Electrical Weapon Market Vendor Landscape
The competitive structure tilts toward integrated defense electronics conglomerates with captive high-voltage engineering capabilities. Tier-one assemblers command procurement leverage through volume commitments from East Asian capacitor foundries, while mid-tier specialists compete on rapid customization for agency-specific firmware requirements. Three archetypes dominate: vertically integrated defense primes with directed-energy pipelines, law enforcement-focused platform integrators with cloud evidence ecosystems, and component specialists supplying pulse generation subsystems. Competitive moves concentrate on strategic partnerships for solid-state battery chemistry access and geographic expansion into underpenetrated certification jurisdictions.
Among defense electronics conglomerates, BAE Systems Plc and Lockheed Martin Corp. exemplify the prime-contractor archetype with established high-voltage pulse generation heritage. Axon Enterprise Inc. occupies a distinct position as a platform integrator combining conducted electrical weapon hardware with evidence management software subscriptions. These three anchors illustrate the bifurcation between kinetic less-lethal systems and emerging directed-energy portfolios.
| Leading Market Players |
|---|
| BAE Systems Plc |
| Combined Systems Inc. |
| Axon Enterprise Inc. |
| Naval Group |
| Honeywell International Inc. |
| Lockheed Martin Corp. |
| Textron Inc. |
| Mitsubishi Heavy Ltd. |
| RTX Corp. |
| Others |
Supply Flow & Price Mechanics
Captive integration into solid-state battery foundries anchors pricing power for European electrical weapon assemblers seeking REACH-compliant chemistry transitions. This backward integration choice simultaneously secures supply position against East Asian capacitor concentration and enables premium positioning for reduced thermal signature configurations demanded by German and French procurement officers.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from five-year cloud evidence subscriptions that Texas and Florida state police departments now negotiate independently. Three-tier pricing structure across premium certified, standard compliant, and economy unmarked equipment reflects divergence in firmware certification burdens and after-sales service commitments. Cost compression in economy tiers intensifies because REACH reformulation expenses concentrate among European manufacturers lacking captive battery chemistry access. Private security firms exhibit greatest price sensitivity due to unregulated procurement discretion, while military electromagnetic pulse platforms command least sensitivity given counter-UAS mission criticality.
Supply Chain Analysis
Dual-sourcing requirements from United States defense contractors mandate multi-supplier qualification for high-voltage pulse components despite manufacturing concentration in Taiwan, South Korea, and Japan. Raw material dependencies center on tantalum capacitors, solid-state electrolyte formulations, and piezoelectric ceramics that draw from specialized foundries with limited alternative supply. Single-source vulnerability in Taiwanese capacitor clusters creates procurement bottlenecks that ripple through tiered supplier networks serving Western assemblers. Distribution runs through defense electronics primes with established agency relationships rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by procurement officers in Berlin and Munich specifying solid-state battery configurations that disqualify legacy cylindrical cell suppliers.
For Market Incumbents: To counter emerging hybrid architecture specialists from Belgian and Dutch defense electronics corridors, Axon Enterprise Inc. and BAE Systems Plc should deepen captive supply of solid-state foundry capacity while accelerating FDA cardiac risk certification investments that extend litigation reserve advantages over unproven entrants. Channel control through existing body-worn camera infrastructure integration remains the priority defensive lever. For New Entrants and Emerging Players: Defense ministry procurement offices in India present the most penetrable geography given underpenetrated BIS certification pathways relative to projected paramilitary budgets. Cloud evidence platform partnerships with existing body-camera vendors offer the cleanest go-to-market angle for hardware specialists lacking agency relationships. Electromagnetic pulse applications against unmanned aerial systems represent the fastest-climbing white-space segment as less-lethal doctrine evolves. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier firmware specialists because EU AI Act automated targeting provisions force segregation of European and non-European software loads that fragment development teams. Five-to-ten year viability hinges on directed-energy pipeline maturation beyond conducted electrical weapon replacement cycles. Watch for electromagnetic pulse contract awards from Belgian and Netherlands defense ministries as the signal indicating inflection toward premium military applications.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | REACH compliance in Germany and France mandates chemistry transitions that favor early integrators. |
| Cloud Evidence Platform Expansion | Texas and Florida police departments unbundle hardware from five-year data storage agreements. |
| EU AI Act Firmware Segregation | Belgian and Dutch military procurement faces steepest recertification burdens for aim-assist systems. |
| Indian BIS Certification Entry | Paramilitary budgets project expansion for riot control and border security applications. |
| Electromagnetic Pulse Development | Counter-UAS specifications from Netherlands defense ministry signal premium segment acceleration. |
Methodological Framework
Direct dialogue with high-voltage engineering directors, law enforcement procurement officers, defense ministry acquisition leads, and solid-state battery foundry executives grounded qualitative insights that secondary validation subsequently stress-tested. Customs records for capacitor imports, FDA medical device filings, ECHA REACH substance restriction updates, and BIS certification databases supplied quantitative anchors. Bottom-up segment sizing triangulated against top-down defense electronics market allocations to constrain estimate variance.
Segment-level projections across product type, technology architecture, application context, and end-user category fed into analytical framework outputs spanning the projection horizon. CAGRs emerged from fitted growth curves calibrated to procurement cycle data and regulatory implementation timelines. Capacitor supply chain concentration indices and solid-state chemistry transition schedules served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansions, EU AI Act enforcement interpretations, and East Asian capacitor cluster disruption scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Large Caliber Ammunition Market