
 North America Tactical UAV Market | 2026-2036
North America Tactical UAV Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tactical UAV Market Analytics
The US DoD's mandate for reduced-carbon expeditionary forces is hardening requirements for fuel-efficient propulsion in tactical UAV programs. AeroVironment Inc. leverages its dominance in hand-launched fixed-wing systems for infantry units. General Atomics Aeronautical Systems anchors the medium-altitude segment with its Gray Eagle product line. Lockheed Martin Corporation differentiates through stealth-optimized airframes designed for contested airspace penetration.
Tactical UAVs are unmanned aircraft systems weighing under 1,320 pounds with operational ranges between 50 and 300 nautical miles, designed for ISR missions requiring rapid deployment from austere locations without prepared runways. Fixed-wing configurations lead procurement volumes due to endurance advantages for wide-area surveillance, while rotary-wing systems capture growing share in urban canyon and shipboard operations where vertical launch and recovery prove essential. The reconnaissance application segment commands the largest current budget allocation, though payload delivery functions are gaining traction as autonomous logistics networks mature.
The FAA regulates commercial and civil airspace integration through Part 107 and emerging type certification standards, while the US DoD maintains separate airworthiness criteria through MIL-STD-882 and service-specific risk acceptance frameworks. NHTSA coordination on ground-based sense-and-avoid systems increasingly shapes dual-use platform development. Stakeholders must monitor how forthcoming FAA remote ID enforcement and spectrum allocation decisions for command-and-control links will reshape competitive access to domestic test corridors and operational deployments.
Market Dynamics
The US Department of Defense's expeditionary force restructuring is compressing procurement cycles for portable ISR platforms while FAA certification pathways for beyond-visual-line-of-sight operations simultaneously unlock commercial airspace access.
Growth Catalysts
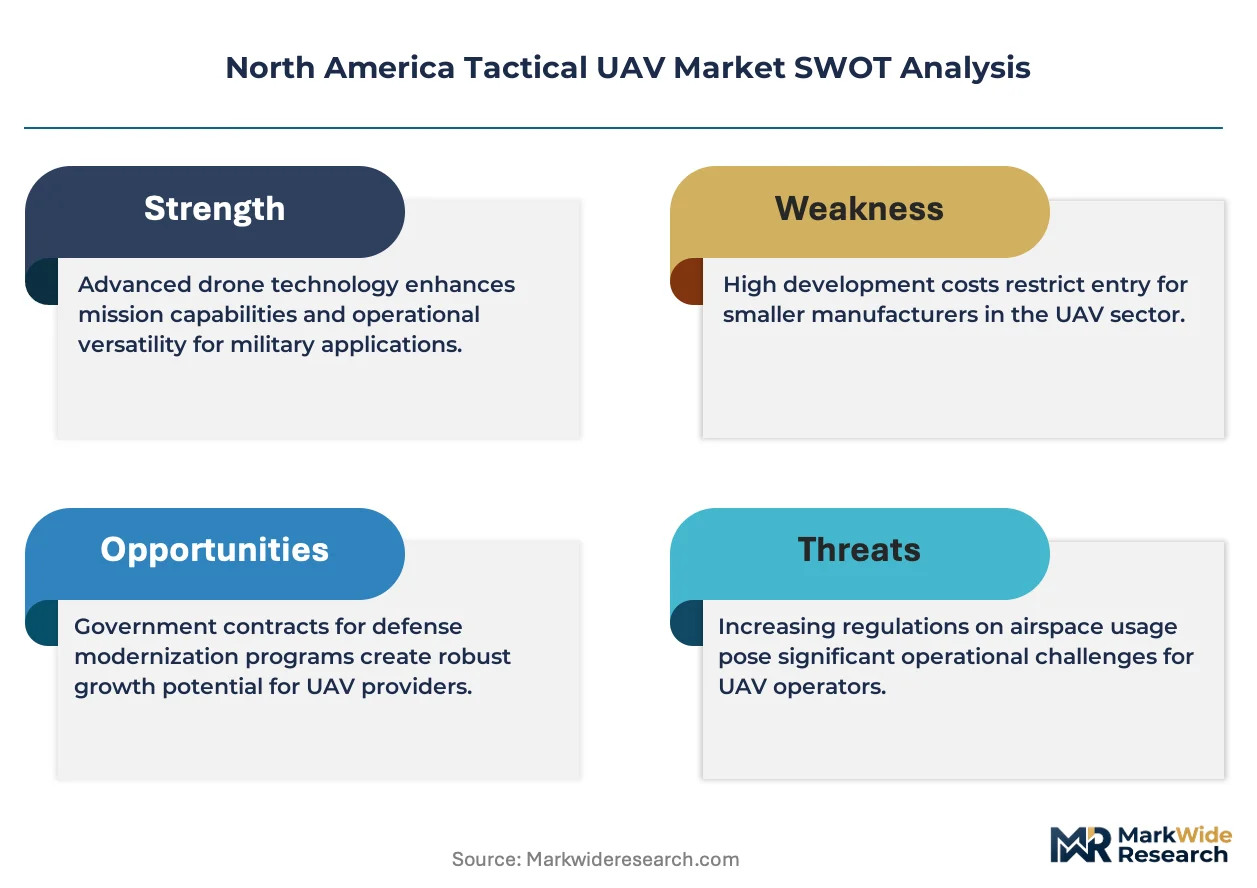
- FAA Part 107 Expansion:The FAA's emerging type certification standards for small unmanned aircraft are creating regulatory clarity that accelerates defense contractor investment in dual-use platform development.
- Southwestern Test Corridor Concentration:Military training ranges across Arizona, New Mexico, and California generate sustained demand for tactical systems validation and operator certification programs.
- Reduced-Carbon Mandates:The DoD's expeditionary energy requirements are hardening specifications for fuel-efficient propulsion architectures in next-generation tactical UAV programs.
Market Restraints
- Domestic Supply Concentration:Critical subsystems including miniature turbojet engines and stabilized electro-optical turrets source predominantly from single-qualified domestic suppliers, creating vulnerability to production bottlenecks.
- Spectrum Allocation Friction:FCC and NTIA coordination delays on protected C-band and L-band allocations for command-and-control links constrain operational range extensions in congested electromagnetic environments.
- Ground-Based Sense-and-Avoid Costs:NHTSA-coordinated radar and optical detect-and-avoid systems impose capital requirements that disproportionately burden small platform developers seeking civil airspace certification.
Strategic Opportunities
- Canadian Arctic Operations:The Royal Canadian Armed Forces' northern surveillance gaps present demand for cold-weather-hardened tactical systems with satellite backhaul integration for maritime domain awareness.
- Autonomous Logistics Networks:Payload delivery applications for tactical UAVs are gaining traction as the US Marine Corps experiments with ship-to-shore resupply using rotary-wing platforms.
- AI-Enabled Target Recognition:Convergence of onboard edge computing with synthetic aperture radar processing is opening mission profiles previously requiring manned airborne early warning platforms.
Industry Challenges
- Airworthiness Certification Timeline:MIL-STD-882 compliance pathways for software-intensive autonomous systems extend development schedules by 18-24 months compared to prior hardware-centric platforms.
- Cross-Domain Integration Complexity:Tactical UAVs must interface with Army Futures Command's Project Convergence battle networks, requiring interoperability with legacy Link 16 and emerging MANET waveforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tactical UAV Market |
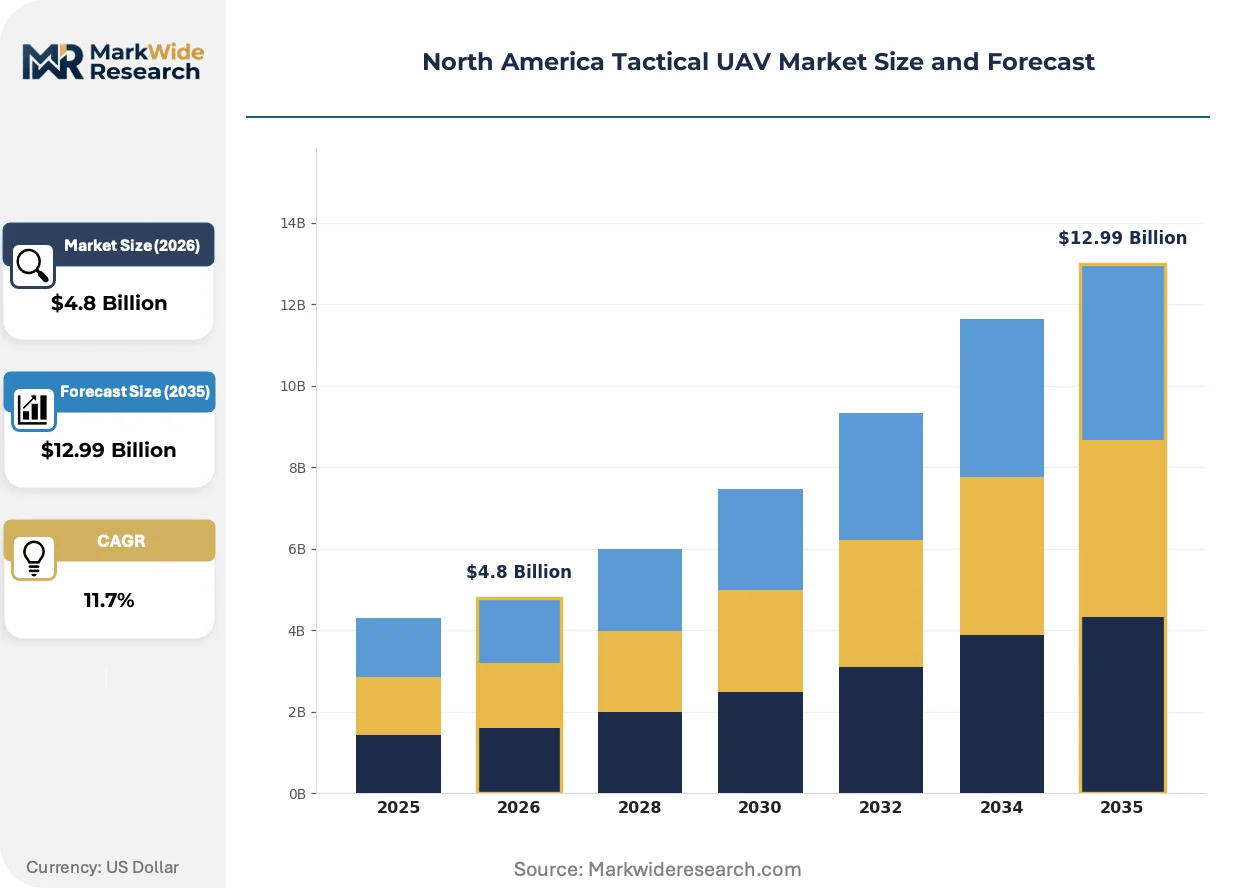
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano End User: Military, Government, Law Enforcement, Commercial Technology: Autonomous, Remote-Controlled, AI-Enabled, Surveillance Application: Reconnaissance, Observation, Target Acquisition, Payload Delivery |
| Companies Covered | Northrop Grumman Corporation, AeroVironment Inc., Lockheed Martin Corporation, General Atomics Aeronautical Systems, Textron Inc., The Boeing Company, Elbit Systems Ltd., IAI, Insitu, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tactical UAV Market Evolving Landscape
Propulsion architectures and autonomy stacks are undergoing rapid recombination as defense primes respond to expeditionary requirements for reduced logistics footprints and compressed deployment timelines.
Hybrid-electric propulsion is modularizing tactical UAV powertrain design. The US Army's Future Tactical Unmanned Aircraft System program is evaluating series-hybrid configurations that combine piston generators with distributed electric motors. This architecture is modularizing subsystem sourcing by decoupling engine selection from airframe integration, enabling primes to swap powerplant vendors without airframe recertification.
FAA remote identification enforcement is reshaping competitive access to domestic operational corridors. The September 2023 compliance deadline for broadcast modules is forcing platform developers to redesign avionics bays and antenna placements. Small tactical system manufacturers serving both defense and civil markets are most affected, with several pursuing dual-certification strategies that satisfy both Part 107 and military airworthiness criteria.
Defense procurement patterns are compressing vendor qualification cycles. The US Special Operations Command's rapid fielding authorities are bypassing traditional Milestone C reviews for urgent operational needs, displacing incumbent suppliers who optimized for extended source-selection timelines. This behavioral shift is most visible in the hand-launched fixed-wing segment, where AeroVironment's historical dominance faces challenge from newer entrants offering open-architecture ground control stations.
North America Tactical UAV Market Segmentation
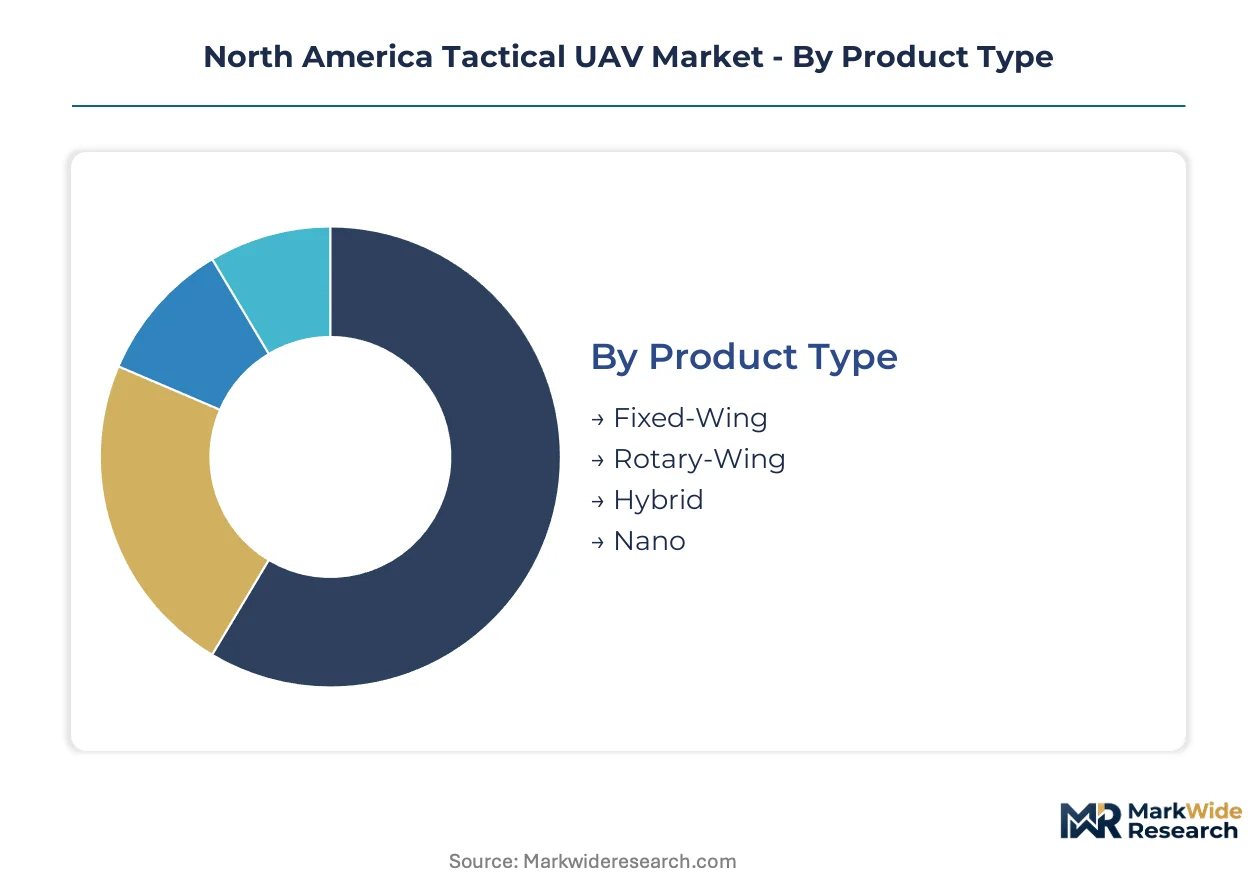
Segmentation of the North America Tactical UAV Market reveals how procurement patterns concentrate around endurance requirements and operational environments. Platform configurations and mission profiles determine supplier positioning across defense and adjacent civil markets.
Product Type:
Fixed-wing platforms dominate production volumes across Arizona and New Mexico test corridors, where endurance specifications drive airframe design priorities.
- Fixed-Wing:Hand-launched and catapult-deployed configurations achieve flight durations exceeding 16 hours with minimal logistics footprint. US Army infantry brigades concentrate procurement in the southwestern United States, where high-altitude training validates wide-area surveillance missions.
- Rotary-Wing:Vertical takeoff and recovery capabilities enable operations from ship decks and urban canyons without prepared runways. US Marine Corps ship-to-shore resupply experiments in California coastal ranges are accelerating demand for maritime-hardened variants.
- Hybrid:Tilt-rotor and compound helicopter configurations combine endurance with vertical launch flexibility. FAA Part 107 certification complexity limits civil market penetration.
- Nano:Sub-250 gram platforms for individual soldier carriage face payload and range constraints in contested electromagnetic environments.
Fixed-wing systems absorb the bulk of installed capacity; rotary-wing platforms are expanding most quickly.
End User:
Customer concentration follows procurement authority structures, with defense acquisition channels commanding qualification resources unavailable to civil operators.
- Military:US Department of Defense programs specify MIL-STD-882 airworthiness criteria and Project Convergence network interoperability. Reduced-carbon expeditionary mandates from Army Futures Command are hardening fuel-efficiency requirements for next-generation platforms.
- Government:Federal agencies including CBP and USFS operate under FAA Certificates of Authorization with beyond-visual-line-of-sight waivers. Border surveillance missions across Texas and Arizona generate sustained demand for medium-endurance systems.
- Law Enforcement:SWAT and search-and-rescue units face budget constraints and civil liberties scrutiny that compress deployment timelines.
- Commercial:Infrastructure inspection and precision agriculture operators navigate FAA Part 107 remote ID compliance costs that disadvantage small fleet operators.
Military end users command the largest procurement volumes; commercial adoption faces the steepest regulatory barriers.
Technology:
Autonomy architecture choices determine software certification pathways and supplier qualification timelines.
- Autonomous:Pre-programmed waypoint navigation with minimal operator intervention reduces cognitive load in contested communications environments. US Special Operations Command rapid fielding authorities favor systems with degraded-mode return-to-base capabilities.
- Remote-Controlled:Direct human-in-the-loop control persists for terminal guidance and sensitive target engagement decisions. Spectrum allocation friction between FCC and NTIA constrains command-and-control link range extensions.
- AI-Enabled:Onboard edge computing for target recognition and route optimization extends mission profiles previously requiring manned platforms. MIL-STD-882 software compliance extends development schedules substantially.
- Surveillance:Dedicated sensor platforms with stabilized electro-optical and synthetic aperture radar payloads integrate with Army battle management networks.
Autonomous systems carry the largest installed base; AI-enabled platforms are gaining share fastest.
Application:
Mission profile segmentation aligns with payload integration requirements and operator training specialization.
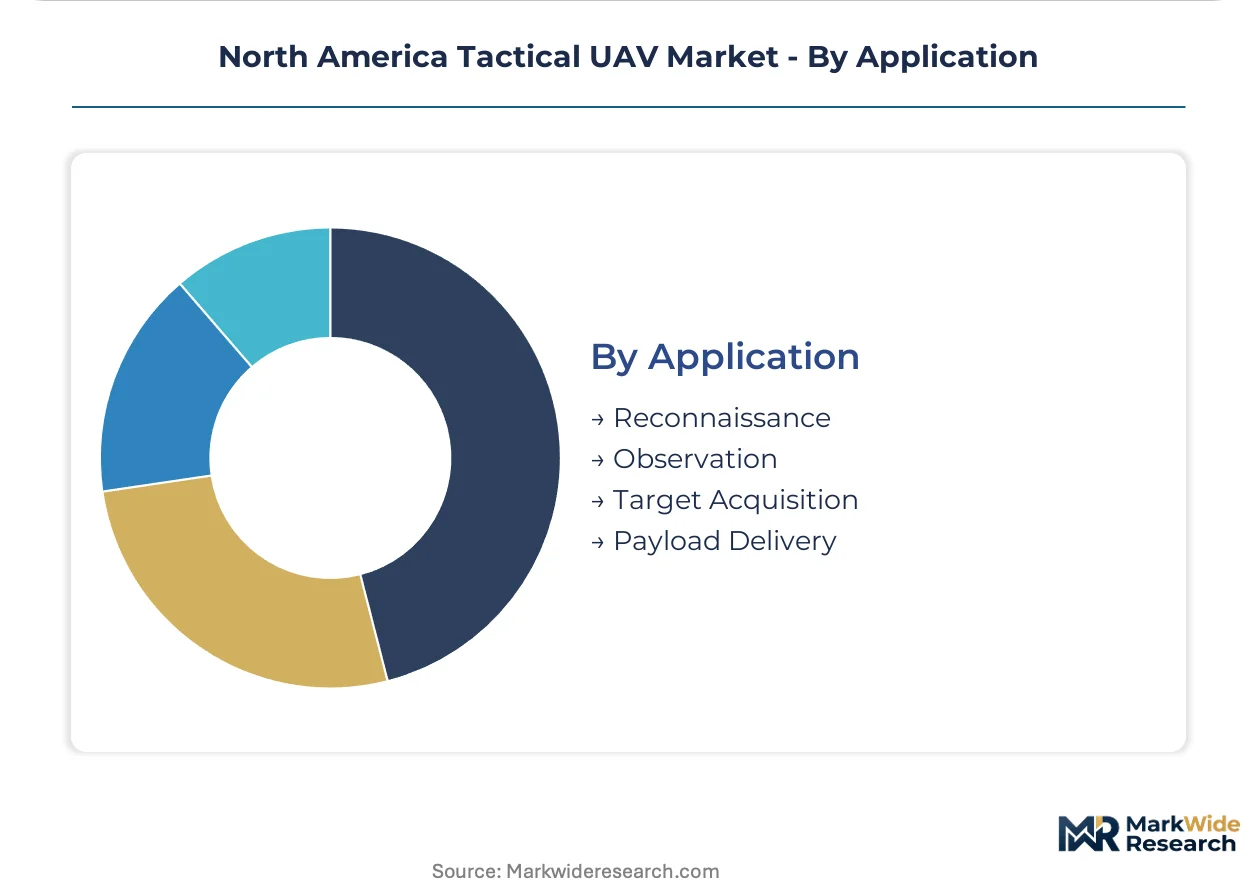
- Reconnaissance:Wide-area surveillance with signals intelligence and imagery collection dominates current budget allocation. Fixed-wing platforms operating from austere locations across the southwestern United States validate this segment's endurance advantages.
- Observation:Persistent stare and pattern-of-life analysis for force protection and perimeter security. Law enforcement and base defense operators concentrate demand in urban corridor environments.
- Target Acquisition:Laser designation and coordinate generation for precision strike coordination. Network interoperability with Link 16 and MANET waveforms determines competitive positioning.
- Payload Delivery:Ship-to-shore logistics and medical resupply missions are gaining traction as rotary-wing autonomy matures. US Marine Corps experimentation in California training areas validates operational concepts.
Reconnaissance applications absorb dominant budget share; payload delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southwestern United States concentrates tactical UAV development and testing activity, with military ranges across Arizona, New Mexico, and California generating sustained procurement demand for portable ISR platforms.
United States
The US Department of Defense commands the largest procurement volumes through Army Futures Command and US Special Operations Command rapid fielding authorities. FAA Part 107 and emerging type certification standards regulate civil airspace integration, while MIL-STD-882 governs military airworthiness. Arizona's Yuma Proving Ground and New Mexico's White Sands Missile Range validate endurance specifications for fixed-wing systems operating in high-altitude conditions.
Canada
The Royal Canadian Armed Forces' northern surveillance gaps generate demand for cold-weather-hardened tactical platforms with satellite backhaul integration. Health Canada and Transport Canada coordinate unmanned systems certification with FAA-aligned standards for beyond-visual-line-of-sight operations. Arctic testing corridors in Nunavut and the Northwest Territories validate maritime domain awareness missions for rotary-wing platforms operating from ice-strengthened vessels.
Mexico
Federal security agencies and naval forces procure tactical UAVs for cartel surveillance and maritime interdiction along Pacific and Gulf coasts. The Secretariat of National Defense operates under US-influenced airworthiness frameworks adapted from FAA and DoD criteria. Baja California and Sonora host cross-border training exercises with US Northern Command, validating interoperability for border security applications.
North America Tactical UAV Market Competitive Landscape
Premium-margin players sit above commodity-margin players across airframe sophistication and software certification burden. The vendor base clusters around three tiers: defense primes with MIL-STD-882 qualification resources, mid-tier specialists in expeditionary form factors, and emerging entrants leveraging open-architecture ground control stations. Strategic moves concentrate on rapid fielding partnerships with SOCOM authorities and backward integration into stabilized electro-optical payload production.
Within the defense prime tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify established positions in stealth-optimized and contested-airspace platforms. AeroVironment Inc. occupies a specialist position in hand-launched fixed-wing systems for infantry units. These three entities represent contrasting archetypes: the integrated prime with battle network interoperability resources, the focused tactical specialist with compressed deployment expertise, and the stealth technology incumbent with penetration mission credentials.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| AeroVironment Inc. |
| Lockheed Martin Corporation |
| General Atomics Aeronautical Systems |
| Textron Inc. |
| The Boeing Company |
| Elbit Systems Ltd. |
| IAI |
| Insitu |
| Others |
Value Network & Pricing Analysis
Reduced-carbon expeditionary mandates from Army Futures Command gate access to premium-tier contracts and qualified supplier pools, compressing margins for platforms that fail fuel-efficiency thresholds while elevating pricing power for certified dual-use architectures.
Pricing Analysis
Value-based pricing anchored to mission uptime and degraded-mode reliability separates premium military-qualified platforms from civil-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects MIL-STD-882 certification burden, with AI-enabled autonomy stacks commanding substantial premiums over remote-controlled baselines. Cost compression in the commercial segment intensifies as FAA Part 107 remote ID compliance costs disproportionately burden small fleet operators. Government end users exhibit lowest price sensitivity due to mission-critical procurement authorities, while commercial infrastructure inspectors face acute margin pressure.
Supply Chain Analysis
Workforce availability constraints in Arizona and New Mexico test corridor manufacturing clusters limit production scaling for qualified airframe integrators. Supply concentrates in the United States for stabilized electro-optical turrets and miniature turbojet engines, with Canadian satellite backhaul subsystem providers and Mexican aerostructure fabricators filling tier-two roles. Single-source vulnerability in domestic miniature turbojet engine supply creates acute production bottleneck risk. Distribution runs through defense prime direct contracting channels and SOCOM rapid fielding authorities, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FAA certification timelines and MIL-STD-882 software compliance burdens force capital-constrained developers toward acquisition or exit.
For Market Incumbents: Anticipate displacement from open-architecture ground control station entrants by securing backward integration into stabilized electro-optical payload production and embedding with Army Futures Command Project Convergence network interoperability requirements. Prioritize rapid fielding partnership locks with US Special Operations Command authorities before qualification cycle compression accelerates. For New Entrants and Emerging Players: AI-enabled edge computing for onboard target recognition offers the most penetrable wedge into reconnaissance applications previously requiring manned airborne early warning platforms. White-space concentration sits in Canadian Arctic cold-weather-hardened systems with satellite backhaul and US Marine Corps ship-to-shore rotary-wing logistics. Pursue dual-certification strategies satisfying both FAA Part 107 and military airworthiness criteria to access defense procurement channels. For Investors and Strategic Acquirers: SOCOM rapid fielding authority utilization spikes are the leading indicator that qualification cycle compression is permanently displacing incumbent-optimized source-selection timelines. Five-to-ten year viability favors mid-tier specialists with expeditionary form factor expertise and captive electro-optical payload capabilities over hardware-agnostic software vendors. Monitor FAA spectrum allocation decisions for protected C-band and L-band command-and-control links as inflection signals for operational range extension plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electro-Optical Payloads | Captive stabilized turret production insulates against single-source engine supplier bottlenecks. |
| Dual-Certification Strategy Development | Simultaneous FAA Part 107 and MIL-STD-882 compliance unlocks defense and civil procurement channels. |
| Rapid Fielding Partnership Formation | SOCOM urgent operational need authorities bypass extended Milestone C review timelines. |
| Hybrid-Electric Propulsion Modularization | Decoupled powertrain architecture enables vendor swapping without airframe recertification. |
| Arctic Hardening and Satellite Backhaul Integration | Royal Canadian Armed Forces northern surveillance gaps validate cold-weather maritime domain platforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with UAV program managers at Army Futures Command, procurement officers at US Special Operations Command, FAA certification specialists, and electro-optical subsystem engineering directors. Bottom-up platform shipment tallies by configuration and end user triangulated against top-down defense budget appropriation analysis and Canadian procurement disclosure tracking.
Granularity-level modeling disaggregated fixed-wing, rotary-wing, hybrid, and nano configurations across military, government, law enforcement, and commercial end users, with technology stacks segmented by autonomy architecture and application profiles spanning reconnaissance through payload delivery. CAGRs derived from regression-adjusted procurement cycle analysis and expeditionary force restructuring timelines, incorporating hybrid-electric propulsion adoption curves and AI-enabled target recognition deployment schedules.
Several conditions sit outside the modeled scope, including classified special access program expenditures, emergency supplemental appropriations for contingency operations, and rapid regulatory shifts in FAA beyond-visual-line-of-sight enforcement. Forecasts reflect assumptions regarding sustained southwestern test corridor concentration and stable spectrum allocation coordination between FCC and NTIA. Material deviation in SOCOM rapid fielding authority utilization or FAA remote ID compliance timeline acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Europe Drones Market
UAV
Global VTOL UAV Market
UAV
Small Drone Market
UAV
Rotary Blade UAV Drones Market
UAV
Latin America Small UAV Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Drones Market
UAV
Global Drone Light Shows Market
UAV
Fuel Cell UAV Market
UAV
Global Drone Software Market
UAV
Fixed Wing Military Drones Market
UAV
UAV Simulator Market
UAV
Ultra Micro Drone Market
UAV
Europe Commercial Drones Market
UAV
Global Multirotor UAV Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market