
 North America Small Arms Market | 2026-2036
North America Small Arms Market Size, Share, and Industry Trends Forecast 2026-2036
North America Small Arms Market Analytics
Civilian distribution through federally licensed dealers is fragmenting as direct-to-consumer online platforms and manufacturer-owned retail concepts gain regulatory traction. Smith & Wesson Brands, Inc. leverages its Massachusetts manufacturing heritage to sustain brand loyalty among legacy buyers. Sturm, Ruger & Co., Inc. anchors the hunting and ranching segments with its rimfire and single-action revolver lines. SIG SAUER, Inc. dominates modular pistol contracts with U.S. defense and law enforcement agencies through its P320 platform.
Small arms encompass portable, shoulder-fired or handheld firearms typically operating at calibers from .17 HMR through .50 BMG, with rifled or smoothbore barrels manufactured through hammer forging, button rifling, or cold-hammer forging processes designed for precision, reliability, and controlled terminal ballistics. Handguns command the largest revenue pool among product types due to concealed-carry demand and compact platform proliferation, while rifles capture premium pricing through precision chassis systems and AR-pattern modularity. Among end users, law enforcement agencies are standardizing on optics-ready, striker-fired pistols, whereas civilian users drive volume through sport shooting and personal defense applications.
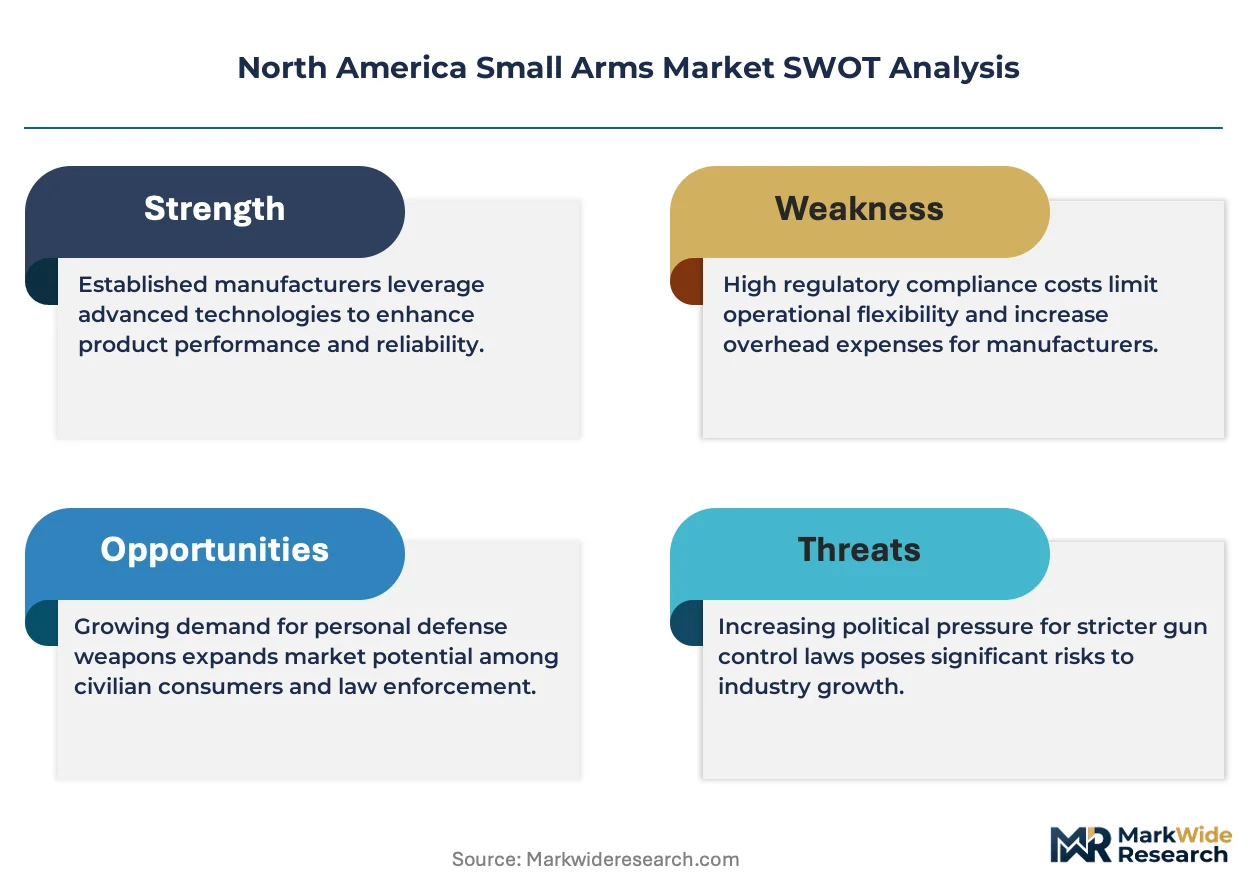
The Bureau of Alcohol, Tobacco, Firearms and Explosives oversees interstate commerce and National Firearms Act enforcement, while state-level constitutional-carry legislation in Texas, Florida, and Ohio reshapes permit demand and training-service economics. The U.S. State Department's International Traffic in Arms Regulations constrains export licensing for controlled defense articles, limiting foreign revenue streams for domestic manufacturers. Stakeholders must monitor pending Supreme Court Second Amendment jurisprudence and state-level magazine-capacity restrictions that could abruptly reconfigure product portfolios and inventory strategies.
Market Dynamics
Constitutional-carry legislation across U.S. states is compressing permit timelines and expanding addressable demand for compact handguns, while polymer-frame manufacturing is displacing traditional steel fabrication in production economics.
Growth Catalysts
- Constitutional-carry expansion:Texas, Florida, and Ohio have enacted permitless carry frameworks, eliminating training-service bottlenecks and accelerating first-time buyer conversion rates in civilian channels.
- Modular pistol platforms:Interchangeable fire-control units and serialized chassis systems allow law enforcement agencies to standardize armorer protocols while reducing fleet-wide lifecycle costs.
- Polymer-frame injection molding:Advanced glass-filled nylon formulations cut per-unit raw material costs by half versus forged aluminum receivers, enabling margin expansion at entry price points.
Market Restraints
- Chromium supply concentration:Domestic barrel manufacturers depend on Turkish and South African ferrochrome for hammer-forging dies, exposing cost structures to ore export restrictions.
- ATF Form 4473 compliance friction:The Bureau of Alcohol, Tobacco, Firearms and Explosives maintains paper-based NICS check documentation requirements that slow retail throughput during demand surges.
- Optics-ready slide machining:Precision milling of MOS-pattern mounting interfaces requires five-axis CNC capacity that concentrates among a handful of domestic job shops.
Strategic Opportunities
- Direct-to-consumer FFL fulfillment:Manufacturer-owned e-commerce platforms with captive federal firearms licensees bypass distributor markups and capture end-customer data for accessory attach.
- Suppressor deregulation momentum:Pending Hearing Protection Act provisions would reclassify silencers from NFA Title II to standard firearms, opening a $1 billion-plus civilian accessory market.
- Red-dot sight integration:Law enforcement and concealed-carry segments are converging on slide-mounted optics as standard equipment, forcing holster and training ecosystem adaptation.
Industry Challenges
- Master armorer certification scarcity:Modular platforms require specialized training on serialized fire-control units, and manufacturer-specific armorers' courses face 12-month backlogs.
- State magazine-capacity patchwork:California, New York, and Illinois enforce 10-round limits while neighboring states permit standard-capacity magazines, complicating national SKU rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Small Arms Market |
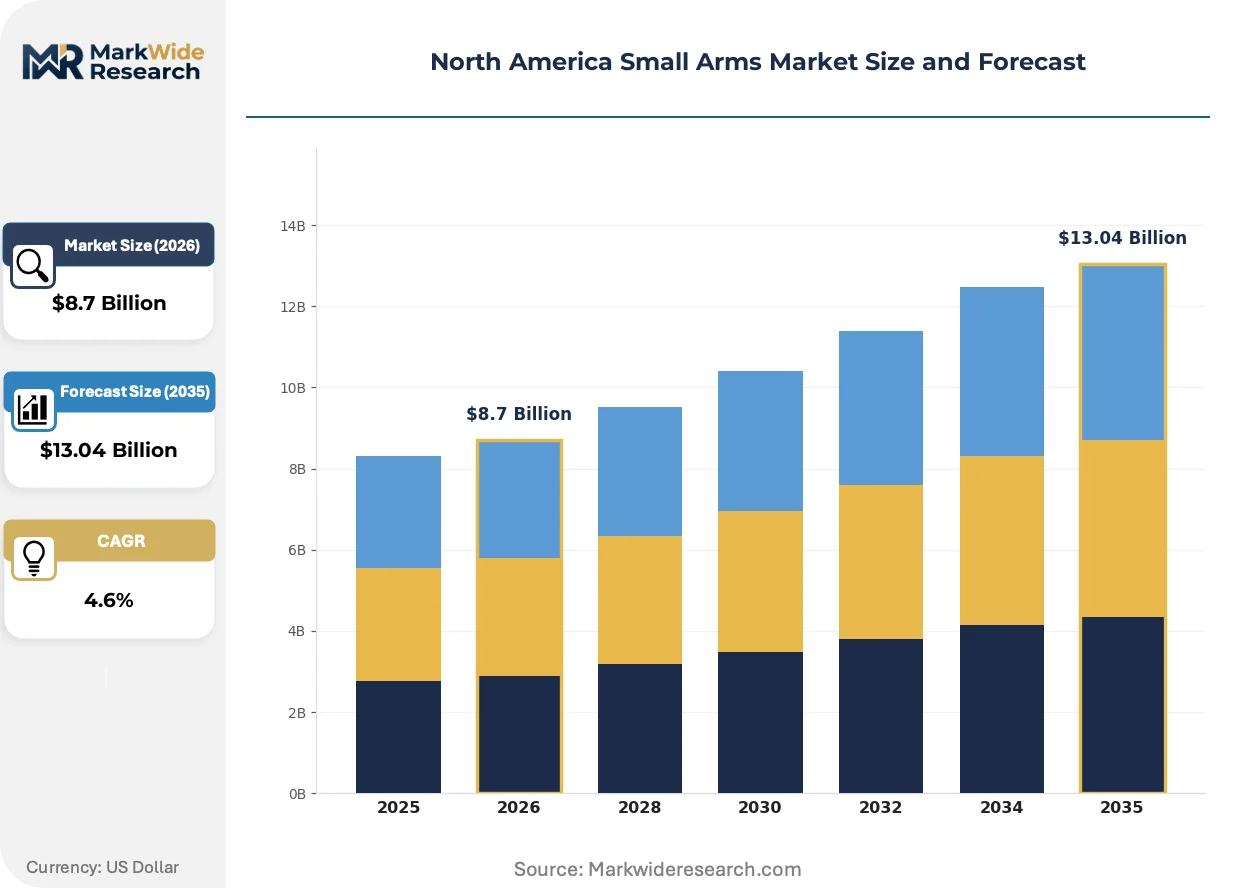
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rifles, Handguns, Shotguns, Machine Guns End User: Defense Forces, Law Enforcement, Civilian Users, Private Security Usage Type: Sport Shooting, Self-Defense, Hunting, Military Training Distribution Channel: Online Retail, Specialty Stores, Gun Shows, Direct Sales |
| Companies Covered | Smith & Wesson Brands, Inc., Sturm, Ruger & Co., Inc., SIG SAUER, Inc., GLOCK Ges.m.b.H., FN Herstal, Colt's Manufacturing Company LLC, Heckler & Koch GmbH, Beretta USA Corp., Remington Outdoor Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Small Arms Market Evolving Landscape
Product development cycles are compressing as striker-fired architectures and optics-ready slide cuts become baseline expectations rather than premium upgrades, forcing legacy manufacturers to retool or cede share.
Striker-fired ignition systems are migrating from law enforcement contract specifications into civilian concealed-carry preferences, eliminating external hammer snag risks and enabling consistent trigger pulls across production lots. First-time buyers in constitutional-carry states now expect duty-grade reliability at consumer price points, collapsing the traditional tiering between patrol-issue and commercial handguns.
The Bureau of Alcohol, Tobacco, Firearms and Explosives is scrutinizing forced-reset trigger designs under National Firearms Act definitions, creating regulatory uncertainty for aftermarket manufacturers. Binary and forced-reset trigger suppliers face potential reclassification as machine-gun components, which would freeze innovation investment and force inventory liquidation across distributor networks.
Online FFL-transfer platforms are capturing an expanding share of first-time firearm purchases, displacing traditional brick-and-mortar counter relationships. Buyers in Texas and Arizona increasingly complete transactions through manufacturer-direct portals with local pickup, eroding the independent dealer's role in customer education and upselling accessory attach.
North America Small Arms Market Segmentation
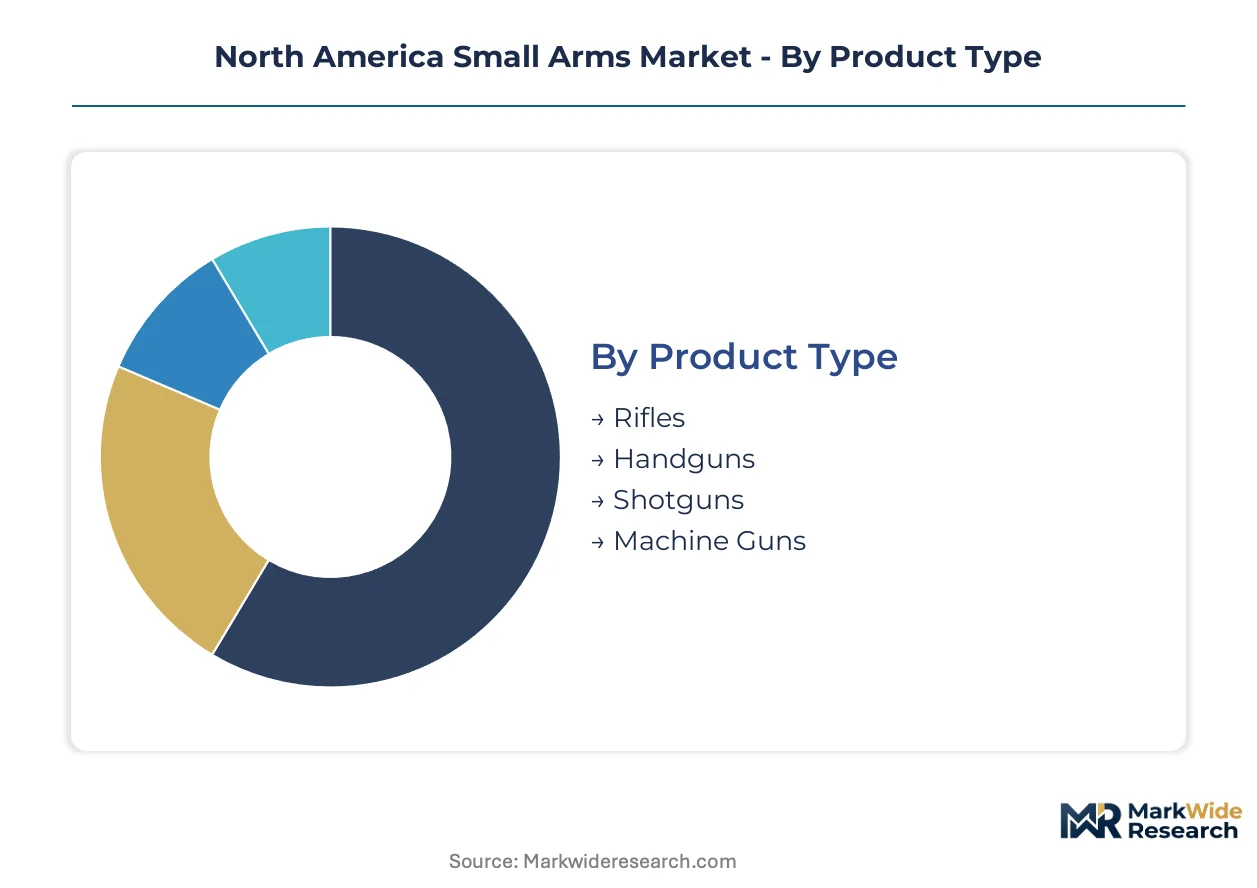
North American small arms procurement patterns diverge sharply across user categories, with civilian channels demanding concealability while defense and law enforcement prioritize modularity and fleet standardization. Product specifications, distribution pathways, and usage contexts create distinct margin profiles that manufacturers must navigate through differentiated SKU strategies.
Product Type:
Mature rifle and handgun platforms anchor revenue stability, while emerging shotgun configurations and precision-manufactured machine guns for specialized units represent technology frontier investments.
- Rifles:Precision chassis systems and AR-pattern modularity command premium pricing through cold-hammer-forged barrels and free-float handguard architectures. Texas and Arizona ranching communities sustain bolt-action centerfire demand for varmint control, while law enforcement agencies standardize on patrol carbine configurations with optics-ready receivers.
- Handguns:Polymer-frame striker-fired pistols dominate concealed-carry permit holders across constitutional-carry states, with serialized fire-control units enabling modular frame swaps. Compact double-stack 9mm variants generate the highest unit volumes through federally licensed dealer channels in the American Southwest.
- Shotguns:Pump-action and semi-automatic 12-gauge platforms serve home defense and waterfowl hunting segments with interchangeable choke systems.
- Machine Guns:Belt-fed automatic weapons chambered in 5.56 NATO and 7.62 NATO remain restricted to defense contracts and law enforcement special weapons units under National Firearms Act oversight.
Handguns retain volume leadership; rifles hold the steepest expansion curve through precision shooting sports adoption.
End User:
Cost tier stratification separates duty-grade procurement from consumer-grade purchasing, with defense contracts absorbing development costs that later cascade into commercial variants.
- Defense Forces:Modular pistol contracts with interchangeable fire-control units reduce armorer training overhead across joint-service small arms programs. The U.S. Army's Next Generation Squad Weapon program is driving 6.8mm caliber adoption that will reshape domestic ammunition manufacturing capacity.
- Law Enforcement:Optics-ready striker-fired pistols with standardized holster compatibility dominate agency fleet purchases, with SIG SAUER's P320 platform capturing multi-state contract awards through serialized chassis architecture.
- Civilian Users:Concealed-carry permit liberalization across Texas, Florida, and Ohio accelerates first-time buyer conversion through compact handgun demand and online FFL-transfer platforms.
- Private Security:Armed security contractors operating critical infrastructure protection require duty-grade reliability at commercial procurement timelines, bridging law enforcement specifications with civilian purchasing flexibility.
Law enforcement retains volume leadership; civilian users are gaining share fastest through constitutional-carry legislative momentum.
Usage Type:
Application context determines feature prioritization, with competitive shooting disciplines driving aftermarket customization while defensive use emphasizes reliability under stress.
- Sport Shooting:Three-gun competition and precision rifle series events drive demand for tuned triggers, compensator-compatible barrels, and extended magazine capacities that exceed standard duty specifications.
- Self-Defense:Concealed-carry practitioners in Arizona and Texas prioritize compact double-stack 9mm handguns with red-dot sight integration and appendix-carry holster compatibility.
- Hunting:Rimfire and centerfire rifle platforms serve varmint, big-game, and waterfowl harvest requirements across state-specific caliber restrictions and magazine-capacity regulations.
- Military Training:Simunition-converted service rifles and dedicated training handguns reduce ammunition costs for qualification cycles while maintaining manual-of-arms consistency with duty weapons.
Hunting retains volume leadership; sport shooting holds the steepest expansion curve through competitive participation growth.
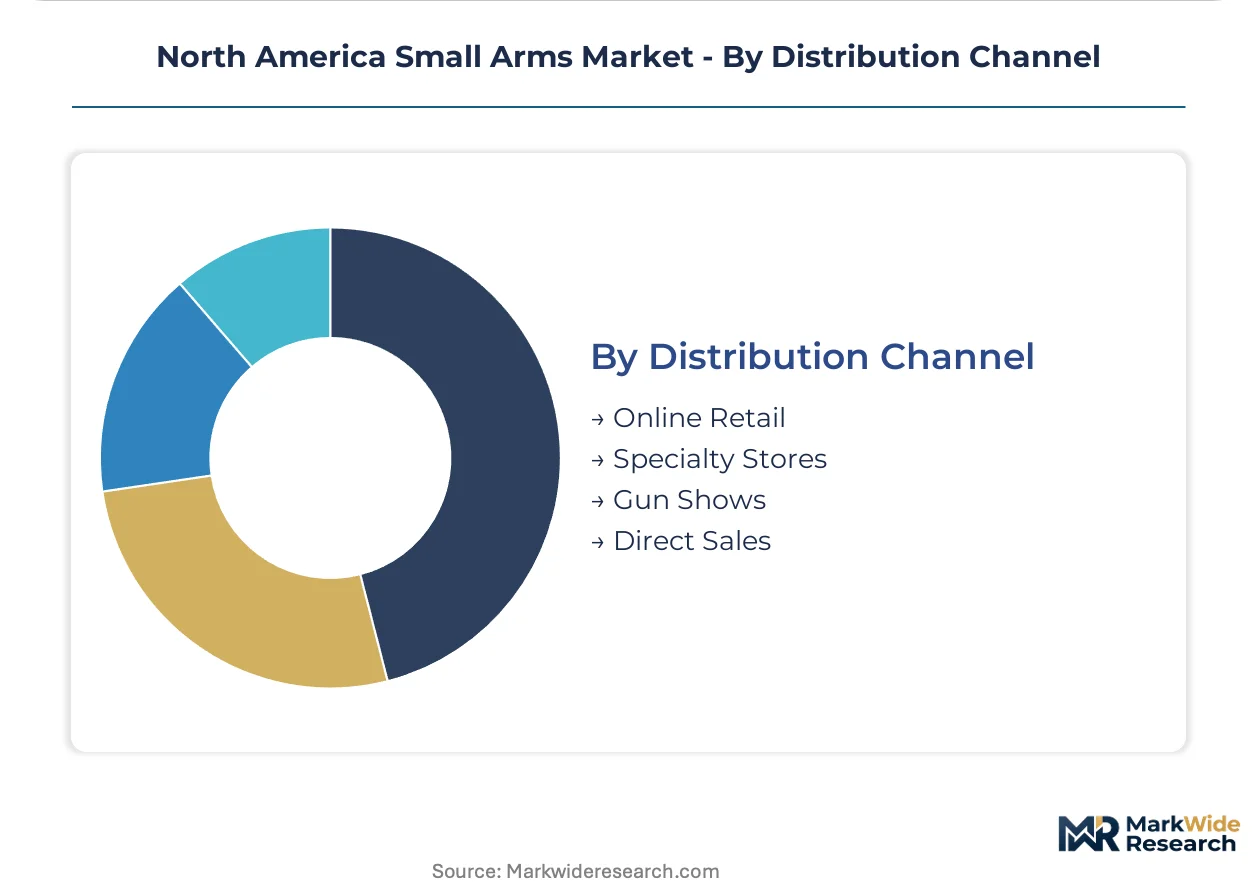
Distribution Channel:
Customer type fragmentation separates relationship-driven purchasing from transaction-driven procurement, with manufacturer-direct platforms capturing data assets that traditional channels cannot replicate.
- Online Retail:Manufacturer-owned e-commerce platforms with captive federal firearms licensees bypass distributor markups and capture end-customer contact data for accessory attach campaigns.
- Specialty Stores:Independent federally licensed dealers sustain hands-on customer education and immediate-transfer convenience that online channels cannot replicate for first-time buyers.
- Gun Shows:Temporary retail events concentrate inventory liquidity for private-party transfers and collectible firearms transactions outside standard dealer networks.
- Direct Sales:Law enforcement and defense contracts route through manufacturer direct-sales teams with dedicated armorer support and fleet-management software integration.
Specialty stores retain volume leadership; online retail holds the steepest expansion curve through digital-native buyer demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bureau of Alcohol, Tobacco, Firearms and Explosives anchors regulatory oversight across the dominant United States market, while Canadian firearms regulation through the Royal Canadian Mounted Police and Mexican defense procurement via the Secretariat of National Defense shape distinct national demand profiles across the continent.
United States
Texas and Arizona sustain the highest per-capita firearm sales volumes through concealed-carry permit liberalization and ranching-community demand. Constitutional-carry legislation in Florida and Ohio eliminates training-service bottlenecks and accelerates first-time buyer conversion rates. The American Southwest concentrates manufacturing capacity in polymer-frame injection molding facilities serving civilian and law enforcement channels.
Canada
Hunting and sport shooting communities in Alberta and British Columbia drive rimfire rifle and shotgun procurement through provincial wildlife management programs. The Royal Canadian Mounted Police administers the Possession and Acquisition Licence framework, creating compliance friction that slows retail throughput relative to U.S. channels. Ontario-based distributors serve as the primary import gateway for European and U.S. manufacturers seeking Canadian market access.
Mexico
The Secretariat of National Defense maintains monopoly control over civilian firearm sales through its Directorate of Commercialization of Arms and Munitions, restricting legal commercial channels to a single Mexico City retail outlet. Northern border states experience spillover demand pressure from U.S. constitutional-carry momentum, though legal procurement remains constrained. Military and law enforcement contracts dominate manufacturer engagement through direct government procurement protocols.
North America Small Arms Market Competitive Landscape
Heritage manufacturers and modular-platform specialists split the market between legacy brand loyalty and technical innovation vectors. Market structure concentrates around three tiers: established U.S. brands with century-plus histories, European imports with defense-contract pedigrees, and polymer-frame innovators capturing civilian concealed-carry growth. Dominant competitive moves include direct-to-consumer e-commerce platform development and serialized fire-control unit architecture standardization.
Within the heritage-manufacturer tier, Smith & Wesson Brands, Inc. and Sturm, Ruger & Co., Inc. exemplify Massachusetts and Connecticut manufacturing legacies that sustain brand equity among legacy buyers. SIG SAUER, Inc. occupies a position bridging European engineering heritage with U.S. defense-contract execution, representing the modular-platform archetype through its serialized chassis systems. These three entities anchor distinct strategic positions without overlapping core buyer relationships.
| Leading Market Players |
|---|
| Smith & Wesson Brands, Inc. |
| Sturm, Ruger & Co., Inc. |
| SIG SAUER, Inc. |
| GLOCK Ges.m.b.H. |
| FN Herstal |
| Colt's Manufacturing Company LLC |
| Heckler & Koch GmbH |
| Beretta USA Corp. |
| Remington Outdoor Company |
| Others |
Value Network & Pricing Analysis
Turkish and South African ferrochrome suppliers anchor barrel-forging die economics, concentrating margin capture upstream while U.S. manufacturers absorb volatility through long-term offtake contracts or premium pricing to civilian buyers.
Pricing Analysis
Texas and Arizona sustain price spreads of fifteen to twenty percent below national averages due to volume concentration and dealer competition, while northeastern states absorb compliance-cost premiums. Three-tier pricing structure across premium precision rifles, standard duty-grade handguns, and economy rimfire platforms separates law enforcement contract tiers from consumer-grade offerings. Pricing pressure stems from polymer-frame injection molding commoditization at entry price points. First-time civilian buyers in constitutional-carry states exhibit highest price sensitivity, whereas defense contract officers prioritize lifecycle cost over unit acquisition.
Supply Chain Analysis
ITAR export controls constrain technology transfer for hammer-forging equipment and serialized fire-control unit architectures, limiting domestic manufacturers' sourcing options for precision machining capacity. Raw material flows draw from Turkish ferrochrome, Austrian tool steel, and domestic glass-filled nylon resin suppliers. Single-source vulnerability concentrates in five-axis CNC job shops capable of optics-ready slide milling. Distribution runs through federally licensed dealer networks with manufacturer-direct e-commerce platforms capturing growing share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular pistol platforms are reconfiguring the market around serialized fire-control unit ecosystems, where interoperability between frames, slides, and holster systems determines customer lock-in and aftermarket attach rates.
For Market Incumbents: Build serialized chassis architecture moats by expanding armorer certification networks and enforcing holster-system compatibility standards. Deepen backward integration into polymer-frame injection molding to offset raw material volatility. Acquire distressed five-axis CNC capacity before optics-ready machining bottlenecks worsen.
For New Entrants and Emerging Players: Establish a beachhead in suppressor-ready rimfire platforms ahead of potential Hearing Protection Act deregulation. Target private security contractors bridging law enforcement specifications with commercial procurement flexibility. Launch direct-to-consumer FFL-fulfillment platforms with integrated training-content subscriptions.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers with dormant defense-contract credentials and idle cold-hammer-forging capacity. Watch state-level magazine-capacity litigation as the signal for inventory reconfiguration cycles and SKU rationalization pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialized Fire-Control Unit Standardization | Enables law enforcement fleet interoperability while reducing armorer training overhead across multi-state contracts. |
| Direct-to-Consumer FFL Platform Launch | Bypasses distributor markups and captures end-customer data for accessory attach campaigns in constitutional-carry states. |
| Optics-Ready Slide Machining Capacity Expansion | Addresses five-axis CNC bottlenecks as red-dot sight integration becomes baseline expectation across segments. |
| Suppressor Product Line Development | Positions for potential NFA reclassification while serving current law enforcement special weapons unit demand. |
| Polymer-Frame Injection Molding Backward Integration | Offsets ferrochrome cost volatility and enables margin expansion at entry price points. |
Research Methodology
The analysis maps civilian concealed-carry, law enforcement fleet procurement, and defense contract segments, each validated through interviews with federally licensed dealers, manufacturer product managers, state-level training coordinators, and armorer certification instructors. Secondary sources include ATF manufacturing and export licensing data, state legislative tracking databases, and customs import records for ferrochrome and tool steel. Bottom-up unit demand estimates triangulate against top-down manufacturer revenue disclosures.
Assumptions held constitutional-carry legislative momentum and ITAR enforcement intensity constant while varying polymer raw material cost trajectories and optics adoption curves across the projection horizon. Segmentation dimensions span product type, end user, usage context, and distribution channel with regional regulatory cluster overlays. CAGRs derive from installed base replacement cycles and first-time buyer conversion elasticity. Forecast inputs incorporate NICS background check trend data and state-level permit issuance rates.
Sensitivities concentrate around Supreme Court Second Amendment jurisprudence and pending ATF forced-reset trigger determinations. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in export control enforcement or state-level magazine-capacity restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Less Lethal Ammunition Market