
 Military Airborne Laser Market | 2026-2036
Military Airborne Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Military Airborne Laser Market Foresight
Software-defined beam control and predictive maintenance packages are pivoting how prime contractors monetize airborne laser platforms. Lockheed Martin leverages captive integration of solid-state laser subsystems to sustain program margins on next-generation fighter applications. Northrop Grumman anchors its position through dominance in high-energy laser testbeds operated from modified transport aircraft. Raytheon Technologies differentiates via specialized fire-control software that bridges kinetic and directed-energy intercept architectures.
Military airborne lasers are high-power coherent light systems engineered for precision engagement from aerial platforms, typically operating at multi-kilowatt to megawatt-class outputs with beam quality metrics below diffraction-limited divergence. Solid-state laser architectures now lead platform integration due to improved electrical efficiency and reduced logistics burden versus legacy chemical oxygen-iodine systems. Fiber laser segments represent the fastest-growing technology category as gallium nitride pump diode reliability improves and thermal management packaging shrinks. Fixed-wing aircraft remain the dominant platform type for high-power applications, though rotary-wing and drone-mounted systems attract growing development investment for tactical precision strike missions.
The US Department of Defense directs procurement through the Missile Defense Agency and Air Force Research Laboratory, while NATO standardization agreements shape interoperability requirements for allied platform integration. FAA coordination governs domestic test airspace allocation, constraining development tempo for full-scale airborne demonstrations. Stakeholders must weigh congressional appropriation cycles against prototype-to-production transition timelines as program funding shifts from research to procurement line items.
Market Dynamics
The transition from chemical oxygen-iodine to solid-state laser architectures is compressing platform weight and thermal management requirements, forcing prime contractors to restructure subsystem supplier relationships and captive manufacturing footprints.
Growth Catalysts
- US Department of Defense Directed-Energy Roadmap:Congressional funding mandates accelerate program approvals from research to procurement line items, creating predictable multi-year budget visibility for platform integrators.
- Fiber laser pump diode reliability:Gallium nitride semiconductor advances reduce thermal management packaging volume, enabling megawatt-class outputs on tactical aircraft with existing electrical generation capacity.
- NATO standardization agreements:Allied interoperability requirements for aerial defense platforms create pooled procurement pools beyond bilateral US contracts.
Market Restraints
- Germanium substrate supply concentration:High-purity optical substrate production concentrates in East Asian foundries, creating single-source vulnerability for beam director optics.
- FAA airspace coordination:Domestic test allocation constraints limit full-scale airborne demonstration tempo regardless of technical readiness.
- Legacy kinetic interceptors:Existing Patriot and THAAD batteries continue receiving sustainment funding, competing for procurement dollars against unproven directed-energy alternatives.
Strategic Opportunities
- Japan's defense buildup:Tokyo's revised National Security Strategy creates first-mover advantage for platforms compatible with F-35 integration timelines.
- Drone-mounted tactical precision:Rotary-wing and unmanned platforms represent underexploited application space for sub-megawatt strike missions against soft targets.
- Software-defined beam control:Predictive maintenance and fire-control software packages enable recurring revenue streams beyond hardware delivery.
Industry Challenges
- Directed-energy systems engineering talent:The specialized intersection of high-power optics, thermal physics, and aerospace integration faces acute workforce scarcity.
- Prototype-to-production transition:Congressional appropriation cycles misalign with multi-year development timelines, forcing program managers to bridge funding gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Airborne Laser Market |
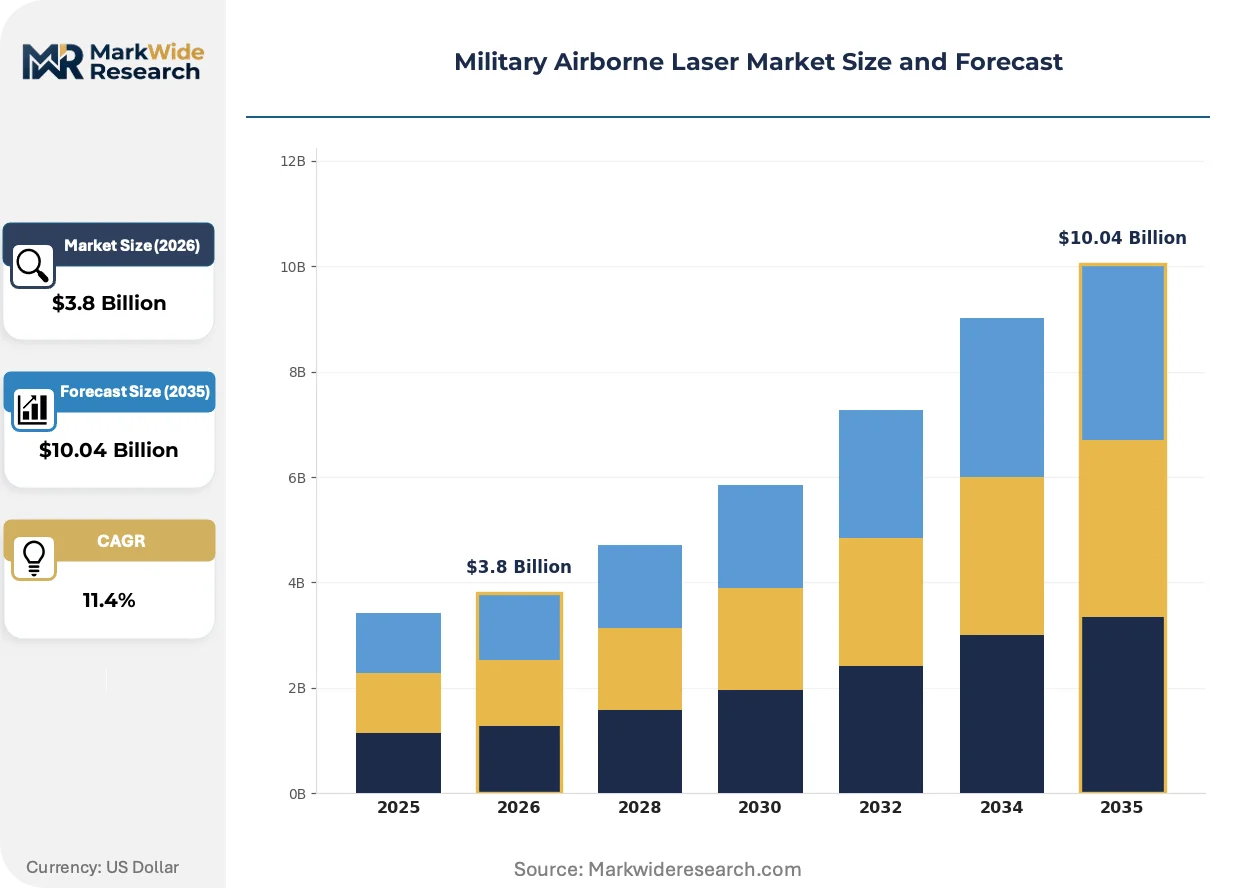
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solid-State Lasers, Fiber Lasers, Chemical Lasers, Free-Electron Lasers Application: Targeting Systems, Aerial Defense, Missile Defense, Surveillance Systems Platform Type: Fixed-Wing Aircraft, Rotary-Wing Aircraft, Drones, Satellites End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions |
| Companies Covered | Lockheed Martin, Northrop Grumman, Raytheon Technologies, Boeing, L3Harris Technologies, Thales Group, BAE Systems, Leonardo, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Airborne Laser Market Shifts & Advancements
Solid-state architectures are compressing platform integration timelines while regulatory frameworks struggle to keep pace with demonstration schedules. Three developments dominate competitive positioning.
Fiber laser technology is consolidating platform preferences across multi-kilowatt to megawatt applications. The Missile Defense Agency and Air Force Research Laboratory prioritize electrically pumped architectures for reduced logistics burden. This shift is consolidating subsystem supplier bases as chemical laser expertise atrophies and solid-state specialists capture program share.
EU Green Deal implementation timelines are pressuring allied defense procurement to account for lifecycle carbon footprints. REACH compliance requirements for rare-earth element sourcing now extend to military exemptions, affecting ytterbium-doped fiber supply chains. European platform integrators are responding with accelerated supplier auditing and alternative dopant research.
Defense procurement offices are unbundling hardware acquisition from sustainment and software upgrade commitments. The traditional bundled platform-plus-support model faces displacement by modular contracting that separates laser subsystem procurement from fire-control software licensing. This pattern is most visible in US Air Force Research Laboratory solicitations, where software-defined beam control now constitutes a distinct evaluation criterion.
Military Airborne Laser Market Segmentation
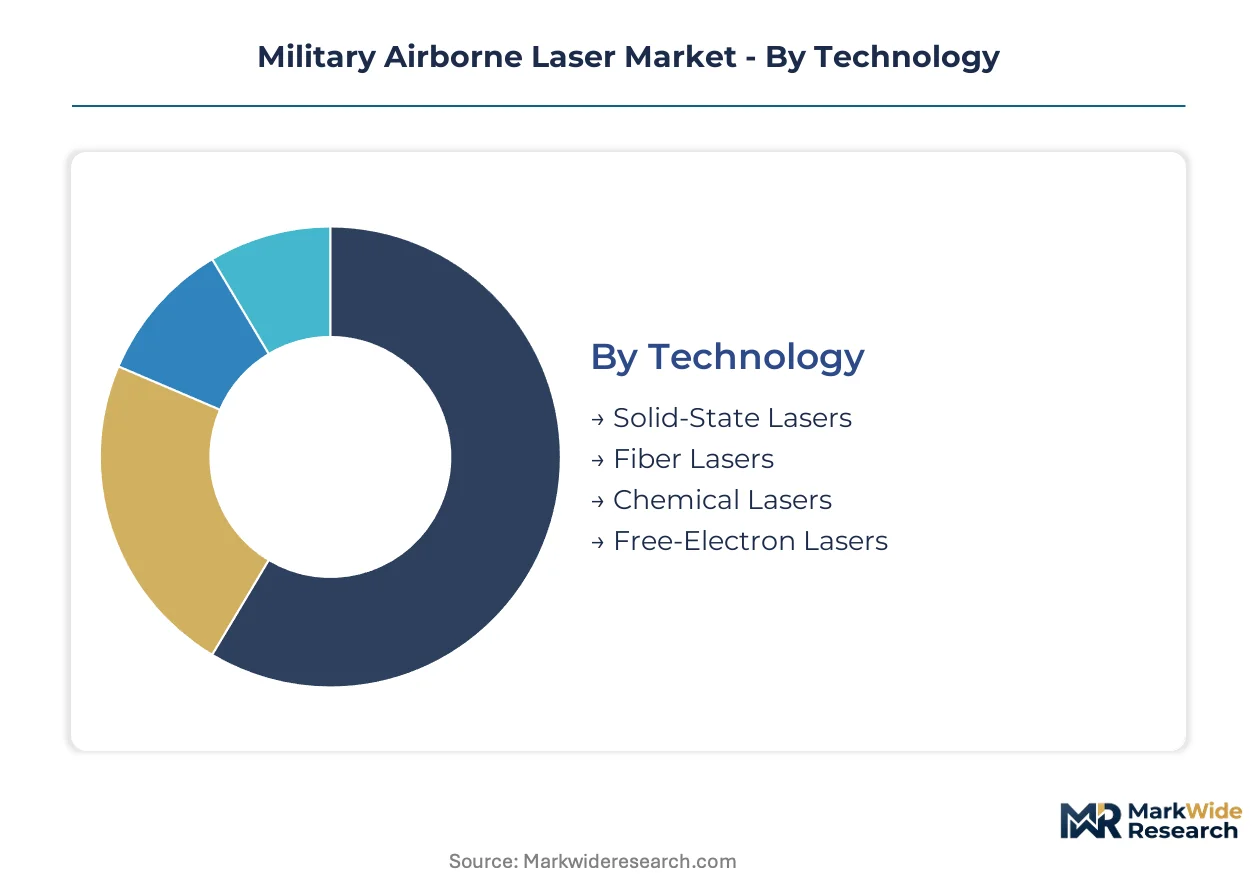
Military airborne laser procurement splits across four critical dimensions that determine integration complexity and contract structure. Technology choice dictates thermal management requirements and platform weight budgets. Application focus shapes fire-control software specifications and interoperability standards. Platform type constrains electrical generation capacity and beam director aperture limits. End-user category determines funding source and certification timeline.
Technology:
Integration depth varies sharply: fiber and solid-state architectures embed directly into tactical airframes, while chemical and free-electron systems require dedicated transport platforms with discrete power subsystems.
- Solid-State Lasers:Diode-pumped slab and disk architectures deliver megawatt-class outputs from electrically efficient packages. The Missile Defense Agency prioritizes these systems for modified Boeing 747-400F testbeds due to reduced logistics burden versus chemical alternatives. Thermal management remains the binding constraint for tactical aircraft integration.
- Fiber Lasers:Ytterbium-doped fiber bundles achieve exceptional beam quality through coherent beam combining. Japan's defense buildup concentrates procurement here for F-35 compatibility timelines. Gallium nitride pump diode reliability improvements are compressing mean-time-between-failure metrics below 10,000 hours.
- Chemical Lasers:Legacy chemical oxygen-iodine systems require hazardous fuel storage and extensive ground support equipment. Demand concentrates in remaining Airborne Laser Testbed sustainment contracts.
- Free-Electron Lasers:Electron accelerator architectures offer tunable wavelengths but demand massive infrastructure. Naval Research Laboratory programs represent the primary development pathway.
Solid-state configurations lead volumes today; fiber lasers are gaining share fastest.
Application:
Cost tiering separates precision strike missions from area defense architectures, with software licensing models diverging accordingly.
- Targeting Systems:Low-power designators and rangefinders integrate across rotary-wing and drone platforms for terminal guidance. Germany's test deployments prioritize these for Eurofighter Typhoon upgrade blocks.
- Aerial Defense:Counter-UAS and cruise missile intercept missions drive kilowatt-class fiber laser procurement. The US Air Force Research Laboratory structures contracts around software-defined beam control for rapid threat library updates.
- Missile Defense:Boost-phase intercept requirements demand megawatt-class outputs from high-altitude platforms. Congressional funding mandates sustain this segment despite prototype-to-production transition delays.
- Surveillance Systems:Ladar and active sensing packages support intelligence collection without weapons-release authority. Research institutions dominate this procurement category.
Missile defense commands the highest unit values; aerial defense shows the steepest expansion trajectory.
Platform Type:
Volume concentration sits with fixed-wing programs, though rotary-wing and unmanned platforms are capturing development investment share.
- Fixed-Wing Aircraft:Modified transport and bomber airframes accommodate heavy beam directors and power generation subsystems. The Missile Defense Agency's Airborne Laser program established the integration template.
- Rotary-Wing Aircraft:Attack helicopter applications face severe weight constraints, limiting outputs to sub-100 kilowatt systems for soft-target precision strike.
- Drones:Unmanned platforms enable persistent stare and reduced personnel risk profiles. Japan's revised National Security Strategy accelerates procurement here for contested airspace operations.
- Satellites:Space-based intercept architectures remain developmental, constrained by launch mass limits and thermal rejection challenges in vacuum environments.
Fixed-wing platforms dominate current inventories; drones are climbing the fastest.
End User:
Customer type determines contract structure, with military forces demanding bundled sustainment and research institutions accepting modular hardware-only procurement.
- Military Forces:Operational commands prioritize fielded capability over experimental performance metrics. NATO standardization agreements shape interoperability requirements across allied platform integration.
- Defense Contractors:Prime integrators acquire subsystems for captive testbed operations and supplier qualification. Lockheed Martin and Northrop Grumman maintain internal directed-energy research fleets.
- Government Agencies:The Air Force Research Laboratory and Missile Defense Agency fund technology maturation through milestone-based contracts with clear transition criteria.
- Research Institutions:Universities and national laboratories access lower-tier procurement vehicles for fundamental physics and materials science investigations.
Military forces account for the largest committed budgets; defense contractors show the most rapid procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany scales test deployments faster than Japan, though both trail the United States in committed procurement volumes. Congressional funding mandates in Washington create multi-year budget visibility that European and Asian defense ministries struggle to replicate.
United States
The Missile Defense Agency and Air Force Research Laboratory direct procurement through milestone-based contracts with clear transition criteria. FAA coordination governs domestic test airspace allocation, constraining full-scale airborne demonstration tempo. Directed-energy engineering clusters concentrate around Albuquerque, New Mexico, where the Air Force Research Laboratory's Directed Energy Directorate operates high-energy laser testbeds.
Germany
Eurofighter Typhoon upgrade blocks prioritize low-power targeting systems for terminal guidance applications. NATO standardization agreements shape interoperability requirements for allied platform integration. Defense technology development clusters in Bavaria, where Airbus Defence and Space maintains directed-energy research facilities alongside university partnerships.
Japan
Tokyo's revised National Security Strategy creates first-mover advantage for platforms compatible with F-35 integration timelines. METI coordinates defense-industrial policy with procurement timelines for unmanned persistent stare capabilities. Concentrated development activity sits in the Nagoya aerospace corridor, where Mitsubishi Heavy Industries advances fiber laser integration for rotary-wing applications.
United Kingdom
BAE Systems anchors national capability through participation in NATO pooled procurement frameworks for aerial defense. Ministry of Defence procurement offices structure contracts around modular hardware-plus-software separation. Directed-energy research concentrates in the Bristol-Southwest England cluster, where the Defence Science and Technology Laboratory operates laser effects testing facilities.
Israel
Rafael Advanced Defense Systems and Elbit Systems drive indigenous development for contested airspace operations against cruise missile threats. National procurement prioritizes rapid fielding over multi-year platform integration cycles. Development activity concentrates in the Haifa metropolitan area, where defense electronics and electro-optics engineering talent pools overlap.
Military Airborne Laser Market Competitive Landscape
Top-tier vendors anchor platform integration, while subsystem specialists capture share in solid-state laser architectures and fire-control software. The vendor base stratifies across three tiers: prime contractors operating captive testbed fleets, mid-tier subsystem suppliers with semiconductor or optics specialization, and research institutions commercializing laboratory innovations. Two archetypes dominate competitive positioning: vertically integrated primes controlling laser subsystem production in-house, and modular integrators licensing beam control software across hardware platforms. Competitive moves concentrate on strategic partnerships for gallium nitride pump diode supply and geographic expansion into Japan's defense buildup.
Among US-based defense primes, Lockheed Martin Corporation, Northrop Grumman Corporation, and Raytheon Technologies Corporation occupy positions spanning the integration spectrum. Lockheed Martin represents the vertically integrated archetype through captive solid-state laser subsystem production. Northrop Grumman exemplifies testbed-centric positioning with modified transport aircraft operations. Raytheon Technologies sits within the software-defined tier, bridging kinetic and directed-energy intercept architectures through specialized fire-control packages.
| Leading Market Players |
|---|
| Lockheed Martin |
| Northrop Grumman |
| Raytheon Technologies |
| Boeing |
| L3Harris Technologies |
| Thales Group |
| BAE Systems |
| Leonardo |
| General Dynamics |
| Others |
Supply & Pricing Matrix
Missile Defense Agency milestone-based procurement concentrates buying power among a handful of prime integrators, locking contract structures around bundled hardware-plus-sustainment packages with limited price transparency for subsystem tiers.
Pricing Analysis
Capacity additions in Japan are reshaping price floors for fiber laser pump diode subsystems as METI-coordinated defense-industrial policy expands domestic gallium nitride foundry output. Contract-based long-term offtake dominates platform integration, with price differentiation hinging on software-defined beam control licensing tiers and thermal management packaging density. Cost compression in solid-state architectures is intensifying because prime contractors captive-source laser subsystems to defend program margins. Research institutions show highest price sensitivity due to modular hardware-only procurement vehicles, while military operational commands accept bundled premiums for fielded capability guarantees.
Supply Chain Analysis
Domestic-content mandates in the US and Japan are reshaping sourcing patterns for high-purity germanium substrates and ytterbium-doped fiber preforms. Supply concentration sits with East Asian foundries for optical substrates, US southwest clusters for directed-energy engineering talent, and Japanese Nagoya corridor for F-35-compatible integration. Raw material dependencies include gallium nitride wafers, rare-earth dopants, and precision beam director optics. Single-source vulnerability in germanium substrate production creates chokepoint exposure. Distribution runs through prime contractor captive testbed fleets and government agency milestone-based contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's defense buildup offers geographic-arbitrage advantage against US procurement cycles, as METI-coordinated timelines compress development-to-fielding intervals versus congressional appropriation gaps.
For Market Incumbents: Deploy software-defined beam control licensing to capture recurring revenue beyond hardware delivery. Lockheed Martin and Northrop Grumman must accelerate captive integration of solid-state laser subsystems before fiber laser pump diode commoditization erodes subsystem margins. Prime contractors should consolidate supplier relationships around gallium nitride semiconductor specialists as chemical laser expertise atrophies. For New Entrants and Emerging Players: Launch via modular fire-control software licensing across hardware platforms rather than competing on megawatt-class platform integration. Drone-mounted tactical precision strike represents the most penetrable white-space, with Japan's unmanned persistent stare procurement creating immediate addressable demand. Target software-defined beam control contracts from Air Force Research Laboratory solicitations where evaluation criteria now separate laser subsystem procurement from fire-control licensing. For Investors and Strategic Acquirers: Prime contractors with directed-energy research fleets are the most active acquirer in this space, seeking solid-state subsystem specialists and gallium nitride pump diode suppliers. Long-term viability hinges on prototype-to-production transition execution across multi-year congressional funding windows. Watch FAA airspace allocation decisions as inflection indicator for full-scale airborne demonstration tempo regardless of technical readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Solid-State Laser Integration | Lockheed Martin sustains margins through in-house diode-pumped slab architecture production for fighter applications. |
| Software-Defined Beam Control Licensing | Raytheon Technologies bridges kinetic and directed-energy intercept architectures through recurring fire-control software revenue. |
| Gallium Nitride Pump Diode Supply Partnership | Northrop Grumman secures semiconductor reliability improvements compressing mean-time-between-failure below operational thresholds. |
| Drone-Mounted Tactical Precision Development | Mitsubishi Heavy Industries captures Japan's unmanned persistent stare procurement for contested airspace operations. |
| NATO Standardization Agreement Alignment | BAE Systems accesses pooled procurement pools beyond bilateral contracts through interoperability certification investment. |
Research Methodology
Direct dialogue with program managers at the Missile Defense Agency, Air Force Research Laboratory procurement officers, prime contractor directed-energy division heads, and FAA airspace coordination staff grounded qualitative assessment of development tempo constraints. Secondary validation drew from congressional appropriation records, DoD directed-energy roadmap publications, NATO standardization agreement texts, and METI defense-industrial policy filings. Bottom-up segment sizing triangulated against top-down procurement budget analysis across the analysis window.
Output matrices modeled technology transitions from chemical to solid-state architectures, application tiering across targeting through missile defense, platform type constraints from fixed-wing through drone-mounted systems, and end-user contract structures from research institutions through military operational commands. CAGRs derived from procurement line-item trajectories and congressional funding mandate visibility. Industry-specific inputs included gallium nitride pump diode reliability curves, thermal management packaging density improvements, and FAA test airspace allocation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under congressional appropriation cycle disruptions or germanium substrate supply interruptions. Forecasts reflect documented assumptions regarding prototype-to-production transition timelines and allied interoperability certification pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
APAC Ballistic Missile Market